
 Narrow-Body Turbofan Engine Shop Visit Services Market | 2026-2036
Narrow-Body Turbofan Engine Shop Visit Services Market Size, Share, and Industry Trends Forecast 2026-2036
Narrow-Body Turbofan Engine Shop Visit Services Market Insights
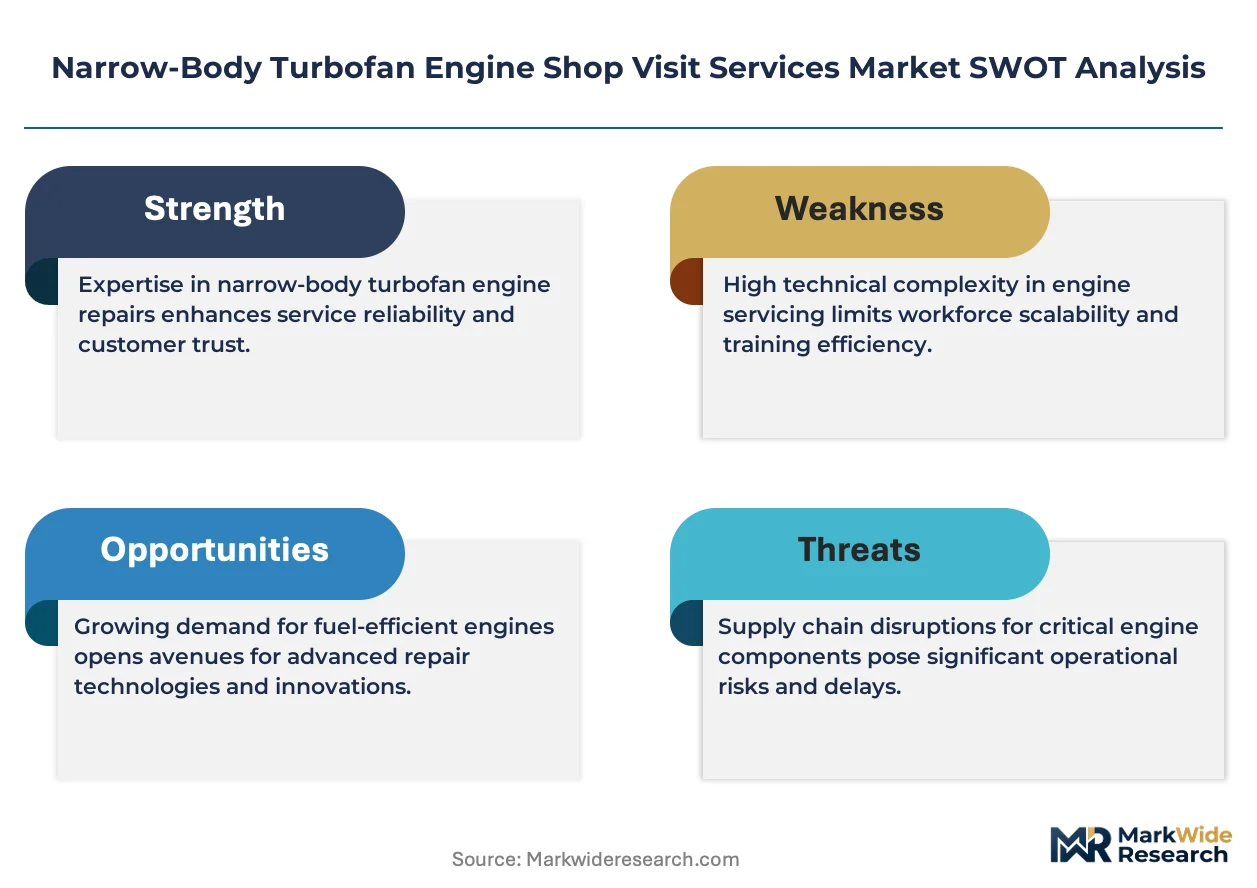
FAA's updated turbine inspection mandates is consolidating the cost-of-entry calculus for narrow-body engine shop visit providers, forcing smaller independents toward specialized niches or exit. GE Aerospace leverages its vertical integration into OEM data analytics to sustain predictive maintenance contracts that lock in recurring shop visit volume. Pratt & Whitney anchors its position through proprietary blade repair technologies that differentiate its service network from third-party alternatives. Lufthansa Technik competes on European regulatory proximity, positioning its Hamburg and Malta facilities as EASA-aligned hubs for CFM LEAP and PW1100G overhauls.
Narrow-body turbofan engine shop visit services encompass the disassembly, inspection, repair, reassembly, and testing of turbofan propulsion systems rated below 50,000 pounds thrust, typically powering single-aisle aircraft with 100-240 passenger capacity; these services restore engine performance to certified output parameters after accumulated flight cycles degrade high-pressure compressor and turbine component tolerances. The primary commercial purpose centers on extending engine operational life between full replacements, optimizing fuel efficiency restoration, and ensuring airworthiness compliance under continuous airworthiness management programs. Routine maintenance and overhaul categories dominate current revenue pools given the established cadence of interval-driven shop visits for mature CFM56 and V2500 fleets, while performance testing and engine wash segments represent faster-growing service lines as operators prioritize fuel burn recovery and emissions footprint reduction between major overhauls. Component repair specialization concentrates margin capture among OEM-affiliated networks that control proprietary coatings and airfoil restoration processes.
FAA airworthiness directives and EASA engine type certificate conditions shape shop visit scope and documentation standards, with both bodies mandating traceable part histories and certified technician qualifications that elevate fixed-cost structures for MRO providers. China's CAAC enforces parallel compliance requirements for COMAC C919 engine support, creating a dual-track regulatory environment where domestic MRO capacity must achieve concurrent Chinese and original OEM certification. Stakeholders must monitor how evolving emissions standards from ICAO's Carbon Offsetting and Reduction Scheme translate into shop visit scope expansion for combustion system modifications and exhaust nozzle efficiency restoration.
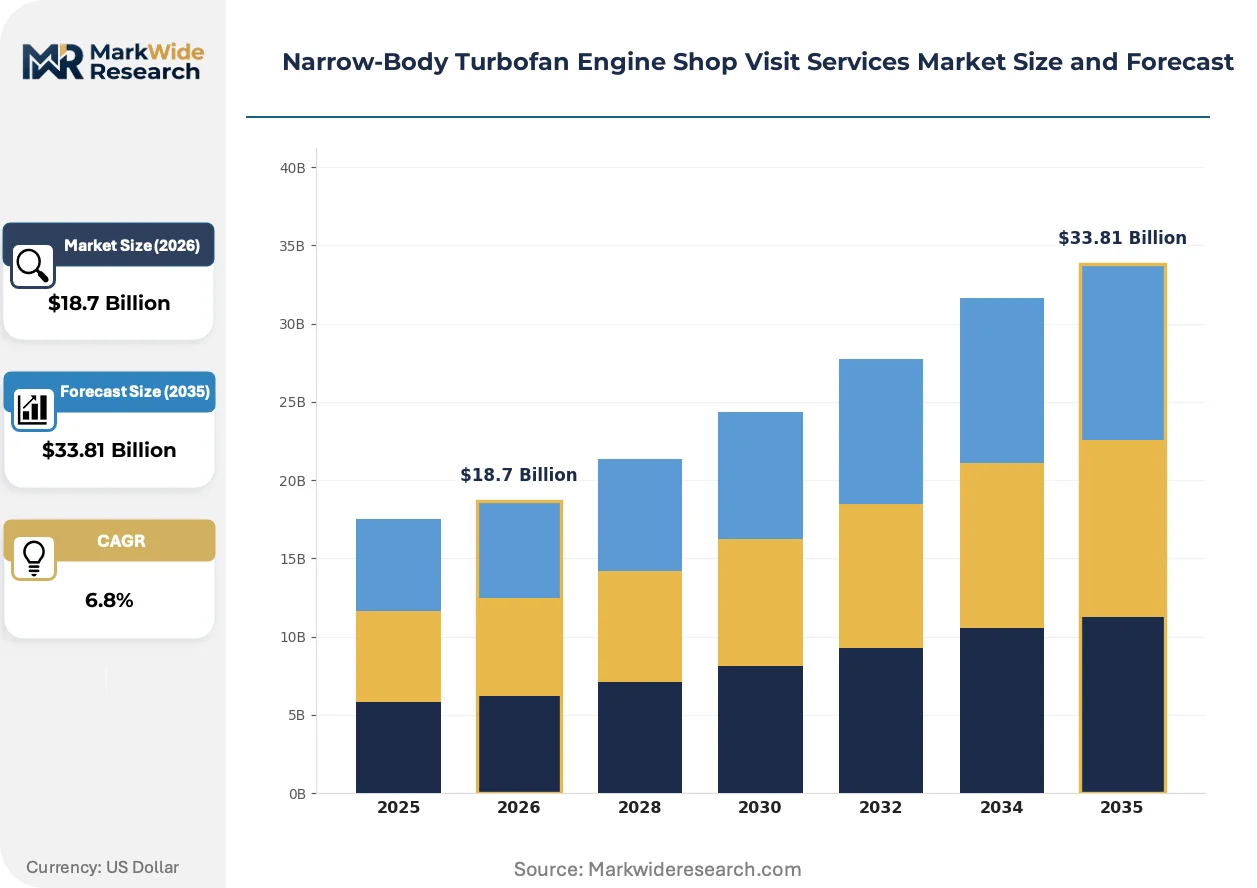
Market Dynamics
FAA's high-cycle turbine inspection mandates are compressing shop visit intervals for mature narrow-body fleets while COMAC C919 deployments accelerate demand for indigenous MRO certification pathways in China.
Growth Catalysts
- Southeast Asian low-cost carrier expansion:Fleet utilization rates above 14 hours daily on Airbus A320neo and Boeing 737 MAX platforms are shortening engine cycle accumulation timelines and accelerating shop visit frequency across Indonesia, Vietnam, and the Philippines.
- ICAO CORSIA compliance pathways:Carbon offsetting requirements are mandating combustion system modifications and exhaust nozzle efficiency restoration during scheduled overhauls, expanding per-visit service scope for LEAP and PW1100G powerplants.
- Blade repair technology maturation:Proprietary coating restoration processes for high-pressure turbine airfoils now enable on-wing repair capabilities that reduce unscheduled removals and extend time-between-overhaul intervals.
Market Restraints
- Specialized alloy supply concentration:Single-source dependency for nickel-based superalloys used in turbine disk manufacturing creates input cost volatility and delivery timeline risk for independent MRO providers.
- Proprietary OEM data lock-in:GE Aerospace and Pratt & Whitney predictive maintenance platforms restrict third-party access to engine health monitoring telemetry, constraining independent shop visit forecasting accuracy.
- Dual-track certification burden:China's CAAC parallel compliance requirements for COMAC C919 engine support force domestic MRO facilities to maintain concurrent OEM and indigenous certification streams, elevating fixed-cost structures.
Strategic Opportunities
- India domestic aviation build-out:IndiGo and Air India's narrow-body fleet expansion toward 1,500 aircraft by 2030 creates unmet MRO demand as local overhaul capacity remains concentrated in engine component repair rather than full shop visit execution.
- Performance-based service contracting:Power-by-the-hour arrangements tied to fuel efficiency restoration metrics are displacing traditional time-and-material billing, enabling OEM-affiliated networks to capture recurring revenue streams.
- Digital twin convergence with additive repair:Real-time engine modeling combined with directed energy deposition for blade tip restoration is enabling predictive component replacement before performance degradation triggers unscheduled removal.
Industry Challenges
- Certified technician scarcity:FAA and EASA-qualified turbine inspection personnel shortages extend shop visit turnaround times by 15-20 percent at independent facilities competing for specialized labor pools.
- Legacy fleet transition complexity:CFM56-5B and -7B overhaul expertise concentration among aging technician cohorts creates knowledge transfer gaps as operators accelerate LEAP-1A and LEAP-1B adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Narrow-Body Turbofan Engine Shop Visit Services Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Routine Maintenance, Component Repair, Overhaul, Performance Testing, Engine Wash Aircraft Model Compatibility: Boeing 737, Airbus A320, COMAC C919, Mitsubishi SpaceJet, Embraer E-Jets Customer Type: Airlines, MRO Providers, OEMs, Leasing Companies, Charter Operators Shop Visit Duration: Short-Term, Medium-Term, Long-Term, Emergency, Scheduled |
| Companies Covered | CFM International, Pratt & Whitney, Safran Aircraft Engines, Rolls-Royce, GE Aerospace, MTU Aero Engines, ST Engineering, StandardAero, Lufthansa Technik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Narrow-Body Turbofan Engine Shop Visit Services Market Trends and Innovations
Shop visit scope is expanding beyond mechanical restoration toward emissions-compliant performance optimization as regulatory pressure and operator cost sensitivity converge on fuel burn metrics.
On-wing automated borescope inspection systems equipped with machine learning defect classification are electrifying routine engine health assessment workflows. Low-cost carriers in Southeast Asia are deploying these systems at outstations to triage fleet condition without ferrying engines to central MRO hubs. The technology is compressing diagnostic cycle times from days to hours while reducing unnecessary removals.
EASA's updated engine type certificate conditions for sustainable aviation fuel compatibility are mandating combustor hardware modifications during scheduled overhauls. The regulatory shift requires MRO providers to maintain dual-configuration part inventories and technician training for conventional and SAF-optimized fuel system architectures. European operators with 2030 emissions targets are prioritizing shop visit slots at EASA-aligned facilities with demonstrated SAF retrofit capability.
Airline procurement departments are unbundling engine wash and performance restoration services from bundled overhaul contracts. The purchasing pattern fragmentation is creating standalone revenue lines for quick-turn service providers while compressing margins for full-service MRO networks dependent on package pricing. This decoupling is most visible among US ultra-low-cost carriers optimizing cash flow through a-la-carte maintenance scheduling.
Narrow-Body Turbofan Engine Shop Visit Services Market Segmentation
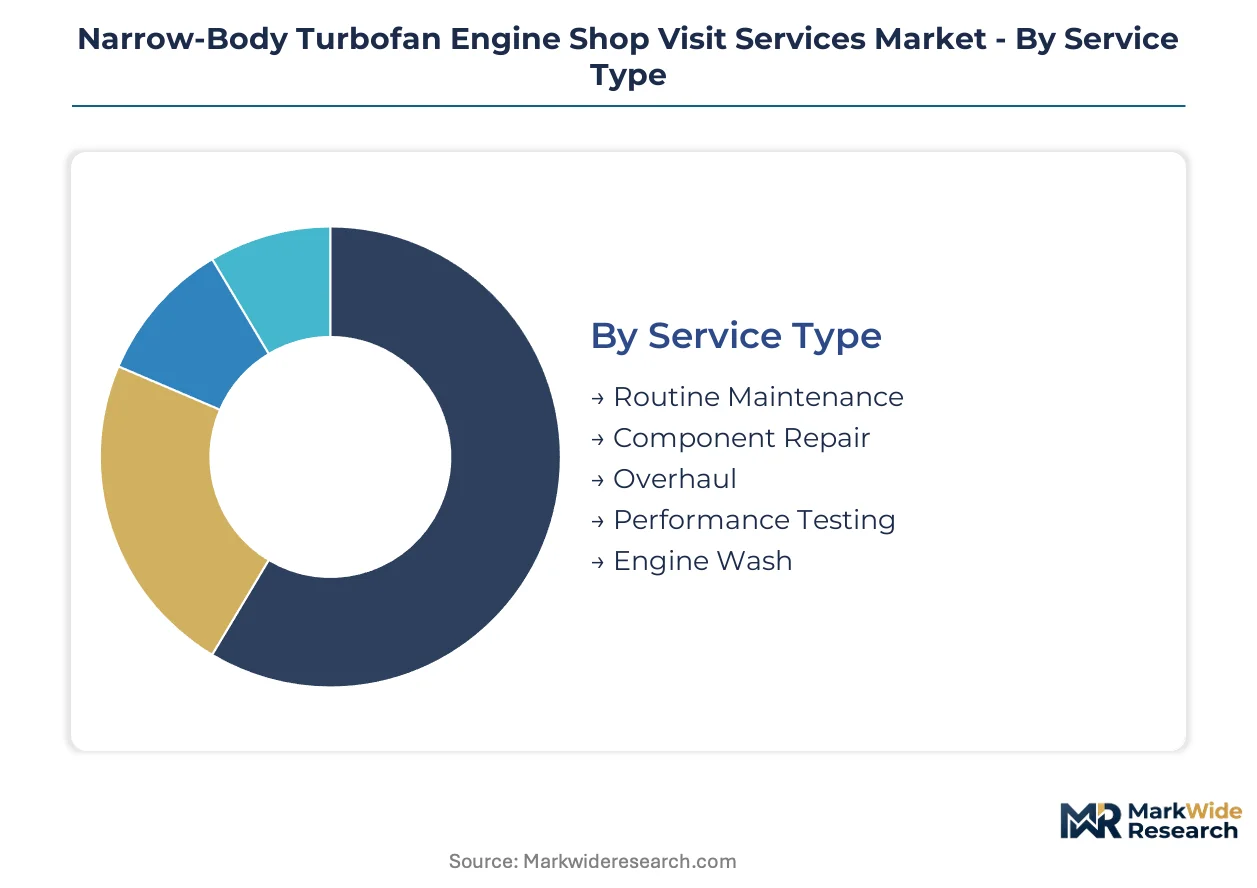
Shop visit service segmentation reveals divergent capital requirements across workflow types, with overhaul infrastructure demanding tenfold higher fixed-cost commitments than routine maintenance lines. Aircraft platform specialization and customer contract structures further stratify provider economics, shaping competitive entry barriers and margin profiles across the narrow-body MRO landscape.
Service Type:
Capital intensity peaks with full overhaul execution, where specialized test cells and certified technician pools lock in multi-million dollar facility investments before first revenue recognition.
- Routine Maintenance:Scheduled inspections, borescope evaluations, and minor module replacements preserve engine airworthiness between major overhauls. Demand concentrates among Southeast Asian low-cost carriers running high-utilization fleets above 14 daily flight hours, compressing interval timelines and sustaining predictable volume.
- Overhaul:Complete engine disassembly, component restoration, and reassembly to zero-time condition restore full performance specifications. China's domestic aviation sector anchors demand as COMAC C919 deployments accelerate and local MRO capacity scales to serve indigenous narrow-body platforms under dual CAAC-OEM certification requirements.
- Component Repair:Specialized restoration of turbine airfoils, compressor blades, and combustor liners using proprietary coating processes.
- Performance Testing:Post-overhaul validation runs and fuel efficiency verification in certified test cell environments.
- Engine Wash:On-wing and shop-based compressor cleaning services restoring thrust output and reducing fuel burn between scheduled visits.
Overhaul absorbs the bulk of installed capacity; engine wash is expanding most quickly as operators unbundle quick-turn services from bundled contracts.
Aircraft Model Compatibility:
Platform-specific tooling and technician certification requirements fragment addressable market scope, with newer-generation engines demanding distinct infrastructure investments from legacy fleets.
- Boeing 737:Spanning CFM56-7B and LEAP-1B powerplants across Classic, NG, and MAX variants, this platform commands the largest installed base of shop visit-eligible engines. MRO providers in the United States anchor capacity concentration, with FAA maintenance directive compliance windows tightening inspection cadences for high-cycle turbine components.
- Airbus A320:CFM56-5B and LEAP-1A engines power the highest-utilization narrow-body fleets globally, particularly among European low-cost operators. EASA-aligned facilities in Germany and Malta position for LEAP-1A overhaul volume as legacy V2500 expertise ages out of the technician workforce.
- COMAC C919:China's indigenous narrow-body platform drives demand for CAAC-certified MRO infrastructure capable of concurrent OEM validation.
- Mitsubishi SpaceJet:Regional jet platform with specialized Pratt & Whitney PW1200G service requirements.
- Embraer E-Jets:GE Aviation CF34-10E powerplants serving regional and charter operator segments with distinct shop visit economics.
Boeing 737 and Airbus A320 together dominate current throughput; COMAC C919 is gaining share fastest as Chinese fleet deployments accelerate indigenous MRO build-out.
Customer Type:
Contract structure heterogeneity shapes revenue predictability, with power-by-the-hour arrangements concentrating volume among OEM-affiliated networks while time-and-material billing sustains independent provider participation.
- Airlines:Direct procurement of shop visit services by network and low-cost carriers, with fleet scale determining contract leverage and slot priority access.
- MRO Providers:Third-party maintenance organizations serving non-affiliated operators, competing on turnaround time and specialized platform expertise.
- OEMs:Original equipment manufacturers capturing recurring revenue through captive service networks and predictive maintenance platform lock-in.
- Leasing Companies:Asset owners mandating shop visit compliance to preserve residual values and lease rate competitiveness across lessee transitions.
- Charter Operators:Fragmented demand from ad-hoc and corporate aviation segments with irregular utilization patterns and expedited turnaround requirements.
Airlines and OEMs together command dominant contract volume; leasing companies are climbing the fastest as lessor-owned narrow-body fleets expand and residual value protection intensifies shop visit mandate enforcement.
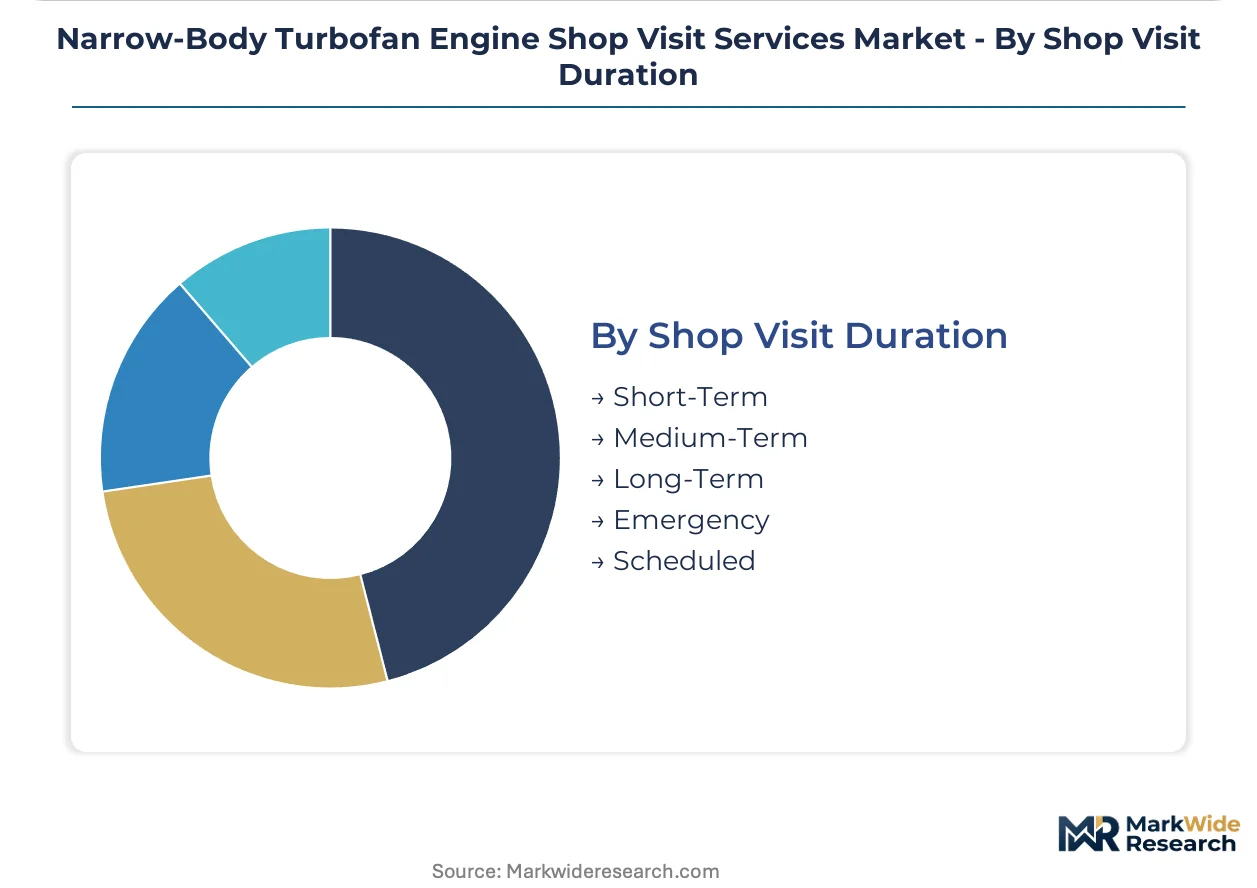
Shop Visit Duration:
Turnaround time classification determines facility scheduling density and labor allocation models, with emergency response capabilities commanding premium pricing and dedicated capacity reserves.
- Scheduled:Pre-planned overhauls aligned with flight hour and cycle accumulation limits, enabling optimal slot allocation and component pre-positioning. Demand concentrates among full-service network carriers in Europe and Asia-Pacific maintaining continuous airworthiness management programs with predictable maintenance windows.
- Emergency:Unscheduled removals triggered by borescope findings, vibration exceedances, or airworthiness directive compliance deadlines. FAA's updated high-cycle turbine inspection mandates are compressing response timelines, rewarding MRO providers with dedicated rapid-response cells and expedited parts supply chains.
- Short-Term:Quick-turn services under 30 days including engine wash and limited module replacement.
- Medium-Term:Standard overhaul cycles of 45-75 days for mature engine types with established repair schemes.
- Long-Term:Extended restoration projects exceeding 90 days for legacy platforms with parts availability constraints or specialized engineering requirements.
Scheduled visits absorb the bulk of facility throughput; emergency response is expanding most quickly as regulatory compliance windows tighten and unscheduled removal rates climb among high-utilization fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Singapore and the UAE are concentrating MRO investment through tax holidays and duty exemptions on engine component imports. These regulatory enclaves attract OEM-affiliated service networks seeking to minimize working capital tied up in high-value turbine spare parts inventories.
United States
FAA maintenance directive compliance windows for high-cycle turbine inspections are compressing turnaround requirements for CFM56-7B and LEAP-1B powerplants. The regulator's updated airworthiness standards mandate traceable part histories that elevate documentation costs for independent providers. Dallas-Fort Worth and Atlanta anchor the densest shop visit capacity clusters, with OEM-affiliated networks capturing premium slots from ultra-low-cost carriers running 737 MAX fleets above 13 daily flight hours.
China
COMAC C919 deployments are accelerating demand for indigenous MRO certification pathways that satisfy concurrent CAAC and OEM validation requirements. The civil aviation regulator enforces parallel compliance streams that force domestic facilities to maintain dual-qualified technician pools. Shanghai Pudong and Tianjin host the most advanced narrow-body engine overhaul infrastructure, with state-backed enterprises scaling test cell capacity to serve LEAP-1C powerplants on domestic trunk routes.
Germany
EASA-aligned facilities in Hamburg and Munich position for LEAP-1A overhaul volume as European low-cost operators accelerate A320neo adoption. The regulator's updated engine type certificate conditions for sustainable aviation fuel compatibility mandate combustor hardware modifications during scheduled visits. Lufthansa Technik anchors the regional service network, leveraging proximity to EASA headquarters for expedited certification of SAF-optimized fuel system architectures.
Singapore
Seletar Aerospace Park tax incentives are attracting third-party MRO providers seeking to serve Southeast Asian low-cost carrier expansion. The Civil Aviation Authority of Singapore maintains bilateral certification reciprocity with FAA and EASA that streamlines cross-border engine acceptance. ST Engineering anchors the indigenous capability base, positioning quick-turn engine wash and performance restoration services for carriers running A320neo fleets above 14 daily utilization hours.
India
IndiGo and Air India narrow-body fleet expansion toward 1,500 aircraft by 2030 is creating unmet shop visit demand as local overhaul capacity remains concentrated in component repair. The Directorate General of Civil Aviation mandates foreign MRO joint ventures for full engine overhaul execution, protecting domestic employment while constraining technology transfer. Bengaluru and Hyderabad host emerging engine service clusters, with state governments offering land and power subsidies to attract OEM-affiliated test cell investments.
Narrow-Body Turbofan Engine Shop Visit Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where OEM-captive networks command premium pricing through predictive maintenance platform lock-in. The market exhibits consolidated leadership at the top, with independent providers fragmenting across specialized platform niches and geographic clusters. Three archetypes dominate: vertically integrated engine manufacturers capturing recurring revenue through service contracts, airline-affiliated MRO divisions leveraging fleet scale for slot priority, and independent specialists competing on turnaround speed for unscheduled removals. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with facilities racing to achieve dual CAAC-OEM certification for Chinese market access.
Among engine manufacturer-affiliated service networks, CFM International, Pratt & Whitney, and GE Aerospace exemplify the OEM-captive archetype through proprietary data analytics and blade repair technologies that differentiate their offerings from third-party alternatives. These entities occupy positions where predictive maintenance contracts lock in recurring shop visit volume and constrain independent forecasting accuracy. Lufthansa Technik and StandardAero represent alternative models—airline-captive versus independent specialist—each anchoring distinct competitive positions based on regulatory proximity and platform-specific expertise rather than manufacturing integration.
| Leading Market Players |
|---|
| CFM International |
| Pratt & Whitney |
| Safran Aircraft Engines |
| Rolls-Royce |
| GE Aerospace |
| MTU Aero Engines |
| ST Engineering |
| StandardAero |
| Lufthansa Technik |
| Others |
Pricing and Supply Chain Analysis
Backward integration into proprietary blade repair technologies anchors pricing power for OEM-affiliated networks while constraining margin capture among independent MRO providers dependent on spot market alloy procurement. FAA airworthiness directive compliance windows and EASA engine type certificate conditions elevate fixed-cost structures that pass through to operator pricing, with dual-track CAAC-OEM certification requirements in China layering additional cost premiums on indigenous narrow-body platforms.
Pricing Analysis
Expedited turnaround premiums for emergency unscheduled removals command substantial markups over scheduled slot pricing, while routine maintenance and engine wash services compete on spot-market transparency. Three-tier pricing structure across OEM-captive, airline-affiliated, and independent specialist levels differentiates on certification pedigree and predictive maintenance platform access. Cost compression in independent MRO tiers is intensifying because proprietary OEM data lock-in restricts third-party forecasting accuracy and parts pre-positioning leverage. Ultra-low-cost carriers in Southeast Asia exhibit highest price sensitivity, prioritizing a-la-carte service unbundling over bundled overhaul contracts.
Supply Chain Analysis
Single-source vulnerability sits with nickel-based superalloy suppliers concentrated in the United States, Germany, and Japan, where turbine disk manufacturing expertise anchors critical input availability. Specialized coating chemistries for high-pressure turbine airfoils and precision-forged compressor blades draw from captive OEM supply streams and qualified independent foundries. Tariff exposure on precision-machined components creates margin volatility for European and Asian MRO facilities sourcing from cross-border specialty metal suppliers. Distribution runs through OEM-affiliated service networks, airline-captive MRO divisions, and independent quick-turn specialists segmented by platform certification and regulatory alignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The narrow-body turbofan engine shop visit services market sits in a technology-transition phase as digital twin convergence with additive repair displaces conventional component replacement workflows. Machine learning-equipped automated borescope systems are replacing legacy manual inspection protocols across Southeast Asian low-cost carrier outstations.
For Market Incumbents: Cement predictive maintenance platform lock-in through expanded telemetry access contracts that constrain independent competitor forecasting capabilities. Deepen blade repair technology moats via directed energy deposition capabilities for on-wing restoration, defending against emerging additive manufacturing specialists targeting quick-turn service niches. Prioritize dual CAAC-OEM certification investment in Shanghai and Tianjin to capture COMAC C919 shop visit volume before indigenous Chinese MRO capacity matures. For New Entrants and Emerging Players: Launch via specialized component repair subcontracting to OEM-affiliated networks, leveraging lower fixed-cost structures than full overhaul execution. Target India's unmet MRO demand as IndiGo and Air India fleet expansion outpaces local overhaul capacity build-out. Pursue engine wash and performance restoration quick-turn services as the most penetrable entry point, capitalizing on procurement department unbundling of bundled overhaul contracts among US ultra-low-cost carriers. For Investors and Strategic Acquirers: Exit pathways concentrate in OEM-affiliated network acquisition of independent specialists with proven LEAP-1A and LEAP-1B platform expertise. Long-term viability favors facilities with demonstrated SAF retrofit capability under EASA updated engine type certificate conditions. Watch certified technician scarcity as the inflection indicator—FAA and EASA-qualified turbine inspection personnel shortages extending turnaround times signal margin compression pressure and consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | CAAC-OEM concurrent validation unlocks COMAC C919 shop visit access in Shanghai and Tianjin clusters. |
| Predictive Maintenance Platform Expansion | Telemetry lock-in contracts secure recurring revenue streams from high-utilization Southeast Asian low-cost carriers. |
| Additive Repair Capability Buildout | Directed energy deposition for blade tip restoration enables predictive component replacement before unscheduled removal triggers. |
| SAF Retrofit Infrastructure | EASA-aligned combustor hardware modification capability captures European operator 2030 emissions compliance demand. |
| Quick-Turn Service Unbundling | Standalone engine wash and performance restoration lines target procurement fragmentation among US ultra-low-cost carriers. |
Research Methodology
Multi-period observation of shop visit frequency trends, fleet utilization rates, and regulatory compliance window compressions anchored the trend analysis, supplemented by interviews with MRO operations directors, FAA-certified turbine inspection technicians, airline fleet planning executives, and OEM aftermarket service managers. Secondary validation drew from FAA airworthiness directive filings, EASA engine type certificate updates, CAAC certification registries, and customs data on specialized alloy imports. Bottom-up facility capacity modeling and top-down fleet projection triangulation informed market sizing across the analysis window.
Segment-weighting approaches distributed value across service type, aircraft model compatibility, customer contract structure, and shop visit duration categories. Service-type splits between routine maintenance, overhaul, component repair, performance testing, and engine wash were modeled against fleet age profiles and cycle accumulation rates. Customer-type segmentation captured power-by-the-hour contract concentration versus time-and-material billing patterns. CAGRs were derived from regression analysis of historical shop visit volume against flight hour projections, with sensitivity testing on low-cost carrier expansion scenarios and regulatory interval compression assumptions.
ICAO CORSIA implementation delays, COMAC C919 deployment pace variations, and nickel-based superalloy supply disruptions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions on technician workforce growth, bilateral certification reciprocity maintenance, and SAF infrastructure build-out timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market