
 Advanced Air Mobility Market | 2026-2036
Advanced Air Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Air Mobility Market Analytics
FAA Part 135 air carrier certification is redrawing competitive boundaries for commercial passenger operations. Joby Aviation leverages extensive flight-test data to sustain its lead in range and payload validation. Archer Aviation differentiates through a tilt-rotor architecture that reduces mechanical complexity. Volocopter navigates European regulatory pathways while anchoring its early deployment strategy in targeted city networks.
Advanced Air Mobility encompasses electric and hybrid-electric aircraft systems designed for vertical takeoff and landing operations, typically utilizing distributed electric propulsion with multiple rotors or lift fans to achieve thrust redundancy and reduced noise signatures below 65 decibels during hover. These platforms serve urban and regional transportation missions that ground infrastructure cannot complete within comparable timeframes. Battery Electric technology dominates current development pipelines due to energy density improvements in lithium-ion cell architectures, while Hydrogen Fuel Cell configurations represent the fastest-growing technology segment for extended-range missions where payload endurance outweighs infrastructure simplicity. Urban Air Mobility applications command the largest share of near-term investment, though Medical Transportation generates disproportionate margin pools through premium pricing for time-critical deliveries.
The FAA governs type certification and operational rules for U.S. airspace, while EASA develops parallel standards under its SC-VTOL framework, and China's CAAC issues separate airworthiness directives that fragment market access requirements. These regulatory bodies shape demand by determining which vehicle architectures qualify for commercial service and which operators may carry passengers. Stakeholders must monitor certification timeline convergence between jurisdictions to avoid stranded platform investments.
Market Dynamics
FAA Part 135 certification timelines are compressing operator entry windows while battery energy density gains unlock extended-range missions that reshape platform economics.
Growth Catalysts
- Urban congestion pricing:Metropolitan transit authorities in Singapore and London are imposing escalating road-use fees that push ride-hailing platforms toward aerial alternatives. This policy shift creates immediate demand pull for point-to-point air taxi services.
- Distributed electric propulsion:Multi-rotor architectures with redundant thrust systems reduce single-point-of-failure risk below conventional helicopter thresholds. This technical configuration accelerates insurer willingness to underwrite commercial passenger operations.
- SC-VTOL framework maturation:EASA's dedicated certification pathway for small-category vertical takeoff aircraft provides regulatory certainty that attracts institutional capital into European manufacturing facilities.
Market Restraints
- Lithium-ion cell supply concentration:Cathode active material processing clusters in China's Hunan and Fujian provinces create geographic chokepoints for battery pack assembly. This concentration exposes non-Chinese airframe integrators to input cost volatility and export licensing friction.
- Ground infrastructure capex intensity:Vertiport construction with rapid-charging electrical draw and noise abatement systems requires municipal bond financing that competes with legacy transit priorities. This capital requirement slows network density buildout below vehicle deployment rates.
- Acoustic footprint limitations:Hover noise signatures below 65 decibels constrain rotor diameter and tip speed combinations that limit payload-range tradeoffs. This physics boundary prevents direct substitution for helicopter missions in dense urban canyons.
Strategic Opportunities
- Hydrogen fuel cell convergence:Solid-state storage systems paired with fuel cell stacks enable missions beyond lithium-ion range limits without vertiport electrical upgrades. This technology pairing opens inter-city corridors that battery-electric platforms cannot serve.
- Medical transport premium pricing:Time-critical organ and patient transfer contracts command reimbursement multiples above scheduled passenger service. This application vertical justifies higher platform acquisition costs through utilization rate guarantees.
- UAE regulatory sandbox:Dubai's integrated transport authority permits commercial trials ahead of full type certification, creating operational data advantages for early entrants. This jurisdiction offers revenue-generating flight hours that accelerate FAA and EASA validation timelines.
Industry Challenges
- Certified pilot supply constraints:Multi-engine turbine ratings do not transfer directly to eVTOL type ratings, forcing operators to fund ab-initio training programs. This skill gap extends crew readiness timelines and inflates labor cost projections.
- Airspace integration complexity:UTM systems must coordinate with existing IFR corridors and helicopter routes without degrading legacy traffic flow. This systems integration burden falls on operators until regulator-mandated standards emerge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Air Mobility Market |
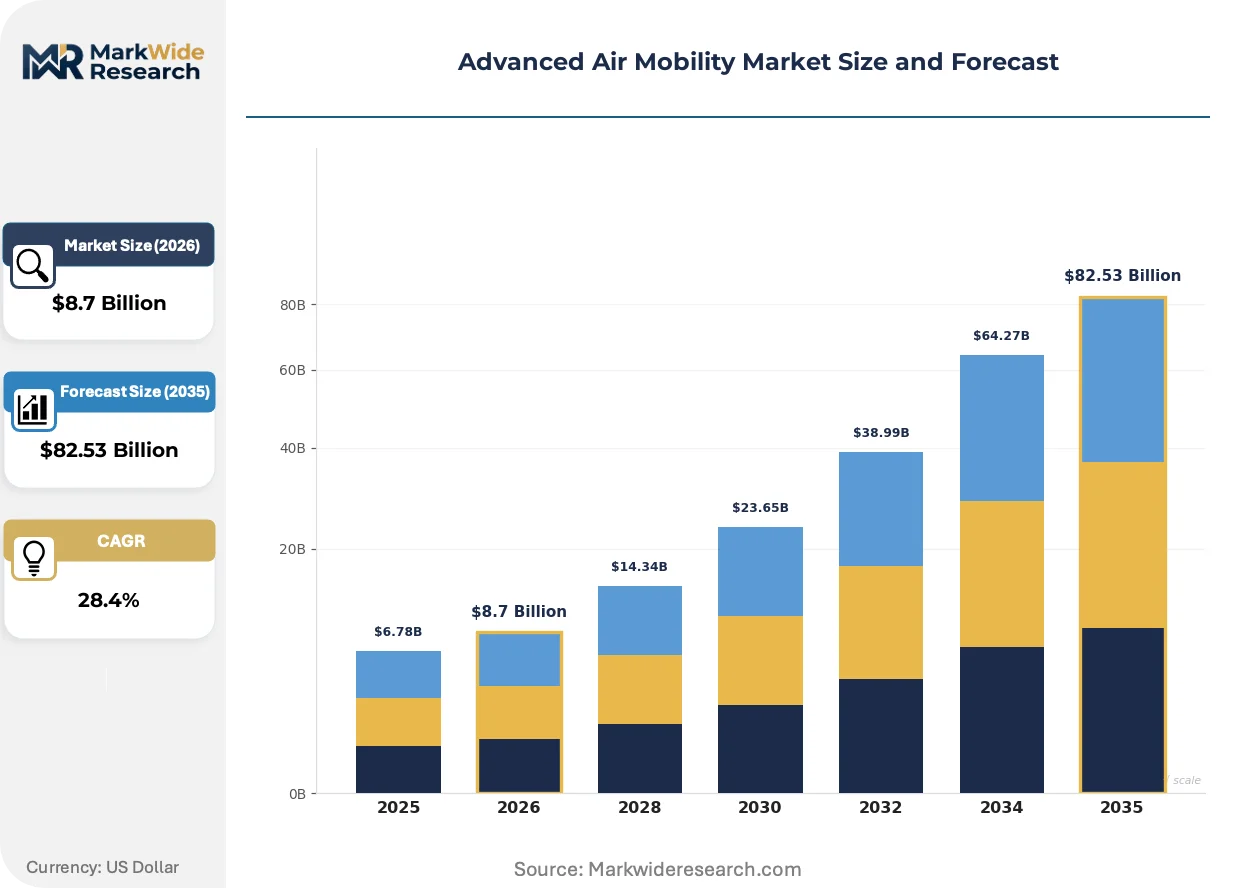
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: eVTOL, Air Taxi, Cargo Drone, Autonomous Aerial Vehicle End User: Government, Logistics Companies, Ride-Sharing Services, Emergency Services Technology: Battery Electric, Hybrid Electric, Hydrogen Fuel Cell, Autonomous Navigation Application: Urban Air Mobility, Medical Transportation, Cargo Delivery, Surveillance |
| Companies Covered | Joby Aviation, Archer Aviation, Volocopter, The Boeing Company, Airbus S.A.S., Embraer S.A., Bell Textron Inc., Lilium GmbH, Guangzhou EHang Intelligent Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Air Mobility Market Evolving Landscape
Battery-electric propulsion architectures are fragmenting mission profiles across distinct range-payload categories while regulatory bodies race to certify vehicles ahead of operational demand.
Silicon-anode lithium-ion cells with lithium-metal enhancements are fragmenting the energy storage landscape for urban air mobility platforms. Archer's tilt-rotor designs and Joby's fixed-wing transitions both target this chemistry for 150-mile mission radii. The technology is fragmenting supplier relationships as airframe developers sign exclusive offtake agreements with cell manufacturers to lock in production slots ahead of automotive demand.
REACH chemical restrictions and the EU Green Deal's sustainable aviation fuel mandates are tightening material disclosure requirements for battery supply chains. European operators must now document carbon intensity across cell production from mining through pack assembly. This regulatory pressure is concentrating procurement decisions on Nordic and Portuguese manufacturing facilities with verified renewable energy inputs.
Hospital networks and emergency medical service consortiums are consolidating purchasing authority for air ambulance contracts into regional procurement cooperatives. These buying groups negotiate multi-year exclusivity in exchange for guaranteed annual flight-hour minimums. This concentration is visible across the southeastern United States, where health systems in Florida, Georgia, and Tennessee have formed joint sourcing entities.
Advanced Air Mobility Market Segmentation
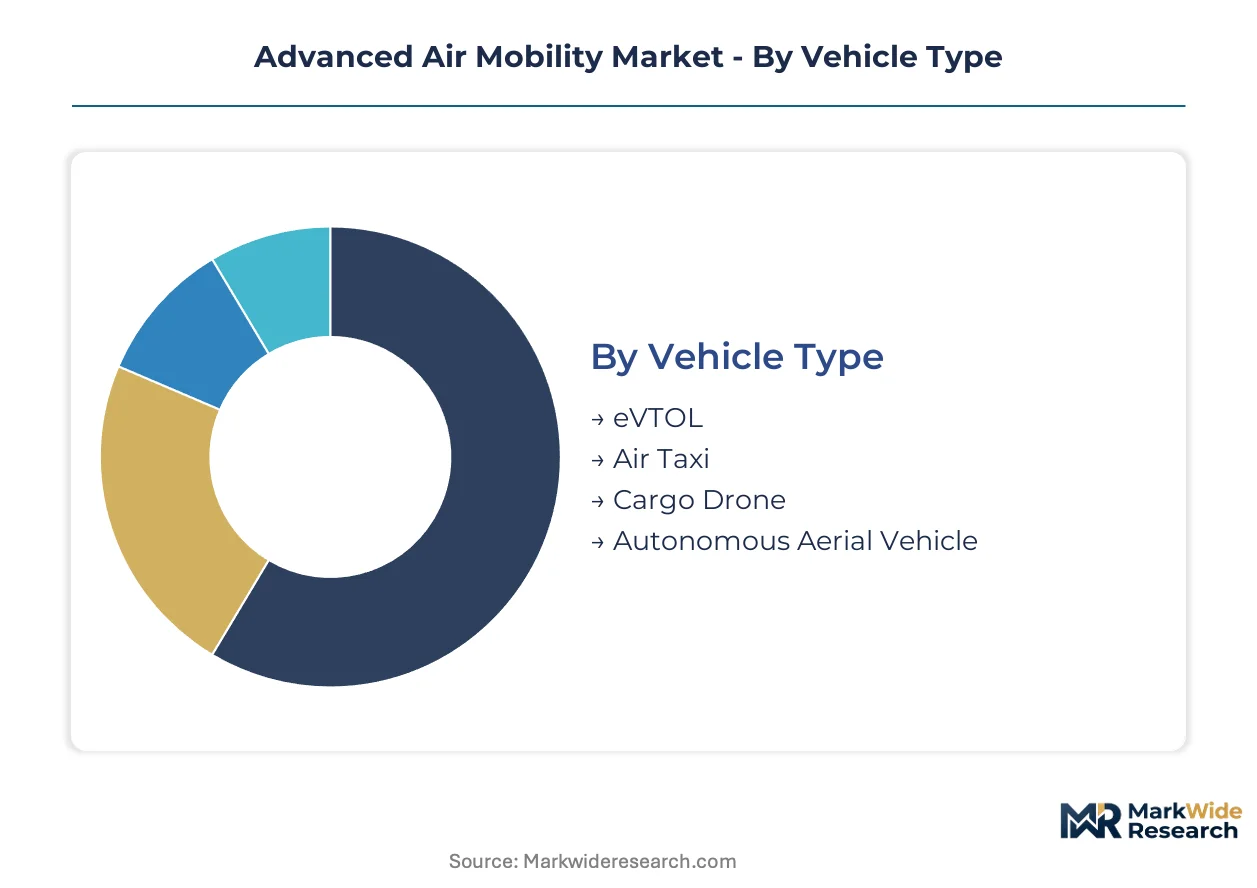
Segmentation in Advanced Air Mobility reveals how vehicle architectures, operational missions, and energy systems map to distinct certification pathways and infrastructure requirements. Each category channels capital toward different stakeholder groups and regulatory jurisdictions.
Vehicle Type:
eVTOL platforms flow through Part 135 certificated operators, while cargo drones deploy through logistics networks with BVLOS waivers; air taxis concentrate in ride-sharing partnerships, and autonomous aerial vehicles await type certification clarity before commercial channel entry.
- eVTOL:Electric vertical takeoff and landing aircraft utilize distributed electric propulsion with tilt-rotor or lift-plus-cruise configurations. FAA Part 135 certification in the United States is concentrating demand among operators with existing air carrier infrastructure, compressing entry timelines for new market entrants.
- Air Taxi:Passenger-carrying platforms designed for point-to-point urban transit with 2-6 seat configurations and noise signatures below 65 decibels. Ride-sharing platforms in Singapore and Dubai are anchoring early deployment through exclusive vertiport access agreements that lock in route monopolies.
- Cargo Drone:Uncrewed platforms for last-mile package delivery with payload capacities below 500 kilograms.
- Autonomous Aerial Vehicle:Pilot-optional systems awaiting detect-and-avoid certification standards.
eVTOL dominates installed base. Air taxi is where expansion concentrates.
End User:
Cost tiers separate government procurement at premium pricing from logistics volume contracts and ride-sharing platform subsidies; emergency services occupy a high-margin niche with utilization guarantees.
- Government:Defense and civilian agencies procuring surveillance and personnel transport platforms under Federal Acquisition Regulation schedules. United States Department of Defense programs in California and Texas are concentrating demand through Other Transaction Authority contracts that bypass standard procurement timelines.
- Emergency Services:Hospital networks and fire departments contracting for organ transport and disaster response missions. Regional procurement cooperatives across Florida, Georgia, and Tennessee are consolidating purchasing authority through multi-year exclusivity agreements with guaranteed annual flight-hour minimums.
- Logistics Companies:Parcel carriers integrating drones into hub-and-spoke distribution networks.
- Ride-Sharing Services:Mobility platforms seeking aerial alternatives to ground congestion.
Emergency services command premium pricing tiers. Logistics companies are where volume scaling concentrates.
Technology:
Energy density divides mission profiles: lithium-ion systems serve urban routes under 150 miles, while hydrogen fuel cells unlock inter-city corridors; hybrid architectures bridge gaps where vertiport electrical infrastructure remains incomplete.
- Battery Electric:Lithium-ion cell architectures with silicon-anode enhancements achieving 300 Wh/kg energy density. Silicon-anode lithium-ion cells with lithium-metal enhancements are fragmenting supplier relationships as airframe developers sign exclusive offtake agreements with cell manufacturers to lock in production slots ahead of automotive demand.
- Hydrogen Fuel Cell:Solid-state storage paired with fuel cell stacks for missions beyond battery-electric range limits. Nordic and Portuguese manufacturing facilities with verified renewable energy inputs are concentrating procurement decisions under REACH chemical restrictions and EU Green Deal mandates.
- Hybrid Electric:Turbogenerator-battery combinations for extended-range missions.
- Autonomous Navigation:Detect-and-avoid systems awaiting UTM integration standards.
Battery electric dominates current development pipelines. Hydrogen fuel cell is gaining share fastest for extended-range missions.
Application:
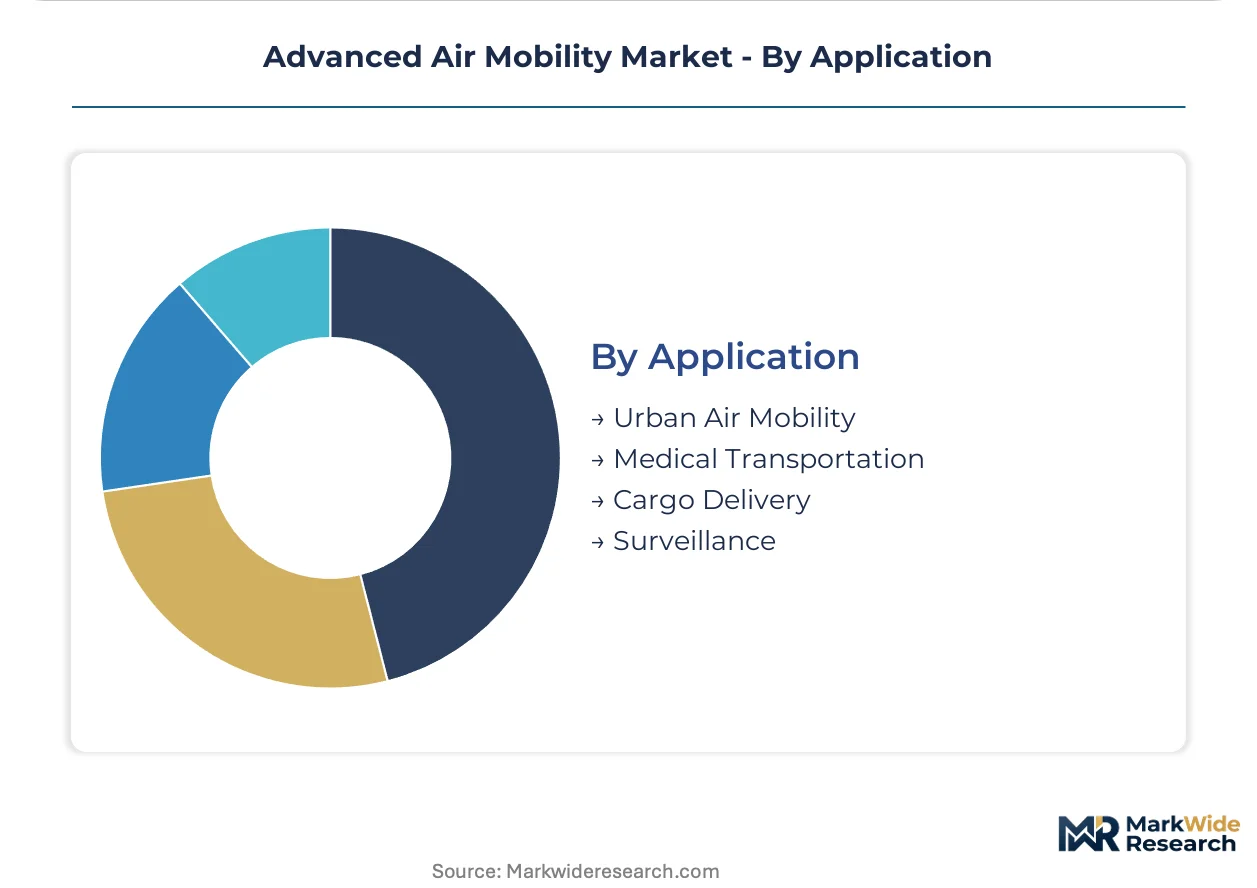
Volume runs through cargo delivery networks, while margin concentrates in medical transportation; urban air mobility anchors infrastructure investment, and surveillance serves government procurement cycles.
- Urban Air Mobility:Scheduled and on-demand passenger services connecting vertiports within metropolitan regions. Dubai's integrated transport authority permits commercial trials ahead of full type certification, creating operational data advantages for early entrants that accelerate FAA and EASA validation timelines.
- Medical Transportation:Time-critical organ and patient transfer with premium reimbursement multiples above scheduled passenger service. Hospital networks across the southeastern United States are consolidating purchasing authority into regional procurement cooperatives that negotiate multi-year exclusivity.
- Cargo Delivery:Last-mile and inter-facility freight movement.
- Surveillance:Border patrol and infrastructure monitoring missions.
Urban air mobility anchors infrastructure capex. Medical transportation is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 135 certification pathways and EASA SC-VTOL frameworks are accelerating deployment timelines in jurisdictions with active regulatory sandboxes. Government procurement programs and ride-sharing platform partnerships are concentrating initial demand in specific metropolitan clusters.
United States
The FAA's Part 135 air carrier certification is compressing operator entry windows for commercial passenger services. Regulatory sandbox programs in California and Texas are generating operational flight hours that validate vehicle architectures ahead of full type certification. Dallas-Fort Worth and Los Angeles metropolitan areas are anchoring early vertiport network development through public-private infrastructure partnerships.
Germany
EASA's SC-VTOL framework provides dedicated certification pathways for small-category vertical takeoff aircraft that attract institutional manufacturing investment. REACH chemical restrictions and EU Green Deal mandates are concentrating battery supply chain procurement on facilities with verified renewable energy inputs. Bavaria and Baden-Württemberg host airframe development clusters where tilt-rotor and lift-plus-cruise configurations undergo flight validation.
China
CAAC airworthiness directives are establishing separate certification standards that fragment market access for foreign platform developers. Dual carbon policy goals are accelerating domestic electric propulsion supply chain localization. Guangzhou and the Yangtze River Delta region concentrate autonomous aerial vehicle testing through municipal transport authority permits ahead of national commercial frameworks.
UAE
Dubai's integrated transport authority permits revenue-generating commercial trials ahead of full type certification, creating operational data advantages for early entrants. NEOM development corridors in Saudi Arabia are integrating aerial mobility into master-planned infrastructure from inception. Abu Dhabi sovereign wealth vehicles are anchoring fleet purchase commitments that de-risk manufacturing scale-up for certified platforms.
Singapore
Urban congestion pricing policies are pushing ride-hailing platforms toward aerial alternatives with immediate demand pull for point-to-point services. The Civil Aviation Authority of Singapore coordinates vertiport siting with maritime port authority zones to minimize airspace conflicts. Seletar Aerospace Park hosts maintenance and training facilities that support regional fleet deployment across Southeast Asian city networks.
Advanced Air Mobility Market Competitive Landscape
Player mix skews toward venture-backed airframe developers with aerospace incumbent participation through strategic partnerships. Market structure exhibits tiered concentration where FAA Part 135 certification progress separates deployable platforms from development-stage concepts. Strategic archetypes include pure-play eVTOL developers, diversified aerospace conglomerates with urban air mobility divisions, and ride-sharing platforms securing exclusive fleet access. Dominant competitive moves center on battery cell offtake agreements for production slot security and vertiport network partnerships for route monopolies.
Among pure-play developers, Joby Aviation, Archer Aviation, and Volocopter occupy positions representing distinct certification pathway strategies. Joby Aviation exemplifies the flight-test data accumulation archetype through extensive range and payload validation programs. Archer Aviation represents the tilt-rotor architecture specialization that reduces mechanical complexity relative to multi-rotor alternatives. Volocopter anchors the European regulatory pathway strategy through EASA SC-VTOL framework engagement while maintaining operational trial presence in Middle Eastern sandbox jurisdictions.
| Leading Market Players |
|---|
| Joby Aviation |
| Archer Aviation |
| Volocopter |
| The Boeing Company |
| Airbus S.A.S. |
| Embraer S.A. |
| Bell Textron Inc. |
| Lilium GmbH |
| Guangzhou EHang Intelligent Technology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Hunan and Fujian cathode processing facilities shapes both input cost floors and platform pricing power for non-Chinese airframe integrators. Battery cell exclusivity agreements lock in production slots ahead of automotive demand, compressing margin flexibility for operators without long-term offtake security.
Pricing Analysis
Certification level creates the primary spread between deployable and development-stage platforms. Three-tier pricing structure across FAA Part 135-certificated, EASA SC-VTOL-validated, and pre-certification prototypes separates premium operator partnerships from speculative manufacturing slots. Cost compression in battery-electric platforms intensifies as silicon-anode lithium-ion cell demand outpaces supply expansion. Logistics companies exhibit highest price sensitivity through volume contract negotiations, while emergency services procurement cooperatives absorb premium pricing for guaranteed utilization rates.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo port corridors constrain cathode active material flow to European and North American pack assembly facilities. Battery supply chains draw from China's Hunan and Fujian provinces, South Korea's cathode manufacturing clusters, and Japan's separator film production. Lithium carbonate, nickel sulfate, and cobalt hydroxide dependencies create single-source vulnerability through concentrated refining capacity. Distribution runs through airframe OEM direct sales to Part 135 operators and logistics fleet managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified pilot supply gaps and vertiport infrastructure bottlenecks create asset-light entry opportunities for stakeholders with regulatory navigation capabilities. The market rewards parties who can compress certification timelines or secure municipal bond financing for rapid-charging electrical draw facilities.
For Market Incumbents: Fortify battery cell offtake agreements with silicon-anode lithium-ion manufacturers to lock production slots against automotive demand absorption. Expand vertiport network partnerships in Dallas-Fort Worth and Los Angeles metropolitan clusters to secure route monopolies before competitor platform certification. Defensive positioning requires preemptive municipal infrastructure commitments that raise rival entry costs. For New Entrants and Emerging Players: Differentiate on hydrogen fuel cell range extension for inter-city corridors that battery-electric platforms cannot serve. Target medical transportation procurement cooperatives across Florida, Georgia, and Tennessee where premium pricing justifies higher platform acquisition costs. Go-to-market execution should anchor on guaranteed annual flight-hour minimums through regional hospital network exclusivity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Part 135-certificated operators with municipal vertiport access agreements. Long-term viability hinges on regulatory sandbox operational data advantages that accelerate FAA and EASA validation timelines. Acquisition focus should center on airframe developers with EASA SC-VTOL framework progress and Middle Eastern trial presence. The inflection signal to monitor is convergence between FAA Part 135 and EASA SC-VTOL certification timelines that would eliminate stranded platform risk.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Cell Offtake Agreement | Locks silicon-anode lithium-ion production slots ahead of automotive demand absorption. |
| Vertiport Network Partnership | Secures exclusive route monopolies through municipal infrastructure commitments in Dallas-Fort Worth. |
| Regulatory Sandbox Entry | Generates revenue-producing flight hours in Dubai that accelerate FAA Part 135 validation timelines. |
| Emergency Services Procurement Alliance | Consolidates purchasing authority through multi-year exclusivity with guaranteed flight-hour minimums. |
| Hydrogen Fuel Cell Range Extension | Opens inter-city corridors beyond battery-electric limits without vertiport electrical upgrades. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with FAA certification leads, EASA SC-VTOL framework managers, vertiport infrastructure planners, battery cell procurement directors, and Part 135 operator executives. Secondary validation drew from FAA type certification filings, EASA SC-VTOL documentation, municipal bond prospectuses for vertiport construction, and customs data on cathode active material trade flows. Bottom-up platform deployment forecasts were triangulated against top-down urban congestion pricing policy impact assessments.
Across the analysis window, volume and value outputs reflect segmented modeling across vehicle architecture, propulsion technology, operational application, and regulatory jurisdiction. CAGR derivation incorporated battery energy density improvement curves, vertiport construction cost trajectories, and pilot training program scaling assumptions. Forecast inputs included silicon-anode lithium-ion cell production capacity expansion schedules and hydrogen fuel cell stack cost reduction pathways.
Forecasts assume regulatory continuity in FAA Part 135 and EASA SC-VTOL frameworks; material policy shifts would require re-modeling. Specific risks that could revise projections include lithium-ion export licensing friction from Chinese customs authorities and municipal bond financing competition with legacy transit priorities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
Airborne Pods Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Hang Glider Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Flying Motorbikes Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Flying Taxi Market
Air Mobility
Air Transport USM Market