
 Microsurgery Robot Market | 2026-2036
Microsurgery Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Microsurgery Robot Market Analysis
The trained microsurgery specialist labor pool is collapsing across OECD health systems, forcing hospitals to adopt automation that compensates for declining human dexterity reserves. Intuitive Surgical leverages two decades of da Vinci platform refinement to dominate soft-tissue robotic procedures. Medtronic anchors its position through the Hugo RAS system, competing aggressively on modular architecture and open console design. Stryker Corporation sustains orthopedic robotics leadership by integrating Mako SmartRobotics with pre-operative planning software.
A microsurgery robot is a precision electromechanical system combining sub-millimeter manipulators, haptic feedback interfaces, and stereoscopic visualization to execute surgical interventions beyond unaided human physiological limits. These systems typically operate at motion scaling ratios of 3:1 to 5:1 with tremor filtration below 6 Hz, enabling suture placement in vessels under 0.5 mm diameter. Robotic surgical systems command the dominant value share as capital-intensive platforms generate recurring instrument and accessory revenue streams. Image-guided technology is displacing traditional robot-assisted configurations in neurosurgery applications where real-time navigation fuses pre-operative MRI with intra-operative positioning data.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development roadmaps by mandating clinical evidence thresholds and post-market surveillance protocols. The EU AI Act introduces additional conformity obligations for software components that incorporate machine learning-based surgical planning algorithms. Stakeholders must monitor how reimbursement parity between robotic and conventional procedures evolves under CMS and national health service frameworks.
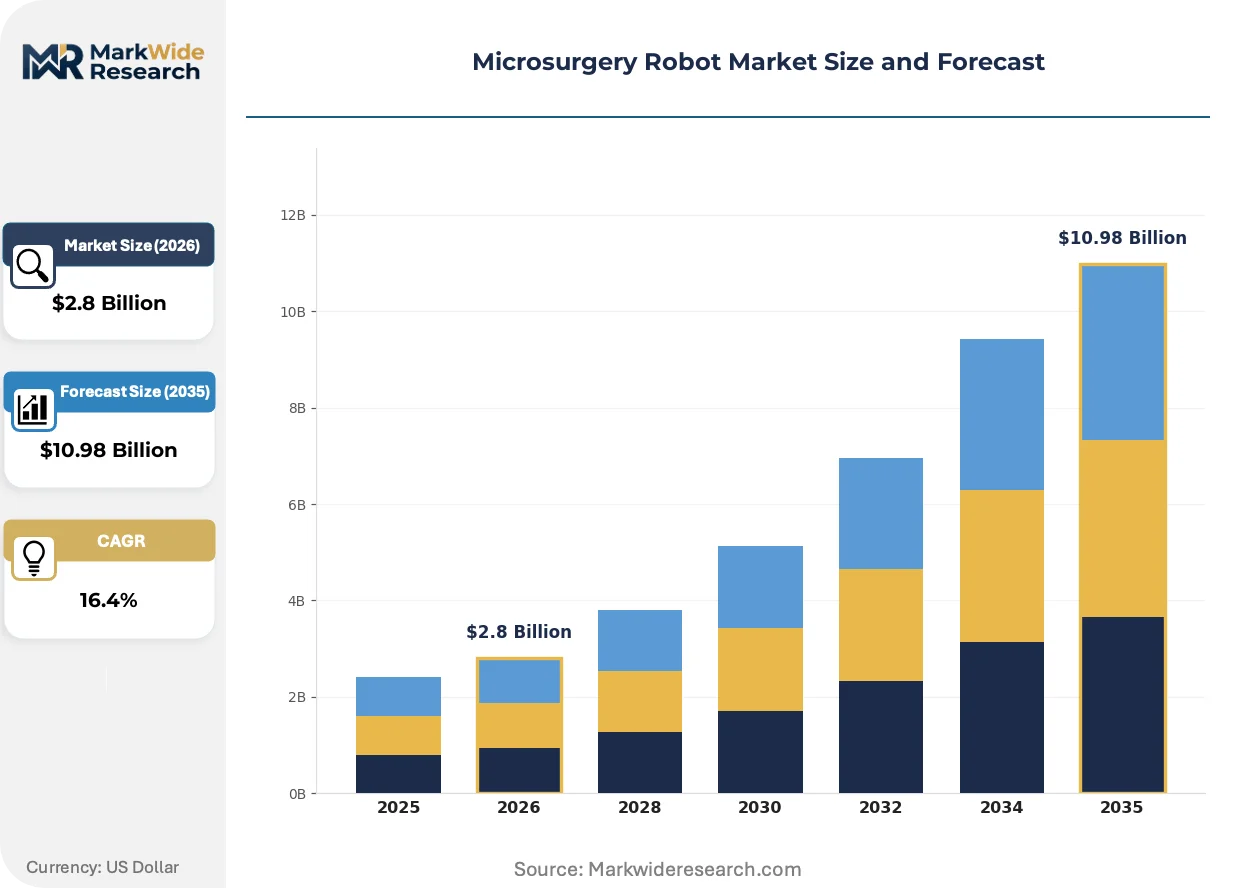
Market Dynamics
The microsurgery robot market is restructuring around the collapse of trained specialist labor pools across OECD health systems, forcing hospitals to deploy automation that compensates for diminishing human dexterity reserves.
Growth Catalysts
- EU Medical Device Regulation streamlining:The MDR's consolidated conformity assessment pathways are accelerating CE marking timelines for Class II surgical robotics, reducing regulatory friction for mid-tier manufacturers entering the European market.
- Academic medical center procurement:University-affiliated hospital systems in Germany, Japan, and the United States are anchoring early adoption curves through multi-year capital equipment leasing programs that bundle training and maintenance.
- Image-guided technology fusion:Real-time navigation systems that fuse pre-operative MRI with intra-operative positioning data are expanding addressable procedure volumes in neurosurgery beyond what traditional robot-assisted configurations could serve.
Market Restraints
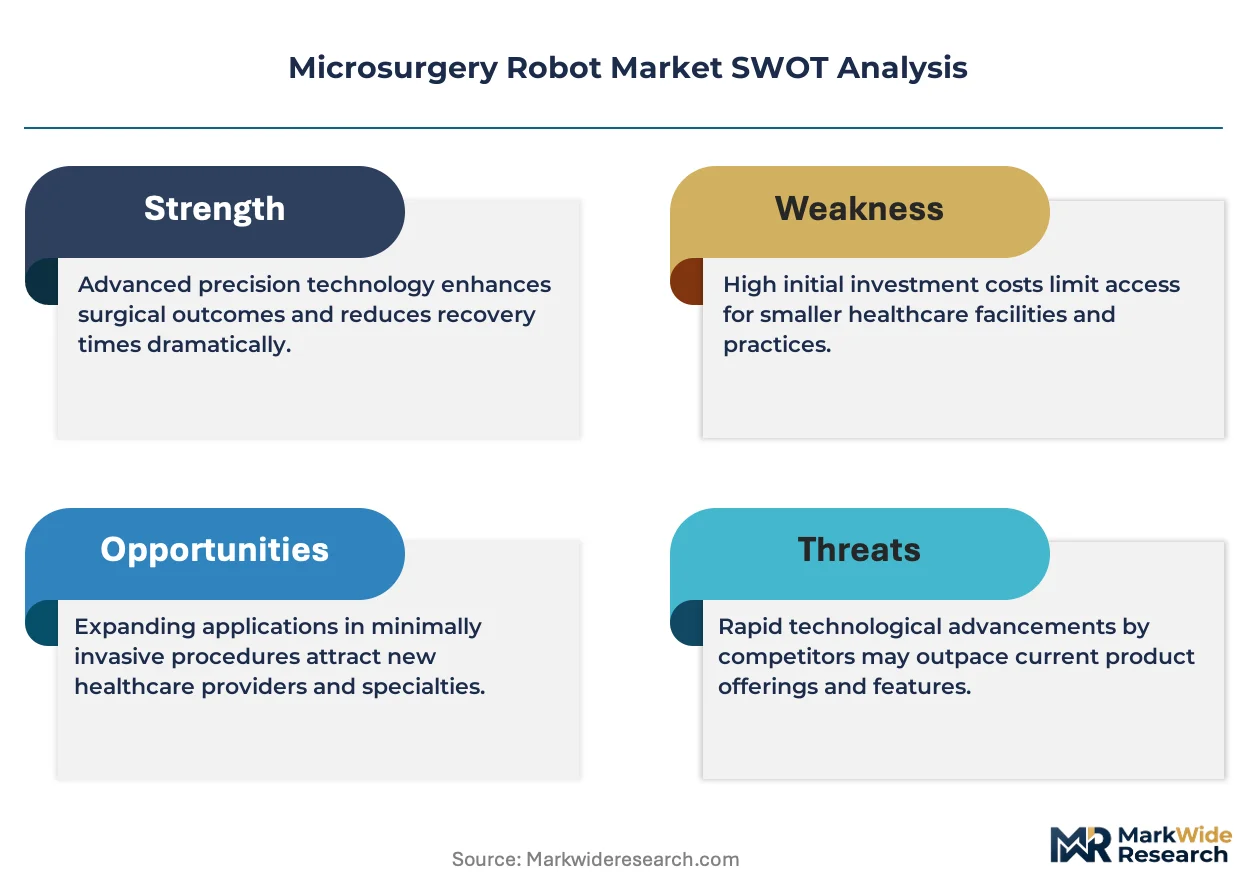
- Capital intensity barrier:Robotic surgical platforms require upfront equipment investments exceeding $2 million per installation, constraining penetration to tier-one hospital systems and excluding community surgical centers.
- Instrument supply concentration:Proprietary consumable ecosystems lock purchasers into single-vendor instrument supply chains, creating switching costs that dampen competitive price pressure.
- Reimbursement parity gaps:CMS and national health service frameworks have not established consistent payment equivalence between robotic and conventional microsurgical procedures, creating revenue uncertainty for adopters.
Strategic Opportunities
- Modular architecture expansion:Open-console designs and componentized robotic systems enable hospitals to scale functionality incrementally rather than committing to monolithic platform purchases.
- EU AI Act compliance services:Software components incorporating machine learning-based surgical planning algorithms create adjacent revenue streams for conformity assessment and post-market surveillance consulting.
- Orthopedic procedure migration:Pre-operative planning software integration with robotic platforms is opening microsurgical precision applications in joint reconstruction and spine procedures previously served by conventional navigation.
Industry Challenges
- Specialist training pipeline collapse:The declining population of microsurgery fellowship graduates is forcing manufacturers to absorb simulator-based credentialing costs that hospitals previously handled.
- Post-market surveillance burden:FDA 510(k) clearance holders face expanded adverse event reporting requirements and periodic safety updates that strain regulatory affairs staffing.
- Legacy system integration friction:Robotic platforms must interface with hospital information systems, imaging archives, and scheduling software through non-standard APIs that prolong implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microsurgery Robot Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgical Systems, Instruments, Accessories, Software End User: Hospitals, Clinics, Ambulatory Surgical Centers, Educational Institutes Application: Neurosurgery, Orthopedic Surgery, Cardiothoracic Surgery, Urology Technology: Laser-Assisted, Endoscopic, Traditional Robot-Assisted, Image-Guided |
| Companies Covered | Intuitive Surgical, Medtronic, Stryker Corporation, Zimmer Biomet, Medical Micro Instruments, MicroSure, Asensus Surgical, Preceyes B.V., Smith+Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microsurgery Robot Market Emerging Trajectories
Haptic feedback interfaces and stereoscopic visualization are converging to extend physiological limits, while regulatory frameworks on both sides of the Atlantic impose new conformity obligations on software-intensive surgical systems.
Sub-millimeter manipulator architectures with motion scaling ratios of 3:1 to 5:1 and tremor filtration below 6 Hz are decomposing the traditional trade-off between precision and accessibility. Academic medical centers in Germany and Japan are deploying these platforms for suture placement in vessels under 0.5 mm diameter. The technology is decomposing the historical concentration of complex microsurgical procedures within a handful of tertiary referral centers.
The EU AI Act introduces additional conformity obligations for machine learning-based surgical planning algorithms, requiring notified body involvement for software updates that modify clinical performance. Manufacturers must now maintain technical documentation and risk management systems that span both hardware and algorithmic components. Neurosurgery applications face the steepest compliance burden due to the critical nature of real-time navigation decisions.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, negotiating simulator training and preventive maintenance through separate competitive tenders. This behavior is compressing vendor margins on recurring revenue streams that previously subsidized platform pricing. The United States exhibits the most aggressive unbundling, driven by IDN consolidation and centralized supply chain governance.
Microsurgery Robot Market Segmentation
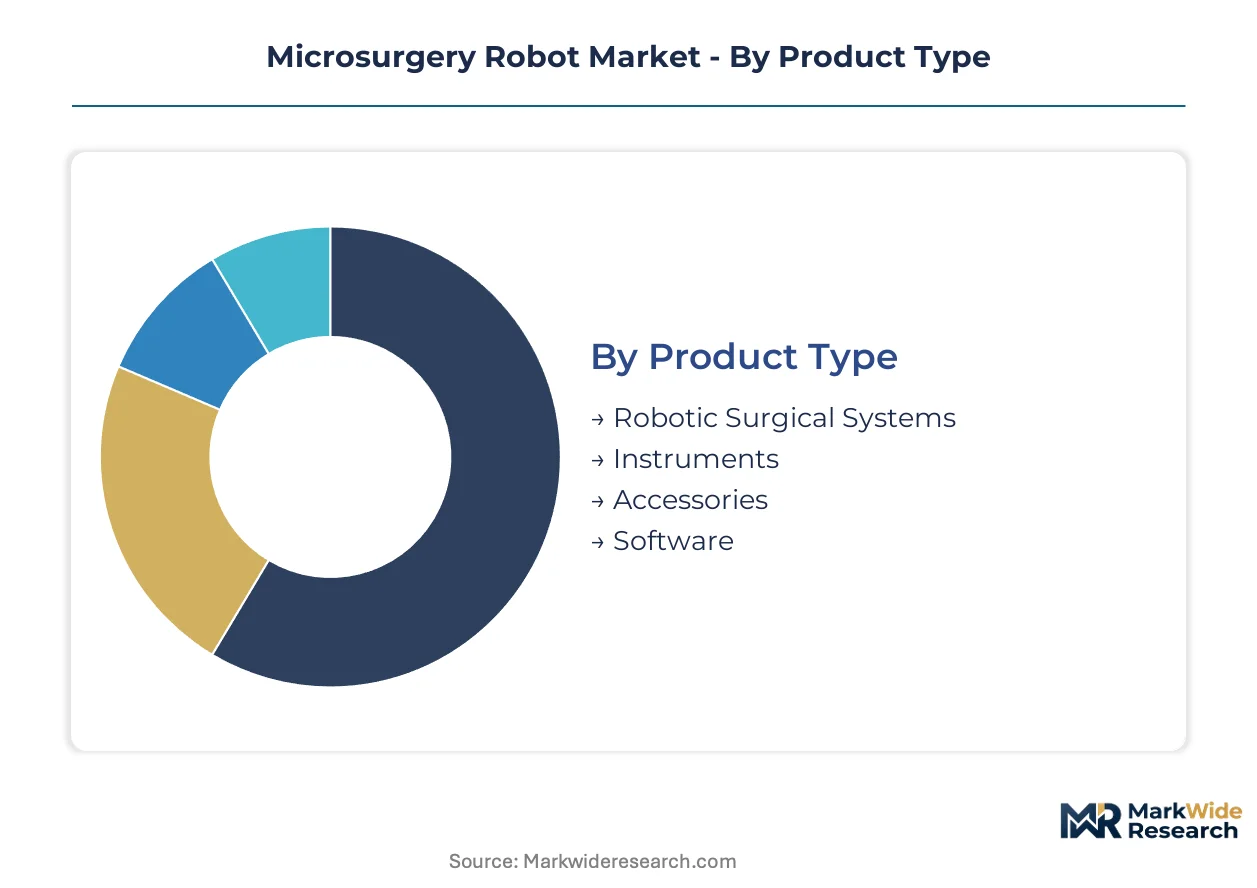
Microsurgery robot procurement patterns diverge sharply across product configurations and clinical settings. Segmentation reveals which system architectures command capital budgets versus which face displacement from emerging navigation technologies.
Product Type:
Robotic Surgical Systems confront the most acute substitution pressure from modular platforms that unbundle console, manipulator, and visualization components.
- Robotic Surgical Systems:Capital-intensive platforms integrating manipulator arms, surgeon consoles, and vision towers generate recurring instrument revenue through proprietary ecosystems. Hospital systems in Germany and Japan anchor procurement through bundled leasing programs that fold training and preventive maintenance into multi-year contracts.
- Instruments:Single-use and limited-reuse end-effectors—needle drivers, forceps, scissors—lock purchasers into vendor-specific supply chains with switching costs exceeding $500,000 for instrument inventory replacement. FDA 510(k) clearance requirements for instrument modifications create regulatory friction that protects incumbent positions.
- Accessories:Drapes, cannulas, and trocars represent lower-margin consumables where procurement departments increasingly unbundle purchases from system contracts.
- Software:Surgical planning and intra-operative navigation algorithms face new EU AI Act conformity obligations that elevate development costs for machine learning-based components.
Robotic Surgical Systems retain volume leadership; Software holds the steepest expansion curve.
End User:
Capital intensity creates sharp tiering between institutions that can absorb $2 million platform investments versus those locked out by budget constraints.
- Hospitals:Academic medical centers in the United States, Germany, and Japan dominate installed base concentration. University-affiliated systems leverage research funding to justify early adoption of sub-millimeter precision platforms for neurosurgery applications.
- Clinics:Community-based surgical facilities face exclusion from robotic microsurgery due to insufficient case volumes to amortize equipment costs. Leasing arrangements and shared-service models are emerging in metropolitan clusters.
- Ambulatory Surgical Centers:Outpatient facilities concentrate on orthopedic procedures where pre-operative planning software integration with robotic platforms enables same-day discharge protocols.
- Educational Institutes:Fellowship programs absorb simulator-based credentialing costs as manufacturer training partnerships replace hospital-funded education pipelines.
Hospitals command installed base dominance; Ambulatory Surgical Centers are climbing the fastest as procedure migration accelerates.
Application:
Image-guided technology fusion is redrawing competitive boundaries between traditional robot-assisted configurations and real-time navigation systems.
- Neurosurgery:Real-time navigation fusing pre-operative MRI with intra-operative positioning data is displacing legacy robot-assisted setups. The EU AI Act imposes the steepest compliance burden here due to criticality of algorithmic decisions.
- Orthopedic Surgery:Pre-operative planning software integration with robotic platforms opens microsurgical precision applications in joint reconstruction. Stryker's Mako SmartRobotics exemplifies this convergence.
- Cardiothoracic Surgery:Closed-chest procedures demand motion scaling ratios of 5:1 with tremor filtration below 6 Hz for coronary anastomosis in vessels under 1 mm diameter.
- Urology:Prostatectomy and kidney procedures established early clinical evidence bases that support reimbursement parity arguments with CMS.
Neurosurgery leads technology displacement activity; Orthopedic Surgery gains share fastest through planning software integration.
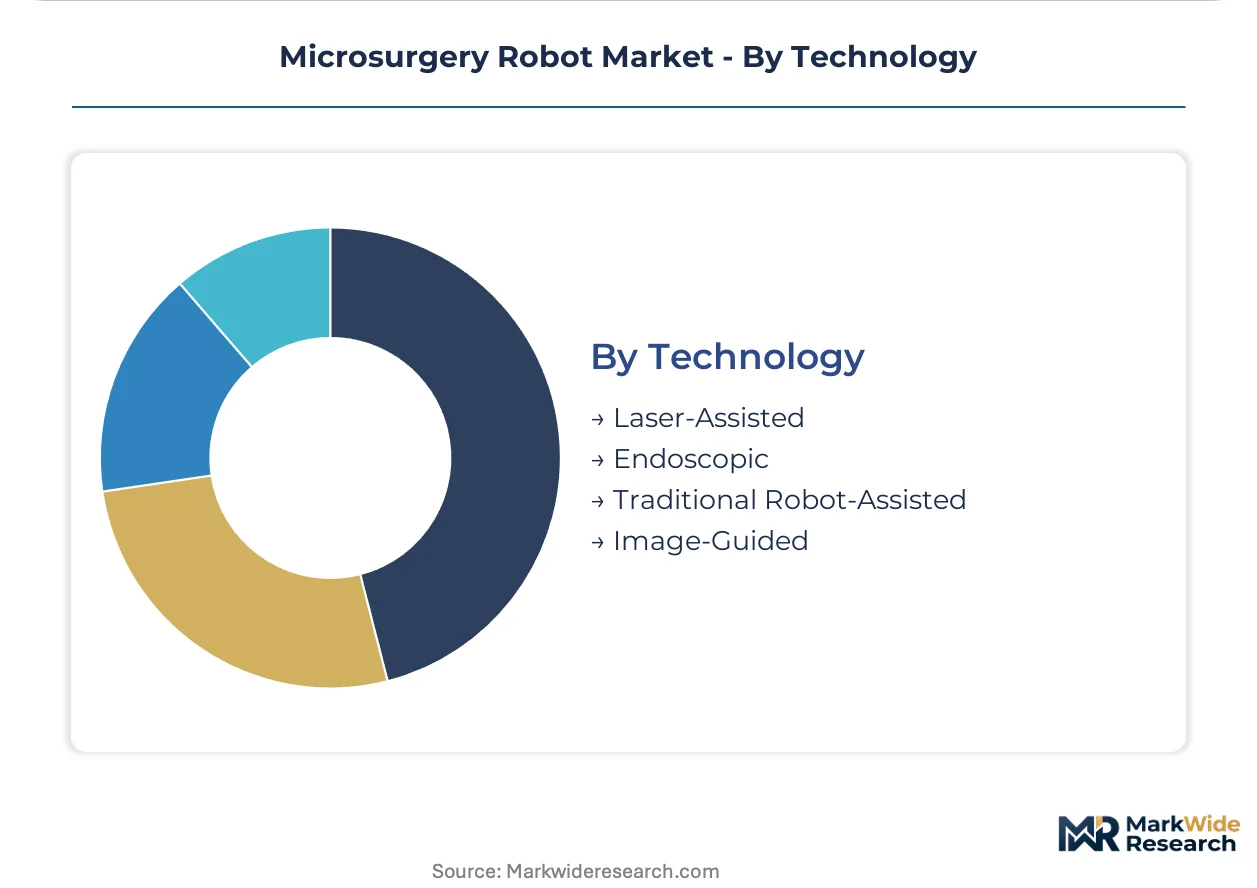
Technology:
Regulatory pathway efficiency varies dramatically across technology categories, with newer modalities facing elongated CE marking timelines under MDR consolidation.
- Image-Guided:Real-time navigation systems are expanding addressable procedure volumes beyond traditional robot-assisted limits. FDA and CE marking pathways for Class II devices are streamlining clearance for manufacturers incorporating pre-operative MRI fusion.
- Traditional Robot-Assisted:Two decades of da Vinci platform refinement have established clinical evidence repositories that defend reimbursement positions. Intuitive Surgical dominates soft-tissue applications through this modality.
- Laser-Assisted:Precision cutting and cauterization in ophthalmic and dermatologic microsurgery applications where thermal damage zones must stay below 50 microns.
- Endoscopic:Minimally invasive visualization platforms face margin compression as hospitals unbundle after-sales service contracts from capital purchases.
Traditional Robot-Assisted retains installed base dominance; Image-Guided technology posts the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the dominant geography, while academic medical centers in Germany and Japan accelerate procurement through bundled leasing structures that fold training into multi-year contracts.
United States
Academic medical centers in Boston and Stanford anchor early adoption curves for neurosurgery applications. CMS reimbursement parity debates create revenue uncertainty for hospital systems contemplating capital investments. The Cleveland Clinic and Mayo Clinic anchor multi-site deployment networks for sub-millimeter precision platforms.
Germany
University-affiliated hospital systems in Munich and Heidelberg drive procurement through research funding justification. The EU Medical Device Regulation streamlines CE marking timelines for Class II surgical robotics entering the European market. The Rhine-Main cluster concentrates manufacturer regional headquarters and training infrastructure.
Japan
Metropolitan hospital networks in Tokyo and Osaka absorb simulator-based credentialing costs as fellowship programs decline. PMDA regulatory pathways align with FDA precedent to accelerate clearance for motion-scaling platforms. The Kansai region anchors orthopedic robotics adoption through integrated pre-operative planning software.
United Kingdom
NHS England procurement frameworks concentrate demand within designated tertiary referral centers. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance protocols that strain regulatory affairs staffing. The Oxford-Cambridge-London triangle hosts early clinical validation studies for image-guided technology fusion.
Switzerland
Swissmedic maintains stringent conformity assessment timelines that filter mid-tier manufacturers from premium hospital procurement lists. Basel and Zurich anchor robotics research partnerships between university hospitals and precision engineering suppliers. The country's reimbursement framework favors evidence-based technology adoption over early speculative deployment.
Microsurgery Robot Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the microsurgery robot market. The upper tier commands proprietary consumable ecosystems that lock purchasers into single-vendor instrument supply chains. Mid-tier manufacturers compete on modular architecture and open-console designs that enable incremental scaling. Competitive moves center on simulator-based training partnerships and unbundled after-sales service contracts.
Within the integrated platform tier, Intuitive Surgical and Medtronic exemplify contrasting strategic positions. Intuitive Surgical anchors soft-tissue applications through two decades of platform refinement. Medtronic occupies a position emphasizing modular architecture and open console design. Stryker Corporation sits within the orthopedic specialization vector, integrating pre-operative planning software with precision robotics.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Medtronic |
| Stryker Corporation |
| Zimmer Biomet |
| Medical Micro Instruments |
| MicroSure |
| Asensus Surgical |
| Preceyes B.V. |
| Smith+Nephew |
| Others |
Supply Flow & Price Mechanics
Multi-year capital equipment leasing programs lock in both platform access and predictable cost structures for hospital systems, bundling training and preventive maintenance into contracted price visibility that shields adopters from spot-market volatility in consumable supply.
Pricing Analysis
Price spreads between the United States and Germany exceed thirty percent for equivalent platform configurations, reflecting differential after-sales bundling norms and unbundling pressures from IDN consolidation. Three-tier pricing structure across premium, standard, and economy levels stratifies by motion precision grade and FDA clearance tier, with academic medical centers absorbing premium tiers while community hospitals face exclusion. Cost compression in instrument consumables is intensifying because procurement departments now tender simulator training separately from platform purchases. Ambulatory surgical centers exhibit the highest price sensitivity due to case-volume constraints, whereas university-affiliated systems in Japan demonstrate the lowest.
Supply Chain Analysis
Germany and Switzerland anchor precision actuator and haptic sensor fabrication, while Japan concentrates stereoscopic visualization component manufacturing. The supply chain draws from rare earth magnets for manipulator motors, sapphire optical elements for endoscopes, and medical-grade alloys for instrument fabrication. Single-source vulnerability concentrates in sub-millimeter encoder production, where two German suppliers dominate global capacity. Distribution runs through manufacturer-direct sales organizations for capital platforms, with instrument consumables flowing through GPO contracts and regional medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microsurgery robot market sits in early-cycle recovery, justified by the resumption of deferred capital equipment procurement as hospital systems rebuild balance sheets post-pandemic.
For Market Incumbents: Secure proprietary instrument ecosystems through exclusive supply agreements with precision component manufacturers, insulating recurring revenue from unbundling pressures. Expand simulator-based training partnerships with fellowship programs to offset the collapse of hospital-funded education pipelines. Image-guided navigation platforms pose the most acute substitution threat to traditional robot-assisted configurations. For New Entrants and Emerging Players: Lead with modular architecture offerings targeting mid-tier hospital systems in Germany and Japan that lack capital for monolithic platform commitments. Orthopedic procedure applications present the most penetrable white-space, where pre-operative planning software integration remains incomplete. A software-first go-to-market angle—selling navigation algorithms before hardware—reduces upfront customer acquisition friction. For Investors and Strategic Acquirers: Specialist firms with EU AI Act compliance infrastructure and notified body relationships command scarcity premia in an environment of elongated software clearance timelines. Long-term viability hinges on reimbursement parity achievement under CMS and national health service frameworks. Watch for CMS technology add-on payment decisions as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR consolidation accelerates timelines for Class II surgical robotics entering European markets. |
| Hospital System Partnership | Bundled leasing programs with academic medical centers in Germany anchor early adoption curves. |
| Software Companion Development | Machine learning-based surgical planning algorithms trigger EU AI Act conformity obligations. |
| Reimbursement Strategy | CMS payment parity arguments leverage urology procedure evidence bases for expansion. |
| FDA Submission | 510(k) clearance requirements mandate clinical evidence thresholds for instrument modifications. |
Methodological Framework
The analysis maps robotic surgical systems, instruments, accessories, and software components, each validated through conversations with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers. Primary interview findings triangulate against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up installed base estimates reconcile with top-down capital equipment spending projections.
Consistency checks validate volume and value outputs against external benchmarks across the analysis window. The forecast framework models product type, end user tier, application specialty, and technology modality dimensions. CAGRs derive from procedure volume elasticity to platform penetration rates, incorporating simulator training capacity constraints and fellowship program graduation trends as medical device-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement parity or accelerated EU AI Act implementation timelines would require recalibration. Forecasts reflect assumptions about regulatory pathway efficiency and hospital capital budget recovery trajectories. Recalibration cycles align with material shifts in CMS technology payment decisions and MDR notified body capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Handheld Robotics Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Robot Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Malaysia Robotics Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market