
 China Industrial Robots Market | 2026-2036
China Industrial Robots Market Size, Share, and Industry Trends Forecast 2026-2036
China Industrial Robots Market Insights
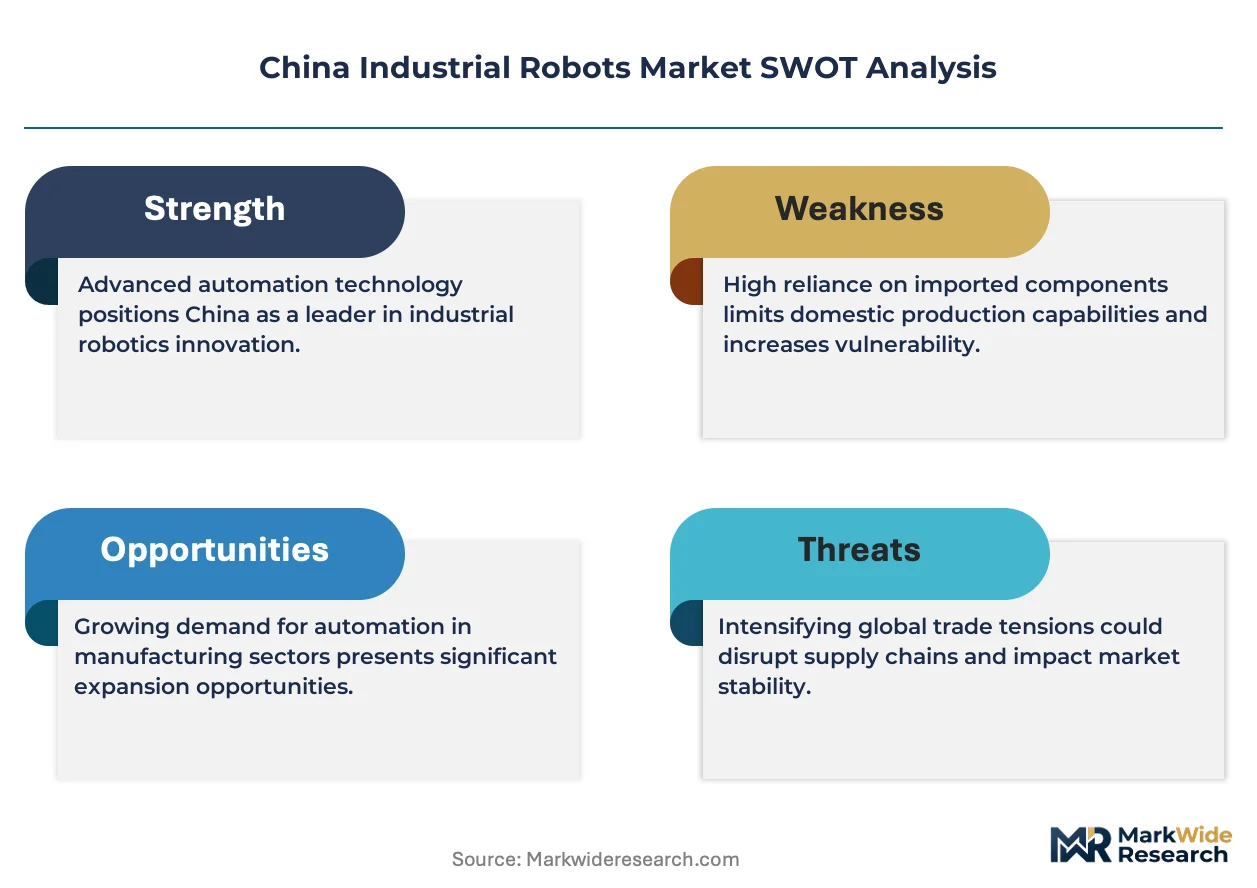
The capability gap between capital-heavy system integrators and component-limited assemblers is collapsing as domestic supply chains mature. Estun Automation leverages in-house servo motor production to control costs across its articulated robot portfolio. SIASUN Robot & Automation anchors its position through deep integration with automotive welding lines in northeastern China. EFORT Intelligent Equipment differentiates via specialized SCARA deployment in electronics packaging.
China industrial robots encompass programmable multi-axis machines with payload capacities from sub-kilogram precision units to over one-ton automotive body handlers, typically incorporating harmonic drives, servo motors, and real-time controllers for repetitive manufacturing tasks. Articulated robots dominate volume given their flexibility in automotive welding and material handling, while collaborative robots represent the fastest-expanding category as SMEs adopt force-limited designs for mixed human-machine assembly. AI-driven robotics and sensor integration technologies are capturing margin pools through predictive maintenance and adaptive path planning capabilities that reduce downtime in electronics and pharmaceuticals applications.
MIIT's Made in China 2025 framework and GB standard certification requirements from SAMR shape product design mandates, forcing domestic vendors to achieve functional safety ratings previously reserved for imported systems. NMPA medical-device-adjacent regulations increasingly influence pharmaceutical robot deployments where contamination control protocols apply. Stakeholders must monitor how dual carbon goals from MEE reshape energy-efficiency benchmarks for factory-floor automation procurement decisions.
Market Dynamics
MIIT's intelligent manufacturing directives are compressing deployment cycles across China's industrial robot base, forcing domestic vendors to match functional safety benchmarks previously held by imported systems while automotive and electronics clusters accelerate replacement timelines.
Growth Catalysts
- MIIT Made in China 2025 Framework:Mandatory intelligent manufacturing targets in automotive and electronics sectors are mandating robot density thresholds that pull articulated units into welding and assembly lines.
- Yangtze River Delta Labor Shortages:Demographic contraction in manufacturing hubs is accelerating capital substitution, with Shanghai and Jiangsu automotive plants expanding robot fleets for body-in-white operations.
- Harmonic Drive Localization:Domestic precision gear production is reducing import dependency for articulated robot joints, cutting lead times from six months to under eight weeks for Guangdong system integrators.
Market Restraints
- Servo Motor Import Concentration:High-performance magnetic materials and precision encoders remain concentrated with Japanese and German suppliers, exposing domestic assemblers to yen and euro volatility.
- GB Standard Certification Friction:SAMR's functional safety validation timelines extend eighteen to twenty-four months, delaying revenue recognition for new articulated robot platforms.
- Collaborative Robot Price Compression:Force-limited designs from European vendors are undercutting domestic SCARA pricing in SME electronics packaging, squeezing margin pools for mid-tier producers.
Strategic Opportunities
- Pharmaceutical Cleanroom Deployment:NMPA contamination control protocols are opening precision SCARA and delta robot demand for aseptic filling and packaging operations in Jiangsu biologics clusters.
- AI-Driven Predictive Maintenance:Sensor fusion and edge computing convergence is enabling uptime guarantees that displace traditional break-fix service contracts in automotive welding lines.
- Sichuan and Chongqing Inland Expansion:Electronics manufacturing relocation from coastal provinces is creating greenfield robot deployment opportunities for lithium battery and display panel assembly.
Industry Challenges
- Multi-Axis Programming Talent Scarcity:Shortages of certified robot technicians and PLC integration specialists are extending commissioning timelines and inflating deployment costs for SME adopters.
- Legacy Equipment Interoperability:Retrofitting twenty-year-old automotive stamping lines with real-time Ethernet and safety-rated controllers requires custom gateway development that fragments project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Industrial Robots Market |
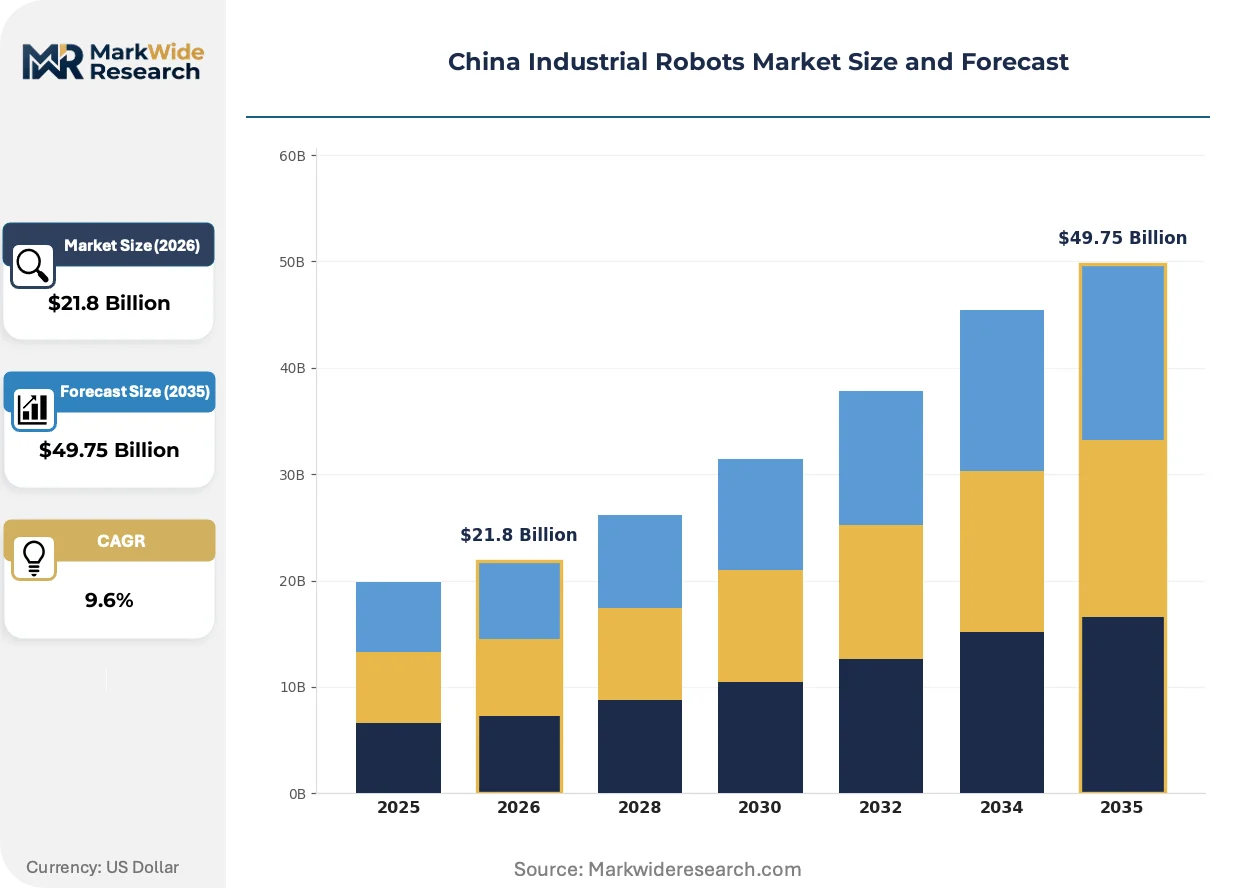
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $49.75 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, SCARA Robots, Carts, Collaborative Robots End User: Automotive, Electronics, Food & Beverage, Pharmaceuticals Technology: AI-Driven Robotics, Sensor Integration, Machine Learning, IoT-Connected Application: Packaging, Assembly, Welding, Material Handling |
| Companies Covered | UBTECH Robotics, HuazhongCNC, SIASUN Robot & Automation, Leader Harmonious Drive Systems, Shanghai STEP Electric, Estun Automation, EFORT Intelligent Equipment, AdTech Intelligent Technology, SZGH Robot, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Industrial Robots Market Trends and Innovations
Adaptive path planning and force-controlled assembly are displacing fixed-sequence programming across China's precision manufacturing base, compressing reprogramming cycles from days to hours while enabling mixed-model production.
Vision-guided bin picking with 3D point cloud processing is displacing dedicated fixture-based loading in electronics assembly, with Shenzhen and Dongguan contract manufacturers adopting the technology for smartphone component handling. The shift is collapsing setup times for product changeovers and reducing capital tied to custom tooling. This capability is displacing fixed-automation investments in high-mix, low-volume environments.
MIIT's GB/T functional safety standards are mandating SIL-2 and PL-d ratings for collaborative robot deployments in automotive and pharmaceutical applications, forcing domestic vendors to redesign control architectures and safety monitoring circuits. The regulation is compressing the price gap between certified domestic units and European imports. Automotive OEMs in northeastern China are responding by consolidating supplier qualification lists to vendors with demonstrated GB compliance.
Electronics contract manufacturers are unbundling robot procurement from system integration services, awarding hardware and programming contracts to separate vendors to capture transparency in component pricing. This fragmentation is pressuring full-service integrators in Guangdong to specialize in either hardware distribution or software customization. The shift is most visible in Shenzhen, where large EMS providers maintain captive engineering teams for robot deployment.
China Industrial Robots Market Segmentation
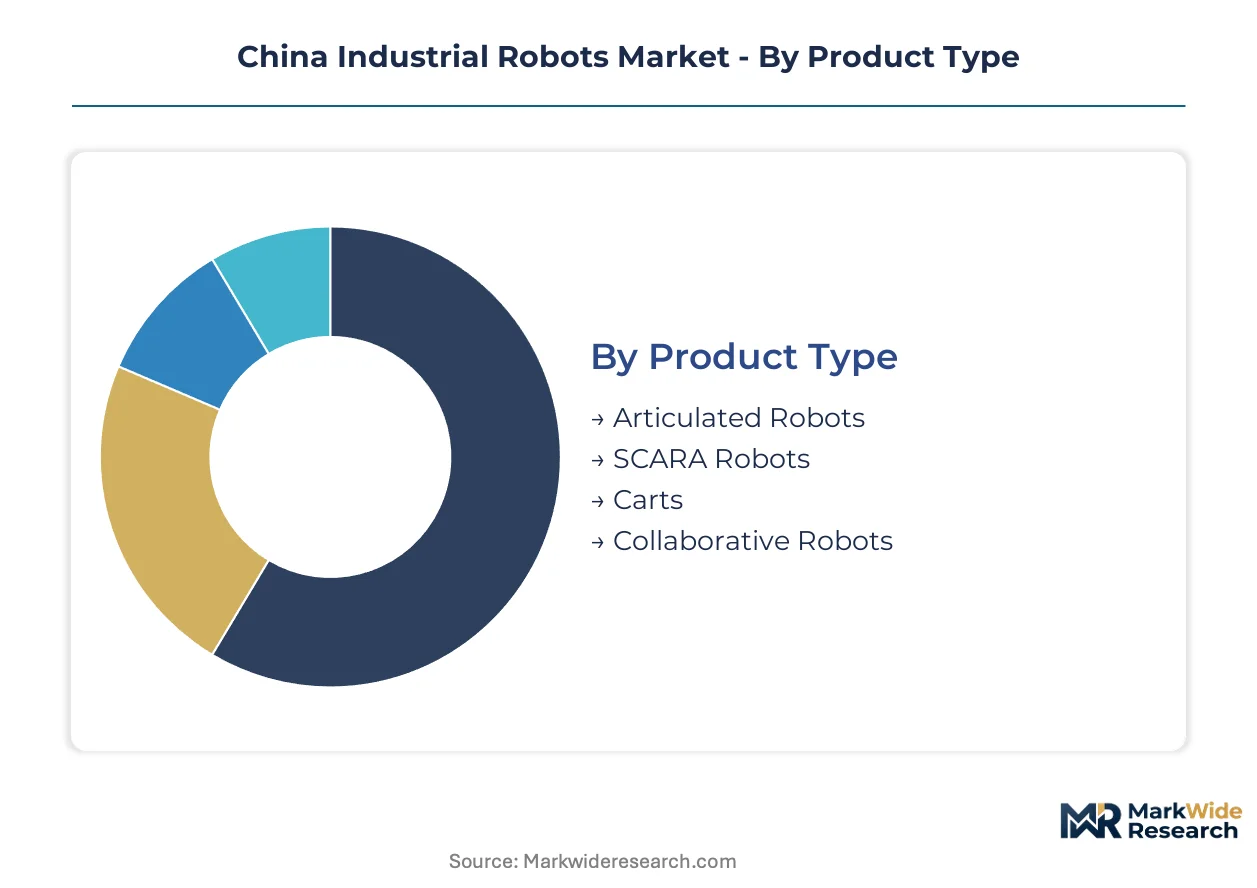
Segmentation in China's industrial robot market reveals how MIIT certification tiers and GB standard compliance reshape procurement patterns across automotive welding lines and electronics assembly floors. Understanding these divides exposes where domestic vendors can displace European and Japanese imports.
Product Type:
MIIT's GB/T functional safety ratings apply differentially across robot architectures, with articulated units facing the strictest SIL-2 mandates while collaborative designs navigate emerging PL-d protocols.
- Articulated Robots:Six-axis configurations with harmonic drive joints dominate automotive body-in-white welding in Shanghai and Jiangsu plants. Yangtze River Delta labor shortages are accelerating fleet expansion for spot welding and sealing operations.
- SCARA Robots:Selective compliance assembly robot arms deliver sub-millimeter repeatability for electronics component placement. Shenzhen and Dongguan contract manufacturers deploy these for smartphone motherboard assembly where speed outweighs flexibility.
- Carts:Automated guided vehicles handle material transport between warehouse and production lines. Electronics clusters in Guangdong favor these for just-in-time component delivery to surface-mount lines.
- Collaborative Robots:Force-limited designs with torque sensors enable mixed human-machine assembly without safety cages. SME packaging operations in Jiangsu biologics clusters are adopting these for batch flexibility.
Articulated robots handle the majority of throughput; collaborative robots are expanding most quickly on share.
End User:
Cost tier differentiation separates capital-intensive automotive deployments from price-sensitive SME electronics adoption.
- Automotive:Body-in-white welding and paint shop automation command the highest payload specifications. Northeastern China OEMs in Shenyang and Changchun anchor demand for heavy-duty articulated fleets.
- Electronics:Precision assembly of smartphones, displays, and lithium battery cells drives SCARA and delta robot procurement. Coastal manufacturing relocation to Sichuan and Chongqing is creating inland greenfield demand.
- Food & Beverage:Washdown-rated robots with IP67 protection handle primary and secondary packaging. NMPA hygiene protocols are tightening stainless steel surface requirements for dairy and beverage lines.
- Pharmaceuticals:Aseptic filling and vial handling in Jiangsu biologics clusters demand ISO 5 cleanroom compatibility. NMPA contamination control regulations are mandating specialized SCARA deployments with validated sterilization cycles.
Automotive absorbs the heaviest capital allocation; pharmaceuticals is climbing the fastest as regulatory compliance tightens.
Technology:
Application maturity separates proven sensor fusion from emerging AI architectures still awaiting GB standard validation.
- AI-Driven Robotics:Machine vision and adaptive path planning enable real-time trajectory adjustment for mixed-model production. Automotive welding lines in Shanghai are piloting these for reduced reprogramming downtime.
- Sensor Integration:Force-torque and proximity sensors deliver collision avoidance and quality feedback. Electronics assembly in Dongguan relies on these for component presence verification.
- Machine Learning:Predictive maintenance algorithms analyze vibration and current signatures to forecast servo motor failures. System integrators in Guangdong are bundling these as uptime guarantees.
- IoT-Connected:Real-time Ethernet and OPC-UA protocols enable centralized fleet monitoring. Dual carbon goals from MEE are pushing energy-consumption tracking as a procurement criterion.
Sensor integration carries the broadest installed base; AI-driven robotics is gaining share fastest as MIIT validates control architectures.
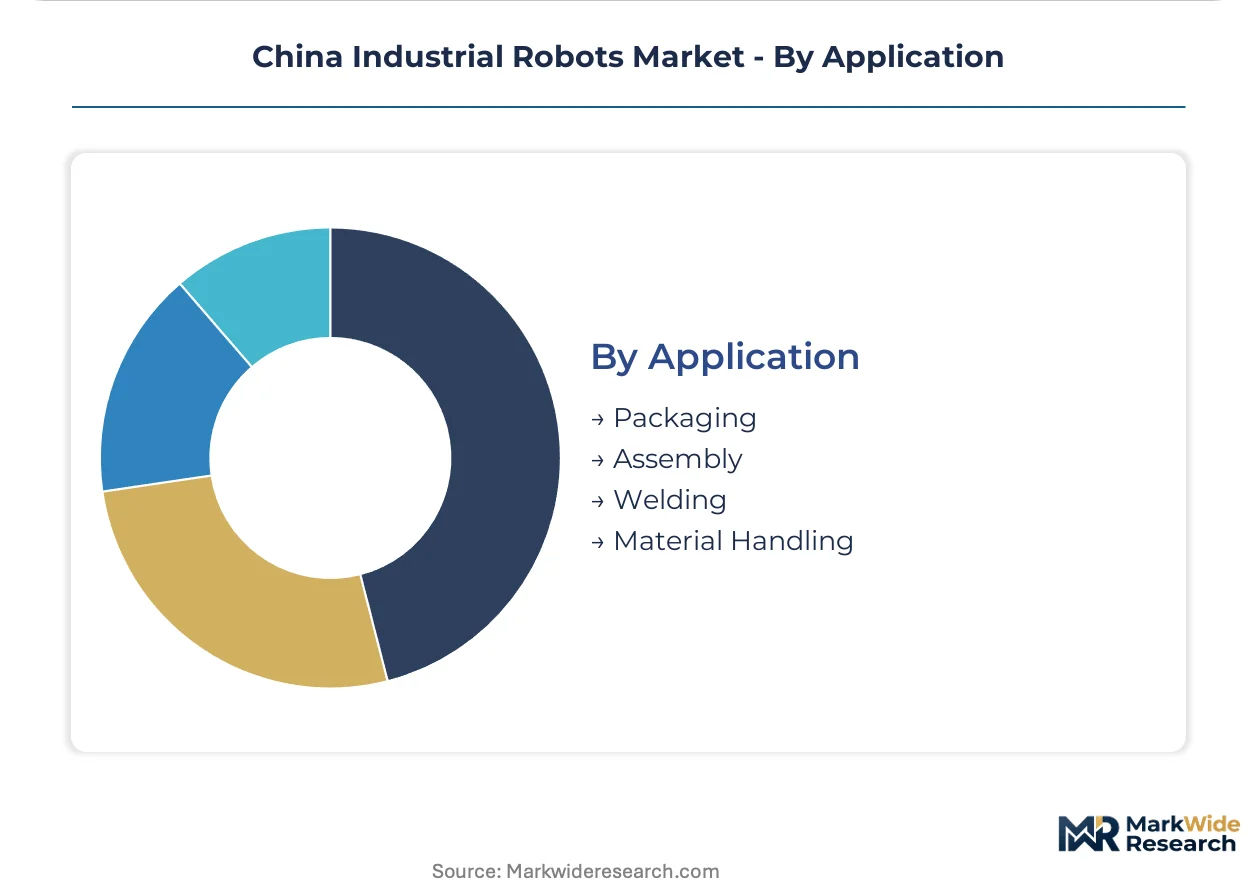
Application:
Volume concentration in material handling contrasts with margin-rich specialized welding requiring certified technician deployment.
- Packaging:End-of-line palletizing and case packing utilize medium-payload articulated arms. Food and beverage plants in Guangdong favor these for throughput consistency.
- Assembly:Component insertion and fastening operations demand precision repeatability. Electronics clusters drive SCARA and collaborative robot adoption here.
- Welding:Arc and spot welding in automotive body shops requires heavy-payload six-axis units with dedicated torch interfaces. Shenyang automotive plants maintain captive welding engineering teams.
- Material Handling:Bin picking, machine tending, and inter-process transport represent the largest deployment volume. 3D vision-guided systems are displacing fixed fixtures in high-mix electronics environments.
Material handling moves the greatest unit volume; welding commands the steepest expansion trajectory as automotive robot density targets tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province commands pricing premiums for precision SCARA units while Sichuan-Chongqing inland markets absorb cost-focused articulated deployments. MIIT's regional industrial policies amplify these divergences through targeted subsidy tiers.
Guangdong Province
Shenzhen and Dongguan electronics clusters drive articulated and SCARA robot procurement for smartphone assembly and lithium battery production. MIIT's intelligent manufacturing directives mandate robot density thresholds in these export-oriented zones. The Pearl River Delta concentration absorbs premium-tier pricing for vision-guided systems.
Jiangsu Province
Automotive body-in-white welding lines in Suzhou and Nanjing anchor demand for heavy-payload six-axis units. SAMR's GB standard certification timelines extend deployment cycles for new articulated platforms. The Yangtze River Delta labor shortage accelerates capital substitution in Shanghai-adjacent plants.
Sichuan and Chongqing
Inland electronics manufacturing relocation creates greenfield demand for medium-payload material handling robots. MEE's dual carbon goals reshape energy-efficiency benchmarks for factory-floor automation procurement. Chengdu and Chongqing display panel assembly clusters favor cost-optimized SCARA configurations.
Shandong Province
Qingdao and Jinan automotive component suppliers deploy collaborative robots for mixed human-machine assembly operations. NMPA medical-device-adjacent regulations increasingly influence pharmaceutical robot deployments in regional biologics clusters. Shandong Peninsula machinery builders source servo-integrated articulated units for captive production lines.
Liaoning Province
Shenyang automotive OEMs maintain captive welding engineering teams for heavy-duty articulated fleets. MIIT's Made in China 2025 framework mandates intelligent manufacturing targets in northeastern China's industrial base. Dalian port logistics drive automated guided vehicle deployment for inter-facility material transport.
China Industrial Robots Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across China's industrial robot base. The market structures around three tiers: capital-heavy system integrators with captive component production, mid-scale assemblers dependent on imported servo motors, and specialized SCARA vendors serving electronics packaging niches. Strategic moves concentrate on backward integration into harmonic drive manufacturing and AI-driven predictive maintenance service bundling.
Among domestic specialists, SIASUN Robot & Automation, Estun Automation, and EFORT Intelligent Equipment occupy distinct positioning archetypes. SIASUN anchors the system integrator tier through deep automotive welding line relationships. Estun exemplifies the backward-integrated model with in-house servo motor production controlling portfolio costs. EFORT sits within the specialization vector for electronics sector SCARA deployment. These three represent how domestic vendors are collapsing the historical capability gap against imported systems.
| Leading Market Players |
|---|
| UBTECH Robotics |
| HuazhongCNC |
| SIASUN Robot & Automation |
| Leader Harmonious Drive Systems |
| Shanghai STEP Electric |
| Estun Automation |
| EFORT Intelligent Equipment |
| AdTech Intelligent Technology |
| SZGH Robot |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Japanese harmonic drive suppliers lock in component access and price visibility for Guangdong system integrators, insulating them from yen volatility while compressing margin flexibility for domestic assemblers locked into spot-market servo motor procurement.
Pricing Analysis
The customization-premium spread separates configured-to-order articulated robots for automotive welding lines from standard SCARA units for electronics assembly. Project-based pricing dominates heavy-payload deployments, while per-unit transactional models prevail in high-volume electronics packaging. Price differentiation hinges on GB standard certification tier and after-sales service bundling. Cost compression in mid-tier SCARA configurations is intensifying because European collaborative robot vendors are undercutting domestic pricing in SME electronics packaging. Contract manufacturers in Shenzhen exhibit the sharpest price sensitivity, while northeastern automotive OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Port congestion on the Shanghai-Ningbo corridor and container availability constraints on the Japan-China trade lane are extending inbound lead times for precision encoders and high-performance magnetic materials. Component supply concentrates in Japan, Germany, and South Korea for servo motors and harmonic drives, while domestic production of robot controllers and structural frames anchors in Jiangsu and Guangdong. Raw material dependencies include rare-earth magnetic materials, precision steel alloys, and semiconductor-grade sensors. Single-source vulnerability for harmonic drive imports from Japanese suppliers exposes domestic assemblers to supply disruption. Distribution runs through captive system integrator networks in automotive and independent electronics distributors in Guangdong.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's industrial robot market sits in early-cycle expansion as MIIT robot density mandates in automotive and electronics manufacturing pull adoption ahead of replacement demand curves.
For Market Incumbents: Fortify backward integration into servo motor and harmonic drive production to offset import dependency exposure from Japanese and German suppliers. Deepen certification investment in GB/T functional safety ratings to defend against European collaborative robot entrants undercutting mid-tier pricing. Channel control through captive system integrator relationships in northeastern automotive clusters provides defensive moats against price erosion. For New Entrants and Emerging Players: Anchor in pharmaceutical cleanroom SCARA deployment in Jiangsu biologics clusters where NMPA contamination control protocols create specialized demand with limited incumbent presence. Target inland electronics manufacturing relocation to Sichuan and Chongqing for greenfield material handling robot opportunities with lower competitive density. A robotics-as-a-service go-to-market angle bypasses upfront capital barriers for SME adopters in electronics packaging. For Investors and Strategic Acquirers: System integrators with demonstrated GB compliance and captive automotive welding line relationships represent the most defensible acquisition target archetype for long-term viability across a 5-10 year industrial automation deepening cycle. Component-limited assemblers without backward integration face margin compression and substitution risk. The signal to watch is MIIT validation timelines for AI-driven control architectures, which would recalibrate competitive positioning between domestic and imported systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Estun Automation's in-house manufacturing reduces cost exposure to yen-denominated imports from Japanese suppliers. |
| GB/T Functional Safety Certification Investment | SAMR's SIL-2 mandates compress the price gap between certified domestic units and European collaborative robot imports. |
| AI-Driven Predictive Maintenance Service Bundling | Sensor fusion uptime guarantees displace traditional break-fix contracts in Shanghai automotive welding lines. |
| Inland Manufacturing Footprint Expansion | Sichuan and Chongqing electronics relocation creates greenfield deployment opportunities for lithium battery assembly. |
| Harmonic Drive Localization Partnership | Domestic precision gear production cuts lead times from Japanese suppliers for Guangdong system integrators. |
Research Methodology
Desk research of MIIT policy directives, SAMR GB standard documentation, and NMPA regulatory filings preceded structured interviews with automotive welding line engineers, electronics contract manufacturing procurement leads, pharmaceutical cleanroom operations managers, and system integrator technical directors. Secondary validation drew from customs trade data for robot component imports, SEC filings of listed automation vendors, and provincial industrial statistics from Guangdong and Jiangsu statistical bureaus. Bottom-up unit deployment estimates triangulated against top-down market size calculations.
Variance decomposition across product type, end-use industry, technology tier, and application mode shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling applied to baseline penetration data. Robot density thresholds mandated by MIIT, labor substitution economics in the Yangtze River Delta, and GB certification timeline assumptions constituted key forecast inputs specific to industrial automation adoption patterns.
Material uncertainties — MIIT policy acceleration or deceleration, yen and euro exchange rate volatility affecting component costs, and NMPA regulatory expansion into additional manufacturing verticals — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and supply chain localization trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Medical Robots Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Automotive Robotic Painting Market