
 North America Collaborative Robots Market | 2026-2036
North America Collaborative Robots Market Size, Share, and Industry Trends Forecast 2026-2036
North America Collaborative Robots Market Analytics
Market Context with Strategic Players
Canada is tilting toward cobot assembly capacity through Ontario-based automation clusters serving cross-border automotive supply chains. KUKA AG leverages its North American engineering footprint to sustain high-payload cobot lines for heavy manufacturing. ABB Ltd. anchors its regional position through integrated force-sensing controllers that dominate material-handling deployments. Universal Robots A/S competes on modularity, offering rapid-reconfiguration arms that appeal to mid-size electronics fabricators.
Technical Definition and Structural Segments
Collaborative robots are force-limited robotic systems designed to operate alongside human workers without fixed safety guarding, typically incorporating torque sensors, speed-monitoring algorithms, and power-and-force-limiting controls that halt motion upon unexpected contact. Their primary commercial purpose centers on flexible automation in batch-production environments where frequent changeovers and mixed human-machine workflows outperform traditional caged industrial robots. Articulated robots occupy the dominant revenue position due to their six-degree-of-freedom dexterity in complex assembly tasks across automotive and aerospace end users. SCARA robots concentrate margin pools in electronics manufacturing, where high-speed planar precision for circuit-board handling commands premium pricing. Dual-arm robots represent the fastest-growing structural category, as synchronized bimanual manipulation expands quality-inspection throughput in pharmaceutical packaging lines.
Regulatory Frame and Forward-Looking Close
The U.S. OSHA technical manual on collaborative systems, the CSA Z434 safety standards in Canada, and the ISO/TS 15066 force-threshold guidelines collectively shape product certification requirements and deployment protocols across North American manufacturing floors. OSHA's emphasis on risk-assessment documentation before cobot integration is forcing integrators to embed safety-planning services into hardware contracts, altering vendor revenue composition. Stakeholders must monitor how pending updates to ISO 10218-2 rewrite speed-separation monitoring thresholds, as these parameters will determine whether existing installed bases require retrofit or replacement.
Market Dynamics
OSHA's updated collaborative robot safety guidelines are forcing manufacturers toward force-limited designs, restructuring procurement criteria and vendor qualification processes across automotive and electronics assembly floors.
Growth Catalysts
- ISO/TS 15066 compliance mandates:The force-threshold guidelines are accelerating retrofit cycles in Michigan and Ohio automotive plants, creating immediate replacement demand for pre-2018 cobot installations.
- Electric vehicle retooling:Tier-one suppliers in the U.S. Great Lakes manufacturing corridor are deploying precision welding cobots to handle battery pack assembly and lightweight aluminum joining.
- Pharmaceutical packaging automation:Dual-arm robots with synchronized bimanual manipulation are expanding quality-inspection throughput in FDA-regulated sterile filling operations.
Market Restraints
- Torque sensor supply concentration:Precision force-sensing components rely heavily on German and Japanese component suppliers, exposing integrators to 14-18 week lead times and currency volatility.
- CSA Z434 certification friction:Canada's variant testing requirements for cross-border automotive deployments add 8-12 weeks to validation timelines, compressing project margins.
- Traditional SCARA substitution:High-speed planar robots retain cost advantages in pure electronics pick-and-place, limiting cobot penetration in circuit-board handling below the premium tier.
Strategic Opportunities
- Mexican nearshoring expansion:Automotive suppliers in Querétaro and Guanajuato lack established cobot integrator networks, creating first-mover service contracts for U.S.-based engineering firms.
- 5G-enabled edge computing convergence:Real-time speed-separation monitoring via low-latency wireless is enabling fenceless deployments in mixed-model assembly previously blocked by cabling constraints.
- IRA clean energy manufacturing credits:Domestic content requirements for battery and solar component production are mandating U.S.-based automation, favoring regional cobot vendors with local assembly capacity.
Industry Challenges
- Safety integrator talent scarcity:Risk-assessment documentation expertise per OSHA technical manual requirements outpaces certified technician supply in the U.S. Midwest and Ontario automation clusters.
- Legacy PLC integration complexity:Cobot controller APIs lack standardization with 1990s-era Allen-Bradley and Siemens shop-floor networks, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Collaborative Robots Market |
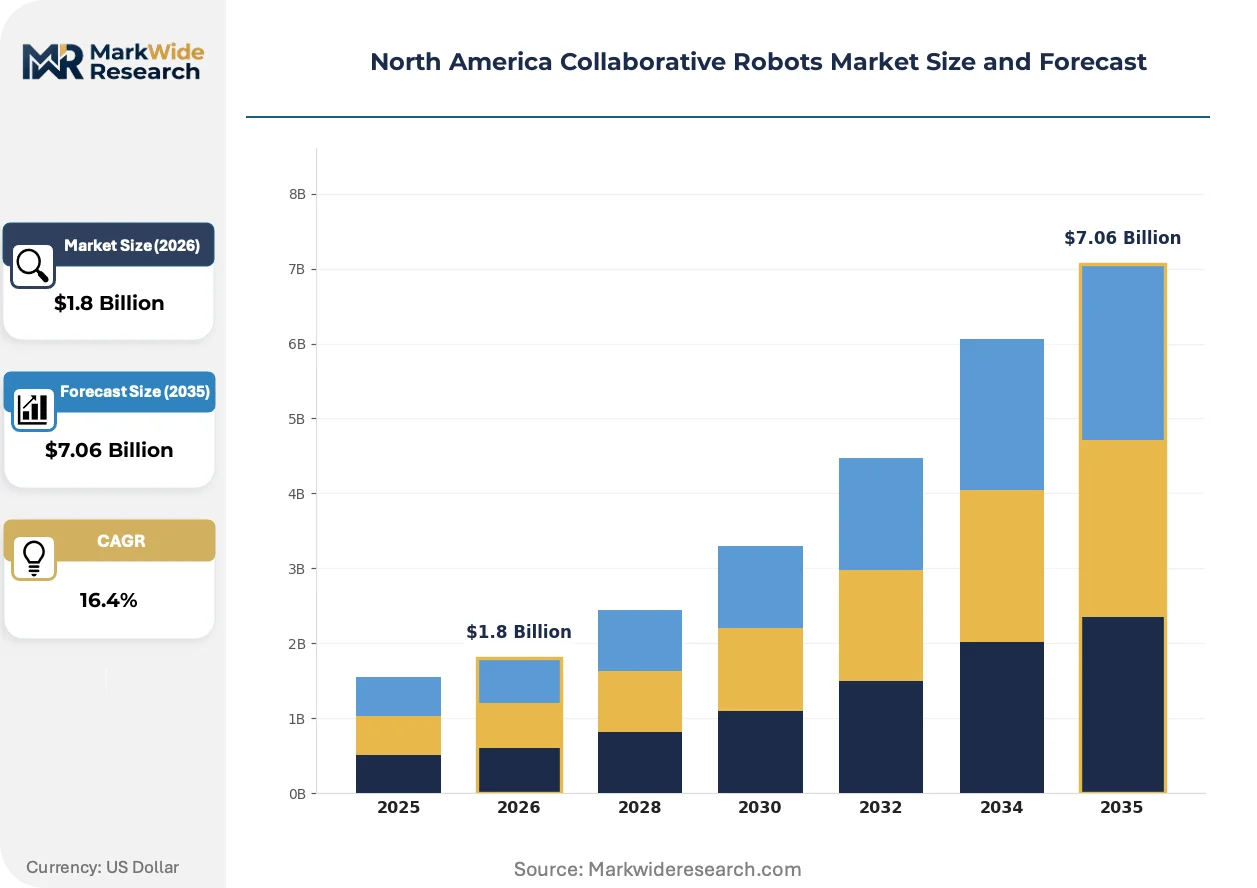
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, SCARA Robots, Cartesian Robots, Dual-Arm Robots End User: Automotive, Electronics, Healthcare, Aerospace Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Assembly, Packaging, Quality Inspection, Material Handling |
| Companies Covered | KUKA AG, Doosan Robotics Inc., ABB Ltd., DENSO Corporation, Techman Robot Inc., Universal Robots A/S, Yaskawa Electric Corporation, AUBO Robotics, FANUC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Collaborative Robots Market Evolving Landscape
Force-sensing hardware and AI-driven motion planning are converging to eliminate the remaining performance gaps between collaborative and traditional industrial robots, collapsing the historical safety-productivity tradeoff that structured buyer segmentation.
Vision-guided tactile feedback systems are collapsing the boundary between human dexterity and robotic repeatability in automotive assembly. Ford and General Motors suppliers in Michigan are deploying these systems for wire harness routing and clip insertion at cycle times matching conventional automation. The technology is collapsing the premium pricing umbrella that protected six-axis articulated robots in complex manipulation tasks.
OSHA's pending updates to speed-separation monitoring thresholds are forcing integrators to embed predictive risk-assessment software into hardware contracts. Tier-one automotive suppliers in Ohio are pre-emptively upgrading installed bases to avoid forced replacement. The regulatory pressure is compressing vendor revenue composition toward recurring safety-service subscriptions.
Buyer procurement patterns are rotating from capital-purchase models toward performance-guaranteed automation-as-a-service contracts. Mid-size electronics fabricators in Ontario and New York State are demanding throughput-based pricing with vendor retention of obsolescence risk. The shift is most visible in contract manufacturers serving Apple and Tesla supply chains, where quarterly volume volatility rewards flexible cost structures.
North America Collaborative Robots Market Segmentation
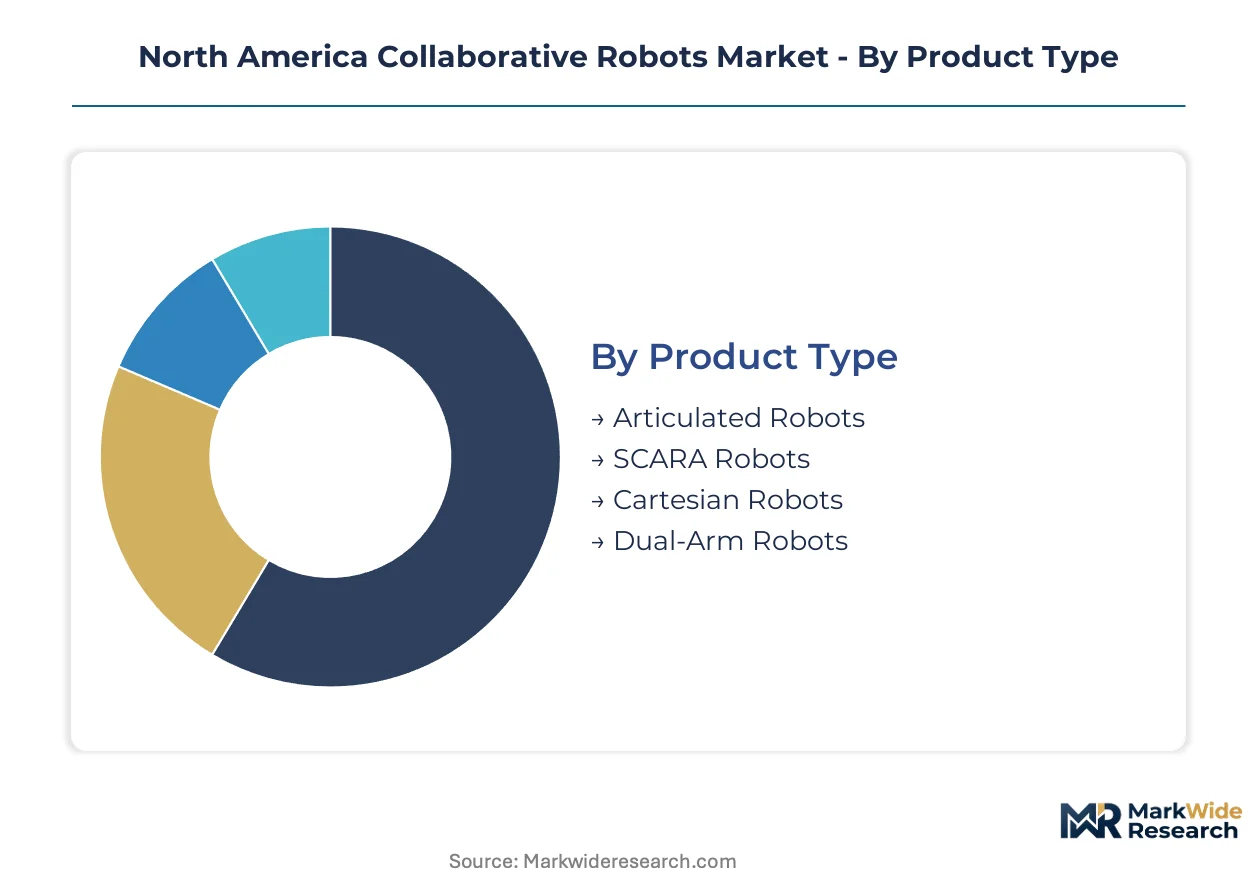
Segmentation in the North America collaborative robots market reveals how force-limited automation architectures align with distinct production environments. Procurement patterns diverge sharply between heavy manufacturing and precision electronics, with regulatory compliance requirements further stratifying deployment choices across OSHA and CSA jurisdictions.
Product Type:
Mature six-axis architectures dominate revenue concentration while emerging bimanual systems capture the fastest expansion trajectories in pharmaceutical and aerospace quality assurance.
- Articulated Robots:Six-degree-of-freedom arm configurations with integrated torque sensors and power-and-force-limiting controls enable complex welding and assembly sequences. Michigan and Ohio automotive plants deploy these systems for battery pack joining and lightweight aluminum handling under ISO/TS 15066 compliance mandates.
- Dual-Arm Robots:Synchronized bimanual manipulation platforms incorporate force-sensing controllers for coordinated two-handed operations. FDA-regulated sterile filling operations in pharmaceutical packaging lines are expanding quality-inspection throughput through these systems.
- SCARA Robots:Selective compliance assembly robot arms deliver high-speed planar precision for circuit-board handling in Ontario electronics clusters.
- Cartesian Robots:Linear three-axis gantries provide cost-effective pick-and-place automation for palletizing operations in cross-border automotive supply chains.
Articulated robots handle the majority of throughput; dual-arm configurations are gaining share fastest in inspection-intensive end uses.
End User:
Cost tier stratification separates capital-intensive automotive deployments from mid-scale electronics and regulated healthcare installations.
- Automotive:Tier-one suppliers in the U.S. Great Lakes manufacturing corridor retool assembly lines for electric vehicle production. Precision welding cobots handle battery pack assembly and aluminum joining tasks where force-limited designs satisfy OSHA technical manual requirements.
- Electronics:Mid-size fabricators in Ontario and New York State demand rapid-reconfiguration arms for mixed-model production serving Apple and Tesla supply chains.
- Healthcare:Sterile manufacturing environments in FDA-regulated facilities deploy force-sensing systems for pharmaceutical packaging and medical device assembly.
- Aerospace:Wire harness routing and clip insertion applications in Michigan supplier networks exploit vision-guided tactile feedback for cycle-time matching with conventional automation.
Automotive absorbs the largest capital allocation; healthcare exhibits the steepest expansion trajectory as FDA compliance drives force-limited retrofits.
Deployment:
Application criticality determines whether manufacturers prioritize real-time local processing or centralized analytics integration.
- Edge Computing:Low-latency wireless architectures enable fenceless mixed-model assembly previously blocked by cabling constraints. 5G-enabled speed-separation monitoring supports real-time human-robot collaboration in Ohio automotive facilities.
- On-Premise:Air-gapped controller networks dominate defense-sensitive and proprietary manufacturing environments where data sovereignty overrides cloud convenience.
- Hybrid:Split architectures process safety-critical motion control locally while pushing production analytics to centralized servers.
- Cloud-Based:Remote monitoring and predictive maintenance platforms serve distributed contract manufacturer networks with standardized fleet management.
Edge computing commands premium positioning for safety-critical applications; cloud-based deployment expands most quickly in multi-site electronics contract manufacturing.
Application:
Volume concentration in material handling contrasts with margin capture in quality inspection where force-sensing precision commands pricing premiums.
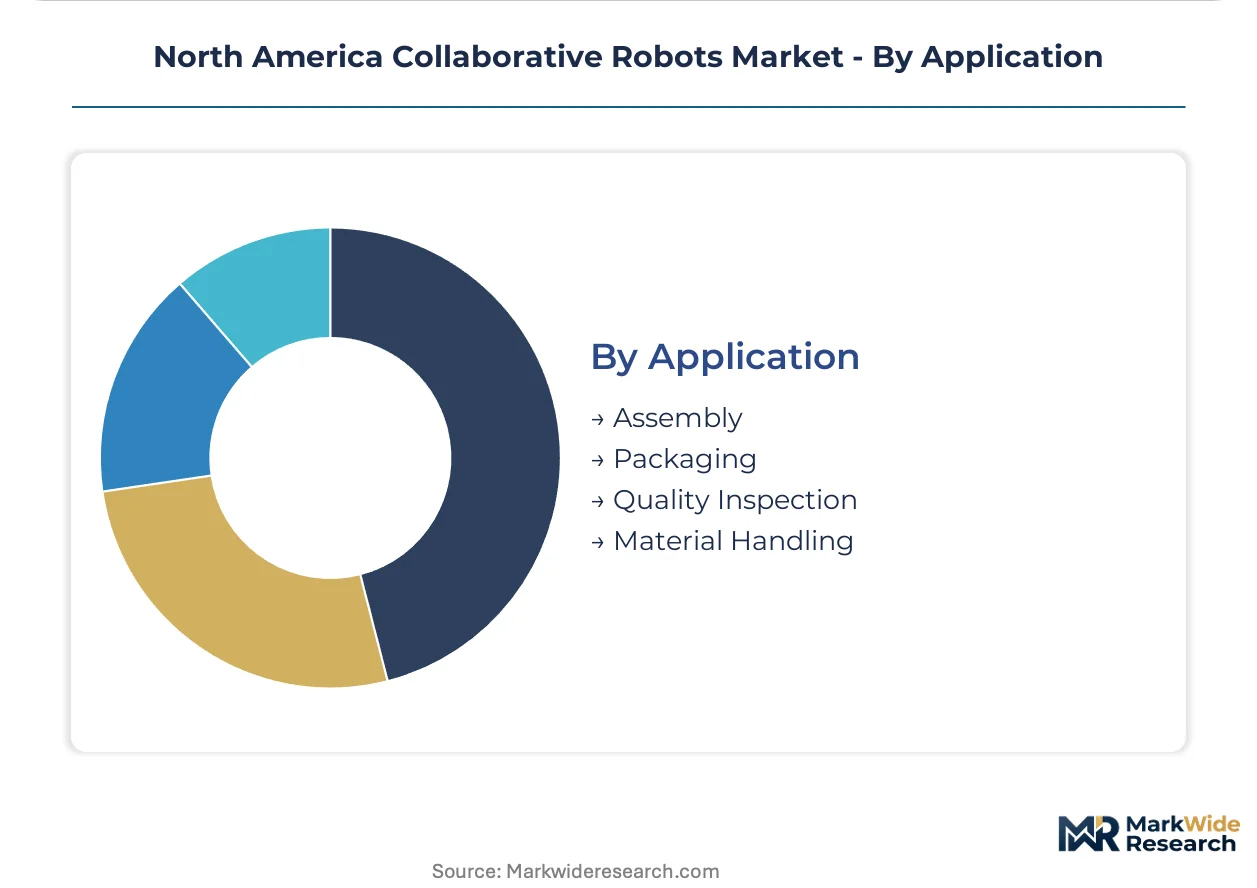
- Material Handling:Palletizing, machine tending, and parts feeding operations constitute the highest deployment volume across automotive and electronics floors. Force-limited designs eliminate fixed guarding requirements in mixed human-robot workflows.
- Quality Inspection:Tactile feedback systems with vision guidance collapse the boundary between human dexterity and robotic repeatability. Pharmaceutical packaging lines in FDA-regulated facilities deploy synchronized bimanual manipulation for sterile filling verification.
- Assembly:Precision joining and fastening operations in battery pack production leverage torque-controlled insertion for electric vehicle supply chains.
- Packaging:End-of-line case packing and palletizing in food and consumer goods facilities exploit collaborative speed without protective enclosures.
Material handling moves the greatest unit volume; quality inspection delivers the fastest share climb as force-sensing precision penetrates regulated manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Robot manufacturing concentrates in the U.S. Great Lakes corridor, where tier-one automotive suppliers retool for electric vehicle production. Canadian automation clusters in Ontario serve cross-border supply chains. Mexican nearshoring hubs in Querétaro and Guanajuato lack established integrator networks.
United States
Michigan and Ohio automotive plants deploy precision welding cobots for battery pack assembly. OSHA technical manual requirements force risk-assessment documentation before integration. The Great Lakes manufacturing corridor absorbs the highest capital allocation for force-limited retrofits.
Canada
Ontario-based electronics fabricators demand rapid-reconfiguration arms for mixed-model production serving Apple and Tesla supply chains. CSA Z434 certification requirements add validation timelines for cross-border deployments. Toronto-Waterloo automation clusters anchor regional assembly capacity.
Mexico
Automotive suppliers in Querétaro and Guanajuato seek first-mover service contracts from U.S.-based engineering firms. The country's national manufacturing regulator enforces workplace safety standards aligned with ISO frameworks. Northern border states attract maquiladora cobot installations for just-in-time delivery to Texas assembly plants.
North America Collaborative Robots Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in torque sensors and force-sensing modules. The vendor base spans German engineering conglomerates, Japanese precision manufacturers, and Danish modular specialists. Two strategic archetypes dominate: high-payload industrial platforms for automotive welding and lightweight reconfigurable arms for electronics handling. Competitive moves center on safety-service subscription bundling and 5G-enabled edge computing partnerships.
Among European-based engineering groups, KUKA AG and ABB Ltd. occupy positions in the high-payload system tier. Universal Robots A/S exemplifies the modular lightweight archetype for mid-scale fabricators. Japanese precision manufacturers including DENSO Corporation and Yaskawa Electric Corporation sit within the component-integrated platform segment.
| Leading Market Players |
|---|
| KUKA AG |
| Doosan Robotics Inc. |
| ABB Ltd. |
| DENSO Corporation |
| Techman Robot Inc. |
| Universal Robots A/S |
| Yaskawa Electric Corporation |
| AUBO Robotics |
| FANUC Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese torque sensor fabrication is compressing component pricing and forcing North American integrators to rebalance inventory exposure against German and Japanese supply alternatives. This utilization slack ripples downstream into cobot system pricing, where vendors absorb margin pressure to maintain automotive contract share.
Pricing Analysis
OSHA technical manual compliance dictates the pricing tier structure across the North America collaborative robots market. Three-tier pricing stratifies across force-limited premium systems with embedded risk-assessment software, standard ISO/TS 15066 certified arms, and economy SCARA alternatives without collaborative safety features. Cost compression in the standard tier is intensifying because automotive suppliers in Michigan and Ohio demand throughput-guaranteed automation-as-a-service contracts. Mid-size electronics fabricators in Ontario exhibit the highest price sensitivity, while FDA-regulated pharmaceutical operations accept premium positioning for sterile manufacturing validation.
Supply Chain Analysis
Precision force-sensing components draw from German, Japanese, and Chinese manufacturing bases, with torque sensors and harmonic drives anchoring upstream dependency. Cobot controller boards, servo motors, and optical encoders feed from Taiwanese and South Korean electronics clusters. Single-source vulnerability concentrates in high-resolution torque sensing modules, where Japanese suppliers dominate medical-grade certification tiers. Distribution runs through tier-one automotive integrators in the Great Lakes corridor and cross-border electronics distributors serving Ontario fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America collaborative robots market is recovering from a cyclical trough driven by electric vehicle retooling capex normalization. Tier-one automotive suppliers are resuming deferred automation programs as battery pack assembly volumes stabilize.
For Market Incumbents: Pre-empt subscription revenue erosion by embedding predictive risk-assessment software into hardware contracts before OSHA finalizes speed-separation monitoring updates. Consolidate service capacity in Mexican nearshoring hubs around Querétaro and Guanajuato to capture first-mover integrator relationships. Backward integration into torque sensor calibration capabilities defends margin position against 14-18 week lead time volatility from German and Japanese component suppliers.
For New Entrants and Emerging Players: Mid-market contract manufacturers in New York State and Ontario represent the most penetrable entry point, where rapid-reconfiguration demands outpace incumbent response times. Mexican automotive supplier parks lacking established cobot integrator networks offer white-space deployment opportunities for U.S.-based engineering firms. A performance-guaranteed automation-as-a-service pricing model aligns with Apple and Tesla supply chain volatility tolerance.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across lightweight modular arm sub-segments as software-defined motion planning displaces hardware-heavy force-sensing architectures. Target acquisition profiles center on edge computing software stacks enabling 5G-enabled fenceless deployments. The signal to watch is CSA Z434 harmonization progress with OSHA technical manual requirements, which would compress cross-border certification friction and accelerate Canadian market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Force-Limited Controller Certification | OSHA technical manual alignment accelerates automotive procurement qualification timelines. |
| 5G-Enabled Edge Computing Partnership | Low-latency wireless unlocks fenceless deployments in mixed-model Ohio assembly plants. |
| Automation-as-a-Service Platform Launch | Throughput-based pricing transfers obsolescence risk from Ontario electronics fabricators. |
| Mexican Nearshoring Service Expansion | Querétaro integrator scarcity creates first-mover capture in automotive supplier parks. |
| Predictive Risk-Assessment Software Integration | Embedded safety subscriptions compress vendor revenue toward recurring service streams. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with cobot system integrators, automotive plant engineers, pharmaceutical manufacturing directors, and electronics contract manufacturing executives; and secondary validation against SEC 10-K automation disclosures, OSHA technical manual updates, ISO/TS 15066 certification registries, and cross-border customs data on robotic component trade. Bottom-up deployment tallies across Michigan, Ohio, and Ontario facilities were triangulated against top-down vendor shipment estimates.
Forecast inputs span product type segmentation across articulated, dual-arm, SCARA, and Cartesian architectures; end-user concentration in automotive, electronics, healthcare, and aerospace verticals; and deployment models from edge computing through cloud-based fleet management. CAGRs were derived from regression analysis against electric vehicle production forecasts and pharmaceutical packaging automation capex cycles. The modeling period incorporates pending ISO 10218-2 revision scenarios and IRA clean energy manufacturing credit qualification thresholds.
Practitioners should monitor OSHA speed-separation monitoring threshold finalization and CSA Z434 harmonization progress for early signals of installed base retrofit demand. Cross-checking against IHS Markit automotive production forecasts and FDA pharmaceutical packaging equipment approval timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Pipe Inspection Robot Market