
 Europe Automation Components Market | 2026-2036
Europe Automation Components Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automation Components Market Analytics
Germany's industrial heartland is rewriting the competitive map for European automation supply. Bosch Rexroth AG leverages its deep manufacturing footprint in Lohr am Main to dominate precision motion control systems. Siemens AG anchors its position through in-house production of industrial controllers and cloud-connected automation platforms. ABB Ltd competes across Nordic and Central European markets with its portfolio of collaborative robots and variable speed drives.
Automation components comprise electromechanical and electronic devices that translate digital control signals into physical machine actions, typically operating at voltage ranges from 24V DC to 480V AC with response times measured in milliseconds. These components execute process control, motion sequencing, and safety interlocking across discrete and continuous manufacturing operations. Sensors and controllers capture disproportionate margin pools as OEMs prioritize predictive maintenance and real-time data acquisition over basic actuation hardware. PLC-based architectures sustain dominant share in process industries, while HMI and cloud-hybrid installations are expanding fastest among small and mid-sized manufacturers seeking remote oversight capabilities.
CE marking under the EU Machinery Directive and Ecodesign regulations enforce functional safety and energy performance thresholds for components deployed across member states. REACH compliance through ECHA restricts hazardous substances in sensor housings and cable assemblies, reshaping supplier qualification criteria. The EU AI Act introduces conformity obligations for autonomous decision-making modules embedded in advanced controllers. Stakeholders must monitor how evolving cybersecurity standards for operational technology networks reshape product certification timelines and customer procurement specifications.
Market Dynamics
German automotive OEMs are forcing a supply chain recalibration across the continent as electric vehicle assembly lines demand precision motion control and real-time sensor feedback loops. Tier-one suppliers in Stuttgart, Wolfsburg, and Munich now mandate predictive maintenance compatibility in every component procurement tender.
Growth Catalysts
- EU Green Deal machinery efficiency mandates:Factory equipment upgrades accelerate as Ecodesign regulations tighten energy performance thresholds for motors and drives deployed across member states.
- France's nuclear and chemical process industries:Safety instrumented systems refresh cycles drive controller and sensor replacement demand at refineries along the Rhône corridor.
- Edge computing convergence with PLCs:Local data processing at the device level reduces latency for Italian packaging machinery OEMs building modular production lines.
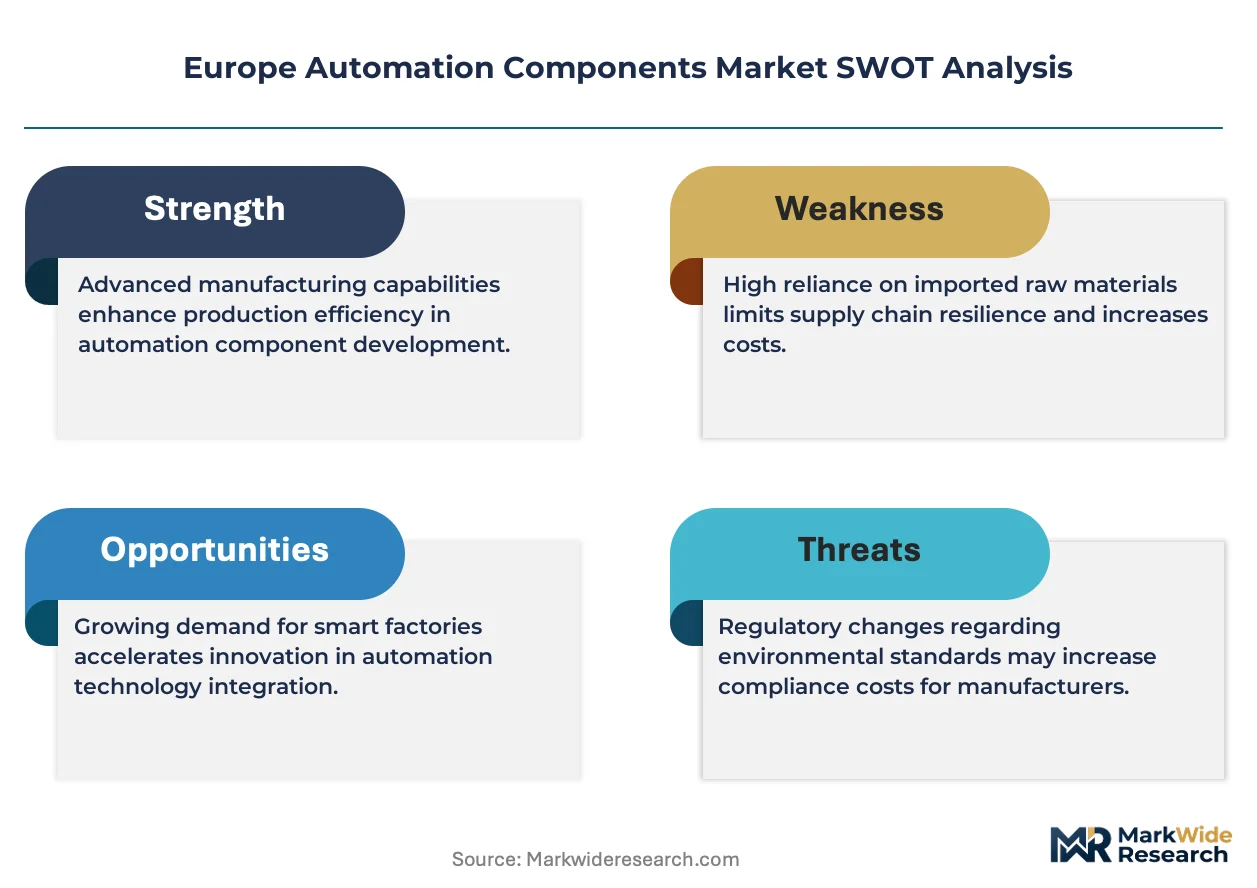
Market Restraints
- Rare earth magnet cost volatility:Permanent magnet supply concentration in China creates input price instability for servo motor manufacturers serving European machine builders.
- REACH compliance timeline friction:ECHA substance restriction updates force reformulation of cable insulation and sensor housings, extending supplier qualification cycles by 8-14 months.
- Mechanical relay substitution by solid-state:Semiconductor-based switching eliminates maintenance in harsh environments, compressing margins for electromechanical component specialists.
Strategic Opportunities
- Poland and Czech industrial modernization:Automotive component suppliers near Wrocław and Ostrava lack local automation service density, creating white space for remote diagnostics platforms.
- EU AI Act conformity services:Autonomous decision-making modules in advanced controllers require third-party certification support, opening recurring revenue streams for testing laboratories.
- 5G-TSN integration in motion control:Time-sensitive networking over wireless enables cable-free robot cells, appealing to Dutch and Belgian food processing equipment manufacturers.
Industry Challenges
- OT cybersecurity skill scarcity:Plant engineers lack training in IEC 62443 implementation, slowing secure-by-design controller deployments at mid-sized manufacturers.
- Legacy fieldbus migration complexity:PROFIBUS-to-PROFINET conversion projects stall when brownfield installations lack documentation, frustrating Italian textile machinery retrofit programs.
- CE marking documentation burden:Machinery Directive technical file requirements consume engineering resources at sensor startups seeking market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automation Components Market |
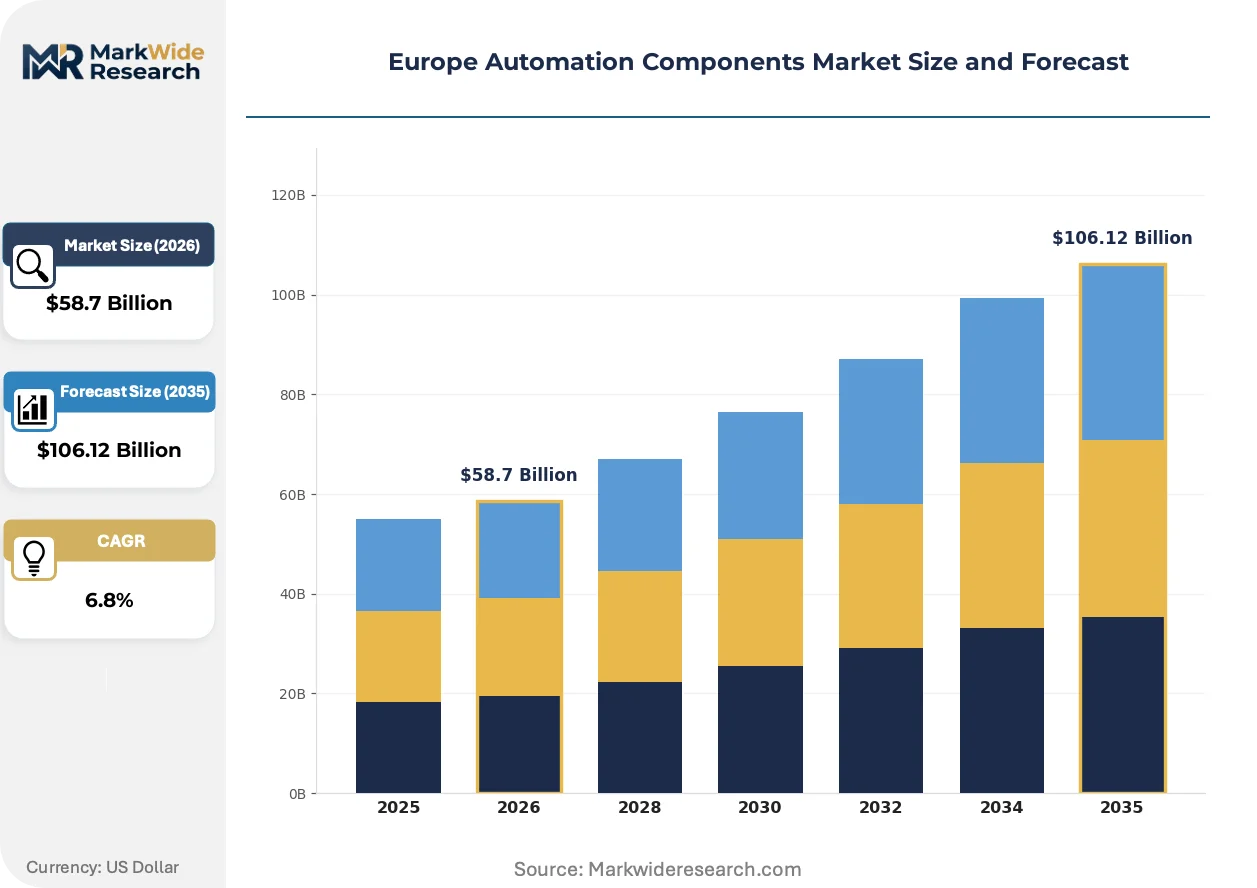
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Actuators, Controllers, Interfaces Technology: PLC, SCADA, DCS, HMI End User: Manufacturing, Automotive, Electronics, Food Processing Installation: On-premises, Cloud-based, Hybrid, Software as a Service |
| Companies Covered | Bosch Rexroth AG, Emerson Electric Co., Rockwell Automation, Inc., ABB Ltd, Schneider Electric SE, Siemens AG, AB SKF, Parker Hannifin Corporation, Nidec Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automation Components Market Evolving Landscape
Digital twin integration is compressing commissioning timelines as virtual commissioning environments replace physical prototyping. Component suppliers now embed simulation-ready data sheets to capture design-in decisions earlier in the machine development cycle.
Single-pair Ethernet physical layers are rendering obsolete traditional fieldbus architectures in material handling and packaging machinery. Bosch Rexroth and Siemens now ship drives with SPE ports standard, while smaller Italian conveyor OEMs adopt the technology to reduce wiring complexity. The shift collapses gateway hardware requirements and slashes installation labor.
CE marking under revised EU Machinery Directive safety standards forces recertification of collaborative robot systems and safety controllers. Manufacturers must demonstrate functional safety compliance through notified body assessment, extending product launch timelines. German automotive suppliers front-load certification budgets to maintain preferred vendor status with OEMs.
Equipment-as-a-service contracting spreads among French and Benelux contract manufacturers seeking to convert capital expenditure into operational expenditure. Machine builders now retain component ownership and charge per-unit-produced, shifting risk to suppliers. This model demands predictive maintenance APIs and remote monitoring capabilities in every sensor and drive shipped.
Europe Automation Components Market Segmentation
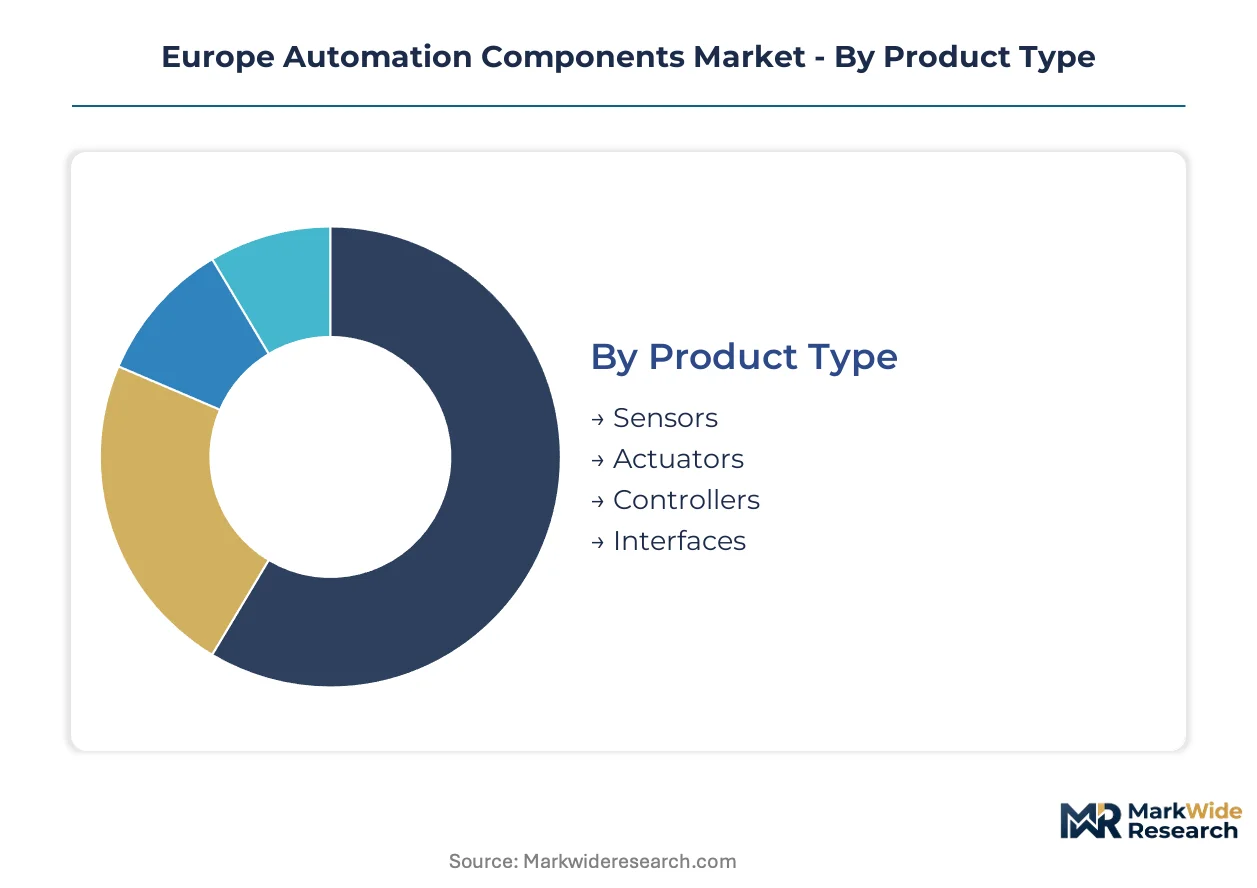
Automation component suppliers in Europe calibrate R&D and distribution investments around four structural axes. Product type and technology dimensions determine margin capture, while end-user concentration and installation preferences shape go-to-market economics across Germany, France, and Italy.
Product Type:
Mature electromechanical categories coexist with emerging electronic intelligence layers, creating divergent margin profiles across the supply base.
- Sensors:Photoelectric, inductive, and vision-based devices capture physical variables and convert them into digital signals for controller processing. German automotive OEMs in Stuttgart and Wolfsburg now mandate IO-Link connectivity and predictive maintenance telemetry in every sensor procurement tender, compressing margins for analog-only suppliers.
- Controllers:Programmable logic controllers and industrial PCs execute sequential logic, motion algorithms, and safety interlocks with millisecond determinism. Edge computing convergence drives demand for controllers with embedded analytics at French nuclear facilities along the Rhône corridor, where local data processing reduces latency for safety instrumented systems.
- Actuators:Servo motors, pneumatic cylinders, and linear drives translate control signals into mechanical motion. REACH compliance timelines force reformulation of cable insulation and housing materials.
- Interfaces:Communication gateways, protocol converters, and signal conditioners bridge heterogeneous device networks. Single-pair Ethernet physical layers are displacing traditional fieldbus architectures in Italian packaging machinery.
Sensors handle the majority of throughput; controllers are gaining share fastest as OEMs prioritize embedded intelligence over basic actuation.
Technology:
Cost tier differentiation separates legacy architectures from premium connected platforms, with mid-market manufacturers driving hybrid adoption patterns.
- PLC:Ruggedized programmable controllers dominate discrete manufacturing with deterministic scan cycles and modular I/O expansion. Brownfield migration complexity from PROFIBUS to PROFINET frustrates Italian textile machinery retrofit programs, stalling secure-by-design deployments at mid-sized manufacturers.
- SCADA:Supervisory control and data acquisition systems aggregate plant-floor data into centralized visualization and alarm management. Dutch food processors near Rotterdam adopt cloud-hybrid SCADA to enable remote oversight of distributed production assets.
- DCS:Distributed control systems manage continuous processes through redundant controller networks and integrated safety systems. France's chemical refineries drive replacement demand as safety instrumented system refresh cycles accelerate.
- HMI:Human-machine interfaces deliver operator visualization through panel PCs, mobile tablets, and augmented reality headsets. Equipment-as-a-service contracting among Benelux contract manufacturers demands predictive maintenance APIs in every HMI deployment.
PLC installations anchor volume; HMI represents the steepest expansion trajectory as remote oversight capabilities become standard procurement requirements.
End User:
Application intensity varies dramatically, with automotive and electronics sectors demanding precision motion control while food processing prioritizes washdown durability and regulatory traceability.
- Automotive:Electric vehicle assembly lines require precision motion control and real-time sensor feedback loops for battery module handling and electric motor assembly. Tier-one suppliers mandate predictive maintenance compatibility in every component tender.
- Manufacturing:General machinery builders and contract manufacturers deploy flexible automation for batch production and mass customization. Polish automotive component suppliers near Wrocław lack local service density, creating white space for remote diagnostics platforms.
- Electronics:Semiconductor and consumer electronics manufacturing demands sub-micron positioning accuracy and electrostatic discharge protection. Cleanroom-compatible components command premium pricing.
- Food Processing:Hygienic design standards and IP69K washdown ratings dominate equipment specifications for Dutch and Belgian meat, dairy, and confectionery producers. Stainless steel housings and food-grade lubricants extend qualification cycles.
Automotive absorbs the largest component volume; food processing is climbing the fastest as EU hygiene regulations tighten and labor costs rise.
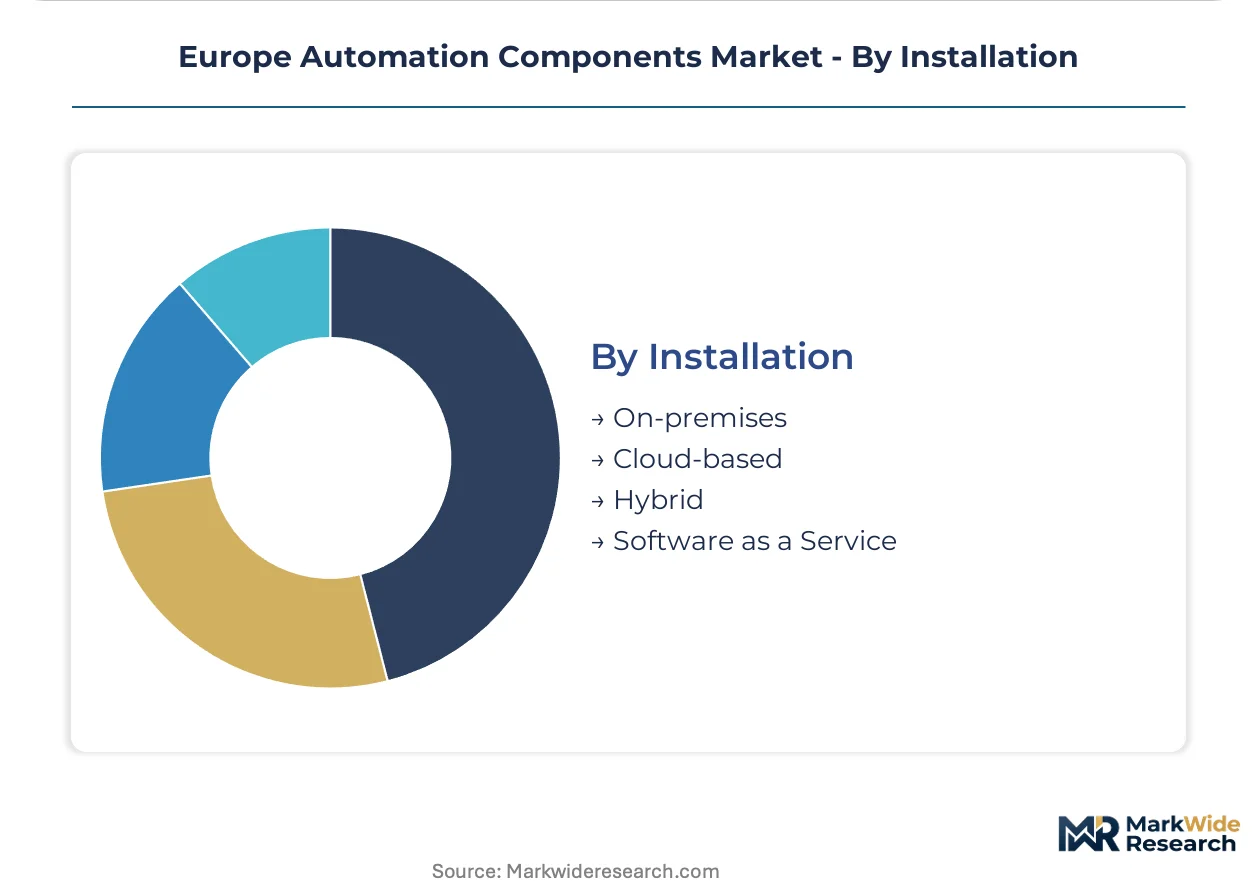
Installation:
Customer type splits between capital-expenditure buyers and operational-expenditure converters, with software-as-a-service models penetrating mid-market accounts.
- On-premises:Traditional capital deployment with local server infrastructure and dedicated engineering staff. German automotive suppliers front-load CE marking certification budgets to maintain preferred vendor status.
- Cloud-based:Fully managed automation platforms with subscription pricing and vendor-managed infrastructure. Cybersecurity skill scarcity in IEC 62443 implementation slows adoption at mid-sized manufacturers.
- Hybrid:Edge controllers with cloud analytics layers balance latency-sensitive control with centralized optimization. Italian packaging machinery OEMs build modular production lines around this architecture.
- Software as a Service:Per-unit-produced pricing with retained component ownership and predictive maintenance obligations. Machine builders in France and Benelux convert capital expenditure into operational expenditure through this model.
On-premises retains dominant share; software-as-a-service is expanding most quickly among contract manufacturers seeking balance sheet flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial conglomerates anchor component supply across the continent, while automotive electrification and machinery efficiency mandates pull demand toward Central European manufacturing clusters.
Germany
Stuttgart and Wolfsburg automotive OEMs mandate predictive maintenance compatibility in every sensor and actuator tender. KBA vehicle certification standards tighten electromagnetic compatibility requirements for factory automation equipment. Bavarian machine builders near Munich expand servo motor procurement for electric drivetrain assembly lines.
France
Rhône corridor refineries drive safety instrumented system refresh cycles for controllers and sensors. ANSM and nuclear safety regulators enforce functional safety compliance for process automation at chemical facilities. Île-de-France contract manufacturers adopt equipment-as-a-service models with per-unit-produced pricing.
Italy
Packaging machinery OEMs in Emilia-Romagna build modular production lines around edge-computing PLCs. CE marking under revised Machinery Directive standards extends certification timelines for collaborative robot deployments. Textile machinery retrofit programs in Lombardy stall on PROFIBUS-to-PROFINET migration complexity.
Poland
Automotive component suppliers near Wrocław lack local automation service density, creating white space for remote diagnostics platforms. EU Green Deal machinery efficiency mandates accelerate motor and drive upgrades at manufacturing facilities. Silesian industrial zones attract German-tier supplier investments in precision motion control systems.
Netherlands
Rotterdam food processors adopt cloud-hybrid SCADA for remote oversight of distributed production assets. Cybersecurity standards for operational technology networks reshape procurement specifications for mid-sized manufacturers. Dutch and Belgian meat and dairy producers demand IP69K washdown ratings and stainless steel housings for hygienic automation components.
Europe Automation Components Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a tiered structure where full-stack automation vendors capture recurring service revenue while electromechanical suppliers compete on specification density. The vendor base stratifies across three archetypes: diversified industrial conglomerates with captive controller platforms, motion-control specialists with deep servo motor expertise, and emerging sensor-focused players betting on IO-Link connectivity. Competitive intensity centers on M&A-driven portfolio expansion into predictive maintenance software and strategic partnerships for 5G-time-sensitive networking integration.
Within the diversified industrial tier, Siemens AG and ABB Ltd anchor European market presence through integrated automation platforms spanning controllers, drives, and cloud connectivity. Bosch Rexroth AG exemplifies the motion-control specialist archetype with precision servo systems manufactured from its Lohr am Main headquarters. These three Germany-based and Switzerland-headquartered entities represent distinct competitive vectors: full-stack platform dominance, precision electromechanical specialization, and Nordic-Central European geographic coverage.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Emerson Electric Co. |
| Rockwell Automation, Inc. |
| ABB Ltd |
| Schneider Electric SE |
| Siemens AG |
| AB SKF |
| Parker Hannifin Corporation |
| Nidec Corporation |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine corridor's freight cost volatility transmits directly into component pricing tiers, amplifying margin compression for electromechanical suppliers while rewarding electronics-heavy portfolios with lighter logistics exposure. Supply concentration in German precision manufacturing clusters reinforces premium pricing power for motion control systems, whereas peripheral sourcing from Eastern European contract manufacturers enables aggressive positioning in standard actuator categories.
Pricing Analysis
CE marking under the EU Machinery Directive dictates the pricing tier structure across the European automation components landscape. Three-tier pricing structure across premium, standard, and economy levels separates safety-certified collaborative robot modules from basic relay assemblies, with certification grade and volume scale as the primary differentiation drivers. Cost compression in economy-tier electromechanical components is intensifying because semiconductor-based solid-state switching eliminates maintenance advantages previously held by mechanical suppliers. Tier-one automotive OEMs in Stuttgart and Wolfsburg demonstrate the least price sensitivity, prioritizing predictive maintenance telemetry and IO-Link connectivity over unit cost, while mid-sized Italian packaging machinery builders remain the most price-constrained buyer segment.
Supply Chain Analysis
Electronics manufacturing services concentration at Jabil, Flex, and regional Czech contract manufacturers anchors final assembly capacity for sensor modules and controller boards. Component sourcing draws from Germany for precision servo motors, China for rare earth magnets and semiconductor substrates, and Taiwan for industrial-grade microcontrollers. Single-source vulnerability in permanent magnet supply creates structural exposure to input price instability for European servo motor manufacturers. Distribution runs through authorized distributor networks anchored by RS Components and Conrad Electronic, with direct OEM relationships gaining share among large German automotive suppliers seeking technical collaboration on electric drivetrain assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state switching technologies threaten electromechanical relay incumbents with accelerated substitution, forcing defensive portfolio restructuring toward embedded intelligence and predictive maintenance software layers.
For Market Incumbents: Harden market position by acquiring IO-Link connectivity specialists to defend against sensor commoditization, and expand in-house production of safety-certified controller platforms to capture CE marking premium tiers. The shift toward semiconductor-based switching demands accelerated R&D investment in hybrid electromechanical-solid-state architectures that preserve existing customer relationships while bridging technology transitions. For New Entrants and Emerging Players: Pursue white-space opportunities in remote diagnostics platforms serving Polish automotive component suppliers near Wrocław and Ostrava, where local automation service density remains underdeveloped. Target equipment-as-a-service contracting models among French and Benelux contract manufacturers seeking operational expenditure conversion, leveraging predictive maintenance APIs as the primary go-to-market wedge against established capital-sale incumbents. For Investors and Strategic Acquirers: Sensor-focused startups with embedded edge analytics capabilities represent the most attractive acquisition target archetype, given OEM prioritization of predictive maintenance telemetry over basic actuation hardware. Long-term viability hinges on portfolio exposure to software-recurring revenue streams rather than transactional component sales. Watch for inflection signals in 5G-TSN integration adoption rates among Dutch and Belgian food processing equipment manufacturers, as wireless motion control penetration indicates readiness for cable-free robot cell architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Sourcing | Mitigates Chinese supply concentration exposure for servo motor manufacturers serving German automotive OEMs. |
| CE Marking Fast-Track Certification Investment | Compresses product launch timelines for collaborative robot systems under revised EU Machinery Directive safety standards. |
| Predictive Maintenance Software Acquisition | Captures recurring service revenue streams as equipment-as-a-service contracting spreads among French contract manufacturers. |
| 5G-TSN Integration Partnership | Enables cable-free robot cell architectures appealing to Dutch and Belgian food processing equipment manufacturers. |
| Edge Computing Controller Platform Launch | Addresses latency requirements for Italian packaging machinery OEMs building modular production lines. |
Research Methodology
A spread of perspectives from plant engineers at German automotive OEMs, procurement leads at Tier 1 suppliers, aftermarket service heads at motion control specialists, and regulatory affairs directors at controller manufacturers converged on the working assumptions underlying this analysis. Primary interview insights were cross-validated against secondary sources including EU Machinery Directive implementation guidance, ECHA REACH substance restriction updates, SEC filings from listed automation vendors, and customs data tracking component trade flows into Central European manufacturing clusters. Bottom-up demand modeling across installation types and end-use industries was reconciled with top-down market sizing derived from production capacity disclosures and OEM procurement trend analysis.
Demand-supply balance framing anchored the forecast framework throughout the projection horizon. The analytical approach modeled volume and value trajectories across product type, technology architecture, end-user industry, and installation preference dimensions, with additional granularity applied to electric vehicle assembly line intensity versus general manufacturing automation refresh cycles. CAGRs were derived from fitted growth curves applied to segment-level baseline estimates, incorporating EU Green Deal machinery efficiency mandate compliance timelines and safety instrumented system replacement cycles at French nuclear facilities as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, rare earth commodity price trajectories, or CE marking regulatory enforcement intensity would shift the trajectory from modeled outputs. Forecasts embed assumptions regarding continued automotive electrification investment and sustained Ecodesign regulation tightening without anticipating disruptive technology substitutions beyond solid-state switching penetration already evident in the baseline. Quarterly review of German automotive OEM production schedules, ECHA substance restriction proposal timelines, and 5G-TSN standards adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
Multi-Axis Motion Controller Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
South East Asia Warehouse Automation Market