
 Wearable Robots and Exoskeletons Market | 2026-2036
Wearable Robots and Exoskeletons Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Robots and Exoskeletons Market Outlook
Industrial buyer archetypes are unwinding their historical dominance as healthcare institutions command larger procurement volumes. Ekso Bionics Holdings Inc. leverages its FDA-cleared rehabilitation portfolio to anchor North American hospital networks. Cyberdyne Inc. dominates the Japanese regulatory pathway with its HAL medical device certification. German Bionic Systems GmbH competes in European industrial logistics through its BionicBack workplace assistance systems.
Wearable robots and exoskeletons are electromechanical frameworks that combine rigid or soft actuation with sensor-integrated control systems to augment, assist, or restore human movement, typically operating through torque-limited joints and force-feedback loops that interpret electromyographic or inertial signals. Lower-limb exoskeletons lead the product type landscape due to established reimbursement codes for spinal cord injury rehabilitation, while soft robotics represents the fastest-growing technology segment as compliant actuators reduce device weight and improve user comfort during extended wear cycles. Industrial assistance applications retain mature margin pools in automotive assembly and warehouse logistics, though physical rehabilitation channels exhibit steeper volume trajectories as clinical evidence accumulates for stroke and multiple sclerosis protocols.
FDA 510(k) and breakthrough device pathways shape product development timelines for US market entrants, while the EU Medical Device Regulation imposes stricter clinical evidence requirements through notified body oversight. Japan's PMDA pharmaceutical and medical device agency maintains distinct approval categories that Cyberdyne has navigated for its HAL hybrid assistive limb systems. Stakeholders must monitor reimbursement parity between passive and powered exoskeleton categories across national health systems to anticipate demand inflection points.
Market Dynamics
Healthcare procurement of lower-limb exoskeletons is displacing industrial buyers as the dominant demand source, driven by FDA breakthrough designations and expanding stroke rehabilitation protocols that compress clinical adoption timelines.
Growth Catalysts
- ISO 13485 Certification Momentum:Quality management standardization accelerates hospital network procurement decisions by reducing vendor qualification cycles for powered rehabilitation systems.
- German Industrial Safety Mandates:Workplace assistance requirements in logistics and automotive assembly drive BionicBack system deployments for manual material handling operations.
- PMDA Medical Device Pathway:Japan's distinct regulatory categories for hybrid assistive limbs enable faster market entry compared to pharmaceutical-style approval frameworks.
Market Restraints
- High-Power Actuator Costs:Rare-earth magnet dependency in torque-dense motors creates input cost volatility that compresses margins for powered lower-limb systems.
- EU MDR Clinical Evidence Burden:Stricter notified body oversight for Medical Device Regulation compliance extends development timelines and elevates certification expenditures.
- Passive Exoskeleton Substitution:Spring-loaded unpowered alternatives capture price-sensitive industrial segments where augmentation requirements remain modest.
Strategic Opportunities
- Multiple Sclerosis Rehabilitation Protocols:Emerging clinical evidence for gait training in neurodegenerative conditions opens addressable patient populations beyond spinal cord injury.
- Soft Robotics Convergence:Compliant actuator integration with textile-based sensor arrays enables home-use prescription models that bypass facility-based reimbursement constraints.
- US Veterans Health Administration Channel:Federal procurement centralization for veteran rehabilitation creates volume concentration opportunities distinct from fragmented hospital purchasing.
Industry Challenges
- Biomechanical Integration Talent Scarcity:Shortage of engineers combining neuromuscular physiology expertise with real-time control systems development constrains product iteration velocity.
- Reimbursement Code Fragmentation:Disparity between passive and powered device coverage categories across national health systems forces parallel commercialization strategies.
- Legacy EMR System Interoperability:Hospital data architecture incompatibility with exoskeleton telemetry outputs complicates outcome documentation for payor justification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Robots and Exoskeletons Market |
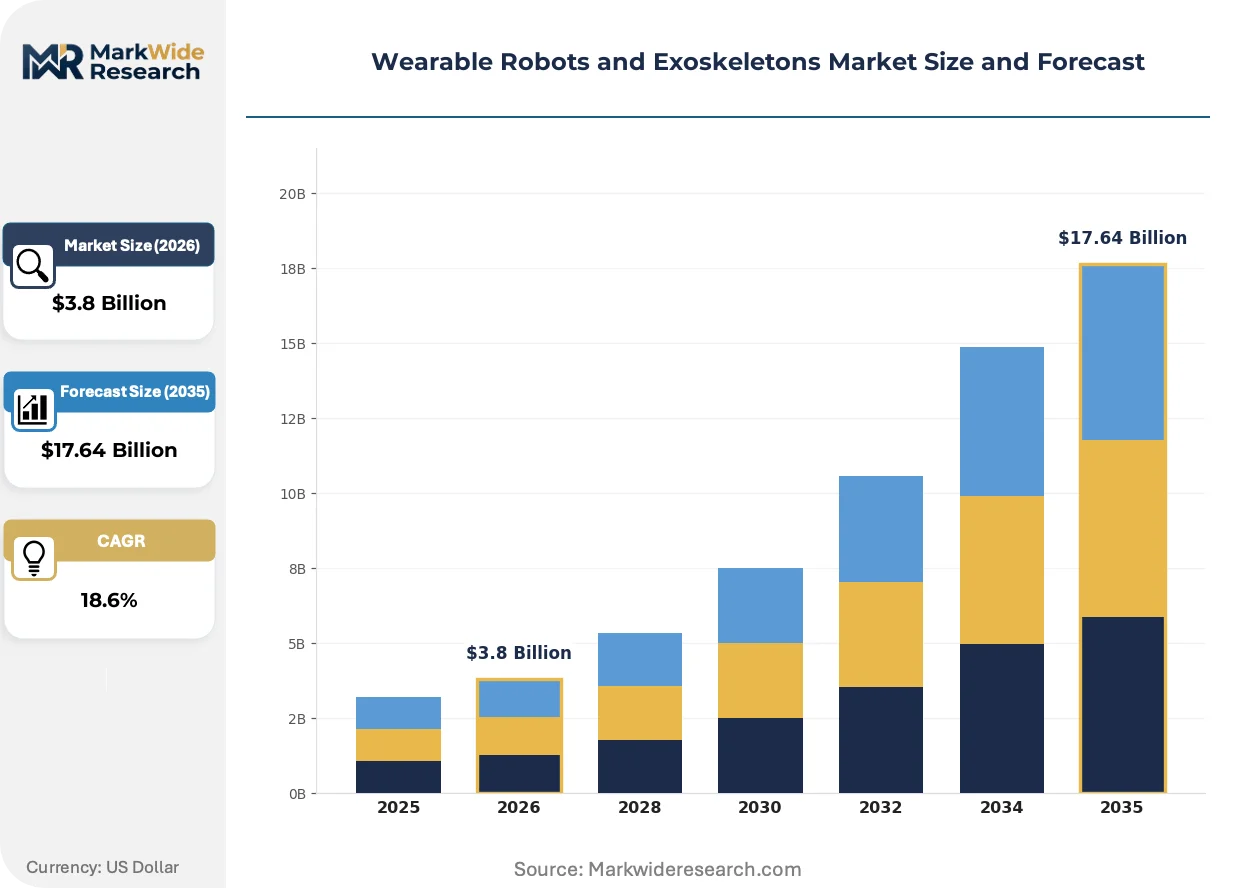
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Body Exoskeletons, Lower-Limb Exoskeletons, Upper-Limb Exoskeletons, Rehabilitation Robots Technology: Soft Robotics, Rigid Robotics, Control Systems, Sensor Integration End User: Healthcare Institutions, Industrial Workers, Military Personnel, Elderly Assistants Application: Physical Rehabilitation, Industrial Assistance, Gaming Interaction, Mobility Enhancement |
| Companies Covered | Sarcos Technology and Robotics Corporation, German Bionic Systems GmbH, Cyberdyne Inc., Honda Motor Co. Ltd, Hyundai Motor Group Robotics LAB, Ekso Bionics Holdings Inc., Myomo Inc., Ottobock, ReWalk Robotics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Robots and Exoskeletons Market Strategic Shifts
Sensor-integrated control architectures are actively fragmenting the competitive landscape as software differentiation supersedes hardware specifications in procurement evaluations.
Soft pneumatic actuation is decomposing the rigid exoskeleton paradigm by enabling garment-like form factors that reduce metabolic cost during extended wear. Rehabilitation clinics in the United States and Japan are piloting these systems for outpatient stroke protocols. The technology is decomposing historical trade-offs between assistance magnitude and user comfort that constrained daily utilization rates.
EU Medical Device Regulation implementation is compressing market access timelines for non-European manufacturers while elevating clinical evidence requirements for Class IIa and IIb active therapeutic devices. Notified body capacity constraints in Germany and the Netherlands are creating approval bottlenecks. Japanese manufacturers with prior PMDA certifications are leveraging mutual recognition pathways to accelerate EU market entry.
Hospital procurement committees are consolidating vendor relationships around full-service rehabilitation platform contracts that bundle device placement with therapist training and outcome analytics. This behavior is displacing discrete equipment purchasing models that dominated early market development. The shift is most visible in integrated delivery networks across the United States where capital expenditure rationalization prioritizes total cost-of-ownership metrics over acquisition price.
Wearable Robots and Exoskeletons Market Segmentation
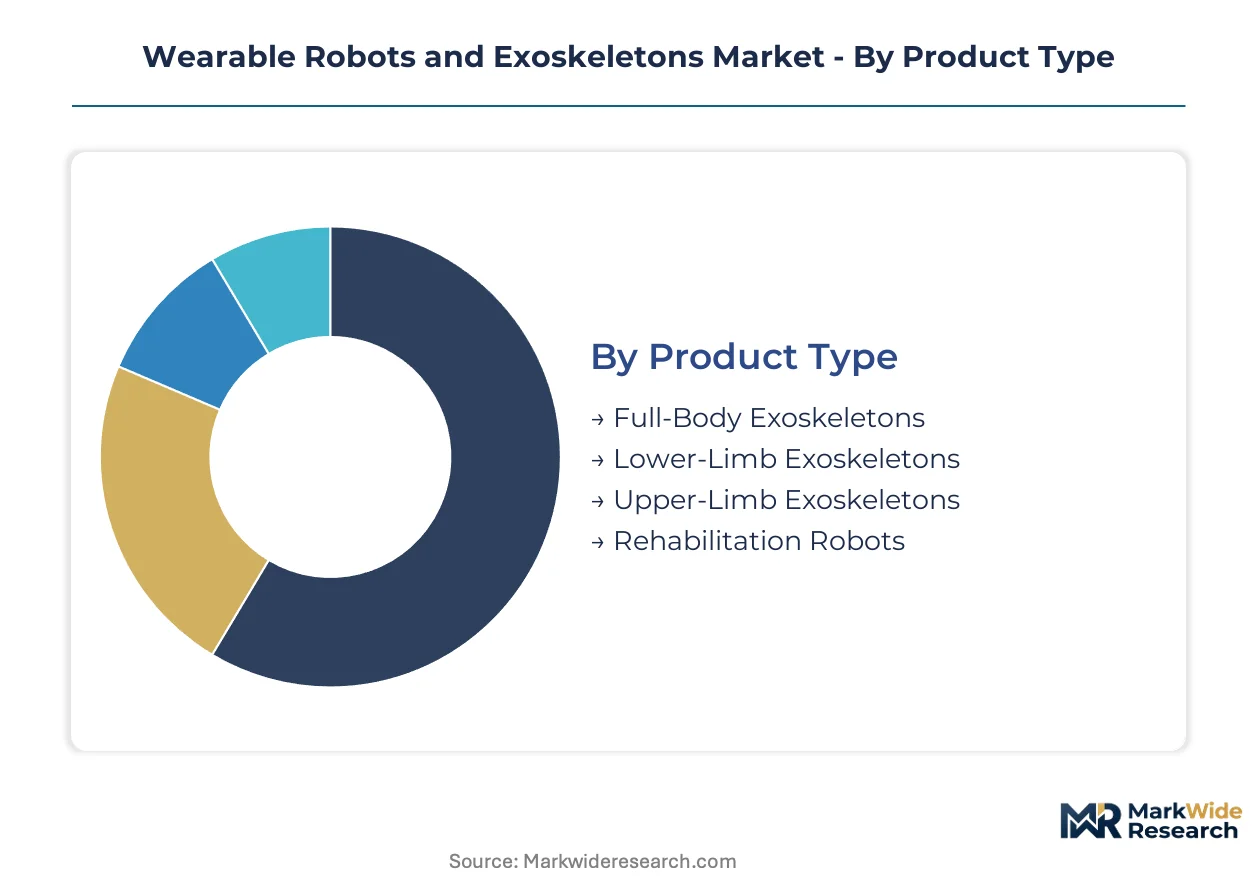
Segmentation in wearable robots and exoskeletons reveals divergent commercialization pathways across rigid and soft architectures. Channel strategies vary sharply between hospital procurement committees and industrial safety managers.
Product Type:
Hospital networks and industrial safety departments source through distinct qualification pathways, with FDA-cleared systems flowing through GPO contracts and workplace assistance devices deploying via occupational health budgets.
- Full-Body Exoskeletons:Torque-dense actuation frameworks spanning hip, knee, and ankle joints with synchronized gait pattern generation. Demand concentrates in US Veterans Health Administration spinal cord injury programs driven by centralized federal procurement authority.
- Lower-Limb Exoskeletons:Powered hip-knee-ankle systems with ground reaction force sensing and variable stiffness control. Stroke rehabilitation clinics in Germany and Japan command the dominant procurement volumes as reimbursement codes mature for gait training protocols.
- Upper-Limb Exoskeletons:Shoulder-elbow-wrist actuation for repetitive task assistance in automotive assembly.
- Rehabilitation Robots:Stationary end-effector devices for upper-extremity therapy in outpatient clinics.
Lower-Limb Exoskeletons dominate installed base. Full-Body Exoskeletons is where expansion concentrates.
Technology:
Cost tiers separate premium sensor-fusion platforms from commodity actuator assemblies, with textile-based systems commanding price multiples over rigid frame alternatives.
- Soft Robotics:Pneumatic or cable-driven actuation embedded in compliant textile substrates with stretchable sensor arrays. Home-use prescription models in Japan are gaining share fastest as PMDA pathways enable faster market entry than pharmaceutical-style frameworks.
- Rigid Robotics:Aluminum or carbon-fiber linkages with brushless DC motors and harmonic drive transmissions. Industrial logistics operations in Germany absorb the dominant procurement volumes driven by BionicBack workplace safety mandates.
- Control Systems:Real-time gait phase detection algorithms with predictive torque modulation.
- Sensor Integration:IMU-EMG fusion architectures for intent recognition in rehabilitation settings.
Rigid Robotics anchors current revenue. Soft Robotics is climbing the fastest.
End User:
Customer type determines pricing architecture, with healthcare institutions negotiating bundled service contracts and industrial buyers focusing on capital expenditure per protected worker.
- Healthcare Institutions:Hospital networks and outpatient rehabilitation clinics with ISO 13485 vendor qualification requirements. Stroke and multiple sclerosis protocols in the United States are expanding fastest as FDA breakthrough designations compress clinical adoption timelines.
- Industrial Workers:Warehouse logistics and automotive assembly personnel performing manual material handling. German automotive OEMs command the dominant deployment volumes driven by occupational health insurance cost reduction targets.
- Military Personnel:Load carriage augmentation for dismounted infantry operations.
- Elderly Assistants:Community-dwelling older adults with mobility limitations in aging demographics.
Healthcare Institutions command procurement volume leadership. Industrial Workers retain margin concentration.
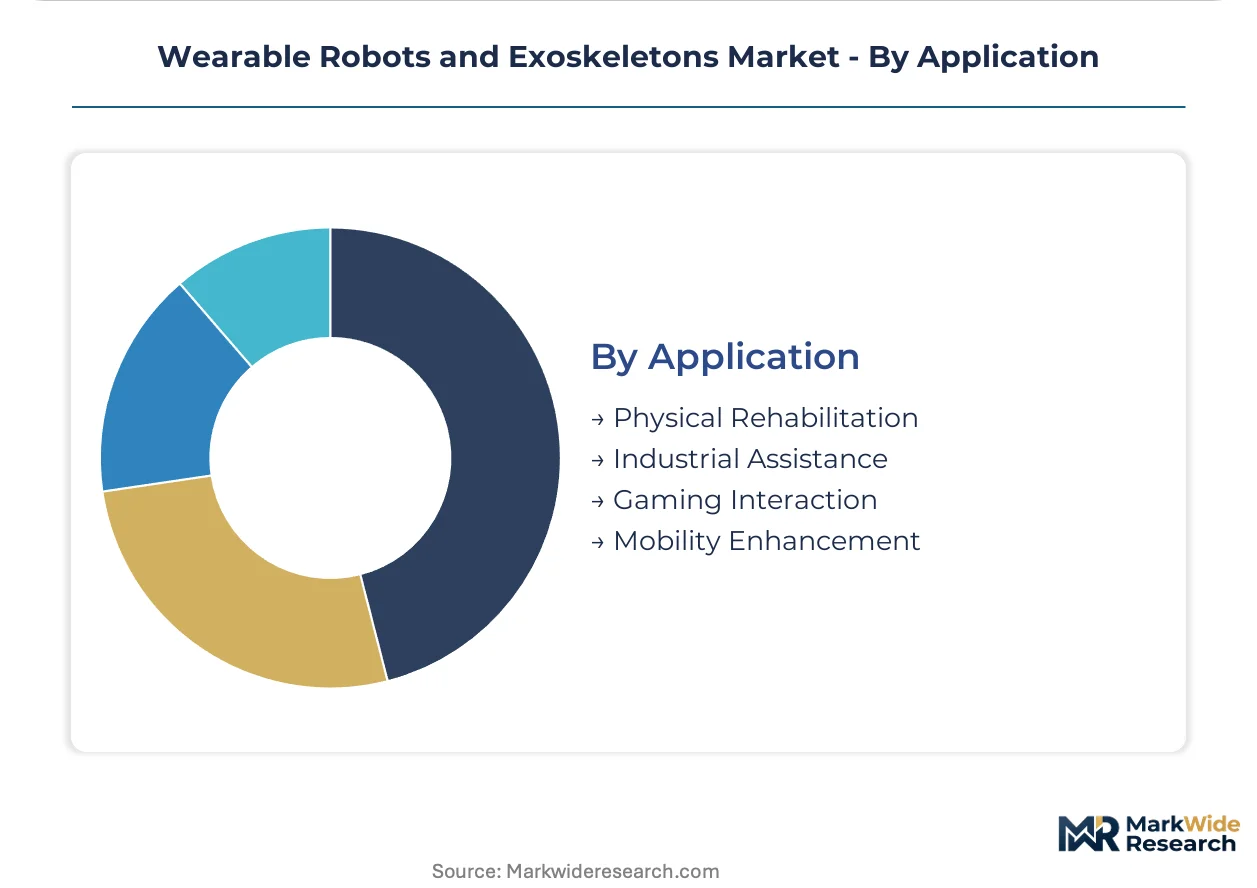
Application:
Application maturity separates established reimbursement channels from emerging self-pay segments, with physical rehabilitation accessing national health system budgets while gaming interaction relies on direct consumer expenditure.
- Physical Rehabilitation:Gait training and upper-extremity therapy for neurological and orthopedic conditions. US hospital networks and Japanese rehabilitation clinics absorb the dominant volumes as clinical evidence accumulates for stroke protocols.
- Industrial Assistance:Back support and load reduction for repetitive lifting operations. German logistics hubs and Japanese manufacturing plants command the steepest expansion trajectory as workplace safety regulations tighten.
- Gaming Interaction:Immersive haptic feedback systems for virtual reality entertainment.
- Mobility Enhancement:Community ambulation support for spinal cord injury and elderly populations.
Physical Rehabilitation dominates facility-based deployment. Industrial Assistance is where volume growth concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Bionic Systems GmbH exports workplace assistance systems to logistics operators across the Netherlands and Belgium. Japanese manufacturers ship HAL-certified rehabilitation platforms to Southeast Asian hospital networks. United States-based developers supply FDA-cleared stroke rehabilitation systems to Canadian and Mexican healthcare institutions.
United States
The Veterans Health Administration commands centralized procurement volumes for spinal cord injury rehabilitation programs. FDA breakthrough device designations compress clinical adoption timelines for stroke protocols. Integrated delivery networks in Texas and California consolidate vendor relationships around bundled service contracts.
Germany
Automotive OEMs in Bavaria deploy BionicBack systems for manual material handling cost reduction. Industrial safety mandates from the country's occupational health insurance framework accelerate workplace assistance adoption. Logistics hubs in North Rhine-Westphalia absorb dominant deployment volumes.
Japan
PMDA medical device pathways enable faster market entry for hybrid assistive limb systems than pharmaceutical-style frameworks. METI standards support rehabilitation clinic expansion in Kanto and Kansai regions. Tokyo-based hospital networks pilot soft pneumatic actuation for outpatient stroke protocols.
United Kingdom
NHS procurement committees evaluate ISO 13485-certified systems for neurological rehabilitation expansion. MHRA oversight aligns with EU MDR clinical evidence requirements for Class IIb active therapeutic devices. London and Manchester rehabilitation clinics accumulate clinical evidence for multiple sclerosis gait training.
South Korea
MFDS medical device approvals facilitate domestic manufacturing of powered lower-limb systems. Seoul Capital Area hospital networks integrate sensor-integrated control architectures for stroke rehabilitation. Daegu-Gyeongbuk industrial clusters explore workplace assistance for aging manufacturing workforces.
Wearable Robots and Exoskeletons Market Competitive Environment
Listed leaders compete with private specialists across regulatory certification depth and reimbursement pathway access. The vendor base spans venture-backed rehabilitation platform developers, automotive spin-off robotics divisions, and industrial safety equipment conglomerates. Three archetypes dominate: FDA-cleared medical device specialists, PMDA-certified Japanese hybrid assistive limb developers, and European workplace assistance system fabricators. Competitive moves concentrate on strategic partnerships with hospital networks and technology licensing for soft actuator integration.
Among Germany-based workplace assistance developers, German Bionic Systems GmbH exemplifies the industrial safety archetype. Cyberdyne Inc. and Ekso Bionics Holdings Inc. represent divergent regulatory pathway specialists, with the former occupying a position within Japan's PMDA framework and the latter anchoring North American FDA-cleared rehabilitation portfolios. These three entities collectively illustrate how geographic regulatory specialization fragments competitive positioning across national health system procurement channels.
| Leading Market Players |
|---|
| Sarcos Technology and Robotics Corporation |
| German Bionic Systems GmbH |
| Cyberdyne Inc. |
| Honda Motor Co. Ltd |
| Hyundai Motor Group Robotics LAB |
| Ekso Bionics Holdings Inc. |
| Myomo Inc. |
| Ottobock |
| ReWalk Robotics Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Japanese rehabilitation clinic networks and HAL-certified manufacturers lock in rare-earth magnet supply access while stabilizing actuator cost visibility across multi-year procurement horizons. These arrangements concentrate pricing power with PMDA pathway incumbents who secured early neodymium supply commitments.
Pricing Analysis
Current-generation rigid lower-limb systems command substantial premiums over prior-generation passive spring-loaded alternatives, while next-generation soft pneumatic platforms are resetting price benchmarks through textile-based manufacturing economics. Three-tier pricing structure across FDA-cleared premium systems, ISO-certified standard rehabilitation units, and industrial workplace assistance devices separates reimbursement-eligible medical grade from occupational safety budget tiers. Cost compression in rigid actuator assemblies is intensifying because Chinese rare-earth export quotas are tightening magnet availability. Industrial safety managers in German logistics hubs exhibit the highest price sensitivity due to per-worker capital expenditure caps, whereas US Veterans Health Administration procurement demonstrates lowest sensitivity through centralized federal budget authority.
Supply Chain Analysis
Rare-earth magnet refining in China, precision harmonic drive manufacturing in Japan, and carbon-fiber composite fabrication in Germany constitute the critical chokepoints for torque-dense exoskeleton production. Brushless DC motors, neodymium-iron-boron magnets, and stretchable conductive textiles draw from geographically concentrated supplier bases with limited second-source alternatives. Single-source vulnerability in Chinese rare-earth processing creates tariff exposure and supply disruption risk for powered lower-limb system manufacturers. Distribution runs through hospital GPO contracts in North America, direct occupational health sales in Europe, and rehabilitation clinic networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
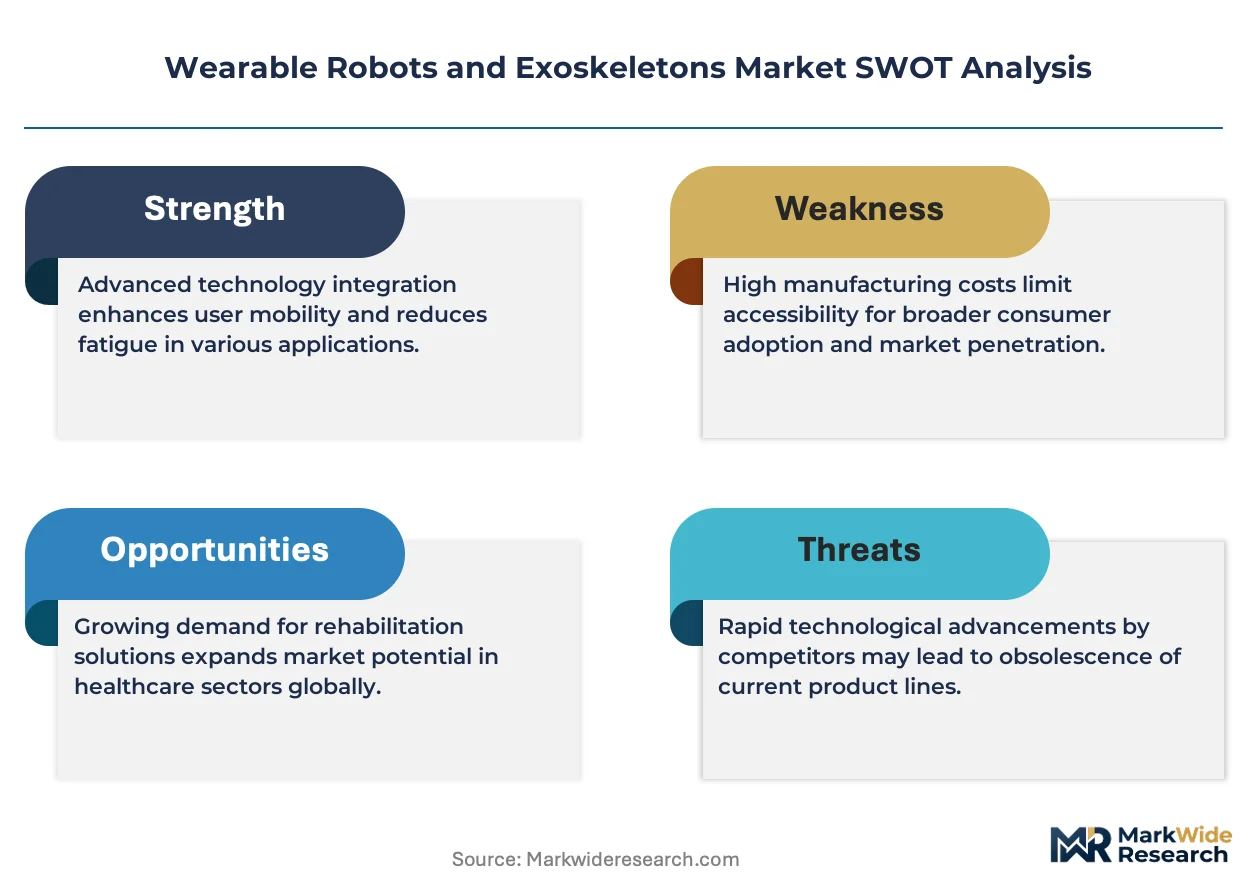
Fragmentation opportunities are proliferating as healthcare procurement displaces industrial buyers, creating distinct vendor qualification pathways that favor specialized regulatory archetypes over diversified generalists.
For Market Incumbents: Shield FDA-cleared rehabilitation portfolios from PMDA-certified Japanese competitors by deepening ISO 13485 certification moats and securing exclusive GPO contracts with integrated delivery networks in Texas and California. Vertical integration into rare-earth magnet sourcing through Australian mining partnerships reduces input cost volatility exposure. Channel control via bundled therapist training and outcome analytics platforms raises switching costs for hospital procurement committees evaluating alternative vendors. For New Entrants and Emerging Players: Anchor in soft pneumatic actuation for home-use prescription models, where PMDA pathways enable faster market entry than pharmaceutical-style frameworks and reimbursement constraints are less severe. Multiple sclerosis rehabilitation protocols in the United Kingdom represent the most penetrable clinical segment, with NHS committees actively accumulating evidence for neurodegenerative gait training. Direct-to-clinic sales bypassing traditional distributor markups offers a viable go-to-market angle for textile-based systems with lower capital intensity. For Investors and Strategic Acquirers: Capital is best deployed toward PMDA-certified Japanese developers with proven HAL medical device track records and established Southeast Asian export channels. Long-term viability across the analysis window hinges on reimbursement code expansion for powered systems versus passive alternatives. The signal to watch is FDA breakthrough device designation velocity for stroke rehabilitation protocols, which would validate clinical adoption acceleration and justify premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates clinical adoption timelines for stroke rehabilitation protocols in US hospital networks. |
| ISO 13485 Certification Investment | Reduces vendor qualification cycles for European hospital procurement committees evaluating powered systems. |
| Soft Actuator Technology Licensing | Enables home-use prescription models that bypass facility-based reimbursement constraints in Japan. |
| Hospital System Partnership | Secures bundled service contracts with integrated delivery networks prioritizing total cost-of-ownership metrics. |
| Reimbursement Strategy | Expands addressable patient populations through Medicare coverage parity for powered versus passive exoskeleton categories. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with rehabilitation clinic directors, hospital GPO contract managers, biomedical engineers, occupational health officers at German automotive OEMs, and PMDA regulatory consultants. Secondary validation drew from FDA 510(k) filings, PMDA medical device approval databases, hospital procurement records, and ISO certification registries. Bottom-up installed base estimates were triangulated against top-down market sizing derived from reimbursement code utilization data.
Across the analysis window, forecasts model volume and value trajectories through segmented projections across product type, technology architecture, end-user category, and application channel. CAGRs were derived from regression analysis of historical procurement patterns against regulatory milestone timelines. Key inputs include FDA breakthrough designation velocity, PMDA approval queue depth, and German occupational health insurance mandate implementation rates.
Decision-makers should treat outputs as directional under assumptions of stable rare-earth supply and continued reimbursement expansion for powered rehabilitation systems; material deviation in Chinese export policy or CMS coverage determinations would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR notified body capacity constraints and Japanese METI standard evolution reshape market access timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Global Exoskeleton Market
Robotics and Automation
Malaysia Robotics Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Mobile Robot Charging Station Market
Robotics and Automation
Middle East and Africa Underwater Robotics Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Europe Educational Robot Market