
 Artificial Intelligence Oven Market | 2026-2036
Artificial Intelligence Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence Oven Market Insights
Commercial kitchens is reorganizing demand patterns away from traditional residential buyers as foodservice operators prioritize labor reduction and consistency at scale. Bosch leverages its industrial automation heritage to anchor European commercial installations. Samsung Electronics competes through IoT ecosystem integration that extends its smart-home platform into professional environments. Whirlpool sustains North American market presence through specialized product lines targeting high-volume bakery and restaurant segments.
An artificial intelligence oven integrates machine learning algorithms, sensor arrays, and connectivity protocols to autonomously adjust temperature curves, cooking duration, and humidity levels based on food recognition and user preferences. These systems typically incorporate thermal cameras, weight sensors, and cloud-based recipe databases to achieve precision outcomes with minimal operator intervention. Smart ovens currently lead value generation as consumers and professionals pay premiums for autonomous cooking capabilities. IoT-enabled technology segments are expanding fastest as interoperability demands from connected-kitchen ecosystems reshape procurement criteria. Multi-function ovens occupy mature margin pools where incremental AI upgrades command replacement premiums over conventional equipment.
The EU Green Deal and F-Gas Regulation shape European demand by mandating energy-efficiency thresholds that legacy ovens cannot satisfy. FDA food-safety guidelines in the United States influence sensor calibration standards and data-logging requirements for commercial AI oven deployments. China's GB standards and MIIT connectivity protocols govern electromagnetic compatibility and data localization for imported smart appliances. Stakeholders must monitor diverging regulatory timelines for energy labeling, data privacy, and equipment certification as these frameworks increasingly determine market access rather than merely product performance.
Market Dynamics
Commercial kitchen automation is compressing replacement cycles as foodservice operators confront persistent labor shortages and escalating wage pressure. The EU Green Deal's energy-efficiency mandates are forcing premature retirement of legacy thermal equipment across European foodservice operations.
Growth Catalysts
- Labor scarcity in foodservice:Commercial kitchens in Germany and France are deploying AI ovens to reduce dependency on skilled line cooks. Automation delivers consistency at scale where human capital constraints bite hardest.
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon restrictions are accelerating replacement of conventional convection ovens with refrigerant-free AI thermal systems. Equipment buyers face compliance deadlines that compress procurement timelines.
- Sensor fusion advancement:Thermal camera arrays combined with weight sensors enable autonomous doneness detection. This convergence reduces operator training requirements and expands deployable user bases.
Market Restraints
- Semiconductor supply concentration:AI oven production depends on specialized edge-computing chips concentrated in Taiwanese foundries. Geopolitical friction threatens component availability and pricing stability.
- Copper and rare-earth volatility:Magnet and wiring materials face extraction bottlenecks. Input cost swings compress OEM margins and complicate long-term equipment financing.
- Legacy kitchen infrastructure:Existing ventilation and electrical systems in older commercial facilities cannot support AI oven power and data requirements. Retrofit costs deter adoption in secondary locations.
Strategic Opportunities
- India cloud-kitchen expansion:The country's delivery-platform boom is creating demand for compact, autonomous cooking equipment. Swiggy and Zomato's dark-kitchen networks represent virgin deployment terrain.
- EU AI Act compliance services:Risk-management frameworks for automated food preparation create adjacent revenue streams. Vendors can bundle algorithmic audit capabilities with hardware sales.
- Edge-AI and 5G convergence:Low-latency connectivity enables real-time recipe optimization without cloud dependency. This pairing unlocks deployments in bandwidth-constrained environments.
Industry Challenges
- Mechatronics talent scarcity:The intersection of thermal engineering and machine-learning deployment requires hybrid skill sets. Foodservice OEMs compete with automotive and robotics sectors for limited personnel.
- CE marking timeline compression:Novel sensor configurations trigger extended electromagnetic compatibility testing. Certification delays stall product launches and strain working capital.
- Interoperability fragmentation:Competing IoT protocols from Samsung, Bosch, and Whirlpool create integration friction. Kitchen operators resist single-vendor lock-in despite ecosystem incentives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence Oven Market |
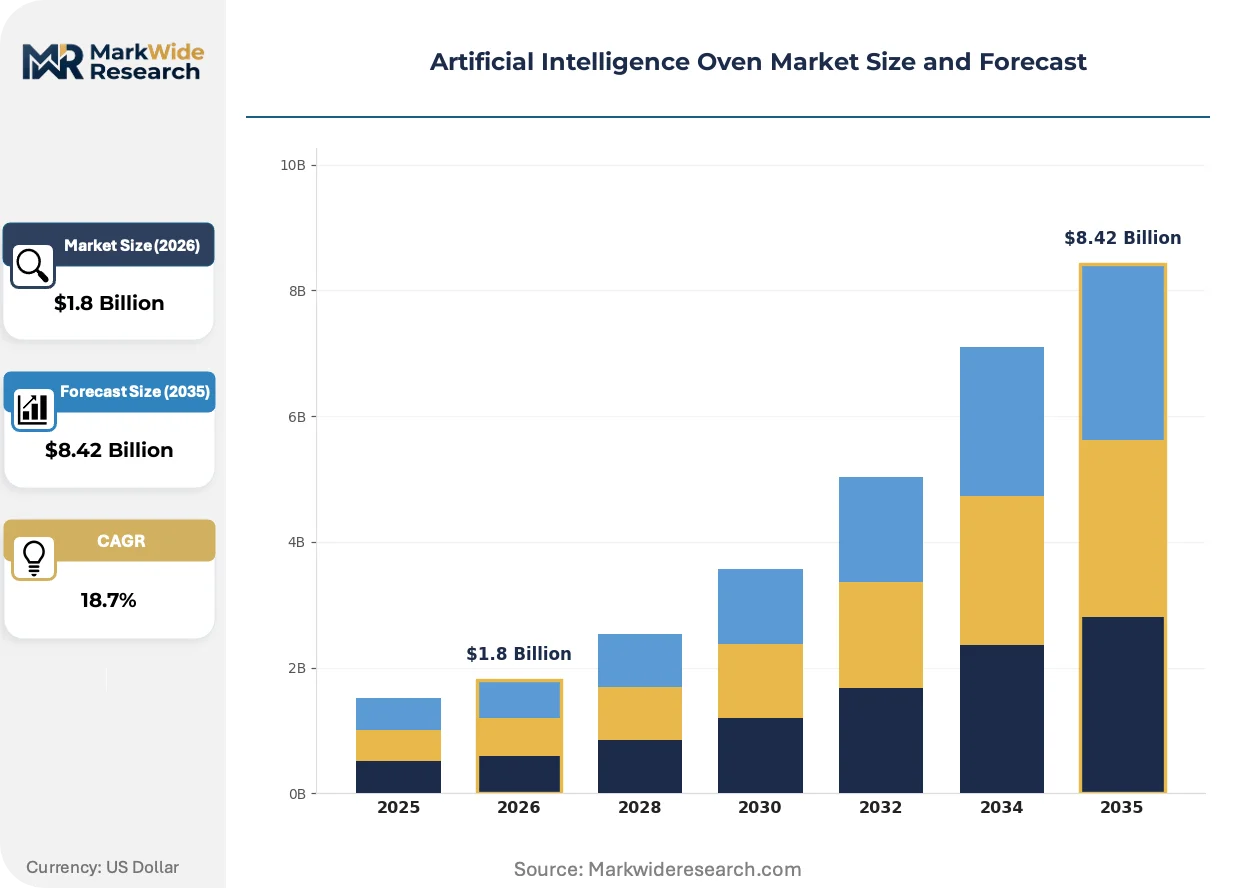
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Ovens, Conventional Ovens, Multi-Function Ovens, Built-in Ovens End User: Residential, Commercial Kitchens, Bakeries, Restaurants Technology: Voice-Activated, Touchscreen, IoT-Enabled, Automated Cooking Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Bosch, LG Electronics, Samsung Electronics, Whirlpool, Haier, Midea, June Oven, Welbilt, VIOMI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence Oven Market Trends and Innovations
Autonomous cooking systems are fragmenting into divergent technical architectures as end-use requirements splinter. Three forces are actively reconfiguring competitive terrain: edge-computing migration, regulatory compliance automation, and procurement model renovation.
Computer vision is bifurcating into two deployment modes. High-end installations employ multi-spectral thermal cameras for real-time crust analysis and moisture retention. Mid-market units rely on simpler RGB-based food recognition with cloud-assisted parameter tuning. Foodservice chains with standardized menus favor the stripped-down architecture, while fine-dining and bakery segments absorb premium sensor costs for precision outcomes.
The EU AI Act's risk-classification framework is mandating algorithmic transparency for commercial food-preparation equipment. Manufacturers must document decision pathways for temperature adjustments and safety shutoffs. German industrial bakery operators are demanding audit trails that satisfy both EFSA food-safety requirements and emerging AI accountability standards, compressing vendor development timelines.
Equipment-as-a-service contracts are displacing capital-expenditure purchases in North American restaurant chains. Subscription models bundle hardware, maintenance, and recipe-database updates into per-meal pricing. This structure transfers obsolescence risk to OEMs while aligning vendor incentives with uptime performance. Large franchise operators in Texas and California are piloting these arrangements to preserve balance-sheet flexibility.
Artificial Intelligence Oven Market Segmentation
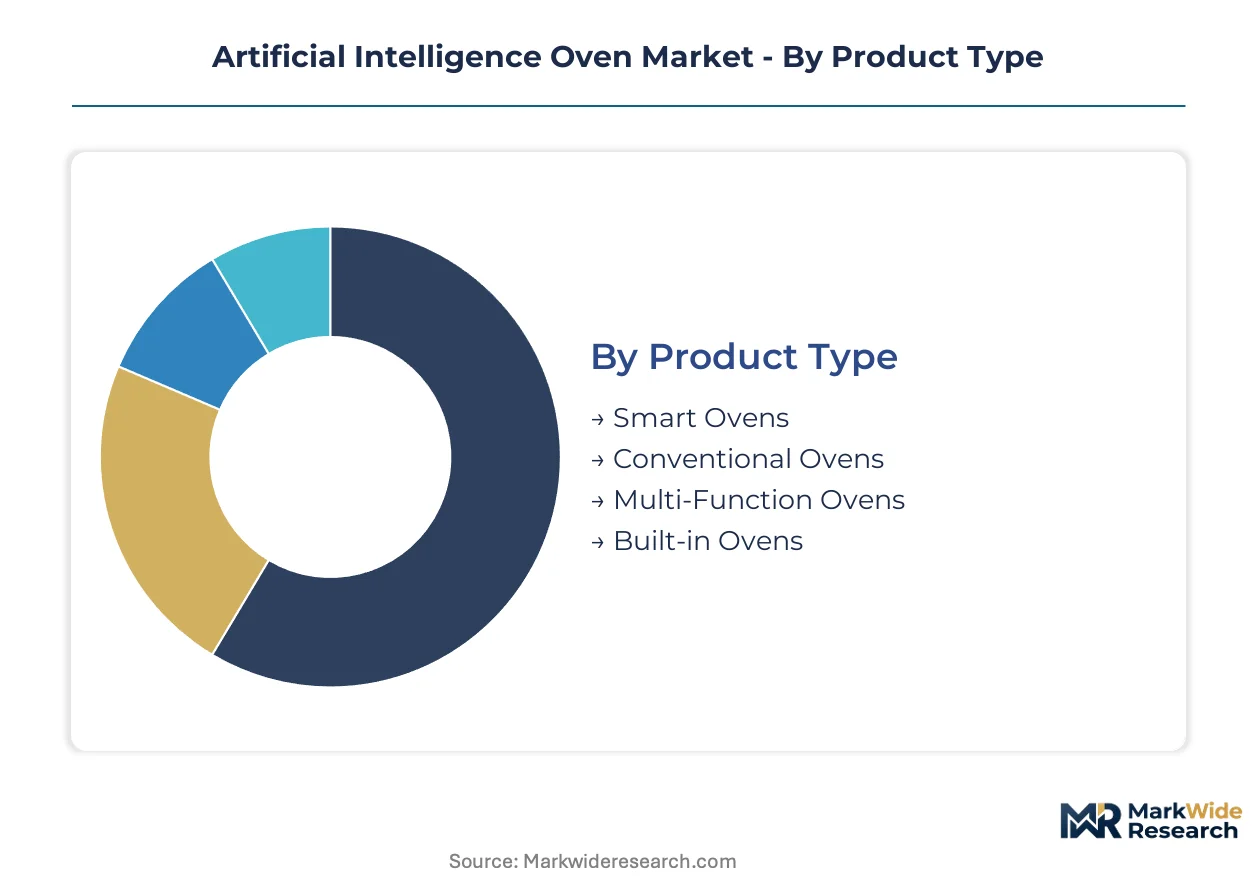
Segmentation in the AI oven market exposes divergent procurement logics across product tiers and installation environments. Regulatory compliance thresholds, connectivity protocols, and kitchen infrastructure constraints fragment demand patterns that vendors must navigate separately.
Product Type:
F-Gas Regulation phase-down deadlines and EU energy-labeling tiers split procurement criteria across product categories, with refrigerant-free thermal systems commanding compliance premiums.
- Smart Ovens:These units integrate machine-learning algorithms with sensor arrays for autonomous temperature and humidity adjustment. German industrial bakeries absorb premium costs for precision crust analysis and moisture retention capabilities where EFSA audit trails are mandatory.
- Multi-Function Ovens:Combines convection, steam, and microwave modalities under unified AI control. French foodservice chains deploy these for menu flexibility where labor scarcity demands equipment that substitutes for multiple line-cook functions.
- Conventional Ovens:Legacy thermal platforms with basic IoT retrofit kits for remote monitoring.
- Built-in Ovens:Architecturally integrated units for premium residential and flagship commercial installations.
Smart ovens handle the majority of throughput; multi-function ovens are expanding most quickly on share.
End User:
Cost tier differentiation separates capital-intensive commercial deployments from residential replacement cycles.
- Commercial Kitchens:High-volume foodservice operations deploy AI ovens to compress labor dependency and standardize output across locations. Texas and California restaurant chains pilot equipment-as-a-service contracts to preserve balance-sheet flexibility while accessing autonomous cooking capabilities.
- Bakeries:Precision thermal control for crust development and proofing automation. German operators demand multi-spectral thermal cameras and algorithmic audit trails that satisfy both EU AI Act risk-classification requirements and EFSA food-safety documentation.
- Residential:Smart-home ecosystem integration drives replacement decisions.
- Restaurants:Table-service establishments prioritize consistency and speed of execution.
Commercial kitchens absorb the dominant share of unit volume; bakeries are climbing the fastest as regulatory deadlines compress procurement timelines.
Technology:
Volume concentration favors connectivity standards that integrate with existing kitchen management systems.
- IoT-Enabled:Cloud-connected platforms supporting real-time recipe optimization and predictive maintenance. India's Swiggy and Zomato dark-kitchen networks represent virgin deployment terrain where low-latency 5G convergence enables bandwidth-constrained operations.
- Automated Cooking:Fully autonomous systems with sensor fusion for doneness detection. Thermal camera arrays combined with weight sensors reduce operator training requirements, expanding deployable user bases in markets facing mechatronics talent scarcity.
- Voice-Activated:Hands-free operation protocols for hygiene-critical environments.
- Touchscreen:Direct interface systems for recipe selection and parameter adjustment.
IoT-enabled platforms carry the bulk of current installations; automated cooking systems are gaining share fastest as sensor fusion matures.
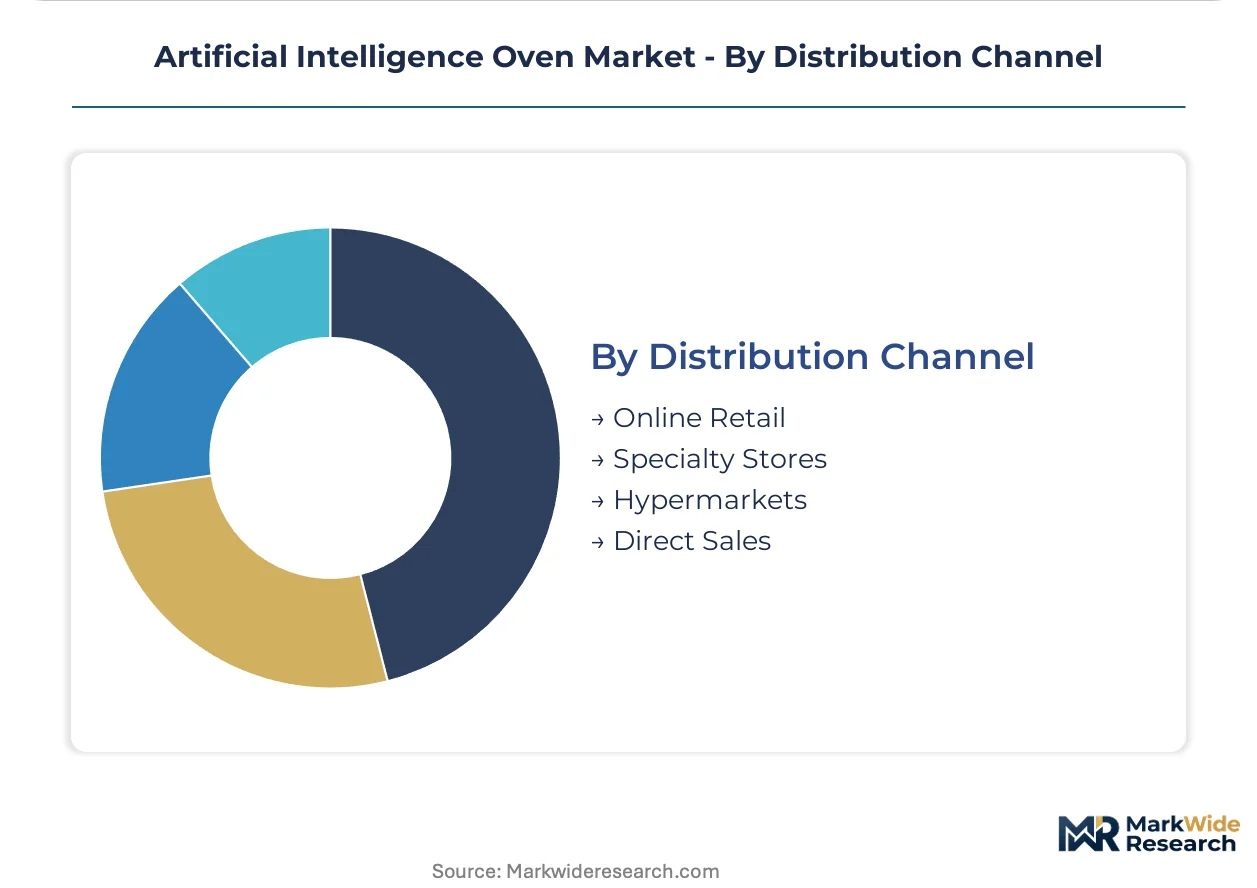
Distribution Channel:
Margin structure varies sharply between direct commercial relationships and retail intermediation.
- Direct Sales:OEM-managed contracts for large foodservice chains and industrial bakeries. Subscription bundling of hardware, maintenance, and recipe-database updates transfers obsolescence risk to vendors while aligning incentives with uptime performance.
- Online Retail:E-commerce platforms capture residential and small-commercial demand. Procurement friction here centers on interoperability verification across competing IoT protocols.
- Specialty Stores:Consultant-led specification for premium installations.
- Hypermarkets:Mass-market volume for entry-tier residential units.
Direct sales channels dominate commercial throughput; online retail is expanding most rapidly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial oven manufacturers export precision thermal systems to North American foodservice chains, while South Korean electronics conglomerates supply AI-enabled cooking platforms to Asian cloud-kitchen operators.
United States
Texas and California restaurant chains pilot equipment-as-a-service contracts to preserve balance-sheet flexibility while accessing autonomous cooking capabilities. FDA food-safety guidelines influence sensor calibration standards and data-logging requirements for commercial AI oven deployments. Dallas-Fort Worth foodservice operators concentrate procurement activity where labor scarcity demands kitchen automation at scale.
Germany
Industrial bakery automation and premium residential smart-kitchen investments overlap to concentrate demand in Europe's largest economy. The EU Green Deal's energy-efficiency mandates and F-Gas Regulation phase-down accelerate replacement cycles across foodservice operations. Munich and Stuttgart industrial clusters anchor Bosch's commercial installation base for precision thermal systems.
China
Domestic appliance giants leverage manufacturing scale to serve both export markets and rapidly urbanizing consumer bases. GB standards and MIIT connectivity protocols govern electromagnetic compatibility and data localization for imported smart appliances. Shenzhen and Guangzhou electronics corridors concentrate edge-computing chip integration for cost-optimized AI oven platforms.
India
Swiggy and Zomato's dark-kitchen networks create virgin deployment terrain for compact, autonomous cooking equipment. BIS certification requirements and FSSAI food-safety standards shape import compliance timelines for international OEMs. Bangalore and Mumbai cloud-kitchen clusters absorb initial equipment volumes where delivery-platform boom compresses procurement decisions.
France
Foodservice chains deploy multi-function ovens for menu flexibility where labor scarcity demands equipment substituting for multiple line-cook functions. EFSA food-safety documentation requirements and emerging EU AI Act risk-classification frameworks compress vendor development timelines. Lyon and Paris metropolitan foodservice operators concentrate adoption of refrigerant-free thermal systems ahead of F-Gas compliance deadlines.
Artificial Intelligence Oven Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D velocity dimensions. The vendor base separates into three tiers: diversified electronics conglomerates with IoT ecosystem breadth, dedicated appliance OEMs with foodservice channel depth, and venture-backed specialists with sensor fusion IP. Strategic moves concentrate on M&A for thermal engineering talent and strategic partnerships for cloud-kitchen operator access.
Within the diversified conglomerate tier, Samsung Electronics and LG Electronics occupy positions defined by smart-home platform extension into professional environments. Bosch exemplifies the industrial automation heritage archetype, anchoring European commercial installations through precision thermal engineering capabilities. June Oven represents the venture-backed specialist model, sitting within the sensor fusion innovation cluster where algorithmic food recognition commands premium positioning.
| Leading Market Players |
|---|
| Bosch |
| LG Electronics |
| Samsung Electronics |
| Whirlpool |
| Haier |
| Midea |
| June Oven |
| Welbilt |
| VIOMI |
| Others |
Pricing and Supply Chain Analysis
CE marking and electromagnetic compatibility certification gates both supplier qualification and price stratification in European AI oven procurement. Buyers face tiered access costs where compliance documentation separates premium sensor-fusion platforms from basic IoT retrofit units, compressing margin pools for non-certified entrants.
Pricing Analysis
Current-generation sensor-fusion ovens with multi-spectral thermal cameras command substantial premiums over prior-generation RGB-based recognition systems, while next-generation edge-AI platforms with 5G convergence are pricing at experimental contract rates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in mid-market units is intensifying because semiconductor foundry concentration limits component availability. Foodservice chains exhibit highest price sensitivity due to equipment-as-a-service contract structures, while German industrial bakeries absorb premium costs for EFSA-compliant audit trail capabilities.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints at Rotterdam and Hamburg are elevating inbound logistics costs for edge-computing chip shipments. AI oven production draws from Taiwanese semiconductor foundries, South Korean display panel manufacturers, and Chinese sensor module assemblers. Magnet and copper wiring materials face extraction bottlenecks in Chile and Indonesia. Single-source vulnerability in specialized edge-AI processors threatens component availability. Distribution runs through direct OEM contracts for commercial chains and online retail platforms for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI oven penetration remains in early-cycle expansion as cloud-kitchen deployment accelerates across India's delivery-platform networks. Labor scarcity in European foodservice operations sustains replacement demand for autonomous cooking equipment.
For Market Incumbents: Compound channel control through equipment-as-a-service contract expansion in North American restaurant chains to lock out emerging IoT platform competitors. Deepen captive supply of edge-computing chips through strategic foundry partnerships, insulating against Taiwan semiconductor concentration risk. Accelerate CE marking pre-certification for novel sensor configurations to compress product launch timelines relative to challengers.
For New Entrants and Emerging Players: Lead with sensor fusion IP licensing to cloud-kitchen operators in India's Swiggy and Zomato networks, where virgin deployment terrain lacks incumbent lock-in. Target French foodservice chains with multi-function oven architectures that substitute for multiple line-cook functions amid acute labor scarcity. Pursue white-label manufacturing partnerships with Chinese appliance OEMs to bypass Bosch and Samsung ecosystem barriers.
For Investors and Strategic Acquirers: The EU AI Act's risk-classification framework reshapes the acquisition landscape by mandating algorithmic transparency documentation that venture-backed specialists possess but diversified conglomerates lack. Position holdings for 5-10 year horizon as regulatory compliance automation creates durable competitive moats. Target acquisition candidates with hybrid mechatronics talent pools spanning thermal engineering and machine-learning deployment. Monitor F-Gas Regulation phase-down deadlines as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chip Supply Agreement | Secures Taiwanese foundry capacity ahead of geopolitical friction. |
| Cloud-Kitchen Operator Partnership | Unlocks virgin deployment terrain in India's Swiggy and Zomato networks. |
| EU AI Act Compliance Service Bundling | Creates adjacent revenue streams alongside German industrial bakery hardware sales. |
| Equipment-as-a-Service Platform Launch | Transfers obsolescence risk to OEMs while aligning incentives with Texas restaurant chain uptime. |
| Multi-Spectral Thermal Camera Integration | Commands premium positioning in EFSA audit trail-compliant German bakery installations. |
Research Methodology
Operator-level perspectives from foodservice procurement directors, industrial bakery maintenance heads, cloud-kitchen operations managers, and smart-home platform engineers anchored the qualitative base. Primary interview insights combined with secondary validation from SEC equipment manufacturer filings, EU energy-labeling databases, FDA food-safety guidance documents, and BIS appliance certification records. Bottom-up unit deployment estimates triangulated against top-down market sizing from customs trade data and commercial kitchen equipment import records.
Sensitivity analysis around semiconductor availability scenarios and F-Gas Regulation compliance deadlines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user category, technology protocol, and distribution channel structure. CAGRs derived from weighted average of historical replacement cycle compression rates and regulatory mandate acceleration effects. Forecast inputs incorporated edge-AI chip foundry capacity expansion timelines and 5G network rollout patterns in target deployment geographies.
The analysis sits within stated boundaries; outcomes outside sustained labor scarcity in foodservice, stable Taiwan semiconductor supply, and EU regulatory timeline adherence would require recalibration. Forecasts reflect documented assumptions regarding sensor fusion maturation curves and cloud-kitchen network expansion velocity. Geopolitical friction in semiconductor supply, copper price volatility, and CE marking timeline extensions represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Cognitive Computing Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
North America Conversational AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Stadium Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market