
 Global Mobile Robots Market | 2026-2036
Global Mobile Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Robots Market Foresight
The EU Green Deal is decoupling warehouse automation from carbon-intensive material flows by mandating energy-efficient fleet operations in European logistics hubs. Amazon Robotics leverages its captive fulfillment network to dominate North American deployments. Locus Robotics specializes in collaborative pick-and-place architectures for mid-size warehouse operators. Geek+ anchors Asia-Pacific demand through dense manufacturing partnerships in China and South Korea.
Global mobile robots are self-propelling electromechanical platforms integrating locomotion subsystems, sensor arrays, and onboard compute to execute tasks without fixed infrastructure or continuous human teleoperation. These systems typically operate at speeds below two meters per second and rely on simultaneous localization and mapping for dynamic path planning in unstructured environments. Autonomous mobile robots now lead unit shipments across material handling applications where LiDAR-based navigation enables real-time obstacle avoidance in shared human-robot zones. Automated guided vehicles retain maturity in automotive assembly lines where magnetic tape or QR-guided routes deliver predictable throughput at lower unit cost.
FDA device regulations, OSHA workplace safety standards, and CE marking under the EU Machinery Directive collectively shape product liability, human-robot collaboration protocols, and market access thresholds across major economies. The EU AI Act introduces additional conformity requirements for autonomous decision-making systems that will filter into procurement specifications for European buyers. Stakeholders must monitor how diverging safety certification timelines between American and European regulators affect cross-border deployment strategies and platform standardization roadmaps.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-ship cycles through dense mobile robot deployments, forcing warehouse operators to reconfigure floor layouts and labor allocation around autonomous fleet orchestration rather than retrofitting automation into existing infrastructure.
Growth Catalysts
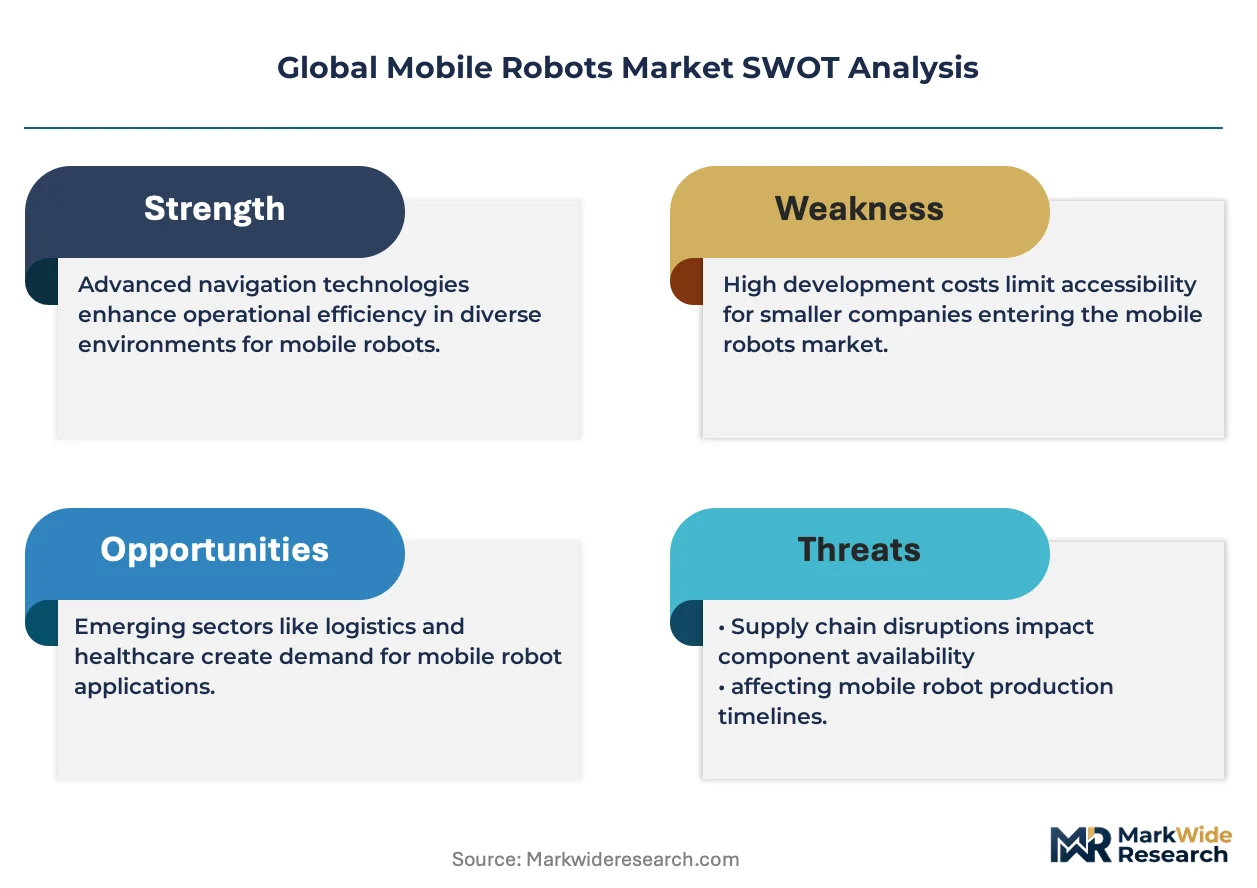
- EU AI Act compliance mandates:European procurement specifications now require algorithmic transparency documentation for autonomous decision-making systems, accelerating replacement of legacy AGV fleets with certifiable AMR platforms in German and French logistics hubs.
- LiDAR sensor cost curves:Solid-state ranging modules are penetrating mid-size warehouse budgets that previously relied on camera-only navigation, expanding addressable market for collaborative pick-and-place architectures.
- Automotive assembly reshoring:Battery cell manufacturing investments in Hungary and Poland are generating concentrated demand for magnetic-tape guided vehicles in cleanroom material transport applications.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material refining capacity clusters in China's Jiangxi and Hunan provinces, exposing European and North American robot OEMs to input cost volatility and forced supplier qualification delays.
- CE marking timeline friction:EU Machinery Directive conformity assessment for autonomous systems requires notified body intervention that extends product launch cycles by eight to fourteen months versus FDA 510(k) pathways.
- Fixed infrastructure legacy lock-in:Existing QR-code and magnetic-tape guided installations in Japanese automotive plants create switching costs that retard AMR migration despite superior flexibility metrics.
Strategic Opportunities
- India warehouse automation underpenetration:Third-party logistics operators in Mumbai and Delhi-NCR corridors are piloting AMR fleets for pharmaceutical cold chain handling ahead of CDSCO distribution integrity mandates.
- EU Green Deal fleet electrification incentives:Energy-efficient mobile robot operations qualify for carbon border adjustment offsets in Dutch and Belgian port logistics, redirecting procurement toward battery-swappable platform architectures.
- 5G private network convergence:Ultra-reliable low-latency connectivity is enabling edge-compute offloading that reduces onboard processing weight and extends operational runtime for heavy-payload autonomous forklifts.
Industry Challenges
- SLAM algorithm talent scarcity:Simultaneous localization and mapping expertise concentrates in robotics research clusters at ETH Zurich and TU Munich, forcing vendors to compete for limited firmware engineering capacity.
- Multi-vendor fleet interoperability:Lack of standardized communication protocols between Kiva-style cube storage systems and conveyor-fed AMR pickers complicates brownfield integration in omnichannel fulfillment centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Robots Market |
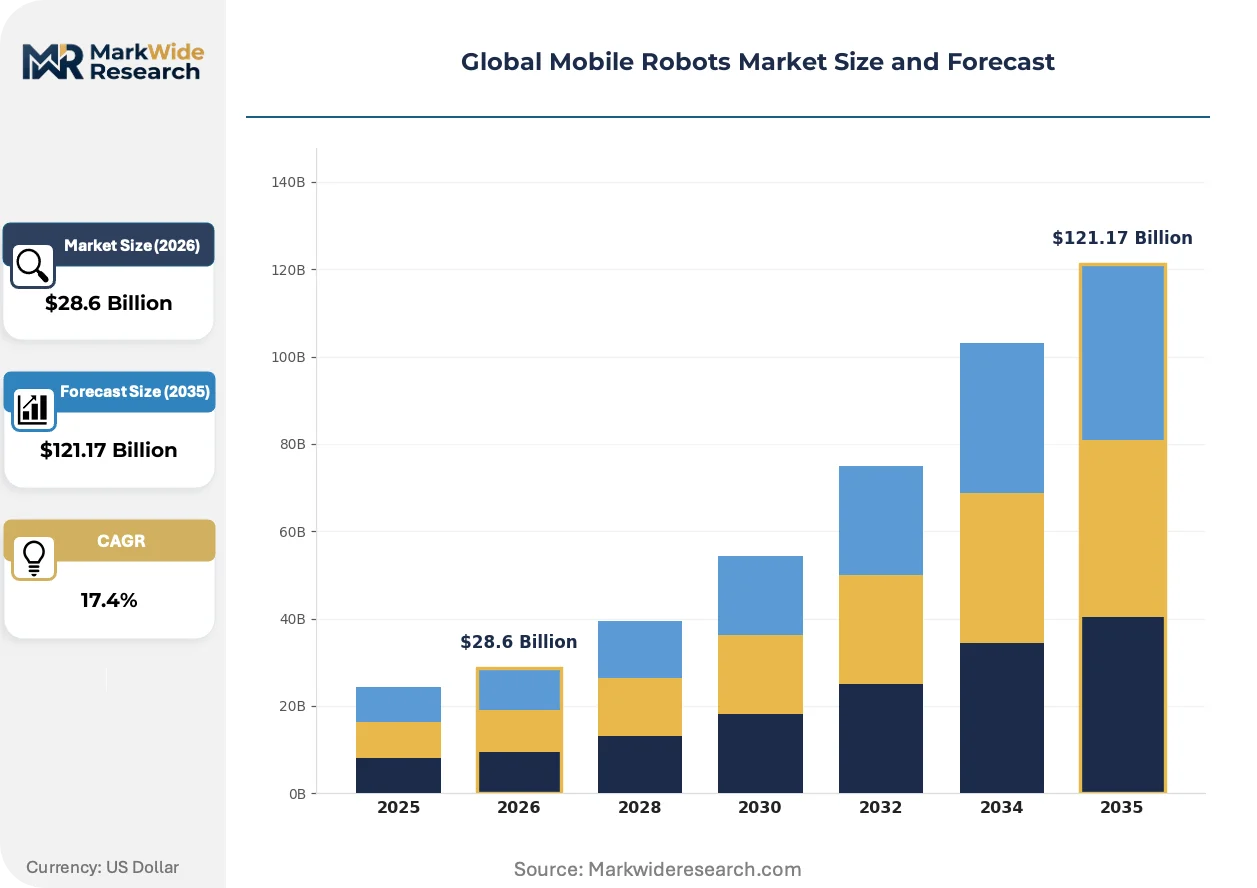
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $121.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Autonomous Mobile Robots, Automated Guided Vehicles, Humanoid Robots, Collaborative Robots Technology: LiDAR, Computer Vision, Ultrasonic Sensors, Infrared Sensors, GPS Navigation Application: Material Handling, Surveillance & Inspection, Delivery Services, Agriculture Automation End User: Warehouse Operators, Security Firms, Agricultural Producers, E-commerce Fulfillment Centers |
| Companies Covered | Locus Robotics, OTTO Motors, Amazon Robotics, Agility Robotics, Seegrid, Mobile Industrial Robots, GreyOrange, Boston Dynamics, Geek+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Robots Market Shifts & Advancements
Navigation and compute architectures are converging toward edge-light designs that trade onboard processing for distributed intelligence, compressing unit economics while expanding deployment scenarios into temperature-extreme and dust-contaminated environments.
Computer vision-based localization is integrating semantic scene understanding that distinguishes between permanent infrastructure and transient obstacles. Automotive tier-one suppliers in Stuttgart and Wolfsburg are qualifying these systems for sequencing applications where毫米级 positioning accuracy prevents assembly line stoppages. The technology is integrating predictive maintenance APIs that preempt actuator degradation before fault codes trigger downtime.
REACH substance restrictions on per- and polyfluoroalkyl compounds are forcing battery enclosure manufacturers toward alternative thermal interface materials. Robot OEMs sourcing from German and Italian suppliers face reformulation timelines that compress product certification windows. European warehouse operators are responding by front-loading procurement of compliant platforms ahead of 2026 enforcement deadlines.
Leasing structures are displacing capital purchase models among mid-size third-party logistics operators in the United Kingdom and Netherlands. Robot-as-a-service contracts bundle maintenance, software updates, and throughput guarantees into per-pick pricing that aligns vendor incentives with operational uptime. This shift is most visible in grocery e-commerce fulfillment where seasonal volume spikes make fixed asset ownership economically unattractive.
Global Mobile Robots Market Segmentation
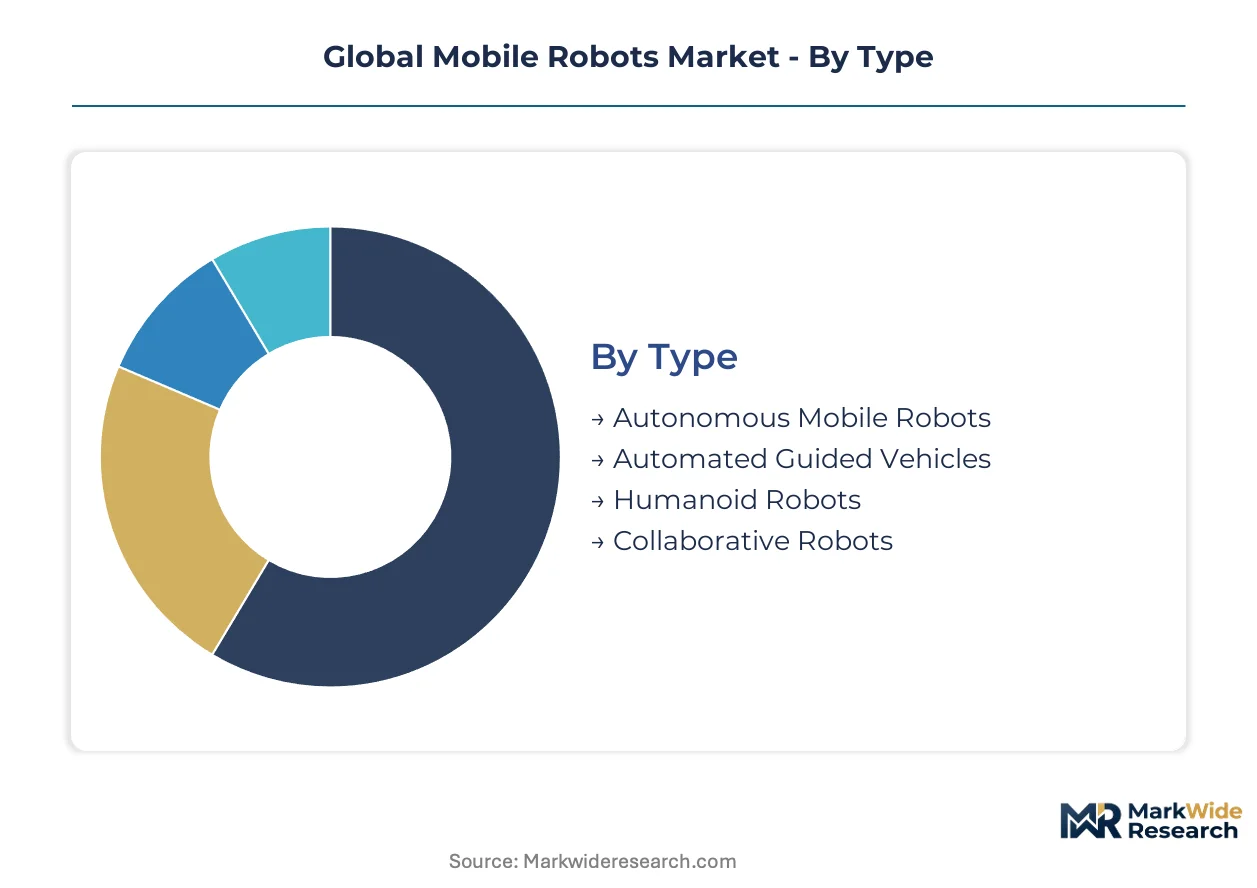
Mobile robot procurement decisions hinge on navigation maturity, payload specifications, and integration complexity with existing warehouse management systems. Segment boundaries blur as vendors bundle sensor modalities and software stacks into unified platform offerings.
Type:
Budget flexibility and operational risk tolerance determine platform selection across fulfillment and manufacturing environments.
- Autonomous Mobile Robots:Self-navigating platforms deploy simultaneous localization and mapping to operate without floor-mounted infrastructure. German automotive suppliers in Stuttgart and Wolfsburg are standardizing AMR fleets for just-in-time component sequencing to assembly lines, driven by EU AI Act documentation requirements for autonomous decision-making systems.
- Automated Guided Vehicles:Magnetic-tape or QR-code guided systems follow predetermined routes at lower capital cost. Polish and Hungarian battery cell manufacturing facilities are expanding AGV deployments for cleanroom material transport, constrained by the eight-to-fourteen-month CE marking timelines under the EU Machinery Directive.
- Humanoid Robots:Bipedal platforms target unstructured manipulation tasks in logistics and retail settings.
- Collaborative Robots:Force-limited arms and mobile bases enable shared workspace operation alongside human pickers.
Volume sits with Automated Guided Vehicles; growth tilts toward Autonomous Mobile Robots.
Technology:
Sensor cost curves and compute requirements shape navigation stack economics for mid-size operators.
- LiDAR:Solid-state ranging modules generate dense point clouds for centimeter-level positioning in dynamic environments. Solid-state LiDAR price declines are penetrating warehouse budgets that previously relied on camera-only systems, expanding addressable market for collaborative architectures in Dutch and Belgian port logistics.
- Computer Vision:Camera arrays paired with neural networks enable semantic scene understanding and object recognition. Computer vision localization is gaining share in temperature-extreme and dust-contaminated environments where mechanical LiDAR degradation accelerates.
- Ultrasonic Sensors:Short-range proximity detection complements primary navigation modalities.
- Infrared Sensors:Thermal imaging supports surveillance and night-time operation protocols.
- GPS Navigation:Satellite positioning enables outdoor fleet coordination for yard logistics and agricultural applications.
Procurement concentrates on LiDAR for indoor precision; Computer Vision is expanding most quickly in edge-light deployments.
Application:
Throughput guarantees and labor substitution economics drive deployment prioritization across verticals.
- Material Handling:Pick-and-place, transport, and sortation operations dominate unit economics in fulfillment networks. E-commerce operators in the United Kingdom and Netherlands are compressing order-to-ship cycles through dense fleet orchestration, reconfiguring floor layouts around autonomous coordination rather than retrofitting into existing infrastructure.
- Surveillance & Inspection:Mobile sensor platforms patrol perimeters and monitor equipment condition. Security firms are piloting autonomous patrol robots for pharmaceutical cold chain facilities in Mumbai and Delhi-NCR corridors ahead of CDSCO distribution integrity mandates.
- Delivery Services:Last-mile autonomous vehicles navigate sidewalks and roadways for parcel distribution.
- Agriculture Automation:Crop monitoring and precision spraying applications deploy in open-field environments.
Revenue concentrates in Material Handling; Surveillance & Inspection is gaining share fastest in regulated pharmaceutical logistics.
End User:
Scale and seasonality determine ownership versus leasing preferences across customer types.
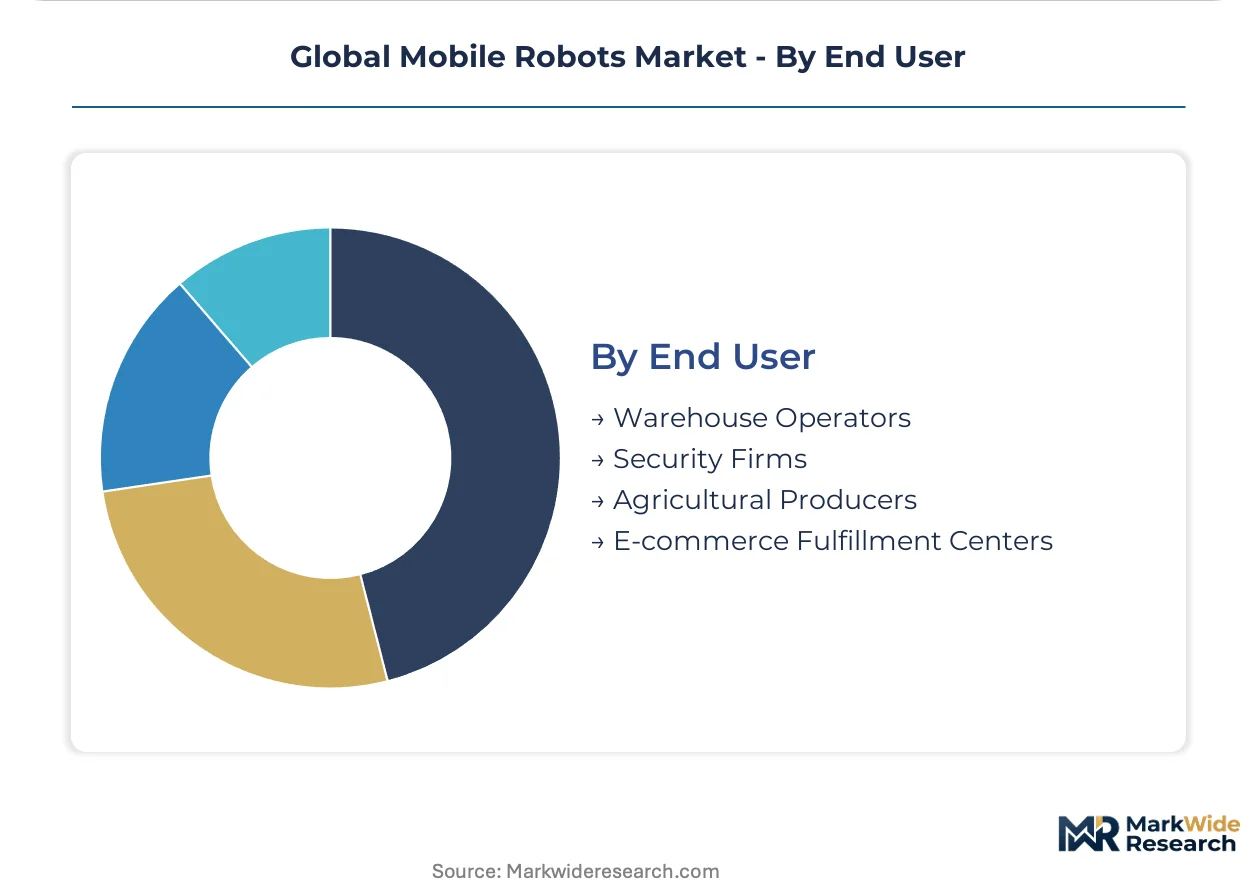
- Warehouse Operators:Third-party logistics providers balance capital efficiency against throughput commitments. Robot-as-a-service contracts are displacing capital purchases among mid-size UK and Netherlands operators, bundling maintenance and software updates into per-pick pricing that aligns vendor incentives with uptime.
- E-commerce Fulfillment Centers:Captive networks optimize for peak season surge capacity and same-day delivery SLAs. Amazon's captive fulfillment infrastructure dominates North American deployment volumes, forcing competing operators toward multi-vendor fleet strategies.
- Security Firms:Patrol and monitoring service providers evaluate autonomous platforms for labor cost reduction.
- Agricultural Producers:Large-scale farming operations deploy autonomous tractors and harvest monitoring systems.
Deployment scale sits with E-commerce Fulfillment Centers; contract structure innovation tilts toward Warehouse Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European mobile robot demand through dense automotive supplier networks that standardize AMR fleets for just-in-time assembly sequencing. Battery cell manufacturing investments in Hungary and Poland are generating parallel demand for cleanroom material transport systems. Japanese automotive plants retain magnetic-tape guided infrastructure that slows AMR migration despite superior flexibility metrics.
United States
Amazon's captive fulfillment network dominates deployment volumes, forcing competing operators toward multi-vendor fleet strategies. OSHA workplace safety standards and FDA device regulations shape human-robot collaboration protocols and product liability frameworks. Greater Boston and Pacific Northwest robotics clusters concentrate SLAM algorithm talent that vendors compete to acquire.
Germany
EU AI Act documentation requirements for autonomous decision-making systems accelerate replacement of legacy AGV fleets with certifiable AMR platforms. CE marking under the EU Machinery Directive extends product launch cycles through notified body intervention. Stuttgart and Wolfsburg automotive suppliers standardize AMR fleets for millimeter-accurate component sequencing to assembly lines.
China
Dual carbon goals and MIIT industrial automation directives concentrate investment in battery-swappable platform architectures for port logistics. Cathode material refining capacity in Jiangxi and Hunan provinces exposes robot OEMs to input cost volatility. Yangtze River Delta manufacturing partnerships anchor Asia-Pacific demand through dense electronics and automotive supplier networks.
India
CDSCO distribution integrity mandates drive pilot AMR deployments for pharmaceutical cold chain handling in Mumbai and Delhi-NCR corridors. PLI scheme incentives for electronics manufacturing attract component suppliers that require automated material transport. Third-party logistics operators balance capital efficiency against throughput commitments through emerging robot-as-a-service contracts.
Japan
METI industrial automation roadmaps emphasize collaborative architectures for aging workforce support in manufacturing. Existing QR-code and magnetic-tape guided installations in automotive plants create switching costs that retard AMR migration. Kanto and Kansai industrial corridors retain AGV maturity where predictable throughput outweighs flexibility premiums.
Global Mobile Robots Market Competitive Landscape
Premium-margin players sit above commodity-margin players across navigation sophistication and software integration depth. The vendor base stratifies between captive fulfillment operators, collaborative pick-and-place specialists, and industrial automation incumbents. Three archetypes dominate: vertically integrated logistics platforms, modular AMR pure-plays, and diversified industrial conglomerates. M&A activity concentrates on SLAM algorithm acquisitions and fleet management software assets.
Within the collaborative pick-and-place tier, Locus Robotics exemplifies the mid-size warehouse operator focus. Among diversified technology holdings, Boston Dynamics occupies a position at the humanoid and advanced mobility frontier. Geek+ anchors the Asia-Pacific manufacturing partnership archetype through dense supplier network integration.
| Leading Market Players |
|---|
| Locus Robotics |
| OTTO Motors |
| Amazon Robotics |
| Agility Robotics |
| Seegrid |
| Mobile Industrial Robots |
| GreyOrange |
| Boston Dynamics |
| Geek+ |
| Others |
Supply & Pricing Matrix
SLAM algorithm talent clusters in Stuttgart and Munich widen labor-cost differentials between German-engineered premium tiers and Asian-manufactured economy platforms, compressing mid-market pricing spreads as vendors arbitrage firmware development across regulatory jurisdictions.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for robot-as-a-service deployments, with per-pick rates scaling by uptime commitments and software update frequency. Price differentiation separates CE-marked AMR platforms with EU AI Act documentation from magnetic-tape AGV systems lacking autonomous decision transparency. Pricing pressure stems from solid-state LiDAR cost compression penetrating mid-size warehouse budgets. E-commerce fulfillment centers exhibit lowest price sensitivity due to captive network scale; third-party logistics operators in India and Southeast Asia face acute capital constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and automotive tier-one suppliers, while distributor networks serve mid-size warehouse operators in fragmented European logistics hubs. Cathode material refining concentrates in China's Jiangxi and Hunan provinces, with South Korean and Japanese battery cell manufacturers providing secondary sourcing. Lithium carbonate and nickel sulfate feedstocks, solid-state LiDAR modules, and precision actuator assemblies constitute critical input dependencies. Single-source vulnerability in Chinese rare-earth magnet supply creates exposure to export licensing disruptions. Distribution runs through systems integrators in Stuttgart and Boston robotics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over SLAM algorithm development and fleet management software stacks determines margin capture. Players are pursuing backward integration into sensor module manufacturing to escape LiDAR supplier concentration.
For Market Incumbents: Deepen captive control over LiDAR sensor supply through equity stakes in solid-state ranging module manufacturers, insulating against Chinese cathode material price volatility. Expand CE marking pre-certification capacity in Germany to compress the eight-to-fourteen-month conformity timeline that delays European product launches. Fortify position against collaborative robot pure-plays by bundling predictive maintenance APIs into long-term service contracts. For New Entrants and Emerging Players: EU AI Act compliance mandates in Germany and France open a window for algorithmic transparency documentation specialists to capture replacement demand from legacy AGV fleets. Target pharmaceutical cold chain logistics in India ahead of CDSCO distribution integrity enforcement. Lead with robot-as-a-service pricing to bypass capital-constrained third-party logistics operators in Mumbai and Delhi-NCR corridors. For Investors and Strategic Acquirers: The window for entry favors fleet management software assets with proven multi-vendor orchestration capabilities. Long-term viability rests on platforms demonstrating interoperability between Kiva-style cube storage and conveyor-fed AMR architectures. Monitor 5G private network deployment velocity in Dutch and Belgian port logistics as inflection signal for edge-compute offloading adoption.| Strategic Initiative | Industry Significance |
|---|---|
| SLAM Algorithm Acquisition | ETH Zurich and TU Munich research spinouts consolidate scarce firmware engineering capacity for autonomous navigation. |
| Battery-Swappable Platform Development | EU Green Deal carbon border adjustment offsets in Dutch port logistics reward energy-efficient fleet electrification architectures. |
| CE Marking Pre-Certification Investment | Notified body partnerships in Germany compress EU Machinery Directive conformity timelines versus standard pathways. |
| Robot-as-a-Service Contract Scaling | Per-pick pricing bundles align vendor incentives with uptime guarantees for UK grocery e-commerce fulfillment operators. |
| 5G Private Network Integration | Ultra-reliable low-latency connectivity enables edge-compute offloading that extends runtime for heavy-payload autonomous forklifts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with warehouse operations directors, fleet management software engineers, automotive tier-one procurement leads, and notified body certification specialists. Triangulation combined bottom-up deployment tracking across German automotive plants and top-down vendor revenue analysis. FDA 510(k) filings, EU Machinery Directive conformity databases, and MIIT industrial automation directives provided regulatory validation.
Data-stream reconciliation across shipment volumes, installation records, and service contract disclosures informed the analytical framework. Segmentation dimensions modeled include navigation technology maturity, payload specification tiers, integration complexity with warehouse management systems, and regional regulatory cluster patterns. CAGRs were derived from logistic diffusion curves fitted to adoption velocity in e-commerce fulfillment networks. Solid-state LiDAR cost trajectories and EU AI Act implementation timelines constituted industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for computer-vision-only navigation would alter the outlook if mechanical LiDAR degradation rates in dust-contaminated environments prove overstated. Forecasts reflect assumptions about CE marking timeline convergence and lithium-ion cell supply diversification that regulatory friction or geopolitical disruption could revise. Practitioners should monitor CDSCO enforcement velocity in India and REACH substance restriction compliance deadlines in German battery enclosure supply chains for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Sweden Robotic Lawn Mower Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market