
 NFT Creation Software Market | 2026-2036
NFT Creation Software Market Size, Share, and Industry Trends Forecast 2026-2036
NFT Creation Software Market Insights
Ethereum mining pools in North America is consolidating hashrate into fewer operational zones, concentrating the infrastructure that underpins most NFT minting transactions. OpenSea leverages its first-mover liquidity network to sustain dominant listing volumes across digital art and collectibles. Coinbase anchors institutional credibility through regulated custody integrations that appeal to risk-averse creators. LeewayHertz differentiates via custom smart contract development services for enterprise clients entering tokenized asset markets.
NFT creation software encompasses applications that generate, mint, and manage non-fungible tokens through cryptographic hashing on distributed ledgers, typically requiring ERC-721 or ERC-1155 smart contract deployment with metadata storage via IPFS or Arweave. These tools enable verifiable digital scarcity for creators, collectors, and brands seeking programmable ownership without intermediary authentication. Digital art commands the largest share of minting activity, though sports collectibles represents the fastest-expanding category as leagues and athletes tokenize highlights and memorabilia. Blockchain technology underpins all transactional functionality, while smart contracts automate royalty distributions that attract musicians and recurring-revenue-seeking artists.
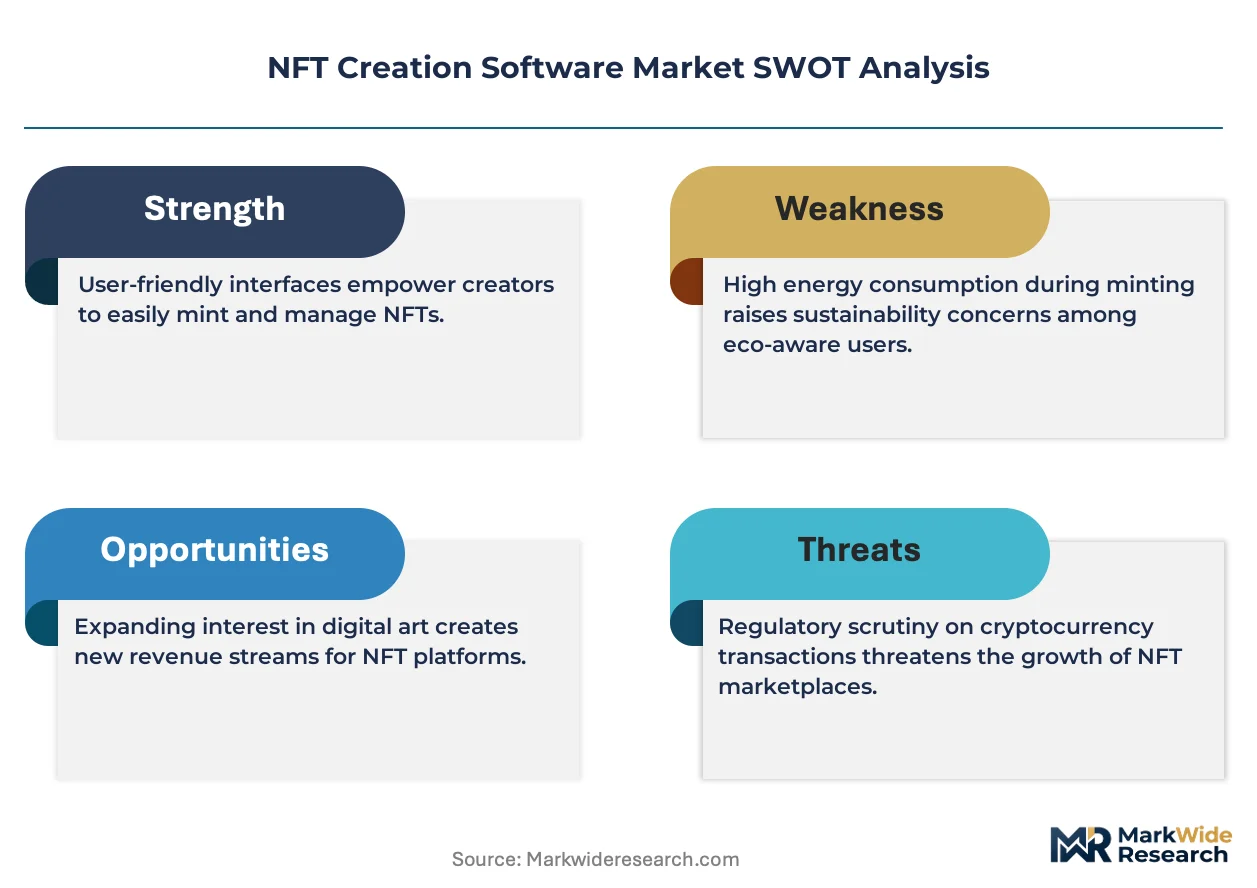
The SEC in the United States scrutinizes token offerings for securities law compliance, pressuring platforms to implement investor accreditation checks and disclosure protocols. The EU's MiCA framework mandates licensing for crypto-asset service providers, reshaping marketplace access requirements across member states. Creators and platform operators must monitor enforcement patterns to determine whether jurisdictional relocation or compliance investment offers superior risk-adjusted returns.
Market Dynamics
Ethereum's transition to proof-of-stake consensus has restructured gas fee economics for NFT minting operations, compressing per-transaction costs while redistributing validator rewards toward institutional staking pools. This foundational shift alters creator platform selection criteria and smart contract deployment patterns across the ecosystem.
Growth Catalysts
- MiCA Licensing Framework:The EU's Markets in Crypto-Assets regulation establishes clear compliance pathways for token issuers, reducing jurisdictional uncertainty for European creators and marketplace operators seeking legal clarity.
- Layer-2 Scaling Infrastructure:Polygon and Arbitrum rollups now process bulk minting transactions at fractional mainnet costs, enabling music labels and sports leagues to tokenize catalog assets without prohibitive gas expenditure.
- Music Industry Royalty Automation:Smart contract-based revenue splits attract independent artists frustrated with traditional collection society delays, driving platform adoption for programmable recurring payments.
Market Restraints
- Validator Concentration Risk:Ethereum staking has consolidated among US-based institutional custodians, creating single-point-of-failure exposure for transaction finality across NFT marketplaces.
- SEC Enforcement Uncertainty:Ongoing securities law investigations into fractionalized token offerings chill institutional capital deployment pending regulatory classification clarity.
- Interoperability Friction:Cross-chain bridging protocols carry smart contract exploit risk that limits creator willingness to mint assets outside native Ethereum environments.
Strategic Opportunities
- India Creator Economy Penetration:Low existing NFT adoption among India's digital artist community presents first-mover platform expansion potential before local regulatory frameworks crystallize.
- Physical-Digital Hybrid Collectibles:Luxury fashion houses seek NFC-linked tokenization for authenticity verification, merging hardware authentication with on-chain provenance records.
- Carbon-Negative Minting Protocols:Proof-of-stake validation combined with carbon credit retirement mechanisms addresses environmental criticism that suppressed 2021-2022 corporate adoption.
Industry Challenges
- Smart Contract Auditor Scarcity:Formal verification expertise for ERC-721 and ERC-1155 implementations remains concentrated among a handful of security firms, creating deployment bottlenecks for enterprise clients.
- Metadata Storage Permanence:IPFS pinning service reliability varies, threatening long-term asset accessibility when creator subscriptions lapse or node operators exit.
- Wallet Onboarding Friction:Seed phrase management complexity excludes non-technical creators, forcing platforms to subsidize custodial solutions that compromise the self-sovereignty value proposition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NFT Creation Software Market |
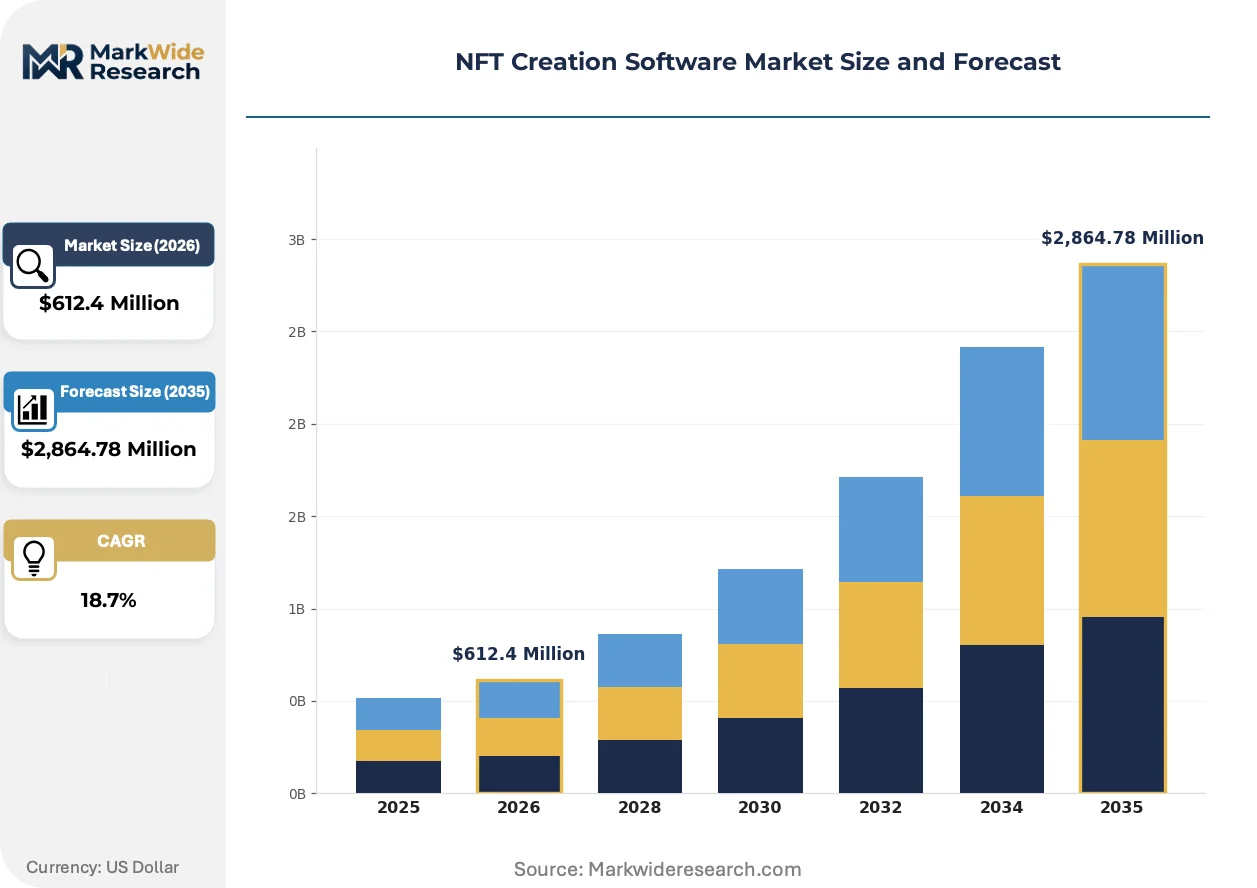
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Art, Music, Sports Collectibles, Domain Names Technology: Blockchain, Smart Contracts, Decentralized Storage, IPFS End User: Artists, Musicians, Gamers, Collectors Distribution Channel: Online Marketplaces, Direct Sales, Social Media, Auctions |
| Companies Covered | OpenSea, Coinbase, LeewayHertz, Suffescom Solutions, Blockchain App Factory, EvaCodes, Antier Solutions, Innowise Group, Cubix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NFT Creation Software Market Trends and Innovations
Generative artificial intelligence tools are compressing production timelines for visual NFT collections, while zero-knowledge proof implementations enable private ownership verification without exposing wallet balances. These developments reshape creator economics and collector privacy expectations simultaneously.
Zero-knowledge rollup architectures are integrating with existing marketplace infrastructure to batch thousands of minting transactions into single Ethereum mainnet proofs. Gaming studios deploying large-scale avatar collections have adopted this approach most aggressively, cutting per-unit gas costs by over ninety percent. The structural compression is integrating smaller creators into previously cost-prohibitive minting categories.
The EU's Markets in Crypto-Assets framework mandates segregated custody for crypto-asset service providers and imposes strict reserve requirements on stablecoin issuers used for NFT pricing. Marketplace operators must restructure treasury management and obtain national financial licenses before 2025 deadlines. German and French regulators have issued earliest implementation guidance, pressuring platforms to prioritize compliance investment in these jurisdictions.
Collector purchasing patterns have pivoted toward utility-bearing assets with embedded access rights rather than speculative JPEG ownership. Music festival ticketing and private community membership tokens now outsell pure art collectibles on volume metrics. This behavioral rotation is most visible in United States metropolitan markets where experiential consumption preferences already dominate leisure spending patterns.
NFT Creation Software Market Segmentation
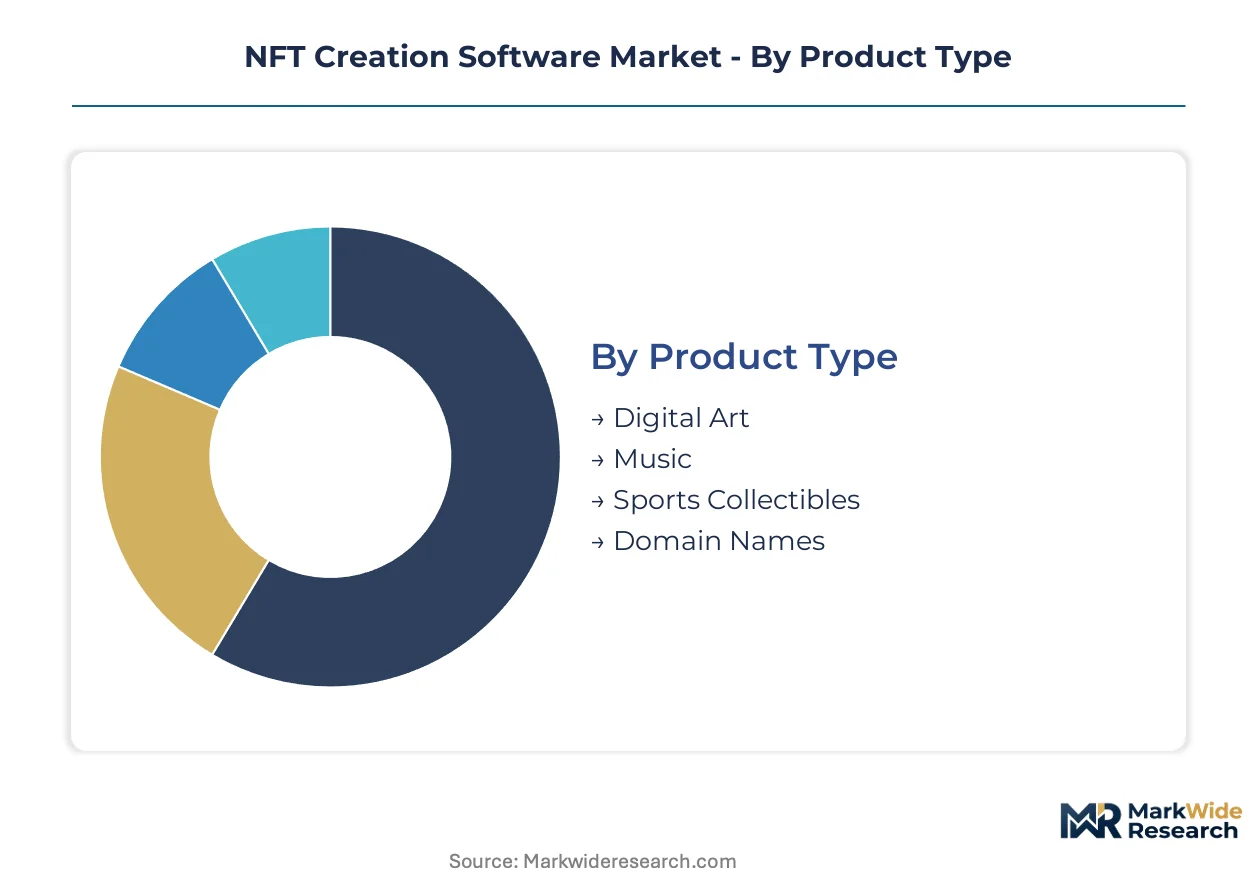
NFT creation software segments diverge sharply by technical sophistication and creator workflow integration. Standardized minting tools serve mass-market creators while configurable smart contract deployments attract institutional clients with complex royalty requirements.
Product Type:
Customization intensity spans from template-driven art generators to fully programmable sports memorabilia contracts with embedded licensing terms.
- Digital Art:Visual minting tools dominate transaction volume through drag-and-drop interfaces and automated metadata generation. Demand clusters among United States-based independent illustrators and generative artists seeking programmable scarcity without coding expertise. Creator platforms prioritize gas-optimized batch minting to accommodate large collection drops.
- Music:Audio tokenization platforms integrate automated royalty splitting across multiple rights holders, attracting Nashville and Los Angeles-based independent musicians frustrated with traditional collection society delays. Smart contract templates now support fractional master recording ownership and streaming revenue attribution.
- Sports Collectibles:League-licensed highlight reels and authenticated memorabilia tokenization.
- Domain Names:Decentralized naming services on Ethereum and Polygon with resale marketplace integration.
Most installed capacity flows through Digital Art. Expansion is steepest in Sports Collectibles.
Technology:
Cost tier stratification separates free-tier creators on shared infrastructure from enterprise clients deploying dedicated validator nodes and custom storage architectures.
- Blockchain:Layer-1 and Layer-2 network selection determines finality speed and transaction economics. Ethereum mainnet retains premium positioning for high-value art auctions despite elevated gas fees, while Polygon and Arbitrum capture bulk minting volume from gaming studios and music labels in Germany and France.
- Smart Contracts:ERC-721 and ERC-1155 standard implementations with customizable royalty enforcement and transfer restrictions. Enterprise clients in Switzerland and Singapore demand formal verification services that exceed available auditor capacity.
- Decentralized Storage:Distributed file systems for metadata persistence without centralized server dependency.
- IPFS:Content-addressed storage protocol with pinning service marketplace dynamics.
Smart Contracts command the highest implementation margins. IPFS is gaining share fastest among cost-sensitive creator cohorts.
End User:
Customer maturity varies from crypto-native collectors managing self-custodied wallets to mainstream musicians requiring full custodial abstraction.
- Artists:Visual creators leveraging generative AI tools for collection generation with automated trait rarity algorithms. Demand concentrates in Brooklyn and Berlin digital art communities where exhibition culture intersects with blockchain verification preferences.
- Musicians:Rights holders seeking programmable revenue distribution and direct fan engagement mechanisms. Nashville studio professionals and London electronic producers adopt platform-agnostic minting tools to avoid marketplace lock-in.
- Gamers:Avatar and in-game asset creators for metaverse environments and play-to-earn economies.
- Collectors:Speculative buyers and curators prioritizing provenance verification and secondary market liquidity.
Artists generate the highest minting frequency. Musicians show the steepest adoption acceleration.
Distribution Channel:
Volume scale separates high-liquidity marketplaces from direct-to-collector relationship models with superior margin retention.
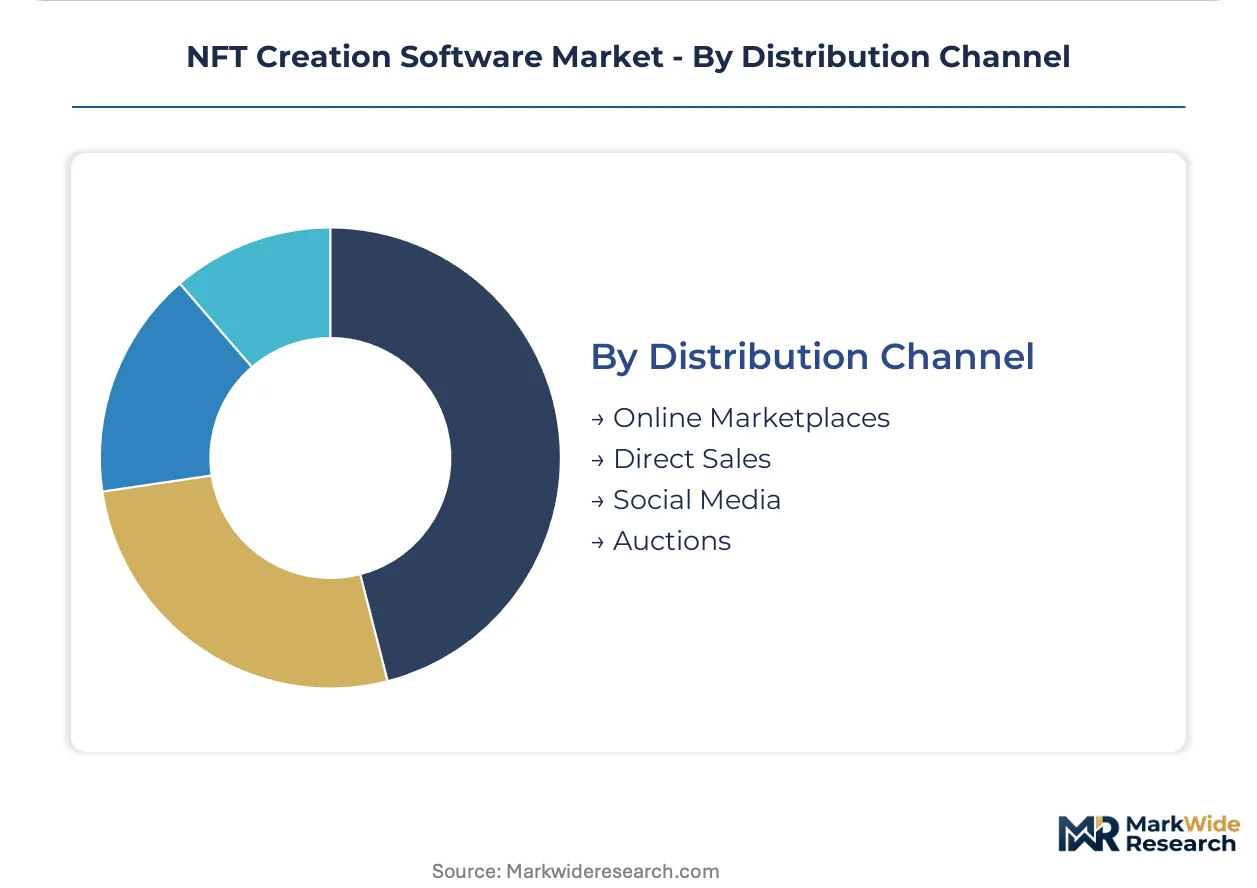
- Online Marketplaces:Aggregated listing platforms with established collector networks and bidding infrastructure. OpenSea and Blur capture United States metropolitan volume through first-mover liquidity advantages and royalty-optional pricing flexibility.
- Direct Sales:Branded minting pages with embedded checkout and email capture for creator-owned customer relationships. Luxury fashion houses in Milan and Paris prefer this channel to preserve brand control and avoid marketplace fee extraction.
- Social Media:Integrated minting buttons on creator platforms with existing follower monetization.
- Auctions:Reserve-price and English auction formats for scarce high-value pieces with extended bidding windows.
Online Marketplaces process the majority of transaction value. Direct Sales is expanding most quickly among enterprise entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping platform headquarters selection, with operators weighing MiCA compliance costs in Germany and France against the SEC enforcement uncertainty in the United States. Jurisdictional migration favors Singapore and Switzerland where licensing frameworks offer clearer operational boundaries.
United States
Creator monetization infrastructure concentrates in Brooklyn and Los Angeles, where independent musicians and digital artists drive minting volume through Ethereum-based tooling. SEC investigations into fractionalized token offerings pressure platforms to implement investor accreditation protocols. OpenSea anchors liquidity networks from San Francisco, sustaining dominant listing volumes despite regulatory headwinds.
Germany
Industrial design studios in Berlin and Munich adopt tokenization for luxury fashion authentication, merging NFC hardware with on-chain provenance. BaFin implements MiCA licensing requirements ahead of the 2025 deadline, forcing marketplace operators to restructure custody arrangements. Frankfurt's financial infrastructure supports institutional staking pools that validate Ethereum transactions underpinning NFT minting operations.
France
Parisian luxury houses pursue physical-digital hybrid collectibles, linking hardware authentication to blockchain records for provenance verification. AMF guidance on crypto-asset service providers establishes earlier compliance timelines than neighboring jurisdictions. The Île-de-France cluster attracts platform operators seeking regulatory clarity before the full MiCA framework activates.
Switzerland
Zurich and Geneva host enterprise clients demanding formally verified smart contracts for complex royalty arrangements. FINMA's established crypto-asset guidelines reduce jurisdictional uncertainty compared to EU member states still implementing MiCA. The Crypto Valley in Zug anchors development teams building custom deployment tools for institutional tokenization projects.
India
Low existing adoption among Mumbai and Bangalore digital artist communities presents first-mover expansion potential before local regulatory frameworks crystallize. RBI scrutiny of crypto-asset transactions complicates payment rails for creator platforms. Telangana's blockchain initiatives in Hyderabad attract pilot projects testing carbon-negative minting protocols for corporate clients.
NFT Creation Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue enterprise custom development and Layer-2 infrastructure specialization. The vendor base stratifies across liquidity-aggregating marketplaces, regulated custody providers, and boutique smart contract studios. Three archetypes dominate: first-mover platforms with entrenched collector networks, institutional-grade custody integrators, and custom development shops serving complex royalty requirements. Competitive moves center on geographic licensing acquisition and rollup technology partnerships that compress minting costs.
Within the liquidity-aggregation tier, OpenSea exemplifies first-mover network effects that sustain transaction volume dominance. Coinbase occupies the institutional credibility position through regulated custody integrations appealing to risk-averse creators. LeewayHertz represents the custom development archetype, anchoring enterprise client relationships through configurable smart contract deployments. These three patterns illustrate how competitive positioning diverges across creator segments with varying technical sophistication and compliance tolerance.
| Leading Market Players |
|---|
| OpenSea |
| Coinbase |
| LeewayHertz |
| Suffescom Solutions |
| Blockchain App Factory |
| EvaCodes |
| Antier Solutions |
| Innowise Group |
| Cubix |
| Others |
Pricing and Supply Chain Analysis
Ethereum gas fee volatility functions as the primary cost benchmark, cascading through minting platforms into tiered service pricing that separates enterprise clients from independent creators. Layer-2 rollup adoption compresses transaction costs, forcing platforms to restructure subscription tiers around verification speed rather than base network fees.
Pricing Analysis
Direct-to-creator platform fees bypass marketplace markups, enabling SaaS-tiered subscription models that scale with collection size and smart contract complexity. Price differentiation hinges on formal verification grade and geographic delivery cost for IPFS pinning redundancy. Cost compression in the mid-market tier intensifies as Polygon and Arbitrum bulk minting erodes Ethereum mainnet premium positioning. Independent artists in Brooklyn and Berlin exhibit highest price sensitivity, while Swiss enterprise clients tolerate premium pricing for formally verified deployments.
Supply Chain Analysis
Validator node hardware supply rests on Taiwanese semiconductor foundries and South Korean memory manufacturers, with final assembly concentrating in Chinese server farms and US-based institutional custody facilities. Smart contract auditing capacity draws from specialized security firms in Switzerland and Singapore, while IPFS pinning services source from distributed node operators across Germany and France. Single-source vulnerability in formal verification expertise creates deployment bottlenecks for enterprise clients. Distribution runs through API-integrated creator platforms rather than traditional software resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NFT creation software market rewards operators who arbitrage between MiCA compliance costs in Germany and SEC enforcement uncertainty in the United States, capturing margin from risk-averse institutional clients seeking regulatory clarity.
For Market Incumbents: To counter Layer-2 rollup commoditization, deepen smart contract auditing partnerships with Swiss formal verification specialists and establish captive staking infrastructure in Frankfurt to secure transaction finality guarantees. Channel control over IPFS pinning services preserves margin against decentralized storage price erosion. For New Entrants and Emerging Players: Enter via India's underpenetrated digital artist communities in Mumbai and Bangalore before RBI payment rail restrictions crystallize, targeting musicians frustrated with traditional collection society delays through white-label royalty automation tools. Platform-agnostic minting interfaces avoid marketplace lock-in vulnerabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where smart contract auditor scarcity concentrates among a handful of security firms, favoring acquisition of boutique verification studios with ERC-721 and ERC-1155 specialization. Long-term viability hinges on carbon-negative minting protocol adoption among corporate clients. Watch Layer-2 sequencer decentralization progress as infrastructure reliability inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MiCA Licensing Acquisition | BaFin and AMF approvals unlock regulated custody services for European institutional clients. |
| Layer-2 Rollup Integration | Polygon and Arbitrum partnerships reduce per-mint gas costs for music label bulk deployments. |
| Formal Verification Partnership | Swiss auditor collaborations address enterprise demand for mathematically proven smart contract security. |
| Carbon-Negative Minting Protocol | Proof-of-stake validation with carbon credit retirement satisfies ESG mandates from luxury fashion houses. |
| Direct Sales Channel Buildout | Branded minting pages in Milan and Paris preserve margin extraction from high-value collectible drops. |
Research Methodology
Direct dialogue with platform engineering leads, smart contract auditors, independent musicians, and luxury fashion digital strategy heads grounded qualitative findings, cross-referenced against SEC enforcement dockets, MiCA implementation guidance from BaFin and AMF, Ethereum validator distribution data, and IPFS network metrics. Bottom-up creator platform usage estimates triangulated with top-down NFT transaction volume analysis.
Segmentation outputs across product type, technology stack, end user archetype, and distribution channel were modeled through the projection horizon, with CAGRs derived from Ethereum staking reward dynamics and Layer-2 adoption velocity. Smart contract deployment frequency and royalty automation penetration served as primary demand-side inputs.
Inputs from German and French regulatory filings were available through the study window; gaps in Indian central bank guidance introduce uncertainty bands around payment rail assumptions. Forecasts reflect documented validator concentration and auditor scarcity constraints. Regulatory enforcement patterns in the United States and EU member states, plus Layer-2 sequencer decentralization milestones, warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Utility App Market
Digital Solutions
Green IT Services Market
Digital Solutions
Container Management Software Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
Data Extraction Market
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Cloud Logistics Software Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
E-Ink E-Reader Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
Crew Management Systems Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
Saudi Arabia Digital Twin Market