
 Intelligent Parcel Delivery Lockers Market | 2026-2036
Intelligent Parcel Delivery Lockers Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Parcel Delivery Lockers Market Insights
China is narrowing the cost gap between domestic and imported locker systems as local manufacturers scale steel fabrication and IoT module assembly. Quadient leverages its European service network to sustain recurring software revenue across installed bases. InPost anchors its competitive position through exclusive partnerships with Polish and UK retail chains. Cleveron specializes in refrigerated locker configurations for grocery and pharmaceutical last-mile segments.
Intelligent parcel delivery lockers constitute electromechanical storage systems integrating RFID authentication, cellular IoT connectivity, and cloud-based management platforms to enable automated package deposit and retrieval without human attendant oversight. Units typically incorporate steel enclosures with individual compartment sizes ranging from envelope slots to oversized parcel bays, plus environmental controls for temperature-sensitive cargo. Smart lockers currently dominate installed value due to their software attach rates and remote diagnostics capability, while refrigerated lockers represent the fastest-growing product configuration as cold-chain e-commerce penetrates grocery and healthcare sectors. Mobile app integration leads technology adoption curves by reducing touchscreen maintenance and enabling push-notification workflows.
FCC equipment authorization governs wireless communication modules in US-deployed units, while the EU AI Act and GDPR constrain biometric access implementations and customer data handling across European installations. Ecodesign regulations under the EU Green Deal are mandating energy-efficient standby modes and recyclable material quotas that reshape component sourcing for manufacturers serving European logistics providers. Stakeholders must weigh biometric authentication adoption against evolving data governance frameworks as regulatory divergence between jurisdictions complicates platform standardization strategies.
Market Dynamics
Last-mile delivery density is compressing carrier margins and forcing logistics operators toward centralized pickup infrastructure. The EU Green Deal's carbon-reduction mandates are accelerating this shift by penalizing repeated delivery attempts.
Growth Catalysts
- E-commerce fulfillment pressure:Online retailers are deploying lockers to manage surging parcel volumes without expanding delivery fleets. Germany's dense urban corridors favor this centralized model.
- EU Green Deal carbon mandates:Logistics operators face penalties for emissions from failed delivery attempts, making locker consolidation economically rational.
- Refrigerated locker technology:Cold-chain capabilities are unlocking grocery and pharmaceutical segments previously excluded from automated pickup.
Market Restraints
- Steel and IoT module cost volatility:Input price swings for enclosure materials and cellular connectivity components compress hardware margins.
- Biometric authentication friction:GDPR constraints on facial recognition and fingerprint data handling limit access-method innovation in European deployments.
- Building code fragmentation:Municipal installation requirements vary across German Länder, slowing rollout standardization.
Strategic Opportunities
- Polish retail corridor expansion:Exclusive partnerships with convenience chains create captive pickup networks in underpenetrated Central European markets.
- Healthcare cold-chain penetration:Temperature-controlled compartments address pharmaceutical last-mile compliance requirements.
- Mobile app workflow convergence:Push-notification retrieval systems eliminate touchscreen maintenance and enable subscription-based software revenue.
Industry Challenges
- Embedded systems engineering talent scarcity:Shortages of firmware developers familiar with electromechanical integration slow product iteration cycles.
- FCC and CE dual certification timelines:Wireless module approvals for transatlantic deployments extend time-to-market by quarters.
- Legacy property management system integration:Apartment and office building access protocols require custom API development for seamless locker embedding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Parcel Delivery Lockers Market |
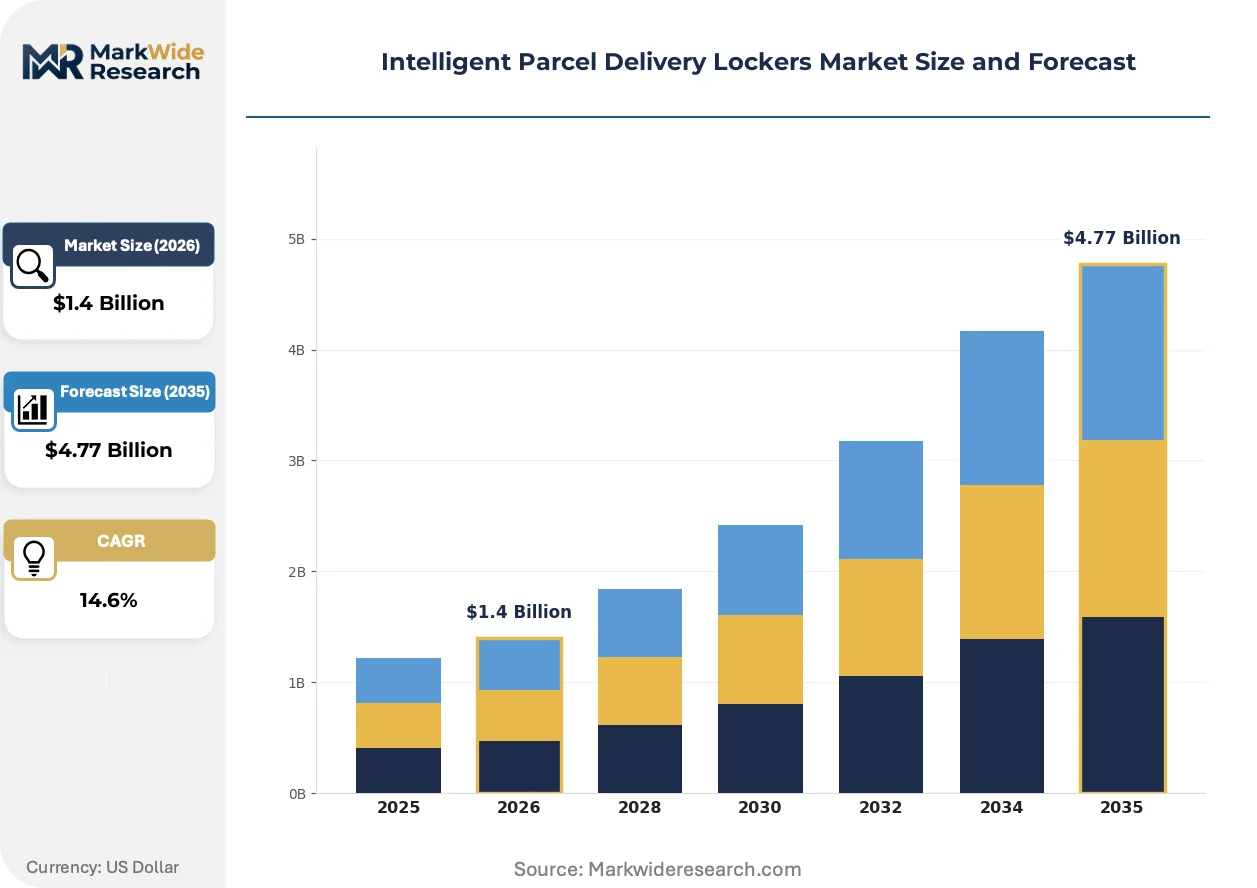
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lockers, Modular Lockers, Refrigerated Lockers, Automated Lockers Technology: RFID, IoT Connectivity, Mobile App Integration, Biometric Access End User: E-Commerce Retailers, Logistics Providers, Universities, Residential Complexes Installation Type: Indoor Lockers, Outdoor Lockers, Standalone Units, Integrated Solutions |
| Companies Covered | Quadient, InPost, KEBA, Ricoh Group, Pitney Bowes, Cleveron, Parcel Pending, Luxer Corporation, Package Concierge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Parcel Delivery Lockers Market Trends and Innovations
Hardware-software convergence is redefining competitive differentiation in parcel locker systems. Vendors are racing to embed predictive analytics and dynamic compartment sizing into cloud platforms.
Computer vision and weight-sensing modules are hybridizing traditional locker architecture. Grocery chains are adopting these hybrid configurations fastest, using automated cargo verification to reduce manual handling. The technology is hybridizing refrigerated and ambient storage into unified footprints, compressing real estate requirements for multi-temperature fulfillment.
GDPR and the EU AI Act are constraining biometric access deployments across European installations. Operators must now default to QR-code and PIN authentication to avoid data-governance liability. German logistics providers are responding by accelerating mobile-app-based retrieval workflows that keep biometric processing on user devices.
Buyer procurement is consolidating around full-service fleet management contracts rather than capital hardware purchases. Third-party logistics operators are displacing direct retailer ownership of locker networks. This shift concentrates most visibly in the United Kingdom, where carrier-neutral pickup infrastructure is displacing single-retailer installations.
Intelligent Parcel Delivery Lockers Market Segmentation
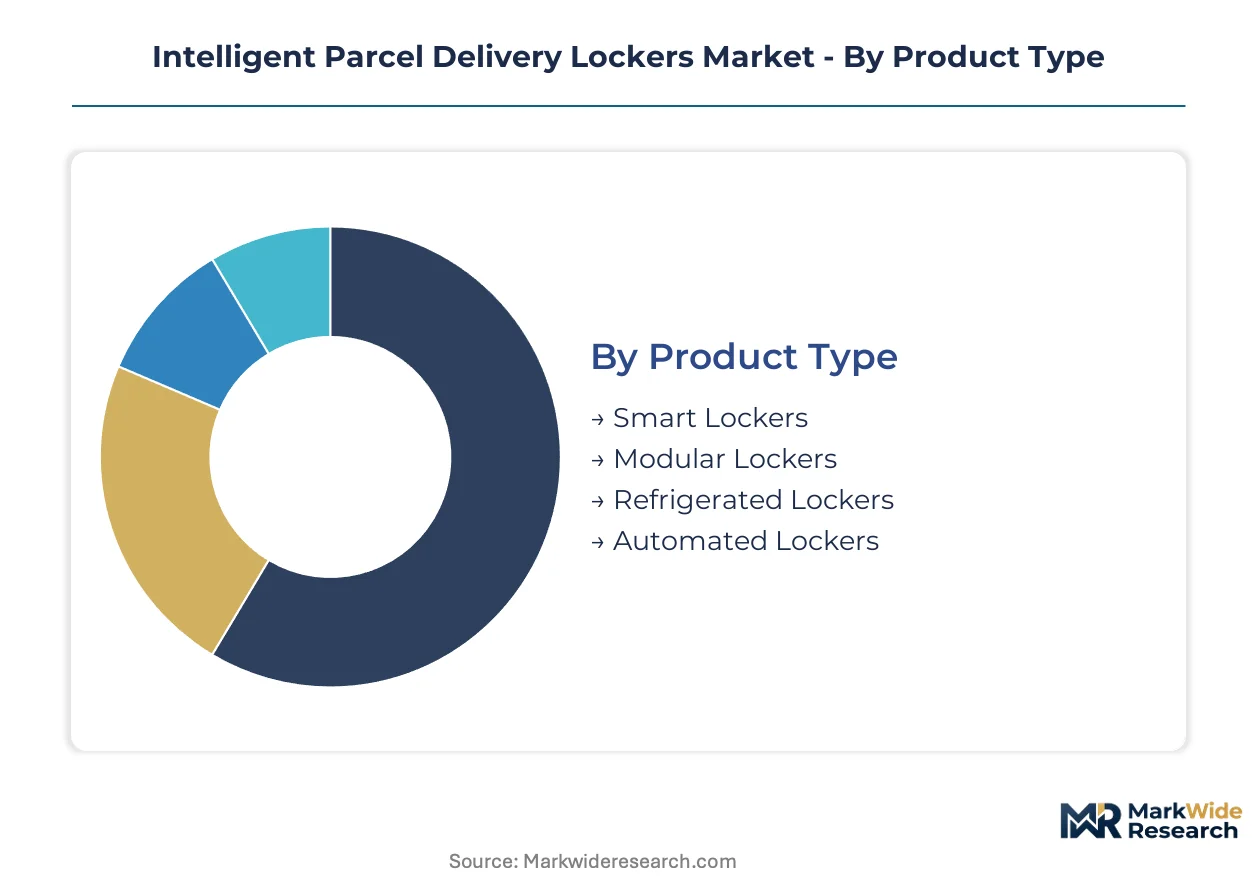
Parcel locker architectures diverge sharply across temperature requirements, authentication methods, and real estate integration models. Understanding these segment boundaries clarifies why vendors pursue radically different hardware-software bundling strategies.
Product Type:
Electromechanical configurations span ambient storage through pharmaceutical-grade cold chain, each demanding distinct enclosure engineering and service revenue models.
- Smart Lockers:Cloud-native units with remote diagnostics, dynamic compartment allocation, and API-first management platforms command premium software attach rates. German logistics operators deploy these at transit hubs to consolidate multi-carrier volume and minimize failed delivery emissions under EU Green Deal penalties.
- Refrigerated Lockers:Thermoelectric or compressor-based cooling maintains 2-8°C for pharmaceutical compliance and frozen corridors for grocery fulfillment. UK grocery chains and Polish pharmacy networks are expanding these fastest as cold-chain e-commerce penetrates last-mile infrastructure.
- Modular Lockers:Scalable bay configurations allow site-specific capacity adjustment without full system replacement.
- Automated Lockers:Conveyor-fed or robotic retrieval systems handle high-throughput distribution centers.
Established volume favors Smart Lockers; emerging adoption favors Refrigerated Lockers.
Technology:
Authentication and connectivity layers determine both capital intensity and recurring revenue potential across installed bases.
- IoT Connectivity:Cellular LTE-M and NB-IoT modules enable real-time status monitoring, predictive maintenance alerts, and over-the-air firmware updates. FCC equipment authorization timelines in the US and CE marking requirements in Europe extend procurement cycles but lock in long-term platform stickiness.
- Mobile App Integration:Push-notification retrieval workflows eliminate touchscreen hardware maintenance and enable subscription-based software revenue. GDPR-compliant designs keep biometric processing on user devices rather than locker-embedded sensors.
- RFID:Legacy contactless authentication persists in closed-loop campus and corporate deployments.
- Biometric Access:Facial recognition and fingerprint modules face EU AI Act and GDPR constraints, limiting European penetration.
Mobile App Integration is climbing the fastest as carriers abandon high-maintenance touchscreens; Biometric Access faces steepest regulatory headwinds.
End User:
Procurement authority is fragmenting between retailers owning customer relationships and third-party logistics operators controlling delivery density.
- Logistics Providers:DHL, FedEx, and national postal services deploy carrier-neutral networks to consolidate parcel injection points and reduce per-stop delivery costs. These operators prioritize modular expansion paths and API interoperability with existing route optimization systems.
- E-Commerce Retailers:Amazon and vertical specialists install captive lockers to protect brand experience and capture last-mile data. Their procurement favors turnkey fleet management contracts over capital purchases.
- Residential Complexes:Property managers install lobby units to differentiate amenity packages and reduce concierge burden.
- Universities:Campus IT departments prioritize student credential integration and semester-based capacity planning.
Logistics Providers concentrate procurement volume; E-Commerce Retailers are gaining share fastest through direct consumer touchpoint strategies.
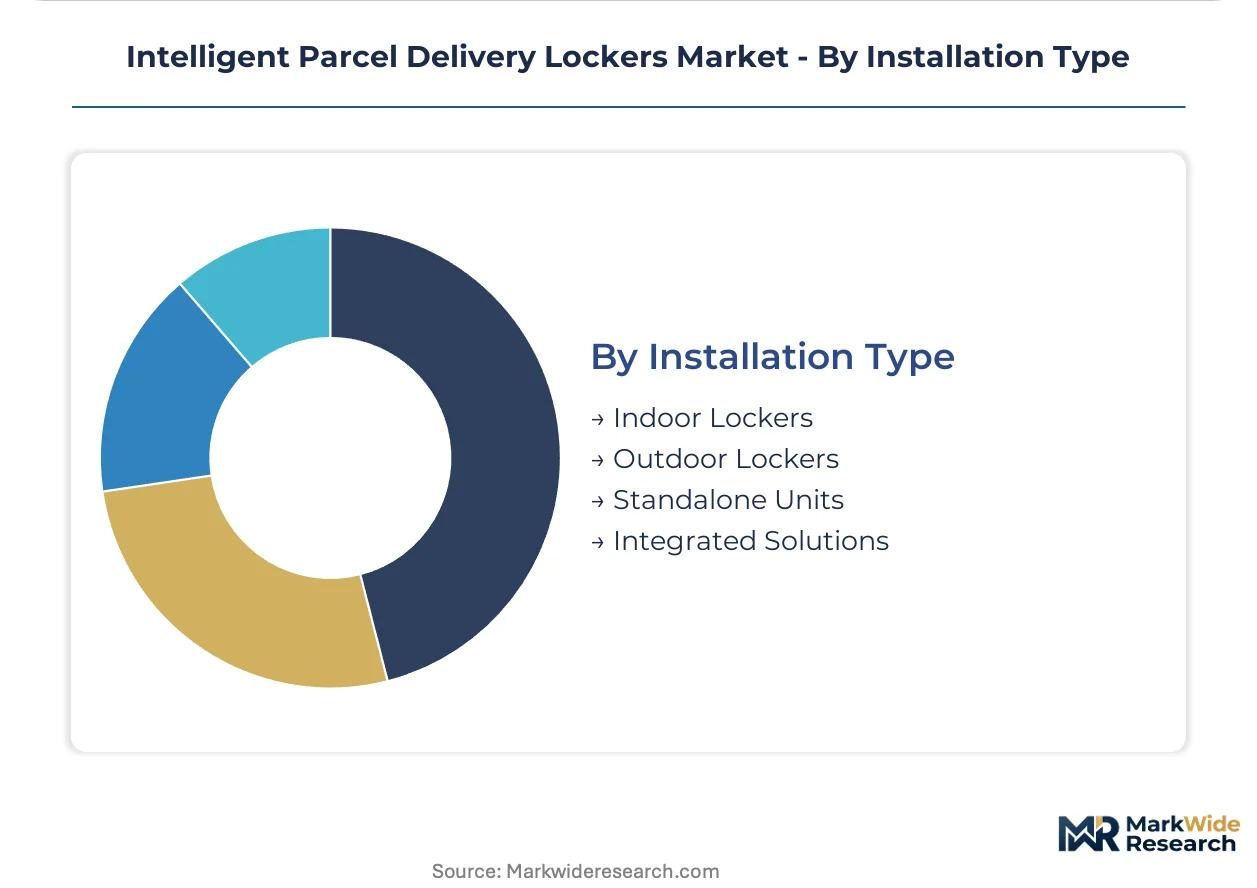
Installation Type:
Real estate constraints and climate exposure dictate enclosure specifications and maintenance scheduling intensity.
- Outdoor Lockers:IP-rated steel enclosures withstand precipitation, temperature cycling, and vandalism exposure. German municipal codes and UK planning permissions create fragmented approval timelines, favoring vendors with established local installation partnerships.
- Indoor Lockers:Climate-controlled environments reduce HVAC load and extend component lifespans in retail and residential lobbies.
- Standalone Units:Self-contained footprints suit parking lots and transit-adjacent sites without building integration.
- Integrated Solutions:Embedded wall or lobby systems require custom fabrication and property management system API development.
Outdoor Lockers dominate addressable real estate; Integrated Solutions command highest per-unit value through building-system convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European deployment velocity, with carbon penalties on failed deliveries accelerating locker infrastructure investment across member states. Dense urban corridors and fragmented building codes create divergent rollout patterns between national markets.
Germany
DHL and national postal operators deploy carrier-neutral networks at transit hubs to consolidate multi-carrier volume. Municipal installation requirements vary across Länder, with Bavaria and North Rhine-Westphalia maintaining stricter facade integration standards than eastern states. Berlin-Brandenburg corridor sees fastest outdoor locker deployment as last-mile density compresses carrier margins.
United Kingdom
Carrier-neutral pickup infrastructure displaces single-retailer installations as third-party logistics operators consolidate procurement authority. UK planning permissions create fragmented approval timelines favoring vendors with established local installation partnerships. London/Southeast corridor concentrates refrigerated locker deployment for grocery cold-chain fulfillment.
Poland
Convenience retail chains anchor captive pickup networks in underpenetrated Central European markets. Domestic logistics operators expand modular locker fleets to reduce per-stop delivery costs in dense urban corridors. Warsaw and Kraków metropolitan areas concentrate deployment as e-commerce fulfillment pressure intensifies.
China
Local manufacturers scale steel fabrication and IoT module assembly, narrowing cost gaps with imported systems. MIIT equipment certification governs wireless communication modules in deployed units. Yangtze River Delta and Pearl River Delta clusters dominate domestic production capacity for electromechanical enclosure systems.
United States
FCC equipment authorization timelines extend procurement cycles for cellular-connected units but lock in long-term platform stickiness. Amazon and vertical e-commerce specialists install captive lockers to protect brand experience and capture last-mile data. California and New York Metro lead deployment density as residential complex amenity competition intensifies.
Intelligent Parcel Delivery Lockers Market Competitive Landscape
Capability concentration sits with electromechanical integration specialists; scale advantage sits with logistics operators with captive deployment networks. The vendor base stratifies across three tiers: European incumbents with established service networks, Asian fabricators with cost-optimized steel and IoT assembly, and North American software-first platforms. Dominant competitive moves include exclusive retail partnerships in underpenetrated corridors and refrigerated configuration development for cold-chain segments.
Within the European incumbent tier, Quadient and InPost exemplify divergent scale strategies. Quadient leverages its continental service infrastructure to sustain recurring software revenue across installed bases, while InPost anchors position through exclusive convenience chain partnerships in Polish and UK markets. Cleveron occupies a specialist position, representing the refrigerated configuration archetype as grocery and pharmaceutical cold-chain penetration accelerates.
| Leading Market Players |
|---|
| Quadient |
| InPost |
| KEBA |
| Ricoh Group |
| Pitney Bowes |
| Cleveron |
| Parcel Pending |
| Luxer Corporation |
| Package Concierge |
| Others |
Pricing and Supply Chain Analysis
Chinese steel fabrication clusters and IoT module assembly lines concentrate upstream capacity, compressing hardware margins for European and North American system integrators who capture value through software attach rates and recurring fleet management contracts. Margin pools sit downstream with logistics operators and property managers who bundle locker access into broader service offerings.
Pricing Analysis
Geographic price spreads of 15-25% separate German-engineered systems from Chinese-manufactured alternatives, with cost differentiation driven by CE certification tiers and after-sales service bundling rather than base hardware specifications. Pricing pressure stems from local Chinese manufacturers scaling LTE-M module integration and cold-rolled steel enclosure production. E-commerce retailers exhibit highest price sensitivity, prioritizing per-unit capital expenditure over total cost of ownership, while healthcare logistics operators accept premium positioning for pharmaceutical-grade refrigerated configurations with validated temperature compliance.
Supply Chain Analysis
Contract manufacturing for electromechanical assemblies concentrates with Yangtze River Delta EMS providers and specialized Czech fabrication shops serving European OEMs. Raw material dependencies center on cold-rolled steel from Chinese mills, cellular IoT modules from Taiwanese and South Korean semiconductor fabricators, and thermoelectric cooling components from Japanese suppliers. Single-source vulnerability runs through LTE-M chipset supply from concentrated foundry capacity. Distribution runs through direct OEM sales to national postal operators and third-party logistics providers, with increasing channel shift toward fleet management contractors who aggregate procurement across retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intelligent parcel delivery lockers market is cycling through a post-pandemic normalization phase as e-commerce fulfillment density stabilizes and capital deployment shifts from expansion toward replacement and upgrade cycles. EU Green Deal carbon penalties on failed deliveries provide cyclical support for locker infrastructure investment.
For Market Incumbents: Pre-empt margin compression from Chinese cost-optimized entrants by deepening software platform stickiness through API-first fleet management architectures and predictive maintenance analytics. Secure exclusive installation partnerships with German municipal transit authorities and UK grocery chains before competitive density intensifies. Invest in CE-marked refrigerated configurations to capture pharmaceutical cold-chain compliance premiums.
For New Entrants and Emerging Players: Polish convenience retail corridors and Spanish residential complex lobbies represent addressable white space with fragmented incumbent presence. Target carrier-neutral deployment models for third-party logistics operators seeking to consolidate multi-retailer volume without captive infrastructure investment. Lead with mobile-app-native retrieval workflows that eliminate touchscreen hardware maintenance and accelerate software revenue recognition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European locker networks with established municipal installation permits and recurring SaaS revenue bases but limited refrigerated configuration capabilities. Five-to-ten year viability hinges on cold-chain segment penetration and software platform scalability rather than hardware shipment volume. Monitor InPost and Quadient competitive positioning in Central European retail partnerships as an inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Configuration Development | Pharmaceutical-grade cold-chain capabilities unlock healthcare logistics contracts with GDP compliance requirements. |
| Mobile-App-Native Platform Migration | Push-notification retrieval eliminates touchscreen maintenance and enables subscription-based software revenue streams. |
| Exclusive Retail Partnership Expansion | Captive pickup networks in underpenetrated Central European markets anchor competitive positioning against carrier-neutral alternatives. |
| API-First Fleet Management Architecture | Seamless integration with DHL and national postal route optimization systems locks in logistics provider procurement decisions. |
| CE-Marked Cold-Chain Certification Investment | Validated temperature compliance differentiates offerings for EU pharmaceutical last-mile requirements under GDP guidelines. |
Research Methodology
A spread of perspectives from logistics fleet managers, property management technology directors, locker OEM product strategists, and cellular IoT module suppliers converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against EU customs data for electromechanical enclosure imports, FCC equipment authorization filings for wireless-connected deployments, and SEC disclosures from publicly traded logistics operators. Bottom-up unit deployment tracking across German Länder and UK planning permission databases was triangulated against top-down e-commerce parcel volume projections.
Demand-supply balance modeling anchored projections, with segmentation across smart, refrigerated, modular, and automated locker architectures combined with technology layers spanning IoT connectivity, mobile app integration, RFID, and biometric access. End-user splits between logistics providers, e-commerce retailers, residential complexes, and universities were modeled with installation type differentiation across outdoor, indoor, standalone, and integrated solutions. CAGRs were derived from logistic curve fitting to observed deployment trajectories in Germany and the United Kingdom, with adjustments for EU Green Deal carbon penalty implementation timelines and cold-chain e-commerce penetration curves in grocery and pharmaceutical segments.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese manufacturers or accelerated biometric authentication deregulation under revised EU AI Act interpretations would shift outcomes substantially. Quarterly review of FCC equipment authorization backlogs, German municipal planning permission approval velocities, and refrigerated locker deployment announcements by UK grocery chains is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Non-Medical Biomimetic Robots Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
Piece Picking Robots Market