
 Southeast Asia Industrial and Service Robot Market | 2026-2036
Southeast Asia Industrial and Service Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Industrial and Service Robot Market Analytics
ISO 10218-1 safety certification is bifurcating the competitive landscape into premium and standard tiers. FANUC Corporation leverages its controller technology leadership to dominate high-precision segments across Thailand and Vietnam. KUKA AG sustains its position through deep integration with German automotive transplant factories in the region. Yaskawa Electric Corporation anchors service robot growth via its Motoman line tailored for electronics assembly in Malaysian plants.
Southeast Asia industrial and service robots encompass articulated, collaborative, mobile, and SCARA platforms operating through programmable controllers with positional repeatability below 0.1 millimeter, primarily deployed to automate labor-intensive manufacturing and logistics operations where workforce shortages constrain output. Articulated robots capture the largest installed base across automotive and metalworking facilities, while collaborative robots represent the fastest-expanding category as small and medium enterprises adopt fenceless automation for mixed-model assembly. Sensor-based and vision systems technologies command margin premiums by enabling adaptive pick-and-place in unstructured environments such as Indonesian food processing and Vietnamese electronics packaging.
Thailand's Board of Investment tax incentives and Malaysia's Industry4WRD national policy shape capital deployment decisions for foreign robot vendors. Singapore's Enterprise Singapore grants and Vietnam's Decree 126 on technology investment further structure market access requirements around local content and workforce training thresholds. Stakeholders must monitor evolving national safety certifications and subsidy eligibility rules that determine which robot configurations qualify for preferential financing in each member economy.
Market Dynamics
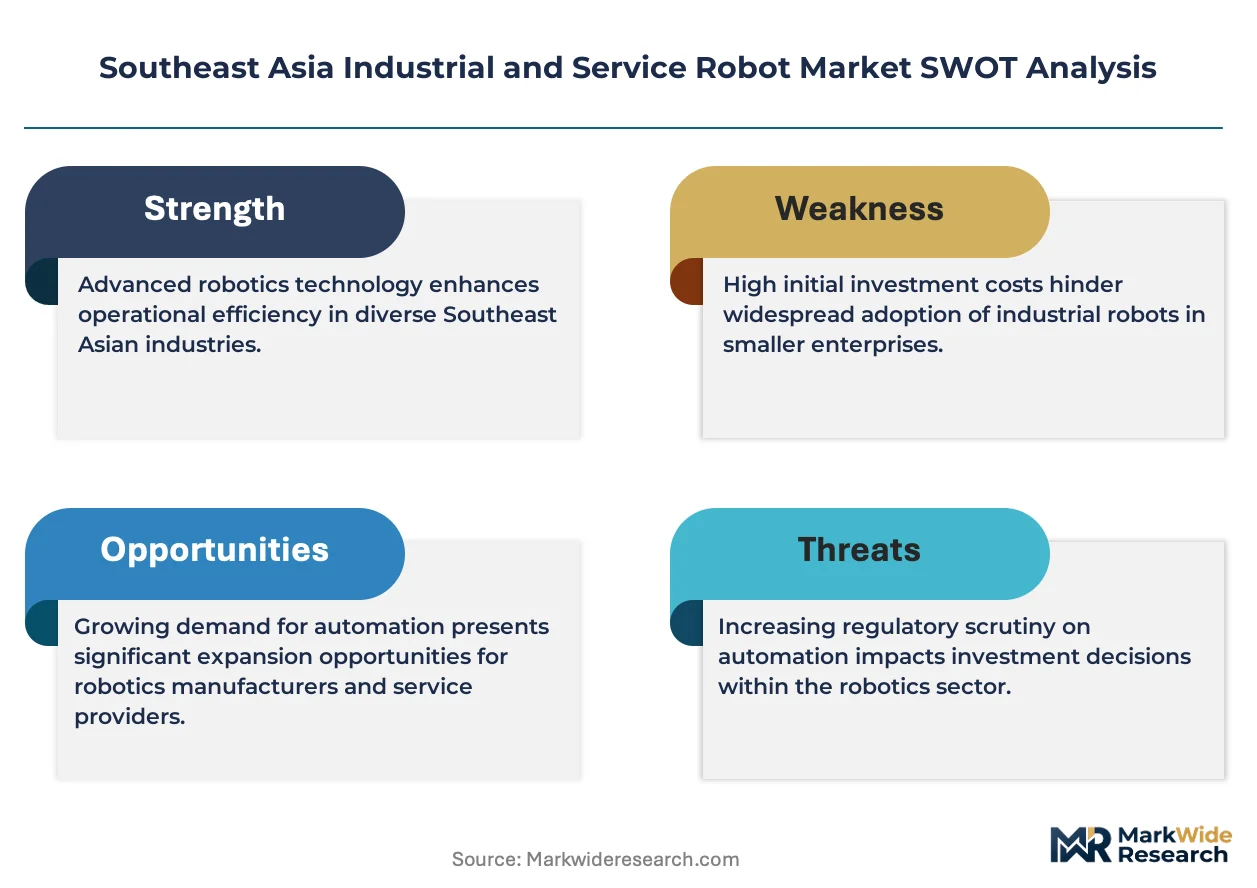
ISO 10218-1 safety certification is fragmenting procurement into premium precision tiers and standard utility tiers, forcing vendors to reposition controller architectures and sensor packages around distinct buyer risk appetites and subsidy eligibility thresholds across Thailand, Vietnam, and Malaysia.
Growth Catalysts
- Thailand's Board of Investment tax incentives:Accelerated depreciation and import duty exemptions on automation equipment lower effective capex hurdles for automotive and electronics manufacturers expanding capacity in the Eastern Economic Corridor.
- Labor shortages in Vietnam's northern industrial corridor:Demographic transition and manufacturing wage inflation push contract manufacturers toward articulated and SCARA platforms for assembly and packaging operations.
- Collaborative robot sensor fusion:Force-torque and vision system integration enables fenceless deployment in mixed-model electronics facilities, opening mid-market access for small and medium enterprises previously excluded by safety infrastructure costs.
Market Restraints
- Controller and servo motor import concentration:Dependence on Japanese and European precision motion control suppliers exposes system integrators to currency volatility and extended lead times for high-repeatability configurations.
- ISO 10218-1 certification timeline:Multi-month validation cycles for safety-rated collaborative systems delay project commissioning and compress vendor cash conversion cycles in competitive tender environments.
- Manual assembly substitution economics:Low prevailing wages in Indonesian food processing and packaging operations sustain labor arbitrage that retards robot adoption below threshold production volumes.
Strategic Opportunities
- Malaysian Industry4WRD adoption gaps:Peninsular Malaysia's small and medium metalworking and plastics sub-contractors remain underpenetrated relative to automotive and electronics tiers, creating whitespace for standardized collaborative platforms with localized training support.
- Mobile robot convergence with warehouse management systems:Integration of autonomous mobile robots with existing enterprise resource planning infrastructure opens logistics automation in Singapore's third-party distribution centers and Vietnam's export-oriented e-commerce fulfillment networks.
- Vietnam Decree 126 technology investment credits:Preferential financing for workforce training and local content thresholds rewards vendors establishing regional technical centers and certification partnerships with domestic polytechnics.
Industry Challenges
- Certified safety integrator scarcity:Shortage of engineers qualified to validate ISO 10218-1 and ISO/TS 15066 collaborative system installations bottlenecks deployment velocity and extends vendor project risk exposure.
- Legacy programmable logic controller interoperability:Proprietary fieldbus protocols and aged controller architectures in Thai and Malaysian automotive transplant factories complicate robot cell integration and inflate customization engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Industrial and Service Robot Market |
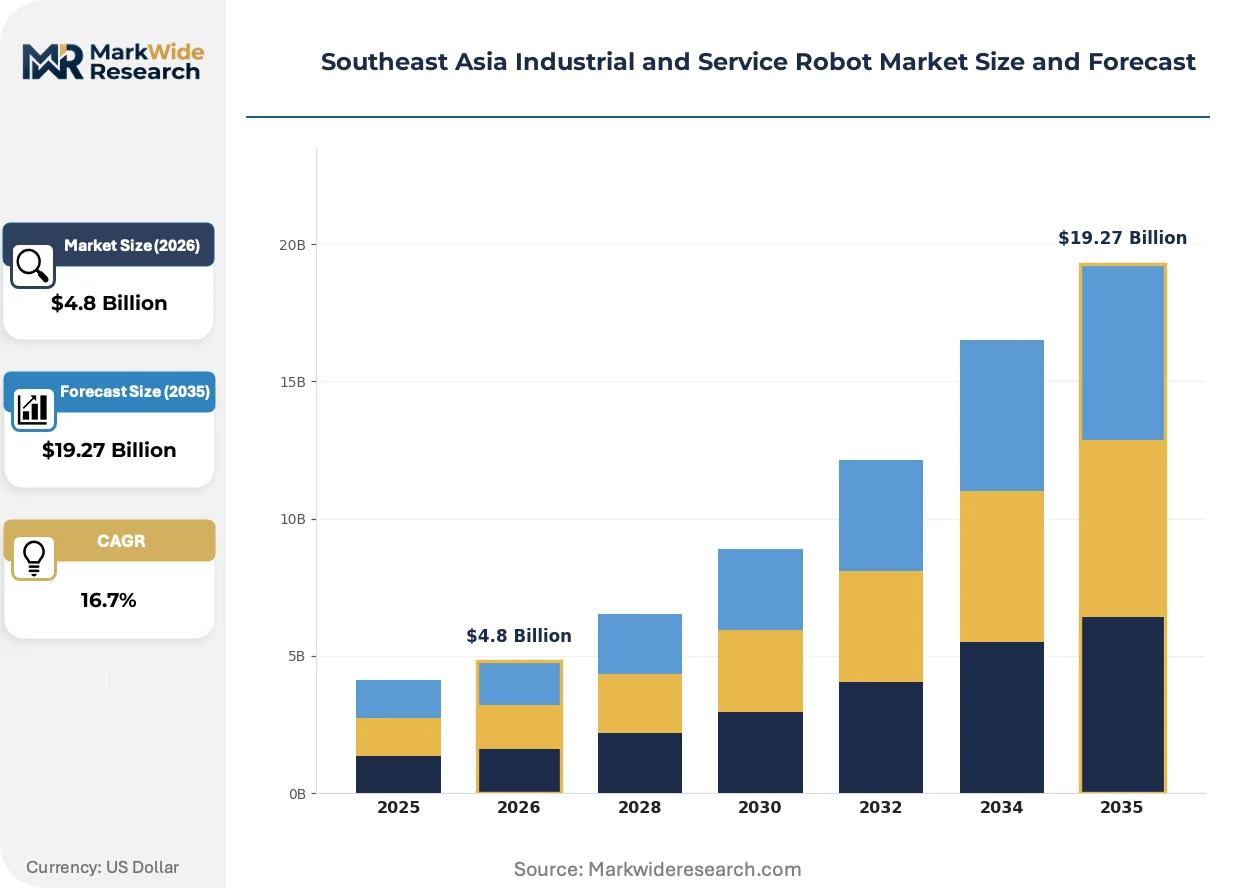
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Articulated Robots, Collaborative Robots, Autonomous Mobile Robots, SCARA Robots End User: Manufacturing, Logistics, Healthcare, Retail Application: Assembly, Material Handling, Inspection, Cleaning Technology: AI-Based, Sensor-Based, Vision Systems, IoT-Enabled |
| Companies Covered | KUKA AG, Denso Corporation, FANUC Corporation, Omron Corporation, Mitsubishi Electric Corporation, Yaskawa Electric Corporation, Kawasaki Heavy Industries Ltd, Delta Electronics, ABB Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Industrial and Service Robot Market Evolving Landscape
Adaptive sensing and edge computing are compressing the performance gap between fixed-automation precision and collaborative flexibility, while national industrial policies restructure vendor go-to-market economics around local content and workforce development mandates.
Vision-guided adaptive gripping is displacing fixed-tool pick-and-place in Vietnamese electronics packaging and Indonesian food processing lines. Contract manufacturers deploying 3D vision and machine learning-based pose estimation achieve sub-millimeter placement accuracy without mechanical fixturing changeovers. This capability is displacing dedicated SCARA cells in high-mix, low-volume production environments where traditional automation economics fail.
Singapore's Enterprise Singapore grants now mandate workforce training hours and local supplier development as conditions for automation subsidy disbursement. This policy architecture redirects vendor competitive strategy toward training partnership depth and domestic system integrator cultivation rather than equipment price positioning alone. Electronics and precision engineering segments face the steepest compliance thresholds, accelerating consolidation around vendors with established regional technical centers.
Small and medium enterprises in Thailand and Malaysia are unbundling after-sales service from capital equipment procurement, preferring outcome-based availability contracts over traditional warranty and break-fix arrangements. This shift compresses vendor revenue recognition timelines and forces servitization of maintenance capabilities through remote monitoring and predictive component replacement. The pattern is most visible in automotive supply chain tiers where just-in-sequence delivery penalties amplify downtime cost visibility.
Southeast Asia Industrial and Service Robot Market Segmentation
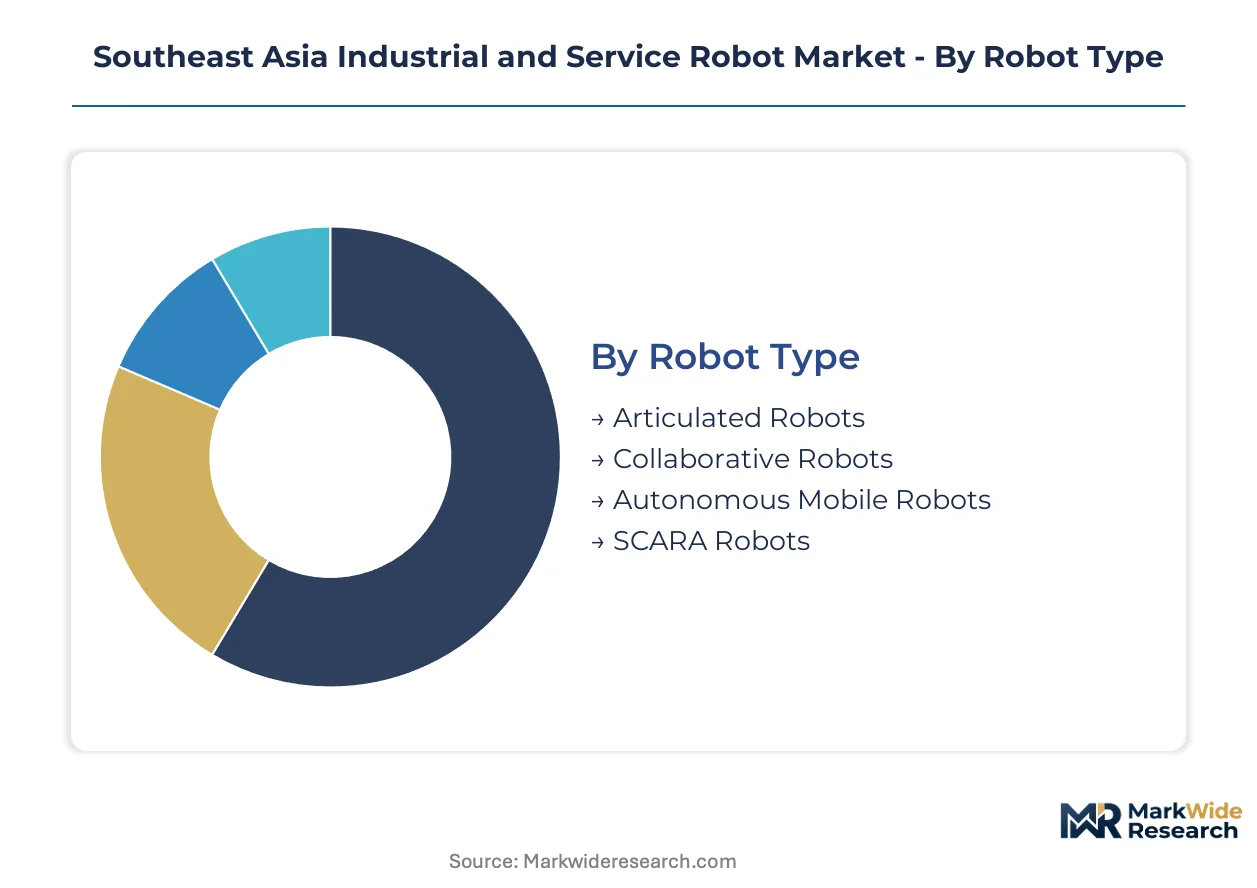
Segmentation reveals how ISO 10218-1 certification tiers and national subsidy thresholds reshape procurement patterns across Thailand, Vietnam, and Malaysia. Understanding these divisions exposes where vendors capture margin premiums versus competing on equipment cost.
Robot Type:
Margin pools concentrate in collaborative platforms where safety-rated sensor fusion commands 40-60% price premiums over standard articulated configurations.
- Articulated Robots:Six-axis configurations with sub-0.1 millimeter repeatability dominate automotive body welding and metalworking in Thailand's Eastern Economic Corridor. Demand clusters at German and Japanese transplant factories where legacy controller protocols favor established vendor relationships.
- Collaborative Robots:Fenceless cobots with integrated force-torque sensing enable mixed-model electronics assembly in Vietnam's northern industrial corridor without safety infrastructure retrofit costs. Small and medium enterprises adopt these fastest where wage inflation erodes manual assembly economics.
- Autonomous Mobile Robots:Warehouse navigation platforms integrate with enterprise resource planning systems in Singapore's third-party logistics centers.
- SCARA Robots:Selective compliance articulated arms target high-speed pick-and-place in Malaysian electronics packaging lines.
Articulated robots hold installed capacity. Collaborative robots are rotating up the share rankings.
End User:
Application complexity and downtime penalty severity determine willingness to pay for predictive maintenance and remote monitoring capabilities.
- Manufacturing:Automotive and electronics contract manufacturers in Vietnam and Thailand deploy the highest robot density per square meter of production floor, driven by just-in-sequence delivery penalties and quality consistency requirements from multinational brand owners.
- Logistics:E-commerce fulfillment networks in Vietnam and Singapore's port-centric distribution hubs adopt mobile robots and goods-to-person systems where labor turnover exceeds 30% annually.
- Healthcare:Rehabilitation and surgical assistance robots face adoption barriers from hospital procurement cycles and clinician training requirements in Malaysia's public health system.
- Retail:Inventory scanning and customer service robots remain pilot-phase in Singapore's high-labor-cost environment.
Manufacturing commands the deepest robot penetration. Logistics is climbing the fastest as warehouse automation accelerates.
Application:
Task repeatability and cycle time predictability shape whether fixed automation or adaptive sensing platforms win the business case.
- Assembly:Electronics component placement in Vietnamese plants requires vision-guided adaptive gripping where high-mix production defeats mechanical fixturing economics.
- Material Handling:Palletizing and machine tending in Thai automotive supply chains favor articulated arms with proven controller reliability over collaborative alternatives.
- Inspection:Machine vision integration for defect detection expands in Malaysian precision engineering where export quality standards mandate traceability.
- Cleaning:Autonomous floor scrubbers and disinfection robots serve Singapore's commercial real estate and healthcare facilities.
Assembly holds the largest task volume. Inspection is gaining share fastest as quality automation spreads beyond automotive.
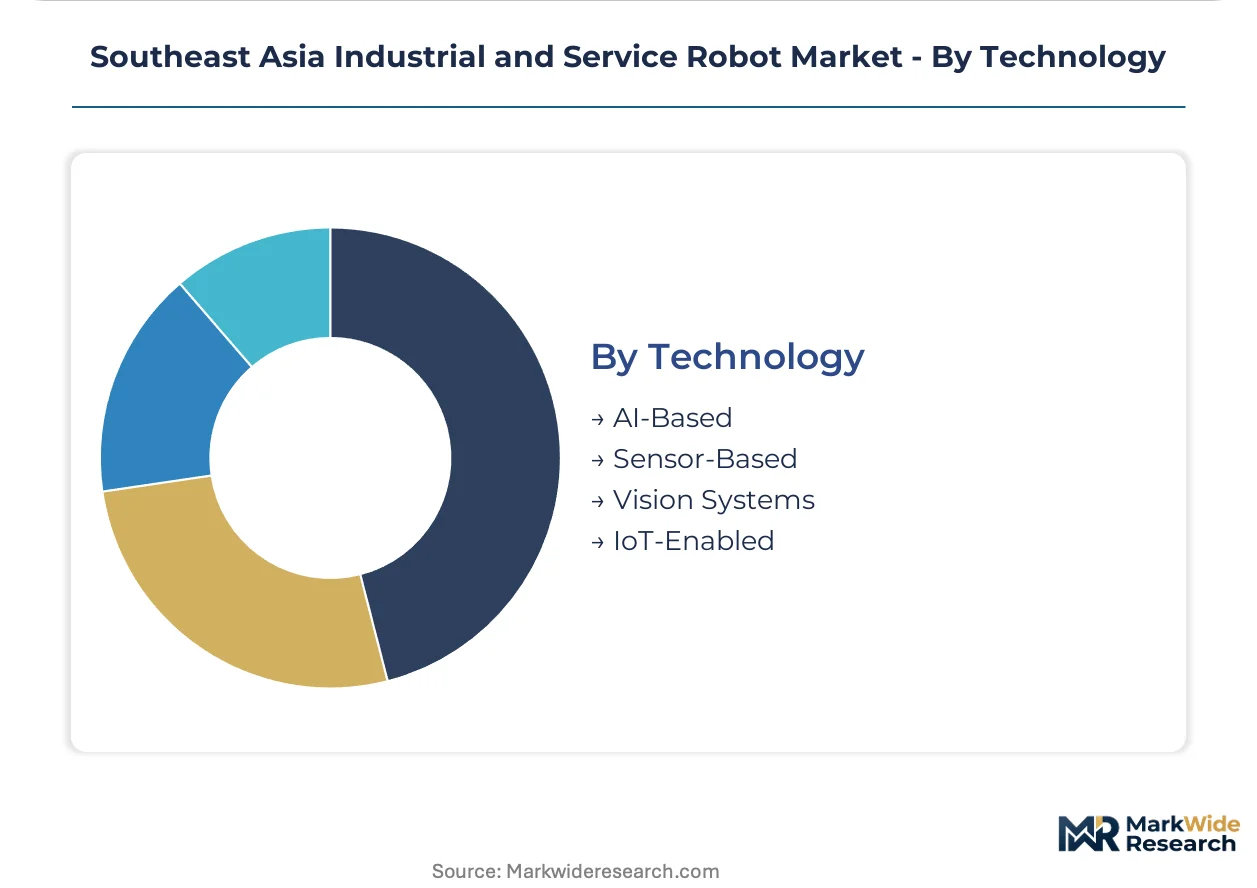
Technology:
Intelligence layer differentiation separates premium pricing tiers from commodity hardware competition.
- AI-Based:Machine learning pose estimation and predictive maintenance algorithms enable unstructured environment operation in Indonesian food processing where product variability defeats rule-based programming.
- Sensor-Based:Force-torque and proximity sensing packages enable fenceless collaborative deployment, opening mid-market access for small and medium enterprises previously excluded by safety infrastructure costs.
- Vision Systems:3D cameras and depth sensors support adaptive pick-and-place in Vietnamese electronics packaging without mechanical changeovers.
- IoT-Enabled:Remote monitoring and over-the-air software updates underpin outcome-based availability contracts in Thailand's automotive supply chain tiers.
Sensor-based platforms hold the broadest installed base. AI-based systems are expanding most quickly as edge computing costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing across Southeast Asia generates asymmetric robot demand, with Vietnam and Thailand importing precision automation systems while Singapore re-exports control technologies and integration services to regional industrial clusters.
Vietnam
Electronics contract manufacturers in the northern industrial corridor deploy articulated and SCARA robots to offset workforce shortages and wage inflation. Vietnam's Decree 126 offers technology investment credits for automation equipment with local workforce training components. Bac Ninh and Hai Phong host dense concentrations of Samsung and Foxconn suppliers automating smartphone assembly and component placement.
Thailand
Automotive transplant factories and tier-one suppliers in the Eastern Economic Corridor drive demand for high-repeatability welding and material handling systems. Thailand's Board of Investment provides accelerated depreciation and import duty exemptions on automation equipment for qualifying manufacturing investments. Rayong and Chonburi anchor robot deployment around Japanese and German OEM assembly plants.
Singapore
Third-party logistics operators and precision engineering firms adopt mobile robots and collaborative platforms for warehouse automation and high-mix assembly. Enterprise Singapore grants mandate workforce training hours and local supplier development as conditions for subsidy disbursement. Jurong and Tuas industrial zones concentrate system integrators serving regional re-export markets.
Malaysia
Electronics packaging and precision metalworking sub-contractors in Peninsular Malaysia represent underpenetrated whitespace for standardized collaborative robots. Malaysia's Industry4WRD national policy structures capital allowances and tax incentives around smart factory certification thresholds. Penang and Selangor host semiconductor packaging and medical device manufacturers expanding automation for export quality compliance.
Indonesia
Food processing and packaging operations in Java sustain manual assembly economics due to prevailing wage levels, limiting robot adoption to multinational-owned facilities with strict quality protocols. Indonesia's Ministry of Industry coordinates with ASEAN partners on harmonized safety standards for imported automation equipment. Bekasi and Karawang industrial estates see selective deployment in instant noodle and beverage packaging lines.
Southeast Asia Industrial and Service Robot Market Competitive Landscape
Listed leaders compete with private specialists across controller technology and system integration capabilities, producing a tiered structure where premium precision tiers command 40-60% price premiums over standard utility configurations. Japanese and European vendors dominate high-repeatability segments through legacy controller protocol relationships with transplant automotive factories. Three archetypes populate the competitive map: integrated motion control specialists, collaborative robot pure-plays, and regional system integrators with certification capabilities. Consolidation pressure and strategic partnership formation represent the dominant competitive vectors as vendors seek to close gaps in safety certification and local service coverage.
Within the integrated motion control tier, FANUC Corporation and Yaskawa Electric Corporation exemplify the controller technology leadership that anchors premium positioning across Thai automotive and Vietnamese electronics facilities. KUKA AG occupies a position representing deep integration with German manufacturing standards and automotive transplant supply chains. These three entities sit within distinct geographic and technological anchoring strategies that shape competitive dynamics across the region's certification-bifurcated procurement landscape.
| Leading Market Players |
|---|
| KUKA AG |
| Denso Corporation |
| FANUC Corporation |
| Omron Corporation |
| Mitsubishi Electric Corporation |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries Ltd |
| Delta Electronics |
| ABB Ltd |
| Others |
Value Network & Pricing Analysis
Controller and servo motor lead times stretching 16-24 weeks concentrate pricing power with Japanese and European precision motion suppliers, compressing system integrator margins while amplifying premiums for vendors with captive component inventories across Thailand and Vietnam.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO 10218-1 certification grade and after-sales service bundling as the primary price differentiation drivers. Pricing pressure stems from small and medium enterprises in Malaysia and Thailand unbundling maintenance contracts from capital equipment procurement. Contract manufacturers in Vietnam's northern corridor exhibit the highest price sensitivity due to thin assembly margins, while automotive transplant factories in Thailand's Eastern Economic Corridor prioritize controller reliability over unit cost.
Supply Chain Analysis
Inventory concentration for precision motion controllers and harmonic drives sits with suppliers in Japan, Germany, and South Korea, exposing Southeast Asian system integrators to currency volatility and extended replenishment cycles. The supply chain draws from rare earth magnets sourced through Chinese processing facilities and servo motors manufactured in Japanese industrial clusters. Single-source vulnerability around force-torque sensor modules creates bottleneck risk for collaborative robot vendors. Distribution runs through regional technical centers in Singapore and Bangkok that coordinate final integration with domestic polytechnic training partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where outcome-based availability contracts and predictive maintenance subscriptions expand faster than hardware unit sales, particularly in Thailand's automotive supply chain tiers.
For Market Incumbents: Compound controller technology leadership through backward integration into safety-rated sensor modules, defending against emerging collaborative pure-plays eroding premium positioning. Deepen certification partnerships with Vietnamese polytechnics to satisfy Decree 126 local content thresholds and lock out competitors lacking workforce training infrastructure.
For New Entrants and Emerging Players: Anchor in Malaysian Industry4WRD whitespace among Peninsular metalworking and plastics sub-contractors currently excluded by legacy vendor service coverage gaps. Target standardized collaborative platforms with localized training support as the most penetrable entry vector, leveraging fenceless deployment economics to bypass safety infrastructure retrofit barriers that constrain established competitors.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ISO 10218-1 certification scarcity and regional technical center requirements favor scaled vendors with compliance infrastructure over fragmented pure-plays. Target system integrators with certified safety engineer pipelines and established government training contracts. Monitor Vietnamese electronics wage inflation rates as the inflection signal for accelerated automation substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Partnership Formation | ISO 10218-1 validation partnerships with Thai and Vietnamese polytechnics satisfy subsidy eligibility rules. |
| Backward Integration into Sensors | In-house force-torque module production reduces lead time exposure and captures safety-rated margin premiums. |
| Outcome-Based Service Contracts | Availability guarantees align vendor economics with automotive just-in-sequence downtime penalties in Thailand. |
| Regional Technical Center Expansion | Singapore and Bangkok hubs coordinate integration while satisfying Enterprise Singapore local supplier mandates. |
| Mobile Robot ERP Convergence | Warehouse management system integration opens Vietnamese e-commerce fulfillment and Singapore logistics automation. |
Research Methodology
The analysis maps articulated, collaborative, mobile, and SCARA robot sub-sectors, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and automation system integrators across Thailand, Vietnam, Malaysia, and Singapore. Primary interview findings triangulate against customs trade data, Board of Investment incentive disclosures, Industry4WRD policy documents, and vendor technical certifications. Bottom-up unit deployment estimates reconcile with top-down manufacturing FDI flow analysis.
Consistency checks validate volume and value outputs against external benchmarks including national automation subsidy disbursement records and transplant factory capacity expansion announcements. The analytical framework models robot type, end-user industry, application task, and technology intelligence layer across the projection horizon. CAGRs derive from installation base growth rates adjusted for replacement cycles and technology substitution patterns. Forecast inputs incorporate wage inflation trajectories in Vietnamese electronics corridors and Thai automotive supply chain automation intensity metrics.
Material uncertainties — subsidy rule modifications, safety certification timeline extensions, and currency volatility in precision component sourcing — sit outside the modeled envelope. Forecasts reflect assumptions around continued labor shortage pressure and policy incentive continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Social Robots Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Sweden Robotic Lawn Mower Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Medical Service Robots Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
SLAM Robots Market