
 Wheel Arch Liner Market | 2026-2036
Wheel Arch Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Arch Liner Market Insights
Aftermarket service revenue is tilting toward OEM-captive programs as vehicle complexity rises and warranty terms extend. Borgers leverages its acoustic engineering heritage to sustain premium positioning in European supply chains. Hanwha anchors Asian production networks through integrated resin-to-component operations. Magna International competes via modular assembly capabilities that bundle wheel arch liners with adjacent underbody systems.
A wheel arch liner is a formed protective panel, typically manufactured from polypropylene, thermoplastic olefin, or fiber-reinforced composite through injection molding or thermoforming processes, designed to shield vehicle underbody components from road debris, moisture, and corrosion while managing aerodynamic drag and acoustic transmission. Front liner configurations dominate current OEM specifications due to higher debris exposure and integration with engine bay thermal management, while composite material adoption accelerates fastest as manufacturers substitute glass-fiber-reinforced grades for metal alternatives to achieve mass reduction targets. Aftermarket providers occupy a fragmented channel layer where universal-fit SKUs compete on price against direct-fit programs controlled by dealership networks.
EPA fuel economy standards and NHTSA safety regulations in the United States, alongside REACH chemical compliance and EU End-of-Life Vehicle directives in Europe, compel material transparency and recyclability in wheel arch liner formulations. China's MIIT passenger vehicle corporate average fuel consumption rules drive similar lightweighting imperatives across domestic and joint-venture production. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer recycling infrastructure investments to secure feedstock access and regulatory continuity.
Market Dynamics
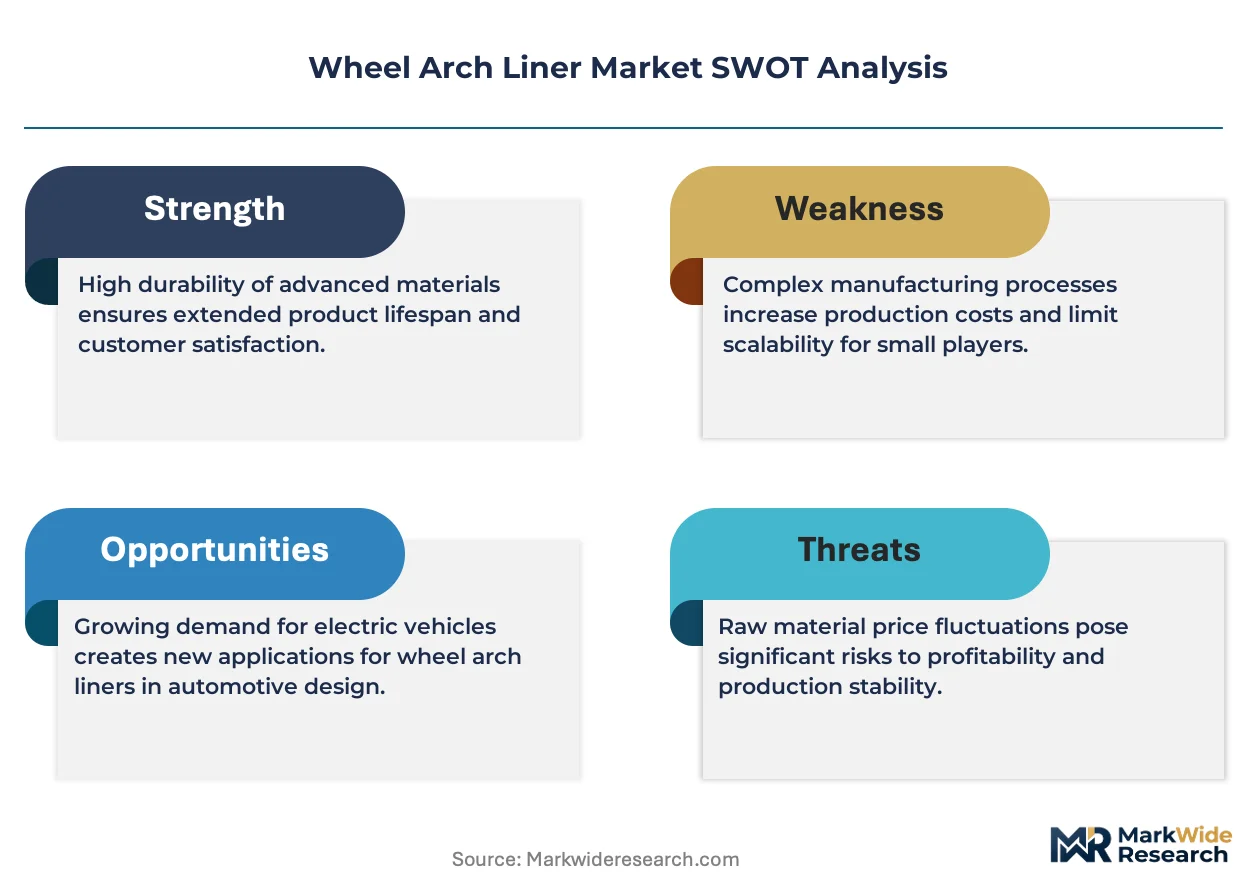
OEM lightweighting mandates under EPA fuel economy standards and EU CO2 fleet rules are compressing material substitution timelines, forcing polypropylene and glass-fiber-reinforced composites to displace metal wheel arch liners at accelerated procurement cycles.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:US automakers face escalating penalties for fleet inefficiency, driving thermoplastic liner adoption to shave kilograms from vehicle underbodies.
- China MIIT passenger vehicle rules:Domestic and joint-venture manufacturers must hit aggressive consumption targets, prioritizing injection-molded wheel arch protection over heavier stamped metal alternatives.
- Glass-fiber-reinforced polypropylene:Material suppliers have refined long-fiber thermoplastic grades that match metal stiffness at 60% lower density, unlocking mass-production viability.
Market Restraints
- Propylene monomer volatility:Wheel arch liner margins compress when naphtha-derived feedstock costs spike, exposing converters to margin erosion they cannot pass through to OEMs.
- Tooling capex concentration:Large-tonnage injection molding equipment and Class A surface finish dies require capital commitments that freeze out mid-tier suppliers from front-liner contracts.
- REACH SVHC disclosure:ECHA substance-of-very-high-concern lists force reformulation of certain flame-retardant additives, creating compliance lag before new grades achieve OEM validation.
Strategic Opportunities
- India PLI scheme for auto components:Domestic manufacturing incentives create localized supply options for global OEMs seeking to de-risk China-centric sourcing.
- Recycled-content mandates:EU End-of-Life Vehicle directive revisions will require post-consumer polymer feedstock, rewarding early movers with secured rPP supply contracts.
- Acoustic-thermal integration:Wheel arch liners are hybridizing with underbody shields and engine bay insulation, opening bundled module contracts with higher per-vehicle content.
Industry Challenges
- Simulation talent scarcity:OEMs now demand upfront CAE validation of acoustic transmission and thermal performance, but finite element analysts with polymer-specific expertise command premium compensation.
- Legacy paint-line compatibility:New composite formulations must survive e-coat bake cycles without warping, forcing iterative tooling adjustments that delay SOP dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Arch Liner Market |
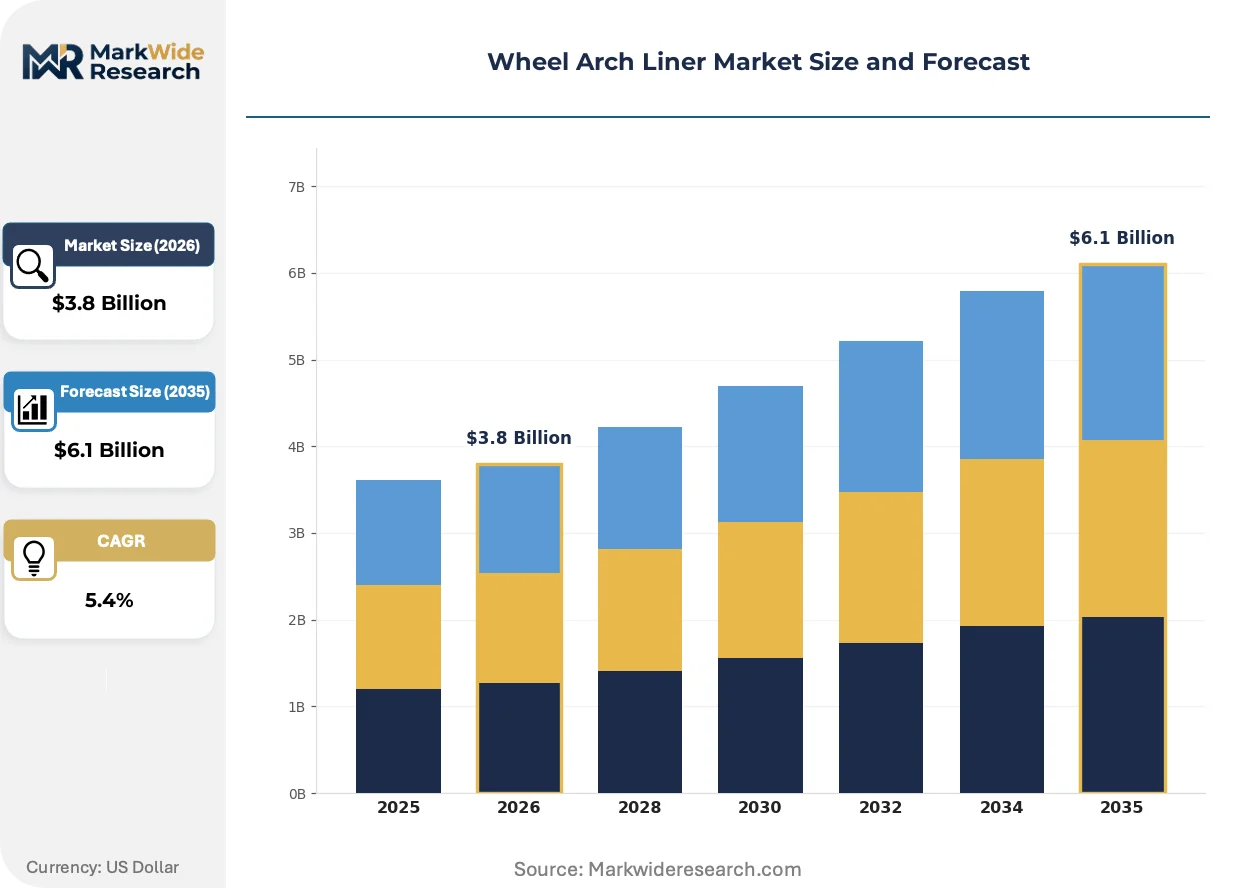
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Liner, Rear Liner, Full Set, Custom Fit Material: Plastic, Rubber, Composite, Metal End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Installation Type: Direct Fit, Universal Fit, Bolt-On, Adhesive |
| Companies Covered | Auria Solutions, Röchling, Borgers, Hanwha, Autoneum, Adler Pelzer, Nihon Plast, Plastic Omnium, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Arch Liner Market Trends and Innovations
Material science breakthroughs and regulatory stringency are converging to redefine wheel arch liner specifications, with acoustic performance and recyclability now weighted equally with mass reduction in OEM technical scorecards.
Long-fiber-reinforced thermoplastic compounds are hybridizing traditional polypropylene with glass fiber lengths exceeding 10mm, delivering structural rigidity previously requiring metal stampings. Tier-1 suppliers in Germany and the United States are qualifying these grades for front-wheel applications where stone impact resistance is critical. The technology is hybridizing cost structures by collapsing separate acoustic insulation layers into single-piece multifunctional liners.
REACH chemical compliance and EU End-of-Life Vehicle directives are forcing full material transparency through supply chains, with ECHA SCIP database requirements mandating disclosure of polymer additives and reinforcement fibers. Converter operations must now maintain batch-level traceability from resin pellet to finished component. European OEMs are responding by pre-qualifying suppliers with certified recycling partnerships and closed-loop material passports.
Fleet procurement departments are consolidating underbody component sourcing into platform-level module contracts, displacing discrete part purchasing. This behavior compresses the supplier base to integrators capable of delivering wheel arch liners, underbody shields, and engine bay protection as unified assemblies. The shift is most visible in Germany and China, where Volkswagen Group and SAIC-GM-Wuling operations have adopted modular sourcing frameworks for new electric vehicle architectures.
Wheel Arch Liner Market Segmentation
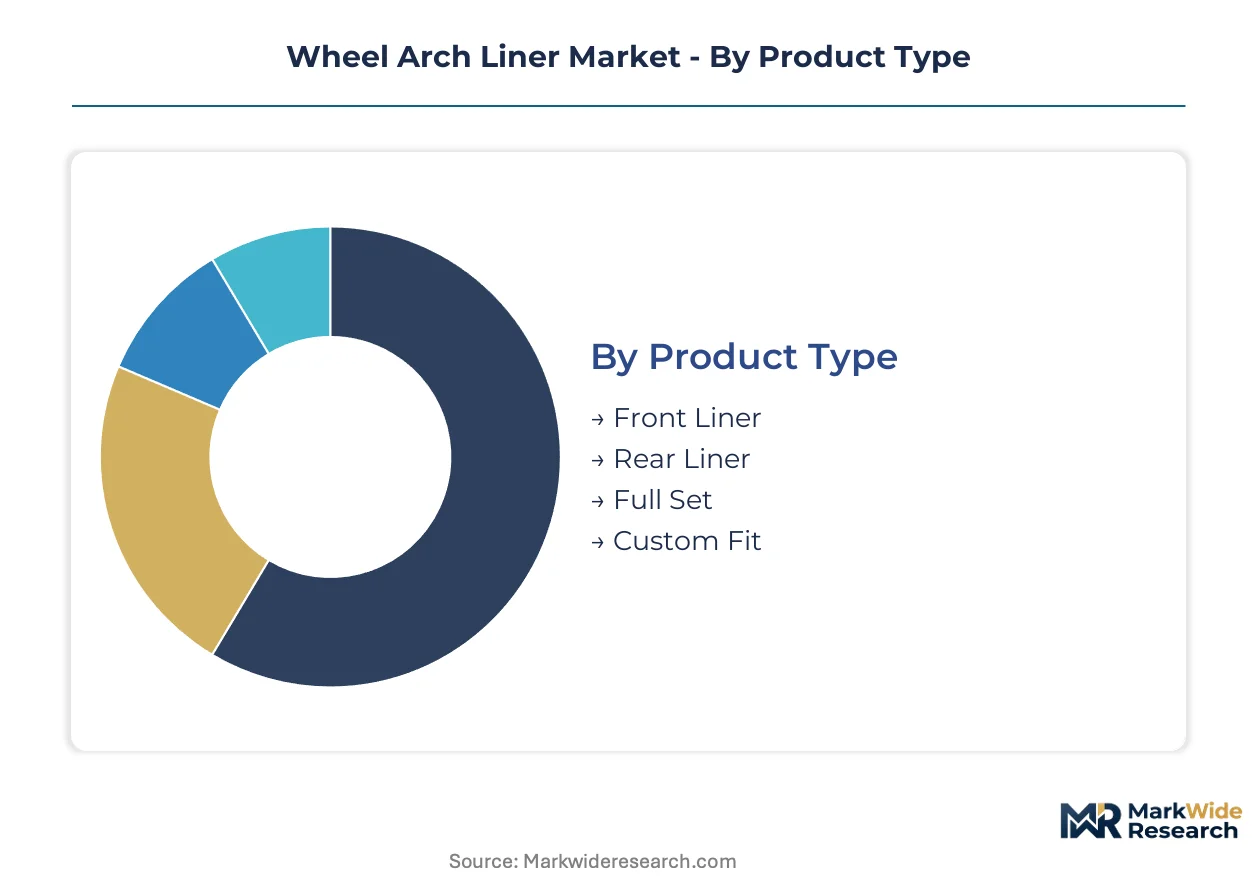
Wheel arch liner procurement splits across fundamentally different technical and commercial logics. OEMs prioritize integrated thermal-acoustic modules validated through CAE protocols, while aftermarket channels compete on fit precision and inventory velocity against universal-fit alternatives.
Product Type:
The use-case spectrum spans debris-intensive front axle protection through complete underbody coverage systems.
- Front Liner:Engineered from glass-fiber-reinforced polypropylene to withstand stone impact and manage engine bay thermal radiation. Volkswagen Group and SAIC-GM-Wuling specifications concentrate procurement in Germany and China where EPA and MIIT fuel economy rules demand lightweighting.
- Rear Liner:Injection-molded thermoplastic designs with lower structural loading requirements than front configurations. Demand clusters in US pickup truck platforms where NHTSA corrosion standards drive material selection toward salt-spray-resistant grades.
- Full Set:Coordinated four-wheel coverage systems bundled under single part numbers for platform-level sourcing efficiency.
- Custom Fit:Application-specific geometries tooled for low-volume specialty vehicles and restoration markets.
Established volume favors Front Liner; emerging adoption favors Full Set.
Material:
Cost tier stratification separates commodity thermoplastics from engineered composites with validated recycling pathways.
- Plastic:Polypropylene and thermoplastic olefin compounds dominate through injection molding economies and established e-coat bake compatibility. REACH SVHC disclosure requirements under ECHA mandates are forcing additive reformulation across European supply chains.
- Composite:Long-fiber-reinforced grades with glass fiber lengths exceeding 10mm deliver metal-comparable stiffness at 60% lower density. German Tier-1 suppliers are qualifying these for front-wheel applications where OEM lightweighting targets are most aggressive.
- Rubber:Thermoset elastomer formulations retained for extreme-flexibility applications in commercial vehicle wheel wells.
- Metal:Stamped aluminum and steel alternatives contracting to niche heavy-duty segments where impact resistance trumps mass reduction.
Procurement weighting tilts toward Plastic for volume applications; Composite captures the steepest expansion trajectory as fiber-reinforced grades achieve OEM validation.
End User:
Customer type determines validation burden, warranty exposure, and margin structure across the value chain.
- OEMs:Platform-level module contracts requiring upfront CAE validation of acoustic transmission and thermal performance. Finite element analysts with polymer-specific expertise command premium compensation, constraining supplier pool depth.
- Aftermarket Providers:Fragmented channel layer competing on price against direct-fit programs, with universal-fit SKUs facing margin compression from propylene monomer volatility.
- Dealerships:OEM-captive service networks capturing extended warranty repair revenue as vehicle complexity rises.
- Vehicle Assemblers:Contract manufacturing operations in India PLI scheme zones seeking localized supply options to de-risk China-centric sourcing.
Margin concentration sits with OEMs; volume expansion favors Aftermarket Providers.
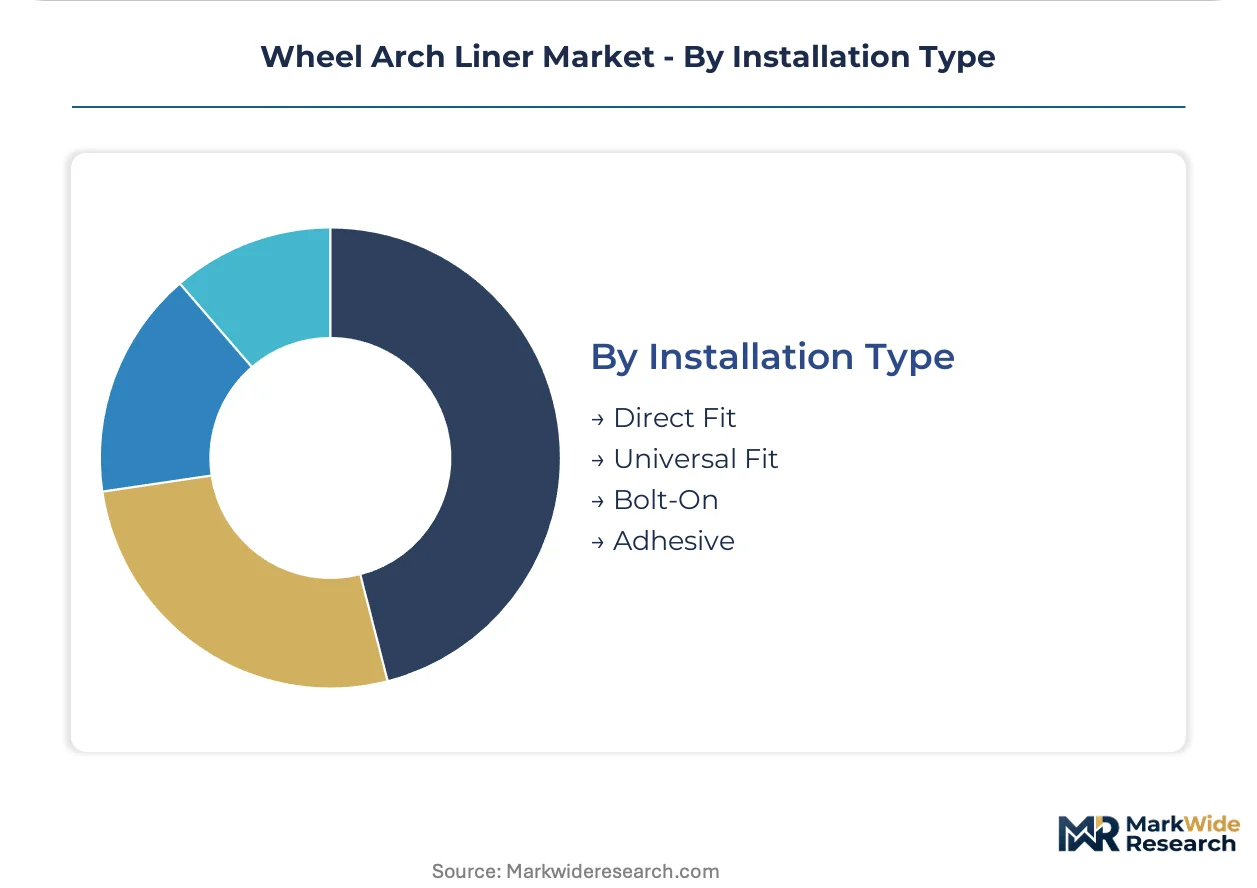
Installation Type:
Application methodology separates production-line integration from field-service economics.
- Direct Fit:Tooling-matched geometries requiring no modification, commanding price premiums through fit precision and reduced labor content.
- Bolt-On:Mechanical fastening systems specified for heavy-duty commercial platforms where serviceability trumps integration density.
- Universal Fit:Trim-to-fit designs competing on price in price-sensitive aftermarket channels with higher return rates.
- Adhesive:Bonded attachment systems emerging in electric vehicle architectures where underbody aerodynamic continuity is prioritized.
Production throughput favors Bolt-On; design evolution favors Adhesive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheel arch liner procurement patterns diverge sharply across major automotive production centers, with European OEMs prioritizing acoustic-thermal integration while Asian manufacturers emphasize resin-to-component cost optimization.
Germany
Volkswagen Group and BMW specifications drive demand for glass-fiber-reinforced polypropylene front liners with validated e-coat bake compatibility. REACH SVHC disclosure requirements under ECHA mandates force batch-level traceability from resin pellet to finished component. Stuttgart and Munich industrial clusters host Tier-1 suppliers qualifying long-fiber thermoplastic grades for electric vehicle architectures.
China
SAIC-GM-Wuling and BYD production volumes concentrate procurement of injection-molded thermoplastic liners under MIIT corporate average fuel consumption rules. The country's national automotive regulator enforces aggressive lightweighting targets across domestic and joint-venture manufacturing. Yangtze River Delta production hubs around Shanghai integrate wheel arch liners with underbody shield modules for export-bound electric vehicles.
United States
Detroit Three automakers specify wheel arch liners for full-size pickup platforms where NHTSA corrosion standards override mass reduction priorities. EPA Corporate Average Fuel Economy penalties escalate through 2026, pressuring thermoplastic substitution for metal alternatives. Southeast Michigan supplier parks coordinate Class A surface finish tooling for front-liner contracts tied to next-generation truck architectures.
India
Maruti Suzuki and Hyundai Motor India operations source localized wheel arch protection under the PLI scheme for auto components. The national automotive component incentive program rewards domestic manufacturing investments with graduated subsidies. Tamil Nadu and Gujarat industrial corridors attract global OEMs seeking to de-risk China-centric supply chains for compact passenger vehicle production.
Japan
Toyota and Honda specifications emphasize acoustic transmission management in hybrid vehicle wheel wells. METI carbon neutrality roadmaps push recycled-content thermoplastic formulations through supply chain partnerships. Aichi Prefecture manufacturing clusters coordinate resin compounding and injection molding operations within 50-kilometer radii of final assembly plants.
Wheel Arch Liner Market Competitive Landscape
Capability concentration sits with acoustic engineering specialists; scale advantage sits with modular integrators. The supplier base stratifies into three tiers: resin-to-component operators controlling polymer feedstock, acoustic-focused engineers delivering NVH-optimized solutions, and platform integrators bundling underbody systems. Dominant competitive moves include strategic partnerships for recycled polymer access and capacity expansion in India PLI scheme zones.
Among German fabricators, Borgers SE & Co. KGaA and Röchling SE & Co. KG exemplify the acoustic-engineering archetype through heritage positioning in European supply chains. Magna International Inc. anchors the modular-integration tier with capabilities spanning wheel arch liners through complete underbody assemblies. These three entities represent distinct strategic postures: feedstock control, NVH specialization, and platform-scale bundling.
| Leading Market Players |
|---|
| Auria Solutions |
| Röchling |
| Borgers |
| Hanwha |
| Autoneum |
| Adler Pelzer |
| Nihon Plast |
| Plastic Omnium |
| Magna International |
| Others |
Pricing and Supply Chain Analysis
Propylene monomer volatility determines both pricing tier spreads and supply chain shape, compressing margins for converters when naphtha-derived feedstock costs spike while simultaneously forcing OEMs toward long-term offtake contracts with resin-integrated suppliers in Germany and China.
Pricing Analysis
Long-term offtake agreements dominate OEM procurement, insulating Volkswagen Group and SAIC-GM-Wuling from spot market swings while aftermarket channels absorb transactional exposure. Price differentiation hinges on Class A surface finish certification and e-coat bake compatibility, with front-liner contracts commanding premiums over rear configurations. Cost compression in commodity thermoplastic grades is intensifying because propylene volatility erodes converter margins faster than pass-through mechanisms allow. Fleet procurement departments exhibit lowest price sensitivity; universal-fit aftermarket distributors face acute margin pressure from resin cost spikes.
Supply Chain Analysis
Extended payment terms from OEM procurement departments strain working capital for mid-tier converters, accelerating consolidation toward resin-to-component operators with captive supply of polypropylene compounds. Manufacturing concentrates in Germany, China, and the United States, with Yangtze River Delta and Southeast Michigan supplier parks anchoring regional production. Feedstock draws from naphtha crackers in the Middle East and shale-derived propylene in North America. Single-source vulnerability concentrates in long-fiber thermoplastic grades qualified for front-wheel applications. Distribution runs through Tier-1 integrators bundling wheel arch liners with underbody shield modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-level module contracting fragments the supplier base, creating niches for acoustic specialists and recycled-material pioneers as OEMs disaggregate sourcing across performance tiers.
For Market Incumbents: Entrench position through backward integration into recycled polypropylene feedstock and capacity expansion in India PLI scheme zones. Borgers and Röchling must defend acoustic engineering premiums against modular integrators bundling wheel arch liners with thermal management systems. Certification investment in ECHA SCIP database compliance secures European OEM continuity. For New Entrants and Emerging Players: Pursue aftermarket direct-fit programs where dealership network control remains porous and universal-fit SKU quality failures create replacement demand. The India PLI scheme offers the most penetrable geography for localized production serving Maruti Suzuki and Hyundai Motor India. A go-to-market angle anchored in recycled-content material passports differentiates against incumbent virgin-resin positioning. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors resin-to-component operators with validated recycling partnerships and CAE simulation capabilities. Long-term viability hinges on securing post-consumer polymer feedstock contracts ahead of EU End-of-Life Vehicle directive revisions. The signal to watch is OEM pre-qualification velocity for closed-loop material passport programs.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polypropylene Supply Agreement | Secures rPP feedstock ahead of EU End-of-Life Vehicle mandate enforcement. |
| Acoustic-Thermal Module Integration | Bundles wheel arch liners with underbody shields for Volkswagen Group platform contracts. |
| India PLI Scheme Manufacturing Footprint | Captures domestic production subsidies serving Maruti Suzuki localization requirements. |
| Long-Fiber Thermoplastic Grade Qualification | Validates glass-fiber-reinforced polypropylene for front-wheel stone impact applications. |
| ECHA SCIP Database Compliance Investment | Enables batch-level traceability for REACH SVHC disclosure mandates. |
Research Methodology
Desk research of automotive production databases, IHS Markit registration data, and SEC filings preceded structured interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. Primary fieldwork captured procurement cycle dynamics and CAE validation protocols. Secondary validation drew from customs records, MIIT corporate average fuel consumption disclosures, and EPA fuel economy compliance reports. Bottom-up vehicle production estimates triangulated against top-down thermoplastic consumption forecasts.
Assumptions held EPA and MIIT regulatory stringency fixed at current trajectory while varying propylene feedstock cost scenarios across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from vehicle production forecasts weighted by thermoplastic substitution rates for metal alternatives. Industry-specific inputs incorporated e-coat bake compatibility validation timelines and long-fiber thermoplastic grade qualification schedules.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by resin producers or sudden OEM pivot to adhesive attachment systems would shift outcomes. Macroeconomic deviation, regulatory acceleration, or breakthroughs in bio-based polypropylene formulations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
Powerglide Shifter Market
Automotive Parts
Automotive Battery Frames Market
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
North America Automotive AHSS Market