
 Automotive Rain Sensor Market | 2026-2036
Automotive Rain Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rain Sensor Market Analysis
Mid-size vehicle OEMs is rotating share toward premium electric vehicle platforms that bundle rain sensing with full sensor suites. Robert Bosch GmbH leverages its integrated manufacturing footprint to supply windshield-mounted optical modules directly to German and Chinese assembly plants. Valeo SA anchors its position through dedicated R&D centers in France and Czechia that refine capacitive detection algorithms for harsh-weather reliability. Gentex Corporation specializes in mirror-integrated installations that reduce wiring complexity for North American light-truck programs.
An automotive rain sensor detects precipitation on vehicle glass surfaces through optical refraction, capacitance change, or ultrasonic echo measurement, typically operating at infrared wavelengths between 880 and 940 nanometers to distinguish water droplets from dust or fog. The device activates wiper systems and adjusts speed without driver intervention, reducing distraction and glass wear during variable rainfall. Optical sensors dominate volume shipments due to maturity in LED emitter and photodiode supply chains, while capacitive variants capture margin pools in luxury segments that demand multi-zone detection. Smart sensor technology leads growth as embedded microprocessors enable fusion with camera and lidar inputs for unified environmental modeling.
The European Union's F-Gas Regulation and CE marking requirements shape material choices and electromagnetic compatibility testing for rain sensors sold into EU member states. In the United States, NHTSA distraction-reduction guidelines and FMVSS windshield-visibility standards push OEMs toward faster-response sensing architectures. China's MIIT enforces GB standards for automotive electronics that affect sensor calibration protocols for domestic production. Stakeholders must monitor divergence between regional electromagnetic compatibility and environmental testing regimes when configuring platform-global sensor designs.
Market Dynamics
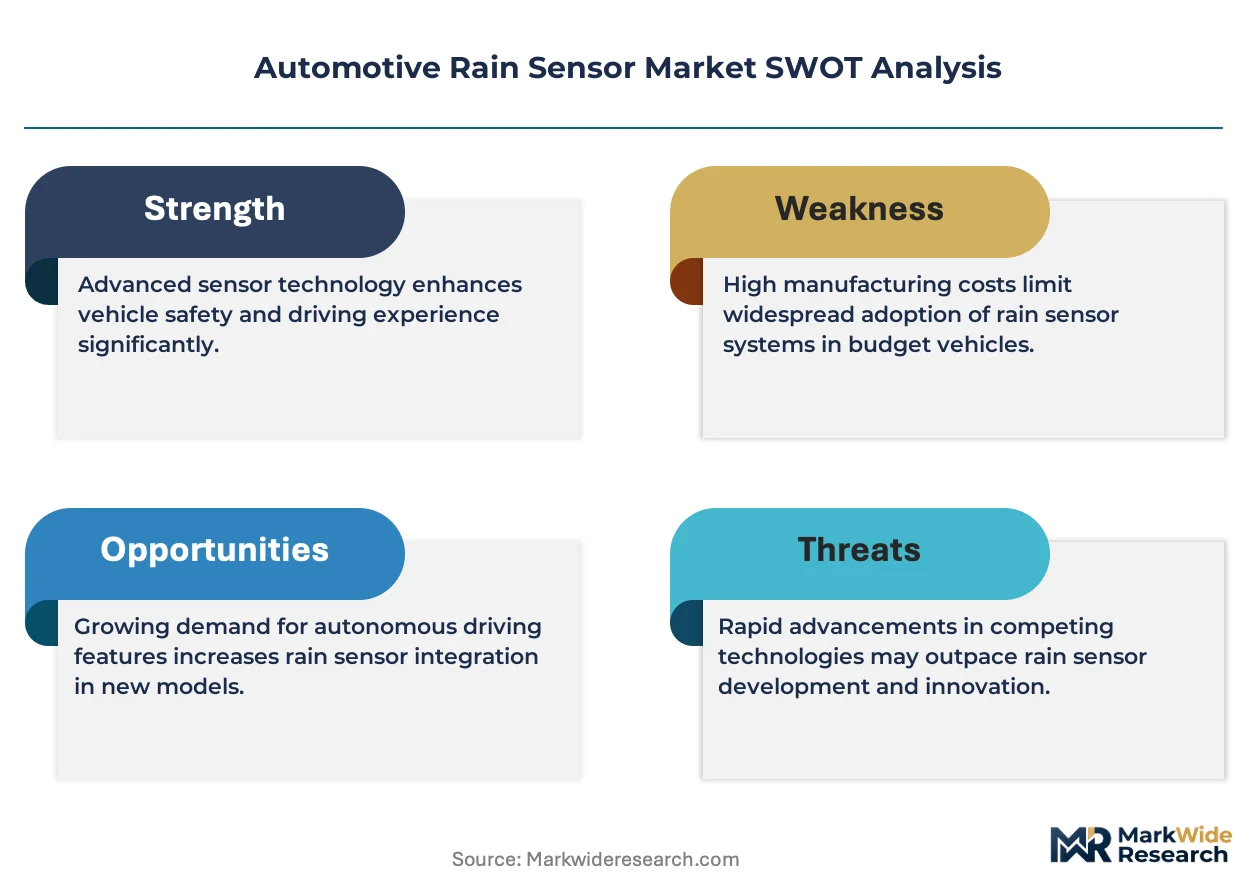
OEM procurement strategies are consolidating sensor sourcing around integrated ADAS module suppliers, compressing standalone rain sensor margins while elevating optical fusion architectures that combine precipitation detection with forward-facing camera inputs.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases are accelerating transitions toward solid-state optical sensing architectures that eliminate refrigerant-dependent components from windshield assemblies.
- ADAS integration mandates:European and Chinese vehicle-type approval frameworks now require automatic wiper activation as a prerequisite for higher-level driver assistance certification, embedding rain sensing into platform-level sensor stacks.
- Silicon photonics maturation:Advances in 940-nanometer LED emitter efficiency and photodiode miniaturization are reducing module footprint and power draw for electric vehicle windshields.
Market Restraints
- Optical component supply concentration:Infrared emitter and detector manufacturing clusters in Taiwan and South Korea create single-source vulnerability for Tier-1 module assemblers.
- Capacitive sensor cost structure:Multi-electrode glass lamination processes require specialized conductive coatings that carry 40-60% raw material premiums over standard optical alternatives.
- Windshield replacement friction:Recalibration requirements for camera-integrated rain sensors extend service bay time and inflate insurance claim costs, depressing aftermarket attachment rates.
Strategic Opportunities
- India automotive electronics:BIS certification pathways for automotive electronics remain underdeveloped for environmental sensors, creating first-mover positioning for suppliers establishing local test facilities.
- Lidar-rain fusion:Convergence of solid-state lidar point clouds with optical precipitation data enables unified hydrometeor classification for autonomous driving stacks.
- Mirror-integrated channels:North American light-truck and SUV platforms are adopting electrochromic mirror assemblies that consolidate rain sensing with glare reduction, opening alternative mounting locations.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety compliance for sensor fusion algorithms requires specialized automotive systems engineering talent that remains scarce in Eastern European and Southeast Asian development centers.
- Windshield OEM integration:Direct glass bonding of sensor modules demands capital-intensive robotic dispensing equipment that smaller Tier-2 suppliers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rain Sensor Market |
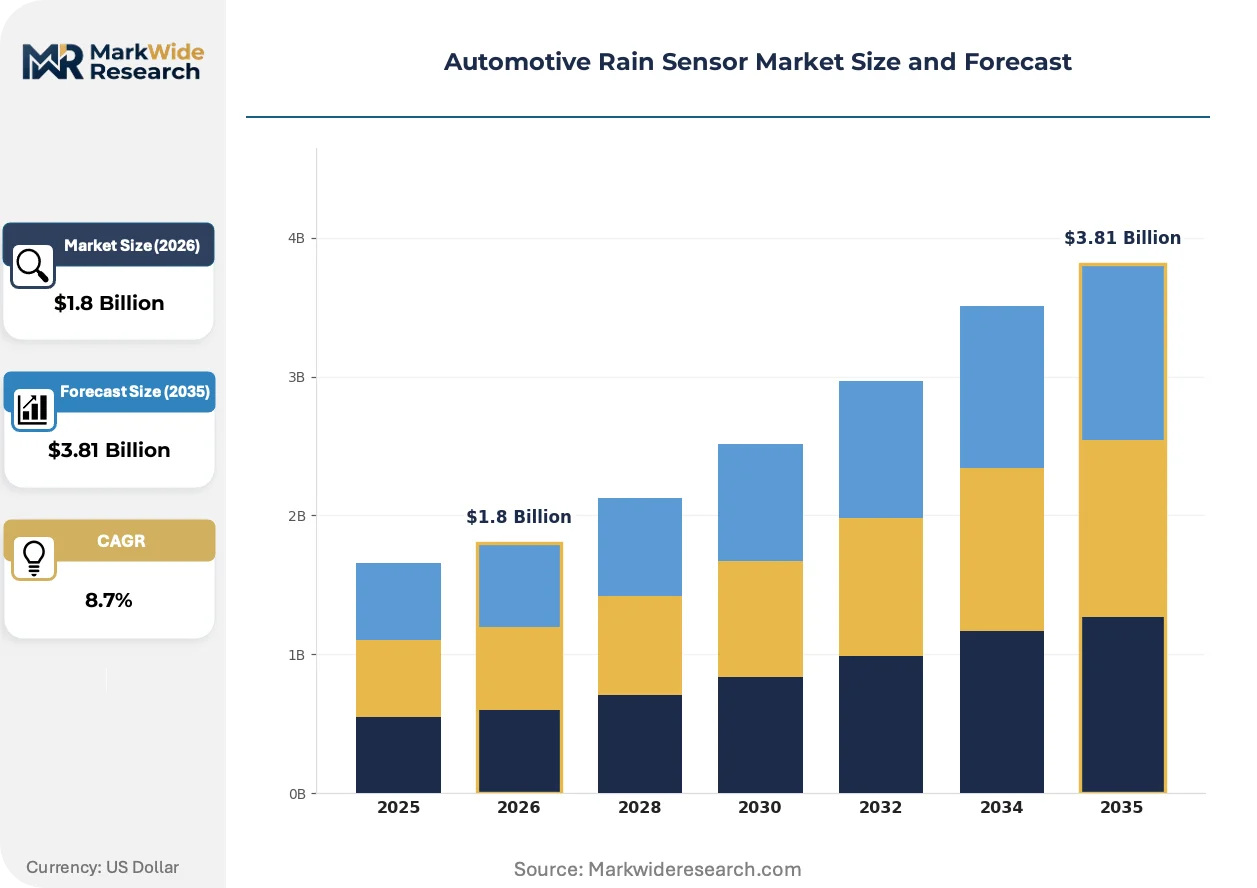
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
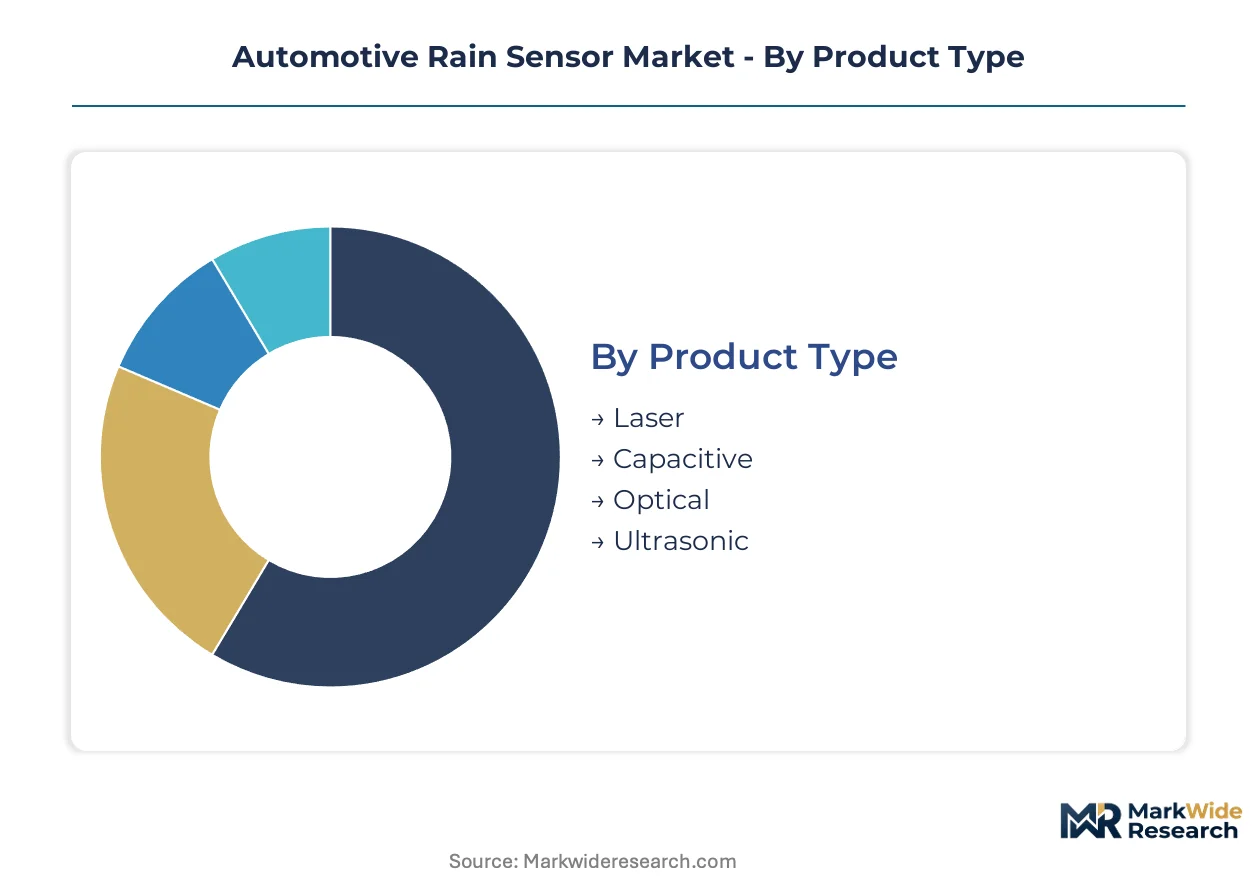
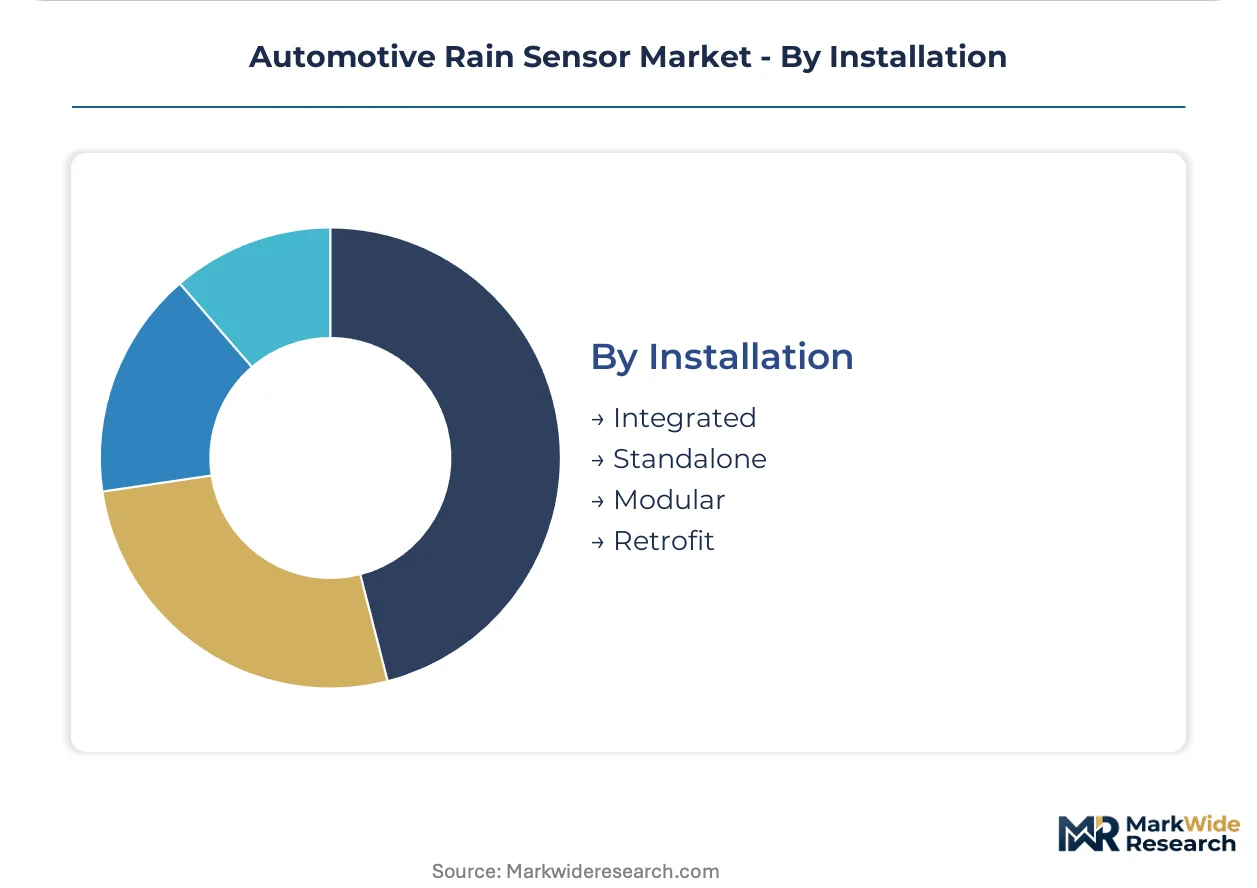
| Segmentation | Product Type: Laser, Capacitive, Optical, Ultrasonic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Smart Sensors, Analog Sensors, Digital Sensors, Hybrid Sensors Installation: Integrated, Standalone, Modular, Retrofit |
| Companies Covered | Valeo SA, Gentex Corporation, Robert Bosch GmbH, Mando Corporation, Aisin Seiki Co., Ltd., Continental AG, HELLA GmbH & Co. KGaA, Marelli Holdings, Inc., DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rain Sensor Market Emerging Trajectories
Sensor fusion architectures are dissolving the boundary between standalone precipitation detection and comprehensive environmental perception, with rain data feeding directly into path-planning algorithms rather than merely triggering wiper motors.
Multispectral optical sensing is decomposing the traditional infrared-only detection paradigm. Advanced modules now sample across near-infrared and short-wave infrared bands to distinguish rain from ice, dust, and organic debris. Premium electric vehicle platforms in Germany and China are adopting these enhanced discriminators to support automated driving mode arbitration. The technology is compressing demand for legacy single-wavelength optical units in segments above mid-size sedans.
China's MIIT GB standards for automotive electronics are tightening electromagnetic compatibility test protocols for sensors mounted behind metallized windshield glass. Domestic OEMs must now demonstrate immunity to 400-megahertz interference from onboard telematics units. The regulation is forcing foreign suppliers to establish localized EMC test chambers in Shanghai and Shenzhen rather than certifying through European notified bodies.
Buyer concentration among mega-platform OEMs is compressing supplier negotiation cycles and unbundling traditional engineering-service contracts from component supply agreements. German and Japanese automakers now separate sensor specification development from volume manufacturing awards, enabling dual-source strategies. This pattern is most visible in battery electric vehicle programs where platform reuse across multiple nameplates amplifies procurement leverage.
Automotive Rain Sensor Market Segmentation
Automotive rain sensor procurement patterns diverge sharply between integrated platform suppliers and standalone component vendors. Technology choices cascade through windshield design, calibration protocols, and aftermarket service economics.
Product Type:
Optical variants dominate export flows to Germany and China, while capacitive units serve premium domestic programs in Japan and the United States.
- Optical:Infrared LED-photodiode pairs operating at 880-940 nanometers detect water droplets through refractive index changes. Demand concentrates in German and Chinese OEM platforms where silicon photonics supply chains enable high-volume, low-cost module production.
- Capacitive:Multi-electrode glass-laminated arrays measure dielectric constant shifts from moisture accumulation. Japanese and US luxury vehicle programs absorb most output, driven by multi-zone detection requirements and tolerance for 40-60% raw material premiums over optical alternatives.
- Laser:Time-of-flight precipitation mapping for autonomous driving validation fleets.
- Ultrasonic:Echo-based detection retained in heavy commercial vehicle applications.
Optical holds the largest share; momentum sits with capacitive as ADAS fusion demands multi-zone granularity.
End User:
Procurement authority is consolidating around Tier-1 integrators capable of bundling rain sensing with forward-facing camera modules.
- Tier-1 Suppliers:Bosch, Valeo, and Gentex-class integrators now specify sensor subcomponents and perform windshield bonding in-house. Their direct OEM relationships compress standalone sensor vendor margins while elevating optical fusion architectures.
- OEMs:Volkswagen Group, Toyota, and BYD-style manufacturers increasingly separate sensor specification development from volume manufacturing awards, enabling dual-source strategies across battery electric platforms.
- Vehicle Assemblers:Contract manufacturers in Eastern Europe and Mexico execute glass bonding per Tier-1 technical packages.
- Aftermarket Providers:Recalibration complexity for camera-integrated sensors depresses attachment rates in collision repair channels.
Tier-1 suppliers command specification authority; aftermarket providers face structural compression from embedded calibration requirements.
Technology:
Smart sensor architectures carry margin premiums that widen with software certification burden.
- Smart Sensors:Embedded microprocessors enable fusion with lidar and camera inputs for unified hydrometeor classification. German and Chinese premium electric platforms are climbing the fastest as ISO 26262 functional safety compliance becomes mandatory for autonomous driving stacks.
- Digital Sensors:Discrete signal processing without fusion capability serves mid-size vehicle price points.
- Analog Sensors:Legacy infrared emitter-detector pairs without onboard processing retained in commercial vehicle cost-sensitive segments.
- Hybrid Sensors:Mixed-signal architectures bridging analog front-ends with digital bus interfaces.
Smart sensors lead value capture; analog sensors defend residual volume in heavy-duty applications.
Installation:
Mounting topology determines recalibration economics and windshield replacement friction.
- Integrated:Direct glass bonding behind metallized windshields demands capital-intensive robotic dispensing equipment. Chinese MIIT GB electromagnetic compatibility standards now require localized EMC test chambers for these configurations.
- Modular:Clip-in sensor housings that separate from camera modules reduce service bay time.
- Standalone:Discrete precipitation detectors without ADAS fusion capability.
- Retrofit:Aftermarket adhesive-mounted units bypassing OEM windshield integration.
Integrated captures platform-level design wins; modular gains share in service-channel flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites China's dominance in automotive electronics exports, while the Rhine-Main-Danube corridor anchors German sensor distribution across Central Europe. These infrastructure assets concentrate procurement authority and calibration laboratory capacity.
China
Domestic OEMs BYD and NIO are scaling premium electric platforms that bundle rain sensing with full ADAS suites. MIIT enforces GB standards for automotive electronics that force foreign suppliers to establish localized EMC test chambers in Shanghai and Shenzhen. Yangtze River Delta manufacturing clusters now host captive calibration facilities for metallized windshield integrations.
Germany
Volkswagen Group and BMW are consolidating sensor sourcing around integrated module suppliers for battery electric architectures. EU F-Gas Regulation accelerates transitions toward solid-state optical sensing that eliminates refrigerant-dependent components. Stuttgart and Munich R&D centers refine fusion algorithms combining precipitation detection with forward-facing camera inputs.
United States
Detroit Three automakers are adopting mirror-integrated rain sensing for light-truck and SUV programs to reduce wiring complexity. NHTSA distraction-reduction guidelines and FMVSS windshield-visibility standards push faster-response sensing architectures. Michigan and Ohio assembly plants execute glass bonding per Tier-1 technical packages from nearby integration centers.
Japan
Toyota and Honda are absorbing capacitive rain sensors for multi-zone detection in luxury hybrid platforms. METI oversees JIS standards that shape electromagnetic compatibility testing for domestic production. Nagoya and Osaka industrial corridors concentrate electrode lamination processes for specialized conductive glass coatings.
India
Maruti Suzuki and Tata Motors are qualifying rain sensors for compact vehicle price points as automatic wiper activation spreads beyond premium segments. BIS certification pathways for automotive electronics remain underdeveloped, creating positioning advantages for suppliers establishing local test facilities in Maharashtra and Tamil Nadu.
Automotive Rain Sensor Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and R&D intensity. The supplier base consolidates around Tier-1 integrators capable of bundling rain sensing with camera modules, compressing standalone sensor margins. Three archetypes dominate: diversified automotive electronics conglomerates, mirror-system specialists, and dedicated sensor technology firms. Competitive moves center on backward integration into LED emitter supply and geographic expansion through captive calibration facilities.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify manufacturing footprint leverage across German and Chinese assembly corridors. Valeo SA occupies a position among French-origin specialists with dedicated development centers in France and Czechia. Gentex Corporation anchors the mirror-integrated channel for North American light-truck programs. These three represent distinct strategic postures: direct glass bonding at scale, capacitive algorithm refinement, and alternative mounting location capture.
| Leading Market Players |
|---|
| Valeo SA |
| Gentex Corporation |
| Robert Bosch GmbH |
| Mando Corporation |
| Aisin Seiki Co., Ltd. |
| Continental AG |
| HELLA GmbH & Co. KGaA |
| Marelli Holdings, Inc. |
| DENSO Corporation |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates both supplier qualification and price differentiation simultaneously, as solid-state optical architectures command premiums over refrigerant-dependent legacy modules while excluding uncertified vendors from German and Chinese OEM procurement lists. Buyers negotiate from consolidated platform volumes that compress standalone sensor margins and elevate fusion-capable suppliers.
Pricing Analysis
Volume-discount tiering structures separate smart sensor fusion modules from discrete optical units from analog legacy components. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 certification grade and ADAS integration depth. Cost compression in the analog tier intensifies because OEMs are unbundling engineering services from component supply agreements. Aftermarket providers exhibit highest price sensitivity due to recalibration complexity depressing attachment rates, while premium EV platforms show lowest sensitivity for multi-zone capacitive variants.
Supply Chain Analysis
Inventory lead times for 940-nanometer LED emitters and photodiode arrays stretch when Taiwan and South Korean foundry capacity tightens. Module assembly draws from German precision optics, Chinese Yangtze River Delta electronics clusters, and Japanese conductive glass coating specialists. Single-source vulnerability in infrared detector supply creates structural risk for Tier-1 assemblers lacking dual-qualified emitters. Distribution runs through captive calibration facilities at Shanghai-Ningbo and Rhine-Main-Danube corridor hubs rather than through independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as automotive production schedules normalize and OEMs restock ADAS sensor inventories deferred during prior capacity constraints.
For Market Incumbents: Fortify backward integration into LED emitter supply chains to neutralize Taiwan and South Korean foundry concentration risk. Deepen captive calibration footprints in Shanghai and Shenzhen to satisfy MIIT GB electromagnetic compatibility mandates before competitors establish localized EMC chambers. Lock in multi-year platform awards with Volkswagen Group and BYD through bundled camera-rain fusion specifications.
For New Entrants and Emerging Players: Differentiate on mirror-integrated mounting architectures for North American light-truck programs where Gentex lacks direct competition in alternative sensor locations. Target India's underdeveloped BIS certification pathways by establishing Maharashtra and Tamil Nadu test facilities ahead of Maruti Suzuki and Tata Motors volume ramp. Pursue electrochromic mirror assembly partnerships rather than direct windshield bonding to bypass capital-intensive robotic dispensing equipment barriers.
For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape toward solid-state optical specialists with refrigerant-free module portfolios. Long-term viability favors suppliers with ISO 26262 functional safety certification capabilities and established EMC test infrastructure across multiple geographies. Watch for MIIT GB standard enforcement intensity in China as the signal indicating whether foreign suppliers must accelerate localized facility investments or retreat to import-dependent positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group and BYD consolidate rain sensing with camera modules across battery electric architectures. |
| Backward Integration into Emitters | Bosch and Continental secure captive 940-nanometer LED supply chains against Taiwan foundry bottlenecks. |
| Geographic Manufacturing Footprint | Valeo establishes Czechia R&D centers and Chinese calibration facilities to serve EU and Asian OEMs simultaneously. |
| Software-Defined Vehicle Investment | Smart sensor architectures enable fusion algorithms that feed precipitation data directly into path-planning stacks. |
| Charging Infrastructure Partnership | Mirror-integrated rain sensing reduces wiring complexity for electric light-trucks at North American fast-charging corridors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from listed Tier-1 suppliers, and customs records for infrared emitter trade flows. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers informed demand-side assumptions. Bottom-up build from sensor content-per-vehicle estimates triangulates against top-down market value reconstructions.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from production schedule trajectories, ADAS penetration curves, and replacement cycle economics across the projection horizon. Industry-specific forecast inputs include MIIT GB standard implementation timelines and EU F-Gas Regulation phase-out schedules for refrigerant-dependent components.
Decision-makers should treat outputs as directional under assumptions of normalized automotive production and steady ADAS regulatory tightening; material deviation in OEM platform delays or trade policy shifts would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Automotive EMC Test Equipment Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
TPMS Battery Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Automotive Clean Cold Technology Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market