
 North America Gear Market | 2026-2036
North America Gear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gear Market Insights
Automotive OEM consolidation toward electrified platforms is recalibrating supplier relationships across the North American gear value chain. Regal Rexnord leverages its broad industrial portfolio to serve diversified machinery demand beyond automotive cycles. Gleason Corporation specializes in precision bevel gear manufacturing systems that command premium positioning in aerospace and defense applications. Commercial Gear & Sprocket Company anchors its competitiveness through custom-engineered solutions for medium-volume industrial clients.
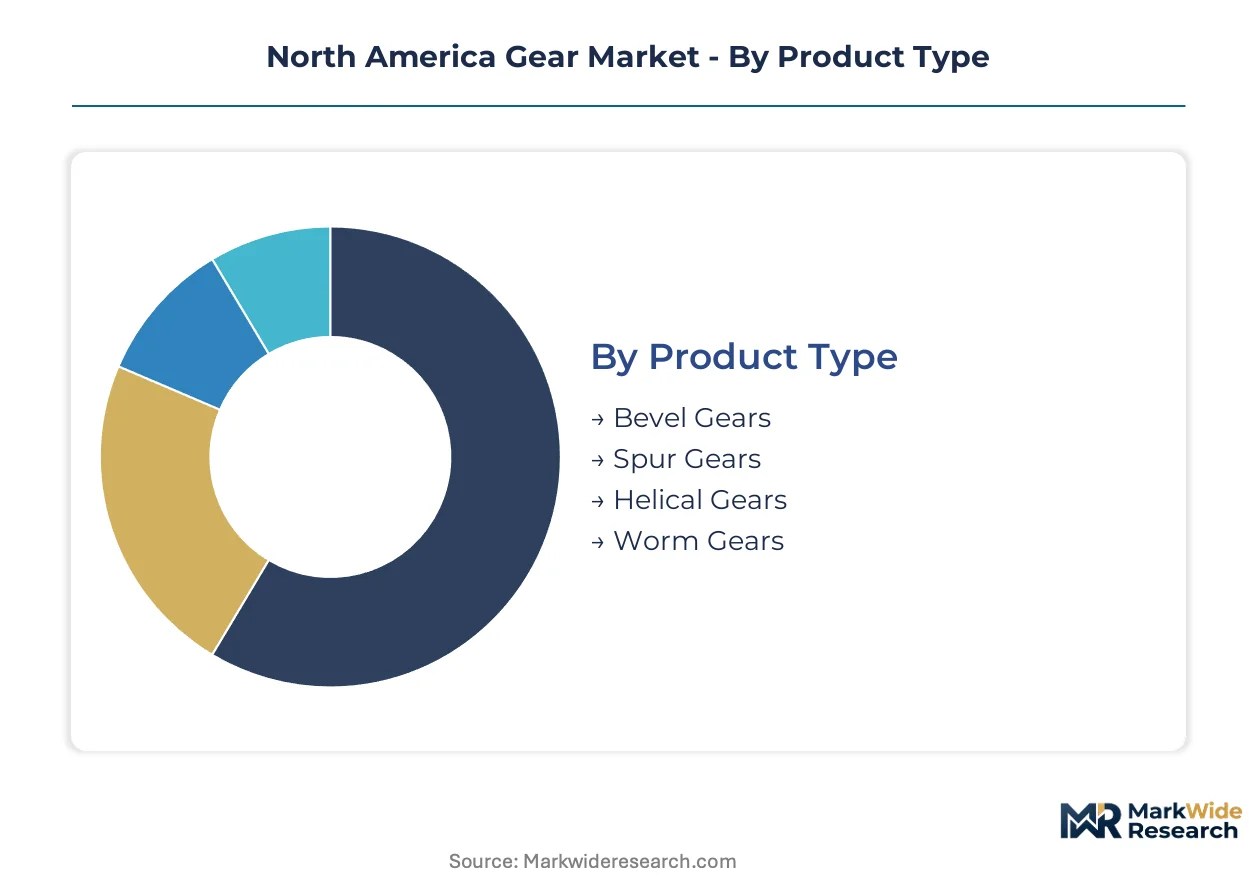
Gears are toothed mechanical components that transmit torque and motion between rotating shafts through precise meshing engagement, typically manufactured via hobbing, shaping, or grinding processes to achieve AGMA or DIN quality grades. Helical gears dominate high-load industrial applications due to smoother tooth engagement and higher load capacity than spur alternatives. Within end-user segmentation, renewable energy represents the fastest-expanding demand pool as wind turbine drivetrains require large-diameter planetary and helical systems. Plastic and composite materials are gaining share in robotics and HVAC applications where noise reduction and corrosion resistance outweigh metallic strength requirements.
NHTSA Corporate Average Fuel Economy standards and EPA tailpipe emissions regulations are compelling automotive gear suppliers to invest in lightweight materials and precision finishing to reduce frictional losses. The FAA airworthiness directives and AS9100 aerospace quality standards govern gear acceptance for commercial aviation applications, creating certification barriers for non-specialized producers. Stakeholders must monitor how US Inflation Reduction Act domestic content provisions reshape sourcing economics for wind energy gearbox assemblies.
Market Dynamics
Automotive electrification is compressing traditional powertrain gear demand while simultaneously opening precision torque-transfer applications in battery electric vehicle drivetrains, forcing suppliers to reallocate capital between declining internal combustion segments and emerging e-axle architectures.
Growth Catalysts
- NHTSA CAFE Standards:Fuel economy mandates are compelling automotive OEMs to specify higher-precision ground gears that reduce frictional losses across transmission architectures.
- Wind Turbine Drivetrains:Renewable energy expansion in the US Great Lakes corridor is generating demand for large-diameter planetary gear systems rated for 20+ year service intervals.
- Additive Manufacturing:Metal 3D printing of conformal cooling channels in gear blanks is enabling topology-optimized designs that reduce weight without sacrificing load capacity.
Market Restraints
- Alloy Steel Price Volatility:Nickel and molybdenum input cost swings compress margin predictability for forged gear producers serving cyclical industrial demand.
- Supplier Concentration Risk:Precision grinding wheel supply concentrates among Japanese and German specialty abrasive manufacturers, creating single-source vulnerability.
- Technical Limitation:Surface fatigue resistance in case-hardened gears remains inferior to through-hardened alternatives for ultra-high-cycle applications above 10^9 load reversals.
Strategic Opportunities
- Mexico Manufacturing Expansion:Nearshoring momentum in Querétaro and Nuevo León offers tariff-advantaged production bases for US-bound automotive gear supply.
- US Inflation Reduction Act:Domestic content provisions for wind energy components create sourcing preference for North American-assembled gearbox systems.
- Digital Twin Convergence:Integration of physics-based gear mesh simulation with IoT vibration monitoring enables predictive maintenance service models.
Industry Challenges
- AGMA Quality Grade Certification:The 12-18 month timeline for achieving Q13-Q15 precision ratings blocks rapid entry into aerospace and medical device supply chains.
- Capex Intensity:CNC gear grinding machines with sub-micron positioning accuracy require $2-4 million capital commitments per production cell.
- Legacy System Integration:Brownfield automotive plants resist retrofitting flexible manufacturing cells optimized for low-volume electric vehicle gear variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gear Market |
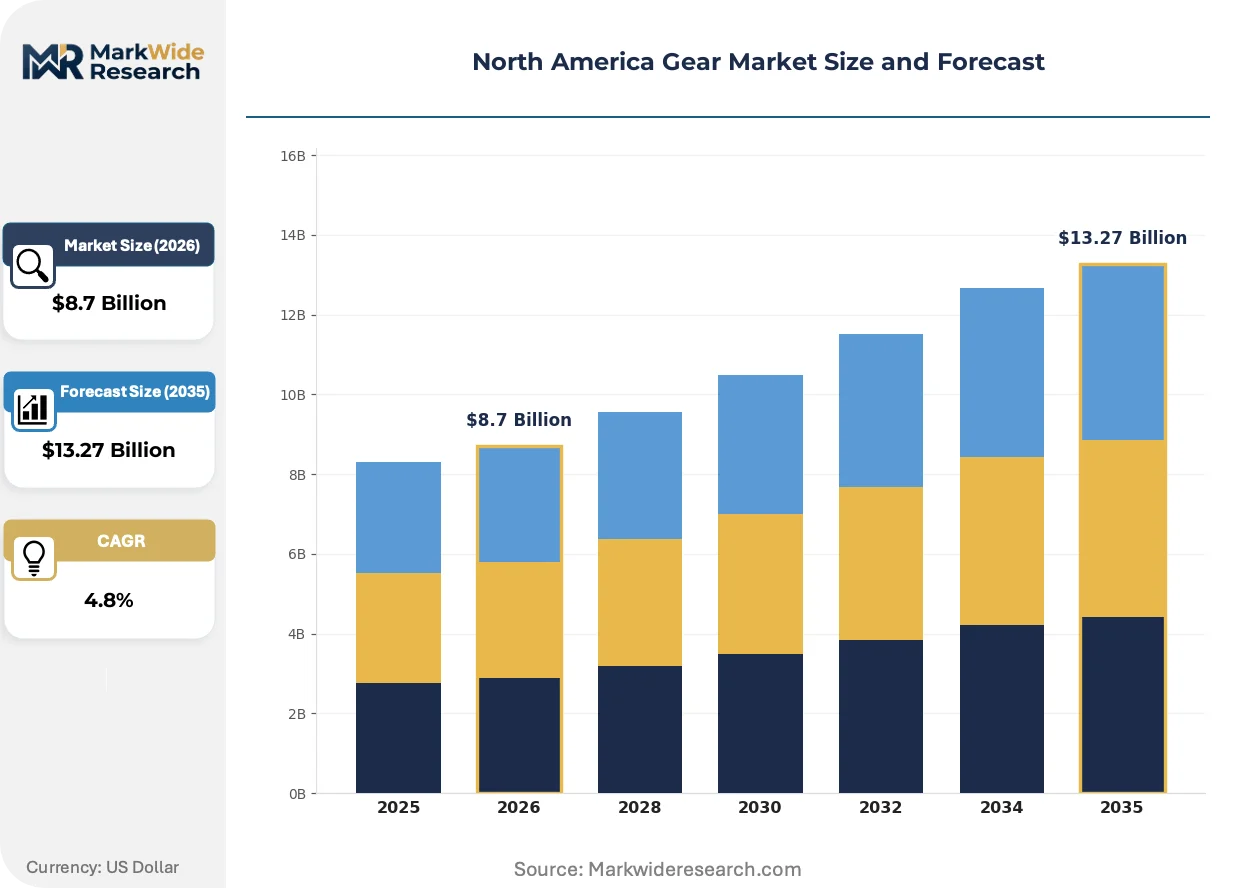
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bevel Gears, Spur Gears, Helical Gears, Worm Gears End User: Aerospace, Automotive, Industrial Machinery, Renewable Energy Material: Steel, Plastic, Aluminum, Composite Application: Power Transmission, Robotics, Construction Equipment, HVAC Systems |
| Companies Covered | Commercial Gear & Sprocket Company, Regal Rexnord, Gleason Corporation, Rockwell Automation, Parker Hannifin Corporation, Boston Gear, Stock Drive Products, Caterpillar Inc., Dayton Gear & Tool, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gear Market Trends and Innovations
Precision manufacturing technologies and regulatory stringency are converging to elevate quality thresholds across North American gear applications, while demand fragmentation is forcing suppliers to diversify beyond traditional automotive dependence.
Metal additive manufacturing is decentralizing production economics for complex bevel gear prototypes and low-volume aerospace components. Tier-one suppliers in the US Great Lakes region are adopting laser powder bed fusion for rapid iteration of custom gear geometries previously requiring 16-week tool-and-die lead times. This capability is decentralizing design authority from centralized engineering centers to plant-floor manufacturing engineers who can iterate tooth profile modifications overnight.
EPA tailpipe emissions regulations are tightening tolerance specifications for powertrain components to minimize energy losses from mesh misalignment and surface roughness. Gear producers must now document traceable measurement data to AS9100-equivalent standards even for commercial automotive supply. The precision finishing segment is responding by investing in automated in-process gaging systems that eliminate batch inspection bottlenecks.
Buyer consolidation among automotive OEMs is compressing supplier negotiation cycles and unbundling traditional tooling-and-production contracts. Tier-one purchasers in Detroit and Cleveland are separating gear design engineering from manufacturing execution, awarding each to lowest-qualified bidders. This pattern is most visible in battery electric vehicle programs where e-axle gear sets represent discrete procurement categories distinct from legacy transmission sourcing.
North America Gear Market Segmentation
Gear specification diversity across North America reflects divergent load requirements, precision tolerances, and environmental operating conditions. Each segmentation axis reveals distinct procurement patterns tied to end-use certification standards and regional manufacturing concentration.
Product Type:
Technical specifications governing tooth geometry and load distribution define competitive positioning across gear architectures.
- Helical Gears:Angled tooth engagement distributes contact across multiple teeth simultaneously, enabling higher torque transmission with reduced noise signatures. Demand concentrates in US Great Lakes automotive transmission plants where NHTSA CAFE standards mandate friction reduction through precision meshing.
- Bevel Gears:Conical tooth geometry transmits power between intersecting shafts at precise angular configurations. Aerospace procurement in Wichita and Hartford clusters drives premium positioning for AGMA Q13+ precision grades required by FAA airworthiness protocols.
- Spur Gears:Parallel shaft engagement with straight tooth profiles offers cost-efficient torque transmission for standard industrial loads.
- Worm Gears:Screw-and-wheel meshing delivers high reduction ratios in compact envelopes for conveyor and lifting equipment.
Helical gears lead on scale; bevel gears lead on momentum.
End User:
Customer concentration patterns vary sharply by certification burden and contract duration.
- Automotive:Powertrain electrification is bifurcating demand between declining internal combustion transmission volumes and emerging e-axle precision gearsets. Detroit-area OEMs now specify ground gears to AGMA Q12+ standards for battery electric drivetrains.
- Renewable Energy:Wind turbine drivetrains require planetary gear systems rated for 20+ year service intervals with minimal maintenance access. Texas and Great Lakes wind corridor expansion is climbing the fastest for large-diameter helical and planetary assemblies.
- Aerospace:Commercial aviation and defense applications demand AS9100-certified precision with full material traceability.
- Industrial Machinery:General manufacturing and material handling equipment drives mid-tier volume demand with shorter procurement cycles.
Automotive dominates absolute volume; renewable energy shows steepest expansion trajectory.
Material:
Material selection balances strength requirements against weight constraints and environmental exposure.
- Steel:Alloy and case-hardened grades remain dominant for high-load power transmission where surface fatigue resistance governs service life. Cleveland and Pittsburgh forging corridors supply automotive and industrial demand with documented metallurgical traceability.
- Plastic:Engineering polymers reduce noise and eliminate corrosion in robotics and HVAC applications where metallic strength exceeds functional requirements. Mexican maquiladora assembly plants are gaining share fastest for injection-molded precision gears.
- Aluminum:Lightweight alloys serve aerospace auxiliary systems and select automotive applications where mass reduction justifies cost premiums.
- Composite:Carbon fiber reinforced polymers enable extreme weight reduction for specialized aerospace and defense platforms.
Steel anchors volume foundation; plastic compounds are gaining share fastest.
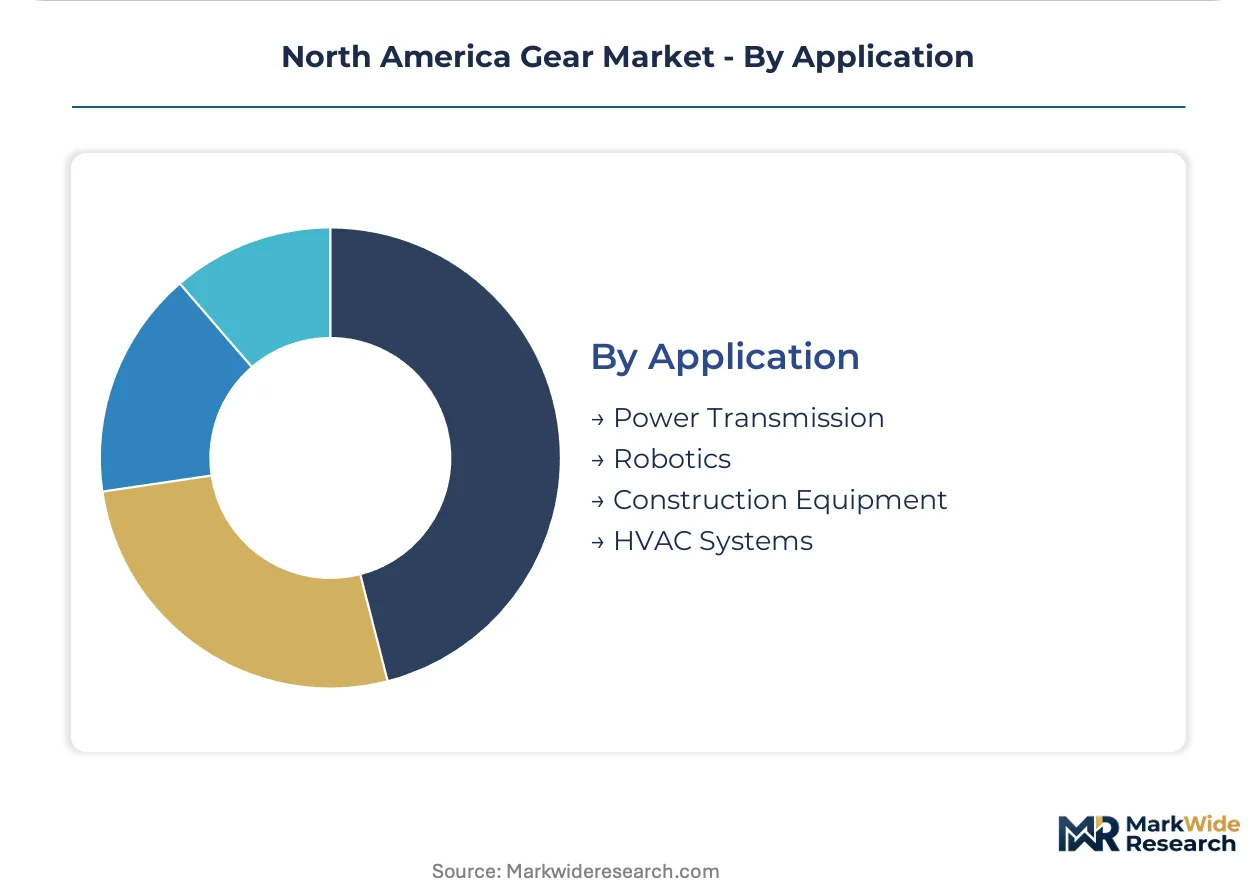
Application:
Use-case environments dictate surface finishing, sealing requirements, and maintenance accessibility specifications.
- Power Transmission:Industrial drivetrains and automotive powertrains require hardened steel gears with precision ground tooth profiles to minimize energy losses. US Great Lakes manufacturing corridors concentrate procurement for heavy-duty industrial gearboxes.
- Robotics:Collaborative and industrial automation systems demand compact, low-backlash gear systems with plastic or hybrid construction for noise-sensitive environments. Michigan and California automation clusters are expanding most quickly for harmonic and planetary precision drives.
- Construction Equipment:Off-highway machinery requires sealed, lubricated gear systems resistant to contamination and shock loading.
- HVAC Systems:Building climate control equipment drives steady demand for quiet-running helical and worm gear configurations.
Power transmission leads on scale; robotics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada and Mexico present divergent procurement patterns for precision gear systems, with Canadian aerospace demand clustering near Toronto and Montreal while Mexican manufacturing expansion concentrates automotive supply near the US border.
United States
Automotive electrification and wind energy expansion dominate gear procurement across Michigan, Ohio, and Texas. NHTSA CAFE standards compel Detroit-area OEMs to specify higher-precision ground gears for battery electric drivetrains. The Great Lakes manufacturing corridor anchors the densest concentration of tier-one gear suppliers serving both automotive and industrial machinery end-users.
Canada
Commercial aviation and defense applications drive demand for AS9100-certified precision gears in Ontario and Quebec. Transport Canada airworthiness regulations align with FAA standards, creating certification continuity for cross-border aerospace supply chains. Toronto and Montreal host specialized machining clusters serving Bombardier and international aerospace OEMs.
Mexico
Nearshoring momentum accelerates automotive gear production in Querétaro and Nuevo León to serve US-bound supply chains. Mexican manufacturing benefits from tariff-advantaged access under USMCA provisions. The Bajío region and northern border states concentrate foreign direct investment in precision machining capacity for transmission and e-axle components.
North America Gear Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North American gear value chain. The supplier base organizes into three tiers: integrated industrial conglomerates with broad power transmission portfolios, precision machining specialists serving aerospace and medical certification requirements, and regional job shops fulfilling custom-engineered industrial demand. Consolidation pressure intensifies as automotive OEMs unbundle design engineering from manufacturing execution, forcing suppliers to defend position through vertical integration or niche certification depth.
Among diversified industrial holdings, Regal Rexnord exemplifies portfolio breadth spanning multiple end-use cycles beyond automotive dependence. Gleason Corporation occupies a position within precision bevel gear manufacturing systems, serving aerospace and defense applications requiring AGMA Q13+ quality grades. Commercial Gear & Sprocket Company anchors the custom-engineered tier, representing mid-volume industrial specialists competing on application-specific design rather than scale economies.
| Leading Market Players |
|---|
| Commercial Gear & Sprocket Company |
| Regal Rexnord |
| Gleason Corporation |
| Rockwell Automation |
| Parker Hannifin Corporation |
| Boston Gear |
| Stock Drive Products |
| Caterpillar Inc. |
| Dayton Gear & Tool |
| Others |
Pricing and Supply Chain Analysis
Precision grinding specialists in the US Great Lakes corridor anchor labor-cost differentials that separate premium AGMA Q13+ aerospace pricing from standard automotive-grade tiers. Mexican maquiladora operations compress mid-tier pricing floors through tariff-advantaged labor arbitrage under USMCA provisions.
Pricing Analysis
Capacity additions in Querétaro and Nuevo León are reshaping price floors for automotive gear supply as nearshoring momentum intensifies. Three-tier pricing structure across aerospace-certified, automotive-precision, and industrial-standard levels reflects quality-grade differentiation and NHTSA CAFE compliance burdens. Cost compression in mid-tier automotive segments is intensifying because OEMs unbundle design engineering from manufacturing execution. Tier-one automotive buyers exhibit highest price sensitivity; aerospace procurement shows lowest sensitivity due to FAA airworthiness certification requirements.
Supply Chain Analysis
Dual-sourcing mandates from Detroit-area OEMs require qualified suppliers in both US Great Lakes and Mexican border states to mitigate tariff exposure. Raw material supply draws from domestic alloy steel forging corridors, Japanese precision grinding wheel manufacturers, and Canadian aerospace-grade aluminum processors. Single-source vulnerability concentrates in specialty abrasive supply from German and Japanese producers. Distribution runs through tier-one supplier hubs near Cleveland and Chicago, with direct OEM delivery for e-axle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as electrification shifts procurement toward ground-gear precision specifications that command sustained premium positioning.
For Market Incumbents: Extend certification depth into AS9100 aerospace tiers to buffer automotive cyclicality. Backward integration into alloy steel forging insulates margin pressure from nickel and molybdenum volatility. Capture e-axle design engineering contracts before OEMs fully unbundle from manufacturing execution. For New Entrants and Emerging Players: Mexican maquiladora partnerships offer tariff-advantaged entry points for automotive gear supply. Target plastic and composite gear segments serving robotics and HVAC applications where noise reduction specifications outrank metallic strength requirements. Pursue rapid prototyping capabilities via metal additive manufacturing to differentiate against legacy tool-and-die timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among custom-engineered mid-volume specialists lacking aerospace certification depth. Five-to-ten-year viability hinges on electrification-driven precision demand sustaining through internal combustion decline. Watch NHTSA fuel economy mandate tightening as inflection signal for ground-gear capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | Unlocks FAA-governed aerospace procurement with multi-year contract visibility. |
| Mexican Manufacturing Footprint | Captures USMCA tariff advantages for Detroit-bound automotive supply. |
| Additive Manufacturing Integration | Compresses prototype iteration cycles from sixteen-week tool-and-die timelines. |
| E-Axle Design Engineering Capture | Secures early-mover positioning before OEM procurement unbundling completes. |
| Precision Grinding Wheel Inventory | Mitigates single-source vulnerability from Japanese and German abrasive suppliers. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national manufacturing corridor. The analysis combines structured interviews with gear manufacturing plant managers, OEM procurement officers at Detroit-area automakers, aerospace quality engineering leads, and aftermarket distribution channel heads. Secondary validation draws from NHTSA regulatory filings, EPA emissions compliance databases, USMCA trade flow records, and SEC disclosures from diversified industrial holdings. Bottom-up production capacity modeling triangulates against top-down end-use demand aggregation.
Granularity extends to product-type precision grades, end-use certification tiers, material alloy specifications, and regional manufacturing clusters. Modeled dimensions include helical versus bevel versus planetary architectures, automotive powertrain versus renewable energy versus aerospace applications, and steel versus plastic versus composite material splits. CAGRs derive from segment-level volume trajectories normalized against macroeconomic industrial production indices. Forecast inputs incorporate NHTSA CAFE standard stringency schedules and wind energy installation pipelines across the Great Lakes and Texas corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to automotive electrification pace and alloy steel commodity volatility. Projections reflect assumptions regarding USMCA continuity, FAA certification protocol stability, and precision grinding equipment import availability. Deviation in NHTSA fuel economy mandate enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Air Suspension Systems Market