
 Outboard Electric Motors Market | 2026-2036
Outboard Electric Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Outboard Electric Motors Market Analysis
Marina supply chains is rewriting how outboard electric motors reach end users, with direct-to-fleet procurement replacing traditional retail networks for commercial operators. Torqeedo leverages its German engineering base to dominate European commercial harbor conversions. ePropulsion anchors the Asian consumer segment through cost-competitive brushless systems distributed via marine e-commerce platforms.
Outboard electric motors are self-contained propulsion units mounted on a boat transom, converting stored electrical energy into rotational mechanical force through brushless DC or AC motor architectures, typically operating at 48V to 800V depending on power class, with sealed housings rated for saltwater immersion. The technology serves commercial fishing fleets, recreational boaters, and government patrol craft seeking zero-emission waterway access. Brushless motor configurations command the largest installed base due to superior torque density and thermal efficiency, while regenerative systems represent the fastest-expanding technology segment as operators recover energy from coastal currents and deceleration events. Application demand skews heavily toward recreational use in developed marina economies, though commercial fishing electrification in regulated European waters is generating disproportionate margin pools.
The European Maritime Safety Agency enforces battery certification standards for electric propulsion systems under the EU Green Deal maritime framework, while the US Coast Guard and EPA jointly govern lithium-ion storage safety and waterway emissions compliance for domestic operators. China's MIIT issues GB standards for motor efficiency and battery swap interoperability that constrain import access for non-compliant manufacturers. Stakeholders must track how evolving voltage classifications and charging infrastructure mandates reshape product roadmaps across jurisdictions.
Market Dynamics
Direct-to-fleet procurement is compressing traditional marina retail networks as commercial operators bypass distributors for volume contracts with manufacturers. This channel compression redistributes margin pools toward OEMs while stranding independent marine dealers dependent on recreational aftermarket sales.
Growth Catalysts
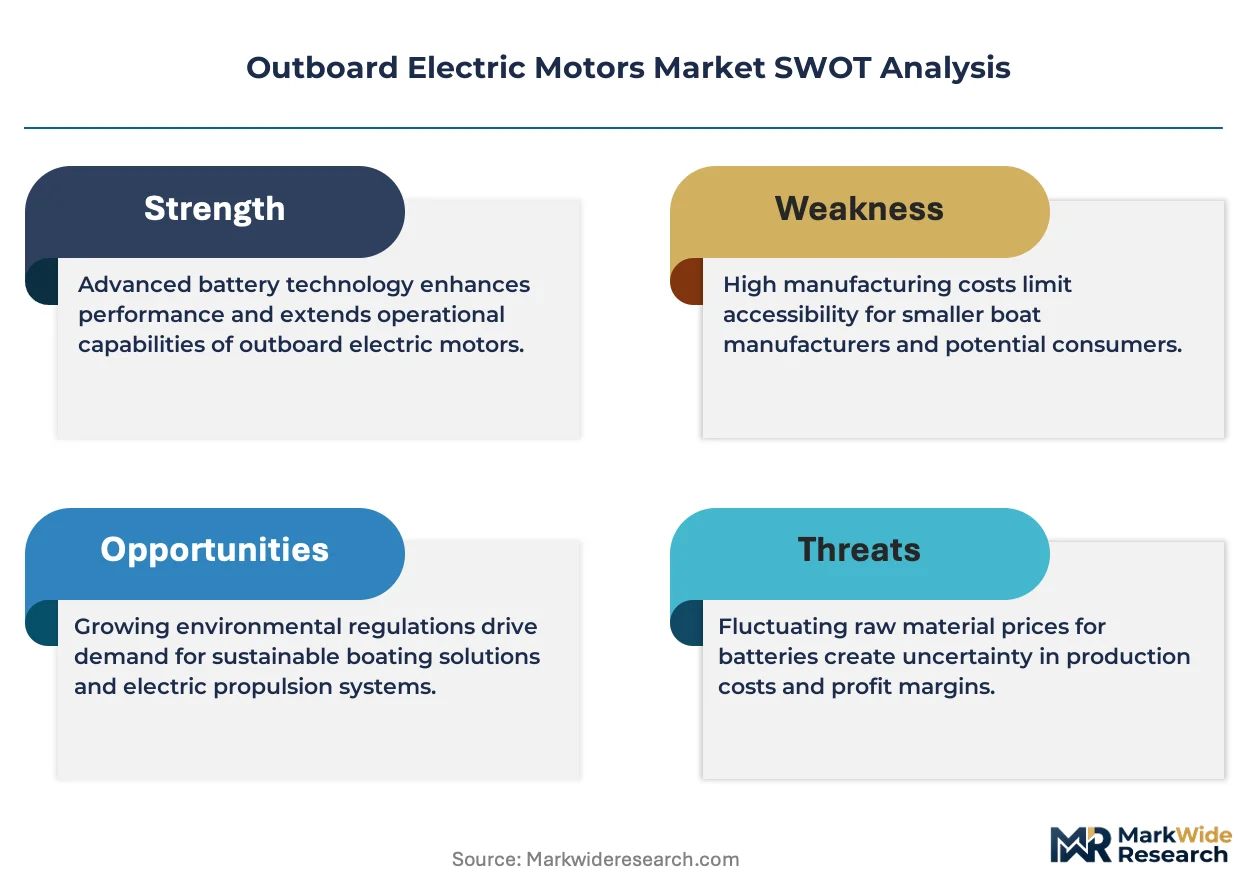
- EU F-Gas Regulation:Norway's zero-emission fjord mandates are forcing tourism operators to retire diesel outboards ahead of schedule, creating replacement demand clusters in Bergen and Tromsø.
- Brushless DC architectures:Torque density improvements in permanent magnet synchronous motors are extending operational range for commercial fishing fleets operating in regulated European inland waterways.
- Swedish marina infrastructure:Shore power retrofit programs across Stockholm archipelago networks are eliminating range anxiety for recreational boaters converting from combustion engines.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing capacity clusters in East Asia create input cost volatility for European motor assemblers without captive battery supply.
- Charging infrastructure gap:German inland waterway networks lack standardized high-voltage dockside charging, limiting commercial adoption outside major harbor clusters.
- Thermal management limitations:Sealed saltwater housings restrict continuous power output in high-ambient marine environments, constraining commercial towing applications.
Strategic Opportunities
- Battery swap interoperability:China's MIIT GB standards for modular pack exchange create white space for manufacturers designing cross-compatible systems for Asian harbor fleets.
- Regenerative coastal current harvesting:Kinetic energy recovery systems in tidal zones represent untapped application expansion for fjord tourism operators in Nordic waters.
- Marine e-commerce platforms:Direct-to-consumer channels in Southeast Asian recreational markets are displacing traditional chandlery distribution for sub-10kW consumer units.
Industry Challenges
- High-voltage certification timelines:European Maritime Safety Agency battery safety approvals average 18-24 months, delaying product launches for 800V commercial systems.
- Marine electrical technician scarcity:Qualified service capacity for brushless motor diagnostics remains concentrated in Northern European harbor cities, limiting aftermarket support in peripheral regions.
- Legacy combustion fleet integration:Transom mounting standard incompatibility between vintage hull designs and integrated electric powertrains forces costly hull modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outboard Electric Motors Market |
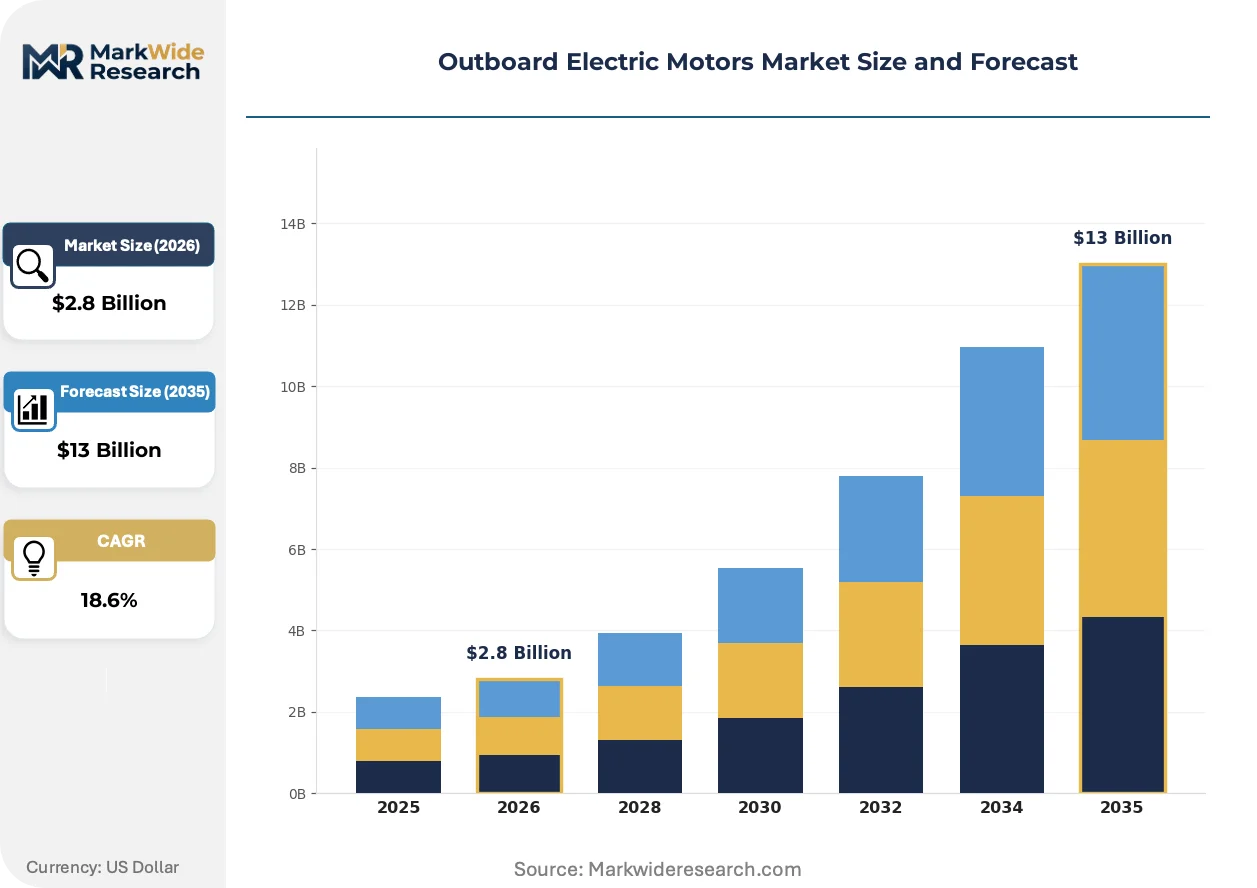
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stern Drive, Outboard, Inboard, Jet Drive Application: Fishing, Recreational, Commercial, Transportation End User: Boat Manufacturers, Individual Consumers, Rental Services, Government Technology: Brushless Motors, DC Motors, AC Motors, Regenerative Systems |
| Companies Covered | Torqeedo, ePropulsion, Minn Kota, Pure Watercraft, Yamaha Motor, Brunswick Corporation, Evoy, Aquawatt, Elco Motor Yachts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outboard Electric Motors Market Emerging Trajectories
Digital twin architectures are virtualizing motor performance optimization before physical prototyping, compressing development cycles for saltwater-rated propulsion systems. This simulation-first approach is redistributing R&D expenditure toward software competencies while reducing physical test tank dependency.
Modular battery virtualization is virtualizing energy storage as a service layer rather than fixed hardware asset. Harbor fleet operators in Norwegian coastal communities are adopting subscription-based power modules, transferring cell degradation risk to third-party asset owners. This virtualization is compressing upfront capital requirements for commercial conversions while creating recurring revenue streams for infrastructure providers.
The EU Green Deal maritime framework is mandating phased emission reductions for inland waterway craft, with the F-Gas Regulation accelerating refrigerant restrictions on auxiliary cooling systems. German commercial operators face 2027 compliance deadlines for harbor craft under 24 meters, driving retrofit demand for integrated electric propulsion in Rhine and Elbe basin fleets. Motor manufacturers are responding with 48V-400V modular platforms enabling incremental power upgrades without full system replacement.
Fleet procurement centralization is consolidating buying power among Nordic marina cooperatives, displacing individual boater transactions as the dominant demand signal. Swedish archipelago tourism associations now negotiate volume contracts covering 200+ vessels, extracting price concessions and standardized service terms unavailable to retail purchasers. This concentration is most visible in Stockholm and Gothenburg harbor networks where municipal fleet electrification targets align with cooperative procurement timelines.
Outboard Electric Motors Market Segmentation
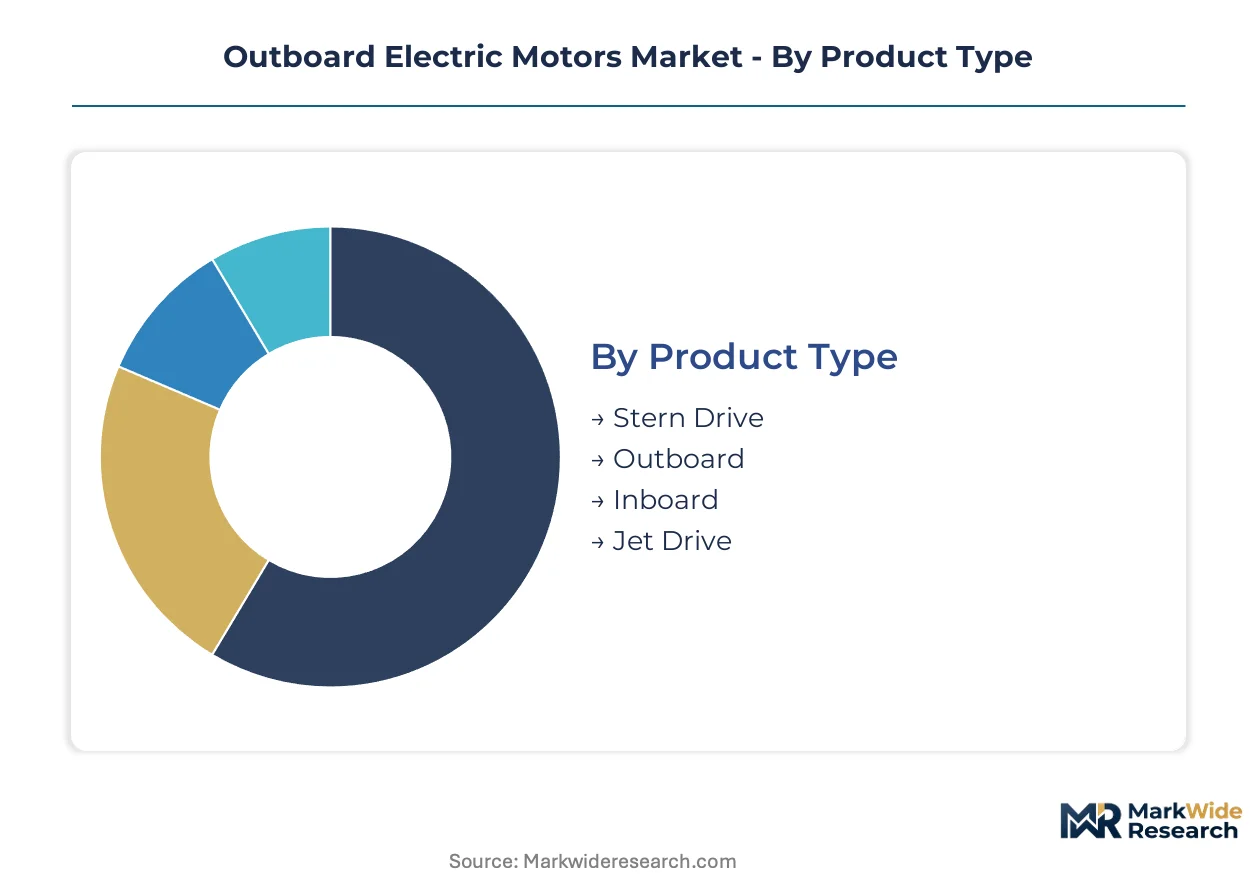
Segmentation in outboard electric motors determines service infrastructure requirements and margin capture potential. Voltage class and duty cycle variations across categories create divergent aftermarket economics for marina networks and fleet operators.
Product Type:
After-sales service intensity varies sharply by mounting configuration, with submerged drive systems demanding specialized technician deployment and corrosion monitoring protocols.
- Outboard:Self-contained transom-mounted units integrate motor, gearbox, and steering in a single saltwater-rated housing. Norwegian fjord tourism operators in Bergen and Tromsø specify these for rapid swap-out maintenance during peak season.
- Stern Drive:Inboard engine placement with through-hull drive leg combines diesel-range familiarity with electric torque delivery. German Rhine basin commercial operators favor this configuration for hull retrofit compatibility.
- Inboard:Shaft-driven propulsion suits larger harbor craft with dedicated engine rooms. Swedish archipelago ferry services specify these for continuous-duty routes.
- Jet Drive:Impeller-based thrust eliminates exposed propellers for shallow-water patrol applications. Government buyers in Nordic waters prioritize debris tolerance.
Outboard holds the largest share; momentum sits with Stern Drive as commercial fleets prioritize retrofit economics over new hull investment.
Application:
Cost tier stratification separates premium commercial systems from volume recreational units, with certification requirements driving pricing spreads.
- Recreational:Weekend boaters in developed marina economies drive unit volume through sub-10kW consumer purchases. Swedish shore power retrofit programs eliminate range barriers for archipelago sailing.
- Commercial:Harbor craft and workboats demand continuous-duty thermal management and redundant battery architectures. EU Green Deal maritime deadlines for German inland waterways accelerate replacement cycles.
- Fishing:Small-scale fleet electrification concentrates in regulated European waters where zero-emission zones restrict combustion access.
- Transportation:Passenger ferry routes in Norwegian coastal communities require high-voltage fast-charging infrastructure integration.
Recreational dominates unit volume; commercial applications generate the steepest expansion trajectory as regulatory deadlines compress procurement timelines.
End User:
Customer type determines procurement channel structure, with fleet buyers extracting volume concessions unavailable to individual purchasers.
- Boat Manufacturers:OEM integration partnerships lock in multi-year supply agreements with standardized voltage platforms. German and Swedish hull builders specify modular 48V-400V systems for production line flexibility.
- Rental Services:Marina-based fleet operators in Stockholm and Gothenburg negotiate cooperative procurement covering 200+ vessels. Subscription-based battery virtualization transfers cell degradation risk to third-party asset owners.
- Individual Consumers:Direct-to-consumer marine e-commerce channels displace traditional chandlery distribution for Asian recreational markets.
- Government:Patrol craft specifications mandate MIL-grade sealing and encrypted diagnostics for security-sensitive operations.
Rental services are concentrating procurement power fastest; boat manufacturers retain the largest installed base through OEM integration contracts.
Technology:
Motor architecture selection dictates thermal envelope, efficiency curve, and regenerative capability for specific duty cycles.
- Brushless Motors:Permanent magnet synchronous designs deliver superior torque density for commercial fishing fleets. Nordic harbor operators specify these for extended range in regulated European inland waterways.
- Regenerative Systems:Kinetic energy recovery from coastal currents and deceleration events extends operational range. Fjord tourism operators in tidal zones adopt these for marginal energy harvesting.
- DC Motors:Simpler control architectures suit cost-sensitive consumer units in Asian recreational markets.
- AC Motors:High-voltage induction designs scale to megawatt-class harbor craft requiring continuous output.
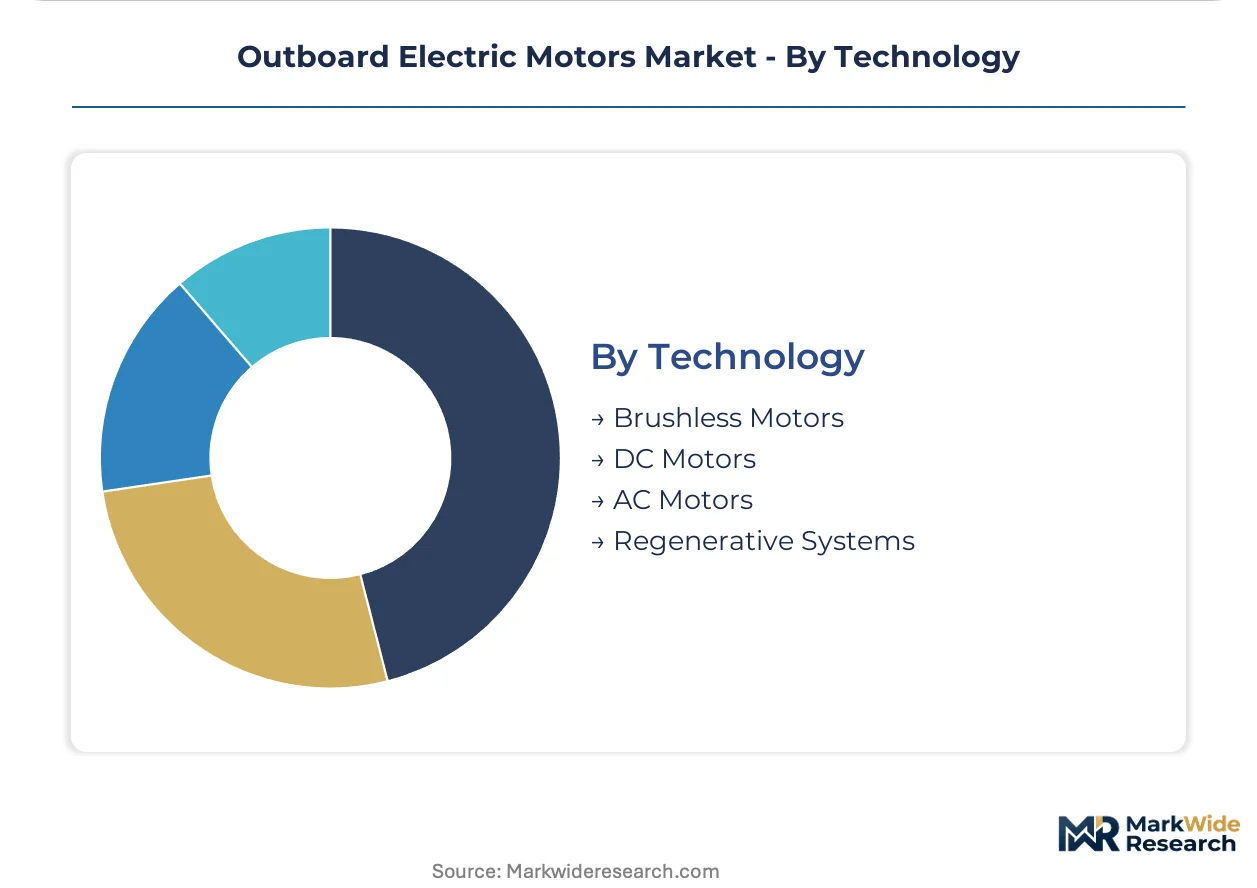
Brushless motors command the largest installed base; regenerative systems are climbing the fastest as operators prioritize range extension in current-rich waters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation and Green Deal maritime standards are accelerating fleet conversions across regulated waterways. Norway's zero-emission fjord mandates, Germany's inland waterway deadlines, and Sweden's shore power investments are reshaping procurement patterns in coastal communities.
Norway
Bergen and Tromsø tourism operators face strict zero-emission zone mandates for fjord access. The Norwegian Maritime Authority enforces compliance timelines that predate EU-wide deadlines. Coastal fleet electrification concentrates in Nordland county where harbor cooperatives negotiate volume procurement contracts.
Germany
Rhine and Elbe basin commercial operators must retire combustion harbor craft under 24 meters by 2027. The Federal Maritime and Hydrographic Agency coordinates with EU Green Deal implementation schedules. Hamburg harbor clusters are retrofitting stern drive configurations for existing hull compatibility.
Sweden
Stockholm archipelago networks are deploying shore power retrofit programs across marina infrastructure. The Swedish Transport Agency aligns harbor craft regulations with EU maritime decarbonization targets. Gothenburg municipal fleet electrification timelines synchronize with cooperative procurement covering 200-vessel tourism associations.
China
MIIT GB standards for battery swap interoperability are constraining import access for non-compliant manufacturers. The Ministry of Industry and Information Technology issues motor efficiency mandates for domestic harbor fleets. Yangtze River Delta port operators are piloting modular pack exchange systems for commercial vessels.
United States
The US Coast Guard and EPA jointly govern lithium-ion storage safety for domestic waterway operators. Federal emissions compliance requirements intersect with state-level harbor electrification incentives. Pacific Northwest marina networks are deploying high-voltage dockside charging for recreational fleet conversions.
Outboard Electric Motors Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic archetypes: German-engineered commercial harbor specialists, Asian cost-optimized consumer platforms, and diversified marine powertrain incumbents. Competitive positioning depends on voltage platform breadth, battery integration depth, and fleet procurement channel access. M&A activity targets battery virtualization capabilities and high-voltage certification expertise. Geographic expansion concentrates on Nordic harbor networks with immediate regulatory deadlines.
Among the named players, Torqeedo exemplifies the European commercial specialist archetype through its engineering-intensive positioning for harbor conversions. ePropulsion occupies a position within the Asian consumer segment through brushless system distribution via marine e-commerce channels. Minn Kota represents the established marine electronics incumbent with recreational aftermarket penetration.
| Leading Market Players |
|---|
| Torqeedo |
| ePropulsion |
| Minn Kota |
| Pure Watercraft |
| Yamaha Motor |
| Brunswick Corporation |
| Evoy |
| Aquawatt |
| Elco Motor Yachts |
| Others |
Supply Flow & Price Mechanics
Overcapacity in East Asian lithium-ion cell production is compressing input costs for European motor assemblers while simultaneously eroding pricing power for battery pack integrators serving Nordic harbor fleets. This utilization asymmetry between cathode material processing clusters and finished motor assembly sites is redistributing margins toward OEMs with captive supply agreements.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts from individual retail transactions across the Nordic marina networks. Pricing stratifies across premium certification tiers for commercial harbor craft, standard modular platforms for recreational conversions, and economy brushless units distributed through Asian marine e-commerce channels. Cost compression in the economy tier is intensifying because Chinese MIIT efficiency mandates are accelerating domestic production scale. Individual consumers in Southeast Asian recreational markets exhibit the highest price sensitivity, while Norwegian fjord tourism cooperatives prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Contract manufacturing concentration for brushless motor stator assemblies rests in German industrial clusters around Bavaria and Baden-Württemberg, with secondary capacity in Austrian precision engineering zones. Rare earth magnet supply draws from Chinese processing facilities, South Korean cathode material refineries, and Japanese separator membrane production. Single-source vulnerability in neodymium magnet procurement creates exposure to export restriction shocks. Distribution runs through direct-to-fleet procurement channels for commercial operators and marine e-commerce platforms for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery virtualization as a service layer is expanding faster than hardware unit sales, transforming capital expenditure structures into recurring operational contracts for harbor fleet operators.
For Market Incumbents: Pre-empt channel compression by securing exclusive procurement relationships with Nordic marina cooperatives before volume contract consolidation hardens. Acquire high-voltage certification expertise to compress European Maritime Safety Agency approval timelines for 800V commercial systems. Defensive patent positioning around regenerative coastal current harvesting technology blocks emerging entrant differentiation in fjord tourism applications. For New Entrants and Emerging Players: Mid-voltage modular platforms for German Rhine basin retrofit applications represent the most penetrable entry point, as 2027 EU Green Deal deadlines force accelerated replacement cycles without incumbent supply lock-in. Battery swap interoperability for Yangtze River Delta harbor fleets offers secondary white space under MIIT GB standard compliance. Direct sales force deployment targeting municipal fleet electrification coordinators bypasses established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery virtualization service providers as asset-light recurring revenue models displace integrated hardware manufacturing. Long-term viability favors acquisition targets with software-defined motor optimization capabilities and shore power infrastructure integration expertise. Monitor European Maritime Safety Agency certification backlog durations as an inflection indicator for product launch velocity advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Virtualization Service Launch | Transfers cell degradation risk to third-party asset owners while compressing customer capital requirements. |
| High-Voltage Platform Certification | European Maritime Safety Agency approvals unlock 800V commercial harbor craft procurement opportunities. |
| Direct-to-Fleet Channel Development | Bypasses stranded marina retail networks to capture margin pools from cooperative procurement consolidation. |
| Regenerative System R&D Investment | Kinetic energy recovery from Nordic tidal currents extends operational range for fjord tourism operators. |
| Marina Infrastructure Partnership | Shore power retrofit programs across Swedish archipelago networks eliminate recreational boater range anxiety. |
Methodological Framework
A spread of perspectives from harbor fleet operators, marina infrastructure planners, brushless motor engineering directors, and European regulatory affairs specialists converged on the working assumptions underlying demand projections. Primary field engagement combined structured interviews with procurement coordinators at Nordic tourism cooperatives and technical validation sessions with saltwater-rated housing manufacturers. Secondary sources encompassed EU Green Deal implementation schedules, European Maritime Safety Agency certification databases, and customs records for lithium-ion cell trade flows. Bottom-up unit demand estimates from marina network surveys were triangulated against top-down energy consumption projections for inland waterway electrification.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning voltage class architecture, duty cycle intensity, and regulatory compliance tier. Modeled categories included outboard mounting configuration, commercial versus recreational application split, and end-user procurement channel structure. CAGRs were derived from installation rate trajectories in regulated European waterways and replacement cycle compression from zero-emission mandate deadlines. Forecast inputs incorporated shore power infrastructure deployment schedules and battery swap interoperability adoption curves under Chinese MIIT standards.
Practitioners should monitor lithium-ion cell supply concentration shifts and European Maritime Safety Agency voltage classification evolutions for early signals of forecast revision triggers. Assumptions underlying projection outputs reflect documented regulatory timelines and infrastructure investment commitments subject to political and funding continuity risks. Quarterly review of certification backlog durations and harbor cooperative procurement award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Traction Motor Core Market
Electric Motor
Global Automotive Motor Market
Electric Motor
China E-Bike (Pedelec Bikes) Hub Motor Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
E-Bike Motor Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Electric Traction Motor Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
High Speed Motor Market
Electric Motor
Kayak Trolling Motor Market