
 Europe Automotive Adaptive Lighting System Market | 2026-2036
Europe Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Adaptive Lighting System Market Foresight
LED phosphor formulations are expanding their share against legacy xenon architectures, cutting thermal management costs while extending module lifespan. HELLA GmbH & Co. KGaA leverages its Swabian engineering base to dominate matrix-beam calibration systems. Valeo Group anchors production across French and Czech plants, sustaining proximity to Stellantis and Volkswagen Group assembly networks. OSRAM GmbH specializes in chip-on-board LED architectures, differentiating through lumen density per watt.
Automotive adaptive lighting systems modulate beam pattern, intensity, and direction in real time using sensor fusion, camera input, and servo-actuated projector modules, typically operating between 12V and 48V vehicle electrical architectures with response latencies under 100 milliseconds. Their primary purpose is to maximize road illumination without dazzling oncoming traffic or pedestrians. LED product types now capture the bulk of new platform allocations, while matrix technology segments command the steepest engineering premiums due to pixel-level beam control requirements. Factory-fitted installation dominates structural volume, though retrofitted modular kits are gaining traction among independent aftermarket providers serving aging premium vehicle parc.
The EU General Safety Regulation and UNECE R48 lighting standards shape homologation requirements, forcing OEMs to embed adaptive functionality as baseline equipment rather than option-box upgrades. ECE R123 governs adaptive front-lighting system performance thresholds, while CE marking mandates electromagnetic compatibility for connected lighting controllers. Stakeholders must monitor how the EU AI Act classifications apply to camera-driven predictive beam algorithms, as compliance costs could reshape supplier tiering before the next platform cycle concludes.
Market Dynamics
The EU General Safety Regulation mandates advanced lighting for pedestrian detection, forcing OEMs to embed adaptive functionality as baseline equipment rather than option-box upgrades across all member states.
Growth Catalysts
- EU General Safety Regulation:The updated framework mandates adaptive front-lighting systems for pedestrian detection, tightening compliance requirements across German and French automotive clusters.
- LED phosphor formulations:These advanced materials cut thermal management costs while extending module lifespan, accelerating displacement of legacy xenon architectures in premium platform designs.
- Stuttgart engineering corridor:Concentrated Tier-1 supplier capabilities in southwestern Germany enable rapid prototyping and calibration of matrix-beam systems for luxury OEMs.
Market Restraints
- Chip-on-board LED supply concentration:Lumen-density leadership rests with a narrow supplier base, creating vulnerability in 48V electrical architecture sourcing.
- UNECE R48 homologation complexity:Cross-border certification delays for predictive beam algorithms extend platform development cycles by multiple quarters.
- Matrix technology cost structure:Pixel-level beam control requires servo-actuated projector modules with sub-100-millisecond response latencies, inflating bill-of-materials against standard LED alternatives.
Strategic Opportunities
- Retrofitted modular kits:Independent aftermarket providers in aging premium vehicle parc across Italy and Spain present untapped demand for adaptive lighting upgrades.
- EU AI Act classification clarity:Camera-driven predictive beam algorithms face pending regulatory categorization that could reshape supplier tiering before the next platform cycle concludes.
- Czech manufacturing proximity:Production anchoring near Stellantis assembly networks enables just-in-sequence delivery for mid-luxury platform expansion.
Industry Challenges
- Matrix-beam calibration expertise:Specialized optical engineering talent scarcity in Swabian and Bavarian clusters constrains production scaling for pixel-control modules.
- Sensor fusion integration:Harmonizing camera input with servo-actuated projectors across 12V and 48V vehicle electrical architectures demands cross-functional systems engineering capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Adaptive Lighting System Market |
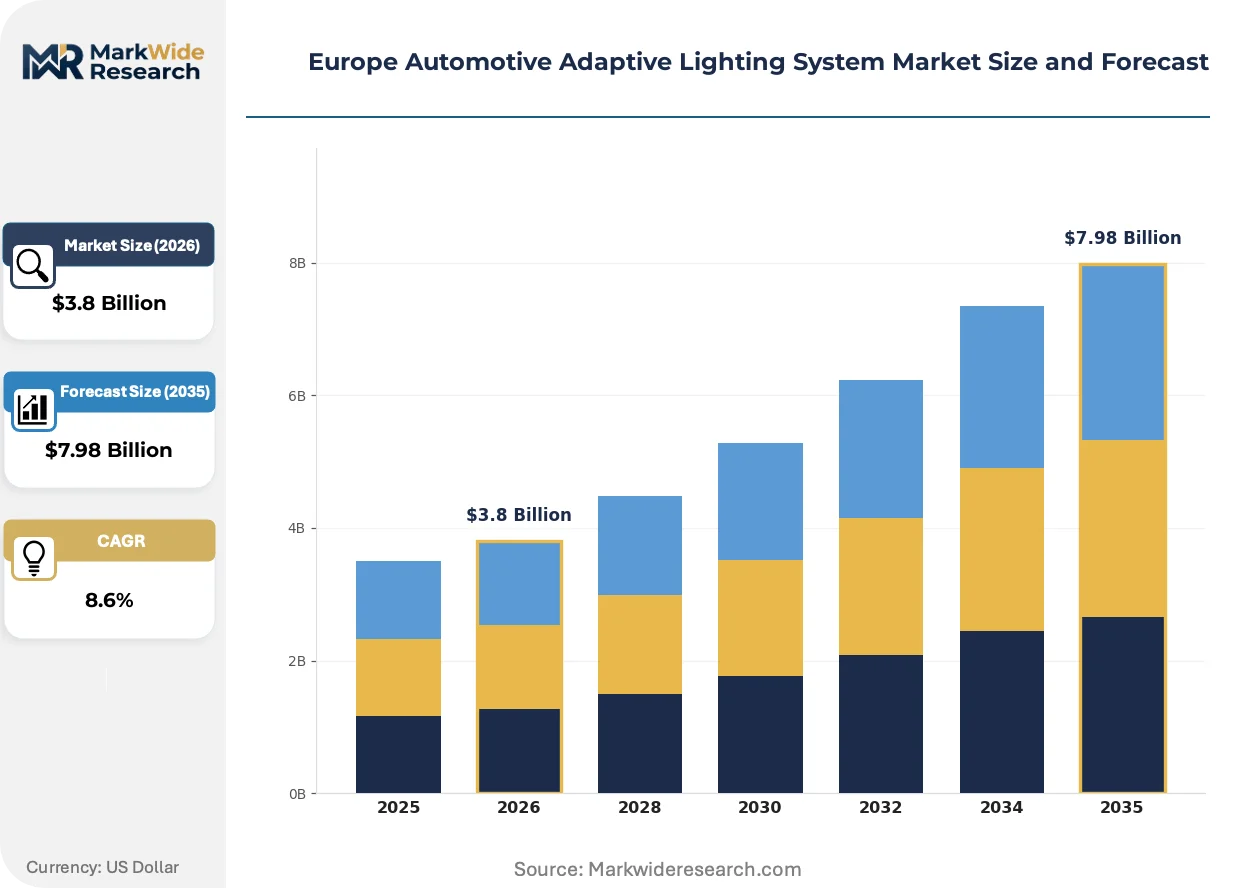
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Xenon, Halogen, OLED Technology: Matrix, AFS, Dynamic, Static End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation: Factory-Fitted, Retrofitted, Integrated, Modular |
| Companies Covered | Koito Manufacturing Co. Ltd, Hyundai Mobis, HELLA GmbH & Co. KGaA, Koninklijke Philips N.V., Stanley Electric Co. Ltd, Valeo Group, OSRAM GmbH, ZKW Group, Magneti Marelli SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Adaptive Lighting System Market Shifts & Advancements
Intelligent headlamp architectures are pivoting from hardware-centric designs toward software-defined beam control, compressing development cycles and enabling over-the-air calibration updates throughout vehicle lifetime.
Digital light processing is electrifying adaptive front-lighting systems through high-resolution matrix modules that modulate beam patterns at pixel granularity. German premium passenger vehicle OEMs are accelerating adoption across luxury platform architectures. This convergence is compressing traditional hardware refresh cycles while extending module functional lifespans through firmware updates.
EU AI Act classifications are reshaping compliance architecture for camera-driven predictive beam algorithms. The regulation's risk-tier framework forces Tier-1 suppliers to restructure algorithm documentation and validation protocols. Connected lighting controllers with CE marking mandates face heightened electromagnetic compatibility scrutiny, particularly in French and Czech production clusters.
Fleet procurement of factory-fitted adaptive systems is consolidating demand around integrated platform architectures rather than option-box selections. Independent aftermarket providers serving aging premium vehicle parc are gaining traction with retrofitted modular kits, particularly in southern European markets where vehicle retention rates exceed northern averages. This bifurcation is fragmenting supplier relationships between captive OEM channels and independent service networks.
Europe Automotive Adaptive Lighting System Market Segmentation
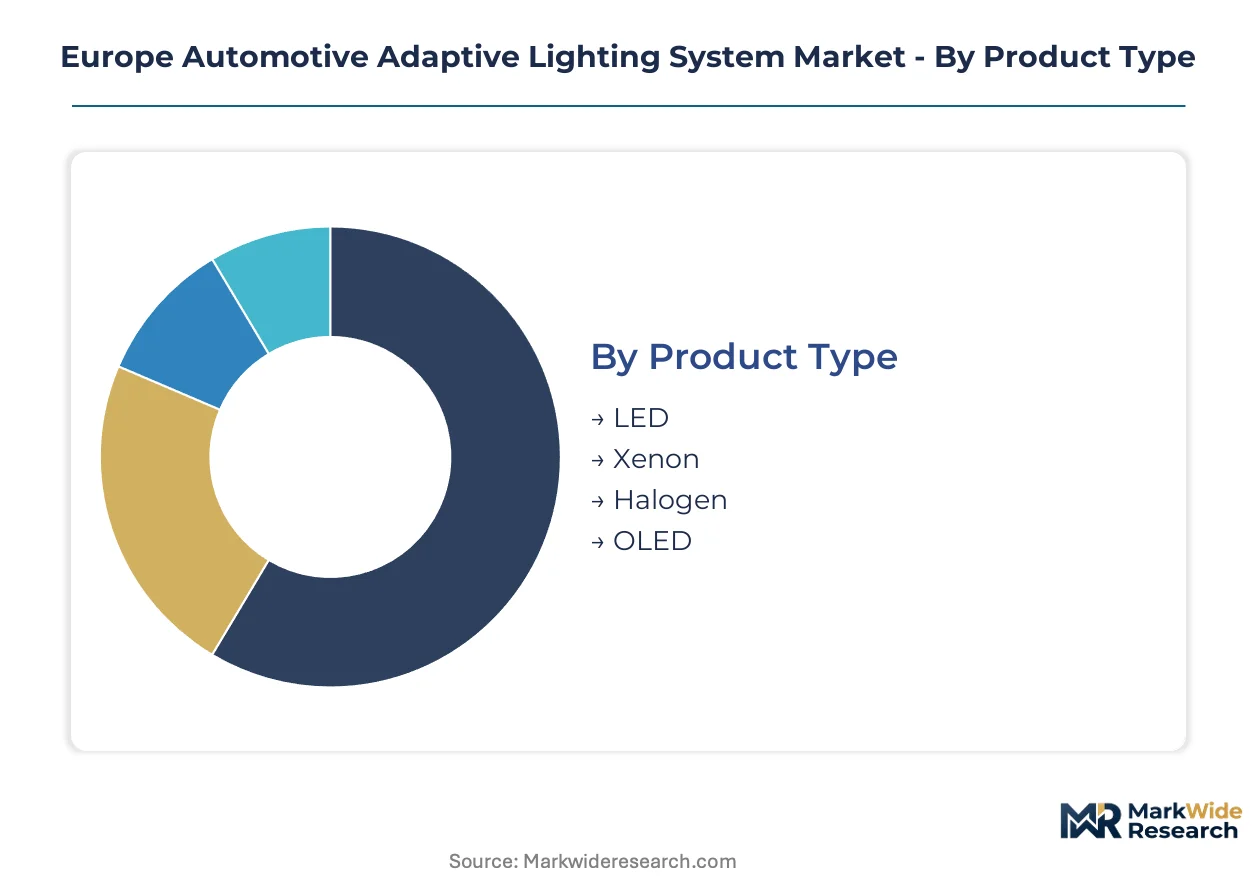
Adaptive lighting system purchasing decisions hinge on platform lifecycle timing, with OEMs embedding intelligence during initial architecture design while aftermarket channels capture aging vehicle renewal demand. Segmentation reveals how technology choices cascade through procurement tiers, electrical architecture compatibility, and regulatory homologation pathways.
Product Type:
Replacement-cycle dynamics favor solid-state architectures over gas-discharge alternatives, as extended service intervals and thermal efficiency reshape total cost of ownership calculations for fleet operators and private buyers alike.
- LED:Phosphor-converted chip architectures deliver lumen densities exceeding 150 lumens per watt while operating across 12V to 48V vehicle electrical systems without ballast complexity. German luxury OEMs in Stuttgart and Munich clusters specify LED modules as baseline equipment to satisfy EU General Safety Regulation pedestrian-detection mandates.
- Xenon:High-intensity discharge systems retain residual share in mid-luxury segments where thermal management infrastructure already exists, though module weight and warm-up latency disadvantage them against solid-state alternatives in stop-start traffic profiles.
- Halogen:Tungsten-halogen incandescence persists in economy passenger vehicles and light commercial fleets across southern European markets where upfront cost sensitivity outweighs efficiency premiums.
- OLED:Organic electroluminescent panels enable uniform surface illumination for signature lighting applications, with Italian design houses driving adoption for rear lamp assemblies where segmentation flexibility matters more than forward-beam intensity.
Volume placements concentrate in LED; the faster expansion belongs to OLED.
Technology:
Cost tier stratification separates pixel-level beam control from simpler mechanical articulation, with engineering premiums widening as camera fusion and predictive algorithms compound system complexity.
- Matrix:High-resolution LED arrays modulate individual pixel intensity to carve glare-free zones around detected vehicles and pedestrians. Czech production clusters near Stellantis assembly networks specialize in calibrating these systems for mid-luxury platform expansion.
- AFS:Adaptive front-lighting systems pivot projector modules based on steering angle and vehicle speed, delivering functional beam adaptation without the bill-of-materials inflation associated with pixel-dense architectures.
- Dynamic:Sweeping indicator sequences and cornering light functions animate beam patterns through sequential LED activation, with French OEMs specifying these for brand differentiation in C-segment crossovers.
- Static:Fixed beam patterns with manual leveling adjustment serve entry passenger vehicles and commercial van segments where regulatory minimums suffice and electrical architecture simplicity reduces warranty exposure.
Factory specifications favor AFS for cost-controlled platforms; matrix systems command the steepest engineering premiums.
End User:
Customer-type procurement patterns diverge between captive supply relationships governing new vehicle production and independent distribution channels serving parc renewal demand.
- OEMs:Volkswagen Group, Stellantis, and BMW integrate adaptive modules during platform architecture definition, locking supplier relationships through multi-year just-in-sequence contracts.
- Aftermarket Providers:Independent service networks in Italy and Spain retrofit modular kits to aging premium vehicles, exploiting higher retention rates in southern European markets.
- Vehicle Assemblers:Contract manufacturers and niche producers source adaptive systems through Tier-1 intermediaries rather than direct lighting specialist relationships.
- Tier-1 Suppliers:HELLA, Valeo, and OSRAM occupy intermediary positions, calibrating module performance to OEM specifications while managing electromagnetic compatibility certification burdens.
Procurement volume aggregates through Tier-1 channels; aftermarket providers are expanding most quickly.
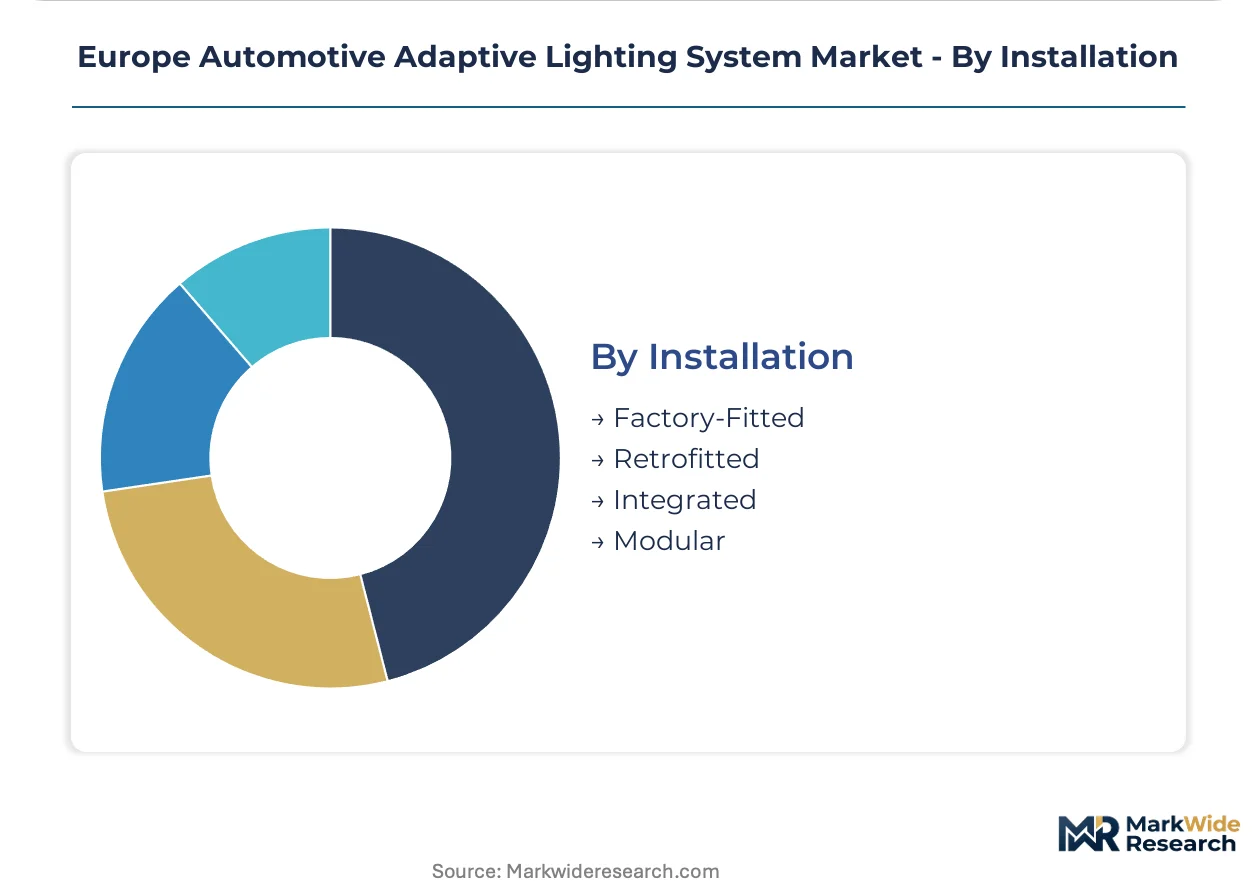
Installation:
Supply concentration in Swabian and Bavarian engineering corridors shapes how installation modalities propagate through vehicle lifecycle stages, from initial assembly to mid-life refurbishment.
- Factory-Fitted:Line-integrated installation during body-in-white sequencing ensures electromagnetic compatibility and beam calibration precision, with German OEMs mandating this pathway for EU type-approval compliance.
- Retrofitted:Post-delivery modular installation requires CAN-bus integration and headlamp housing modification, with Spanish independent garages developing specialized expertise for premium German vehicle parc.
- Integrated:Lighting controllers embedded within domain architecture share sensor fusion infrastructure with advanced driver assistance systems, reducing redundant wiring harness complexity.
- Modular:Self-contained projector and control units enable plug-and-play replacement strategies, particularly for fleet operators managing total cost of ownership across extended vehicle lifecycles.
Structural volume flows through factory-fitted pathways; modular formats are climbing the fastest in aftermarket channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive manufacturing clusters concentrate the highest adaptive lighting system demand, with Stuttgart and Munich engineering corridors driving specification intensity for premium passenger vehicle platforms.
Germany
Volkswagen Group and BMW procurement teams specify matrix-beam systems as baseline equipment across luxury architectures. KBA homologation protocols enforce EU General Safety Regulation compliance for pedestrian-detection functionality. Stuttgart's Swabian engineering base hosts concentrated Tier-1 supplier calibration facilities serving domestic OEM assembly networks.
France
Stellantis platform engineering teams integrate adaptive modules during initial C-segment crossover design phases. ANSM electromagnetic compatibility certification applies to connected lighting controllers manufactured in French plants. Valeo Group anchors production across French and Czech facilities to sustain proximity to Stellantis assembly operations.
Czech Republic
Mid-luxury platform expansion from Stellantis and Skoda Auto generates procurement volume for matrix-beam calibration systems. CE marking mandates shape controller documentation requirements for export-bound production. Ostrava and Brno industrial zones concentrate just-in-sequence delivery capabilities for lighting module integration.
Italy
Aging premium vehicle parc across northern Italian markets sustains independent aftermarket demand for retrofitted modular kits. ECE R123 performance thresholds govern adaptive front-lighting system import compliance. Turin and Milan service networks develop specialized expertise for German OEM vehicle refurbishment.
Spain
Higher vehicle retention rates in southern European markets expand addressable base for aftermarket adaptive lighting upgrades. UNECE R48 cross-border certification complexity affects predictive beam algorithm platform development timelines. Barcelona and Madrid independent garages capture share in premium vehicle parc renewal demand.
Europe Automotive Adaptive Lighting System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with factory-fitted pathways consolidating around captive OEM relationships while aftermarket channels fragment across independent service networks. Three archetypes dominate: integrated Tier-1 suppliers with calibration expertise, component specialists focused on LED chip architectures, and regional fabricators serving parc renewal demand. Competitive positioning hardens through strategic partnerships for sensor fusion integration and portfolio diversification into software-defined beam control.
Among Germany-based engineering specialists, HELLA GmbH & Co. KGaA and OSRAM GmbH exemplify the integrated Tier-1 archetype, occupying positions that bridge optical calibration and solid-state illumination technology. Valeo Group represents the cross-border production specialist, anchoring capabilities across multiple European manufacturing clusters to align with OEM assembly geography.
| Leading Market Players |
|---|
| Koito Manufacturing Co. Ltd |
| Hyundai Mobis |
| HELLA GmbH & Co. KGaA |
| Koninklijke Philips N.V. |
| Stanley Electric Co. Ltd |
| Valeo Group |
| OSRAM GmbH |
| ZKW Group |
| Magneti Marelli SpA |
| Others |
Supply & Pricing Matrix
LED phosphor formulation advances are compressing thermal management costs while concentrating procurement leverage among German and Czech production clusters. This dual effect simultaneously reshapes cost economics for matrix-beam modules and reinforces supplier tiering around optical calibration expertise.
Pricing Analysis
Volume aggregates through factory-fitted OEM channels while margins concentrate in matrix-beam calibration tiers. Three-tier pricing structure across premium, standard, and economy levels separates pixel-control architectures from mechanical articulation systems. Cost compression in mid-luxury segments is intensifying because Stellantis and Skoda Auto procurement teams negotiate just-in-sequence contracts. Fleet operators exhibit highest price sensitivity; German luxury OEMs show lowest, embedding adaptive functionality as baseline equipment under EU General Safety Regulation mandates.
Supply Chain Analysis
Single-source vulnerability sits with chip-on-board LED architectures sourced from concentrated German and Austrian supplier bases. Production draws from phosphor substrates, servo-actuated projector housings, and camera fusion processors. Tariff exposure compounds risk for controllers manufactured in French plants and exported to Czech assembly networks. Distribution runs through captive OEM channels for new vehicle fitment, while independent aftermarket providers fragment final-mile delivery across Italian and Spanish service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
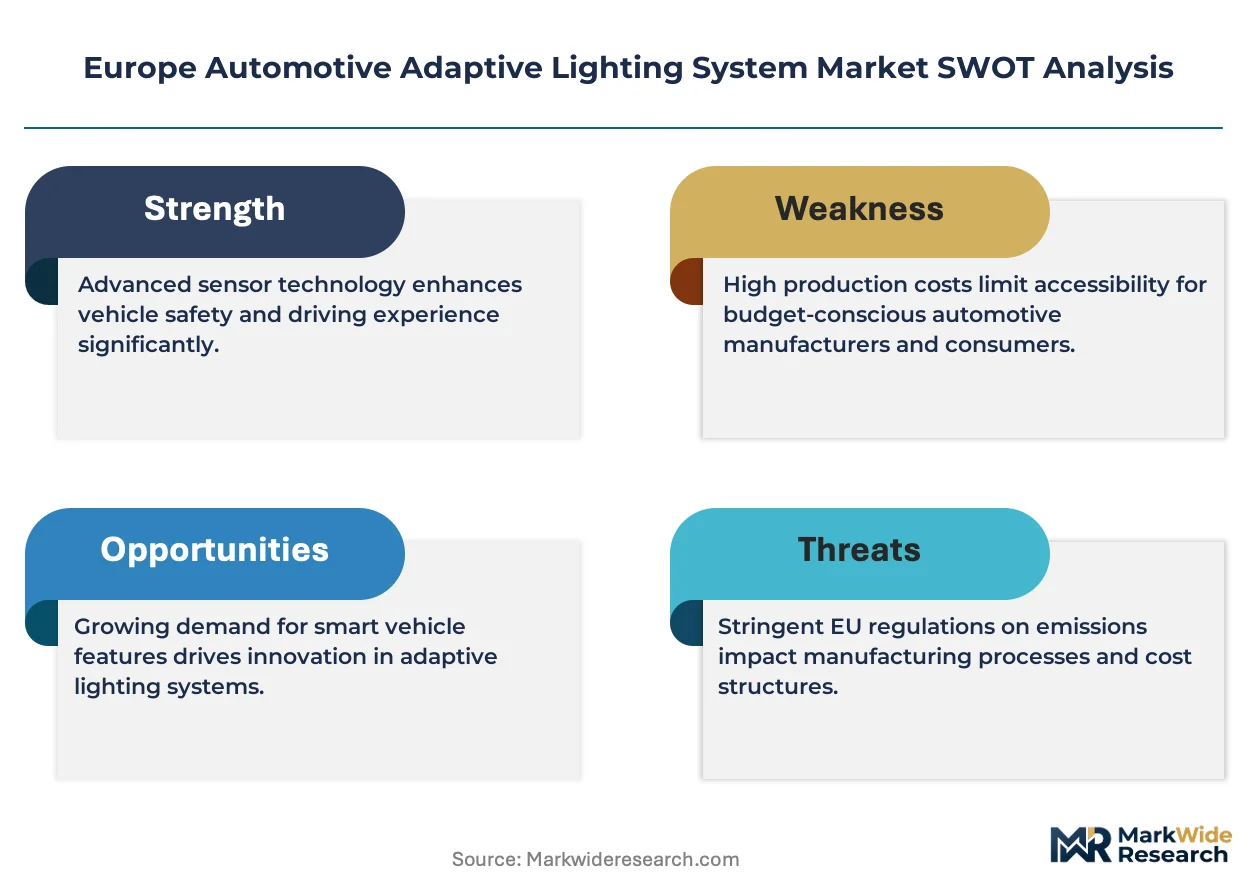
The EU General Safety Regulation erects a compliance moat that rewards incumbents with validated pedestrian-detection algorithms while screening out undercapitalized entrants lacking homologation infrastructure.
For Market Incumbents: Cement calibration expertise advantages by acquiring specialized optical engineering talent in Swabian clusters before matrix-beam production scaling constraints tighten. Expand backward integration into chip-on-board LED sourcing to neutralize supply concentration vulnerability. Prioritize firmware update architectures that extend module functional lifespans against substitute technologies. For New Entrants and Emerging Players: Enter via retrofitted modular kits for aging premium vehicle parc in Italian and Spanish markets where vehicle retention rates exceed northern European averages. Target independent aftermarket channels with CAN-bus integration expertise for German OEM vehicle refurbishment. Lead with specialized garage partnerships rather than direct OEM supply relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified Tier-1 suppliers seeking optical calibration capabilities. Long-term viability hinges on software-defined beam control architectures that compress hardware refresh cycles. Watch EU AI Act classification clarity for camera-driven predictive algorithms as the inflection signal that reshapes supplier tiering.| Strategic Initiative | Industry Significance |
|---|---|
| Matrix-Beam Calibration Facility Expansion | Czech production clusters near Stellantis networks capture mid-luxury platform growth. |
| Software-Defined Beam Control Investment | Firmware update architectures extend module lifespans beyond traditional hardware cycles. |
| Backward Integration into LED Phosphor Supply | Captive sourcing neutralizes chip-on-board concentration vulnerability in 48V architectures. |
| Aftermarket Garage Network Partnership | Italian and Spanish independent service channels access aging premium vehicle parc renewal demand. |
| EU AI Act Compliance Documentation | Structured algorithm validation protocols preempt regulatory reclassification costs for predictive beam systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary fieldwork encompassed Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. KBA homologation databases, ANSM electromagnetic compatibility certifications, and vehicle production registries supplied validation benchmarks. Bottom-up module shipment estimates triangulated against top-down OEM platform allocation data.
Granularity extended to vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions across the analysis window. CAGRs derived from segment-level growth rate reconciliation with aggregate market trajectory. Forecast inputs incorporated EU General Safety Regulation compliance timelines and matrix-beam adoption curves by platform lifecycle stage.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act reclassification scenarios or chip-on-board supply disruption events. Assumptions reflect documented regulatory trajectories and supplier capacity expansion plans. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Automotive Pressure Switch Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market