
 Automotive Magnesium Alloy Market | 2026-2036
Automotive Magnesium Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Magnesium Alloy Market Outlook
EPA tailpipe emissions rules are shifting the cost-of-entry calculus for structural materials in light-duty vehicles. Magnesium Elektron leverages captive smelting capacity to anchor supply security for North American automakers. Meridian Lightweight Technologies specializes in high-pressure die casting of magnesium closure panels, sustaining its position in premium vehicle programs.
Automotive magnesium alloys are lightweight metallic materials composed primarily of magnesium with aluminum, zinc, manganese, or rare earth additions, typically offering density around 1.74 g/cm³ and specific strength advantages over aluminum counterparts. These alloys serve the primary purpose of reducing vehicle curb weight to improve fuel efficiency and extend electric vehicle range. Cast alloys dominate current volume given their suitability for complex geometries in transmission housings and engine components, while sheet alloys represent the fastest-growing category as warm-forming breakthroughs enable body panel applications previously restricted to aluminum or steel. Die casting technology leads process selection for structural automotive parts, though injection molding gains traction for thinner-walled components where material yield demands precision.
NHTSA, EPA, and California Air Resources Board shape material substitution timelines through progressively stringent fleet efficiency mandates that penalize weight-heavy vehicle designs. REACH compliance in European markets restricts certain alloying additives, redirecting R&D toward cerium and lanthanum-based formulations that maintain performance without restricted substances. Stakeholders must monitor evolving crashworthiness test protocols that determine whether magnesium-intensive structures achieve insurance industry acceptance alongside regulatory certification.
Market Dynamics
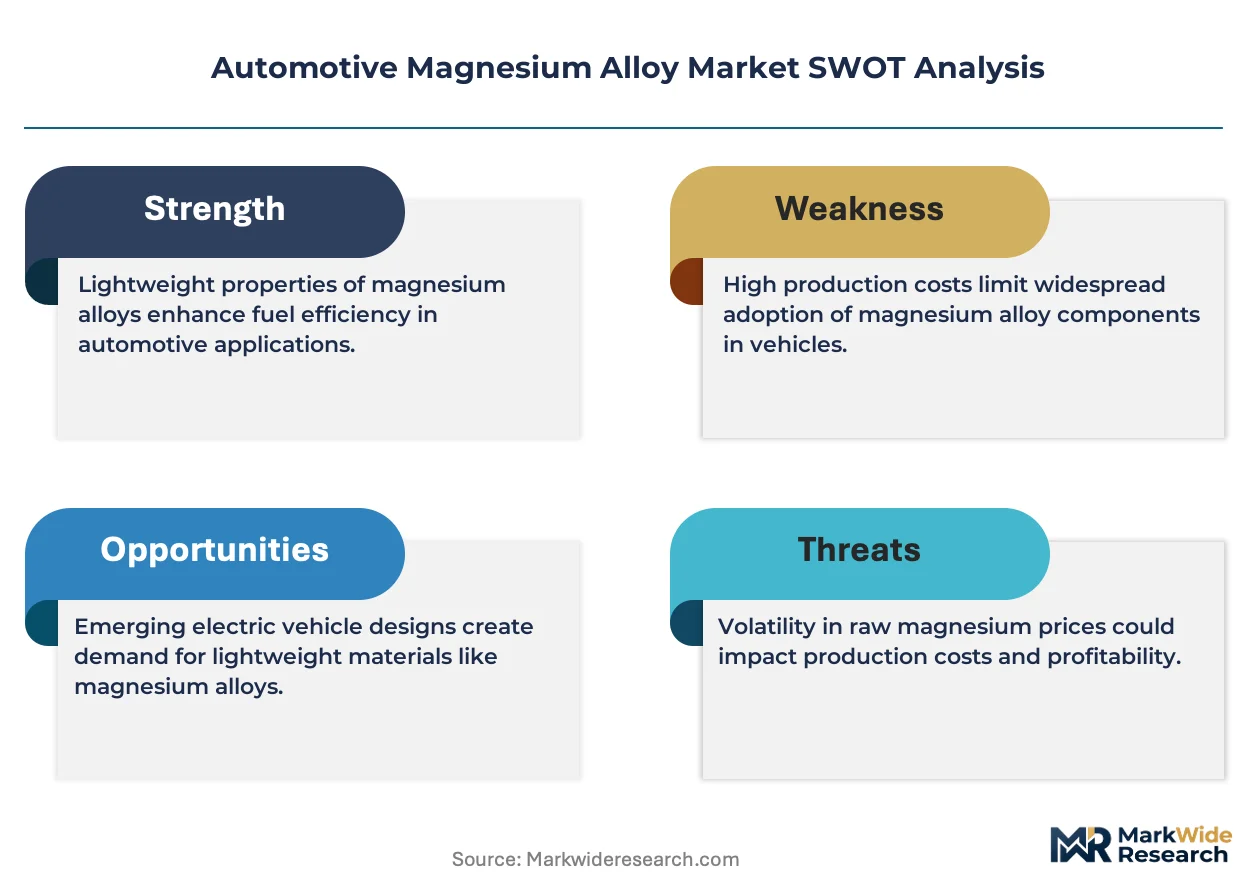
Electric vehicle platform architectures are forcing automakers to reconsider every kilogram of curb weight, with magnesium alloys emerging as the primary substitution pathway for aluminum-intensive body structures previously considered optimal.
Growth Catalysts
- EPA Fleet Efficiency Mandates:Corporate average fuel economy standards impose escalating penalties on overweight vehicle designs, accelerating magnesium adoption in closure panels and structural reinforcements.
- High-Pressure Die Casting:Process innovations enable thinner-walled, complex geometries for transmission housings and battery enclosures that aluminum cannot replicate at comparable mass.
- Germany:BMW, Mercedes-Benz, and Volkswagen operate dedicated magnesium casting programs that normalize material specifications across premium vehicle architectures.
Market Restraints
- Primary Magnesium Supply Concentration:Chinese smelters control approximately 85% of global primary magnesium output, creating geopolitical exposure for North American and European automakers.
- Corrosion Susceptibility:Galvanic corrosion between magnesium and dissimilar metals requires isolation engineering that adds assembly complexity and cost.
- REACH Compliance:European chemical regulations restrict certain yttrium and neodymium alloying additives, forcing reformulation cycles that delay product qualification.
Strategic Opportunities
- India:Domestic electric vehicle production targets under the PLI scheme create first-mover advantage for magnesium sheet suppliers establishing warm-forming partnerships with local OEMs.
- Thermal Management Applications:Battery pack housings and power electronics enclosures represent underpenetrated demand as thermal conductivity requirements intensify.
- EU Green Deal:Carbon border adjustment mechanisms penalize aluminum's energy-intensive production, improving magnesium's lifecycle emissions competitiveness.
Industry Challenges
- Crashworthiness Certification:Insurance industry acceptance of magnesium-intensive structures lags regulatory approval, requiring additional testing protocols that extend program timelines.
- Warm-Forming Equipment Scarcity:Limited installed base of precision-controlled forming presses constrains sheet alloy capacity expansion.
- Alloying Metallurgy Talent:Specialized expertise in rare earth magnesium formulations remains concentrated within a handful of research institutions and incumbent suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Magnesium Alloy Market |
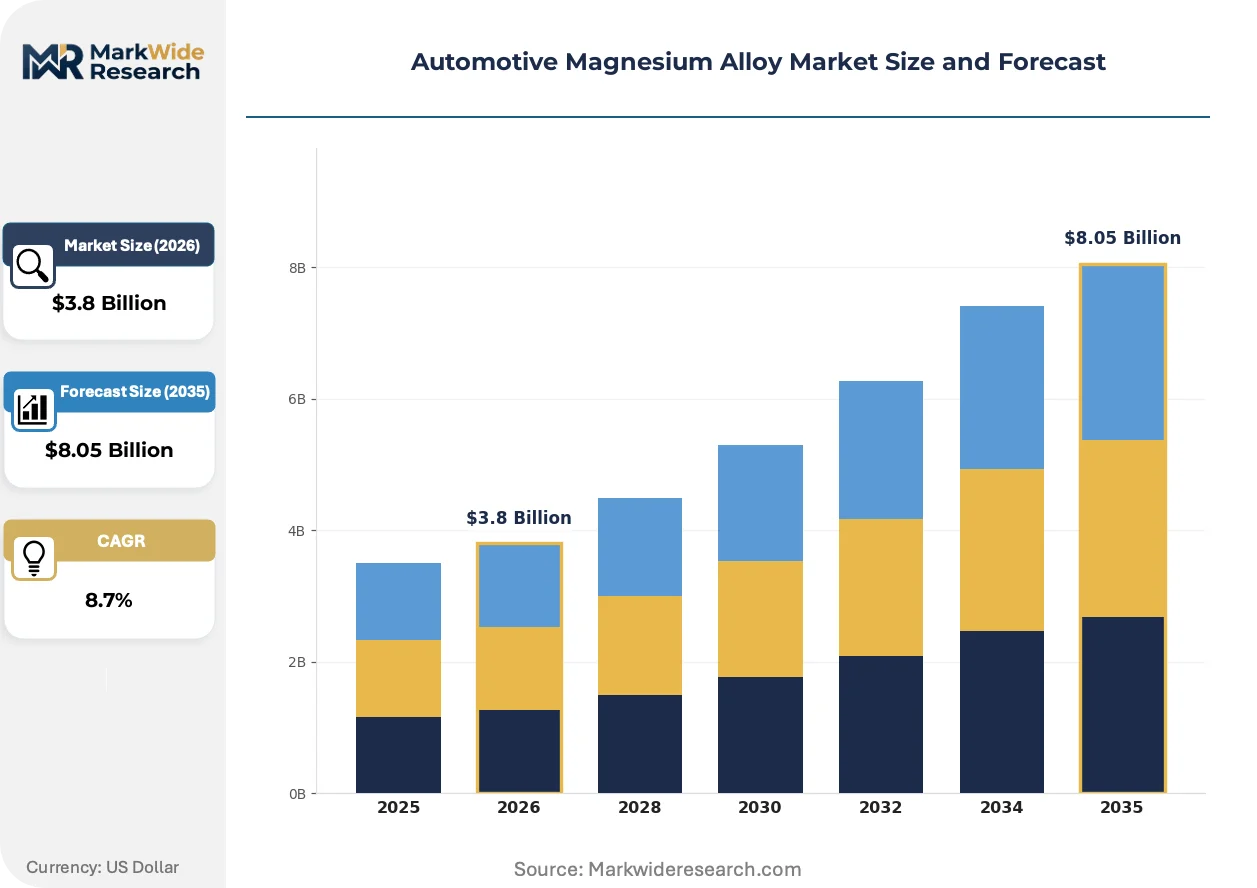
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Alloys, Cast Alloys, Sheet Alloys, Forged Alloys Application: Body Panels, Engine Components, Transmission Housings, Chassis Parts End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Die Casting, Heat Treatment, CNC Machining |
| Companies Covered | Magnesium Elektron, Meridian Lightweight Technologies, Magna International Inc., GF Casting Solutions, Dynacast International, AMG Advanced Metallurgical Group, Smiths Advanced Metals, Shanghai Regal Magnesium Limited, US Magnesium LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Magnesium Alloy Market Strategic Shifts
Warm-forming breakthroughs for magnesium sheet alloys are unlocking body panel applications previously restricted to aluminum or steel, while regulatory pressure on lifecycle emissions intensifies material selection scrutiny.
Thixomolding injection molding technology is expanding into thinner-walled automotive components where material yield demands precision beyond conventional die casting capabilities. Tier 1 suppliers in Japan and Germany are adopting thixomolding for dashboard carriers and center console structures. The process is expanding into laptop-scale production volumes for electric vehicle interior modules, compressing cycle times relative to traditional casting methods.
REACH chemical regulations in Europe are redirecting magnesium alloy R&D toward cerium and lanthanum-based formulations that maintain creep resistance without restricted substances. ECHA substance evaluations have accelerated substitution timelines for yttrium-containing grades. German automakers are responding with accelerated qualification programs for rare earth alternatives in powertrain applications.
Automaker engineering teams are consolidating material specifications around platform-level magnesium content targets rather than component-by-component substitution decisions. This behavioral shift compresses supplier negotiation cycles and favors integrated casting-to-assembly partnerships over transactional procurement. The pattern is most visible in Volkswagen's MEB electric platform and Hyundai's E-GMP architecture.
Automotive Magnesium Alloy Market Segmentation
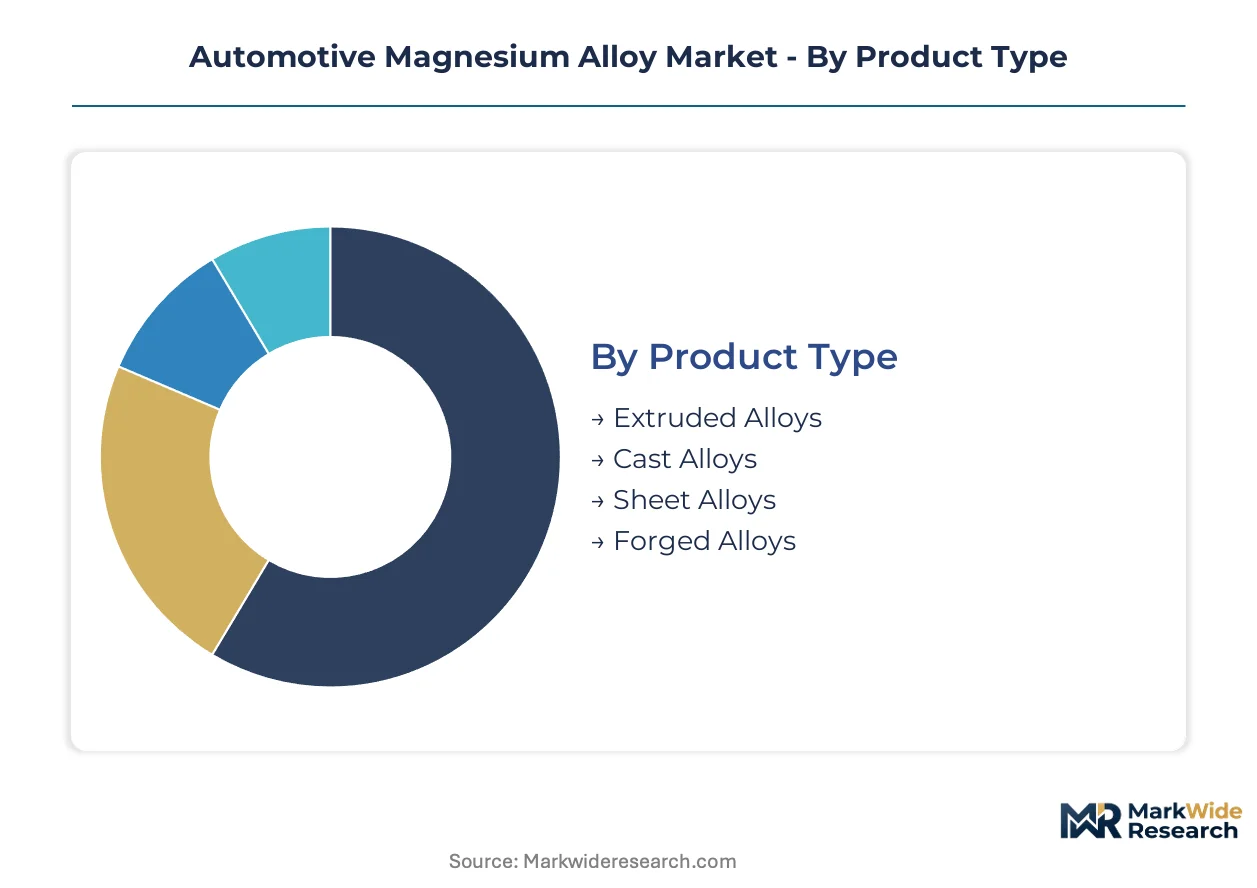
Supply concentration across primary magnesium smelting cascades into uneven segment development, with die casting and sheet forming technologies commanding disproportionate capital allocation. Material substitution decisions by Volkswagen, BMW, and Mercedes-Benz propagate through tiered supplier networks, amplifying volume concentration in specific alloy categories and process technologies.
Product Type:
Supply concentration in Chinese primary magnesium production favors segments with established toll-casting relationships and captive alloy development programs.
- Cast Alloys:Aluminum-silicon-manganese compositions dominate transmission housings and engine blocks where fluidity and hot tear resistance matter. Demand concentrates in Germany, where BMW and Mercedes-Benz maintain dedicated high-pressure die casting foundries for powertrain architectures.
- Sheet Alloys:Warm-formable AZ31 and ZEK100 grades enable body panel substitution previously restricted to aluminum, with specific strength advantages in closure applications. Germany's Volkswagen Group accelerates qualification timelines for hood and door inner panels across MEB electric platforms.
- Extruded Alloys:AZ80 and ZK60 profiles serve structural reinforcements and crash management systems.
- Forged Alloys:High-strength ZK-series compositions address suspension knuckles and steering components where fatigue resistance is non-negotiable.
Today's leader: Cast Alloys. Tomorrow's challenger: Sheet Alloys.
Application:
Cost tier differentiation separates premium vehicle architectures with magnesium-intensive designs from mass-market programs constrained by piece-price targets.
- Transmission Housings:AZ91D and AM60B alloys deliver the complex geometries and pressure-tight integrity that automatic transmission cases demand. Volkswagen's consolidated specifications across MQB and MEB platforms normalize magnesium adoption for dual-clutch and electric drive unit housings.
- Body Panels:Warm-formed sheet achieves 30-40% mass reduction versus aluminum equivalents in hood, decklid, and door applications. BMW's 7-Series and Mercedes-Benz S-Class programs validate insurance industry acceptance for magnesium closure structures.
- Engine Components:Oil pans, valve covers, and front covers leverage die casting economies for four-cylinder and V-engine architectures.
- Chassis Parts:Crossmembers and subframe nodes require specialized corrosion isolation engineering against galvanic coupling with steel suspension elements.
Volume concentrates in transmission housings. Margin expansion potential sits with body panels.
End User:
Customer type stratification reflects divergent technical capabilities, with integrated OEM programs displacing transactional procurement relationships.
- OEMs:BMW, Mercedes-Benz, and Volkswagen operate captive engineering teams specifying platform-level magnesium content targets rather than component-by-component substitution. This behavioral shift compresses supplier qualification cycles and favors long-term casting-to-assembly partnerships.
- Tier-1 Suppliers:Meridian Lightweight Technologies and Magna specialize in high-pressure die casting of closure panels, sustaining positions through dedicated magnesium foundry investments aligned to premium vehicle programs.
- Vehicle Assemblers:Contract manufacturers and emerging EV specialists source magnesium components through Tier-1 intermediaries lacking in-house metallurgy expertise.
- Aftermarket Providers:Limited penetration restricted by liability concerns and absence of standardized repair protocols for magnesium-intensive structures.
OEMs consolidate specification authority. Tier-1 suppliers capture process value-add.
Technology:
Maturity gradients separate established high-pressure die casting from emerging thixomolding and precision forming technologies requiring specialized equipment investment.
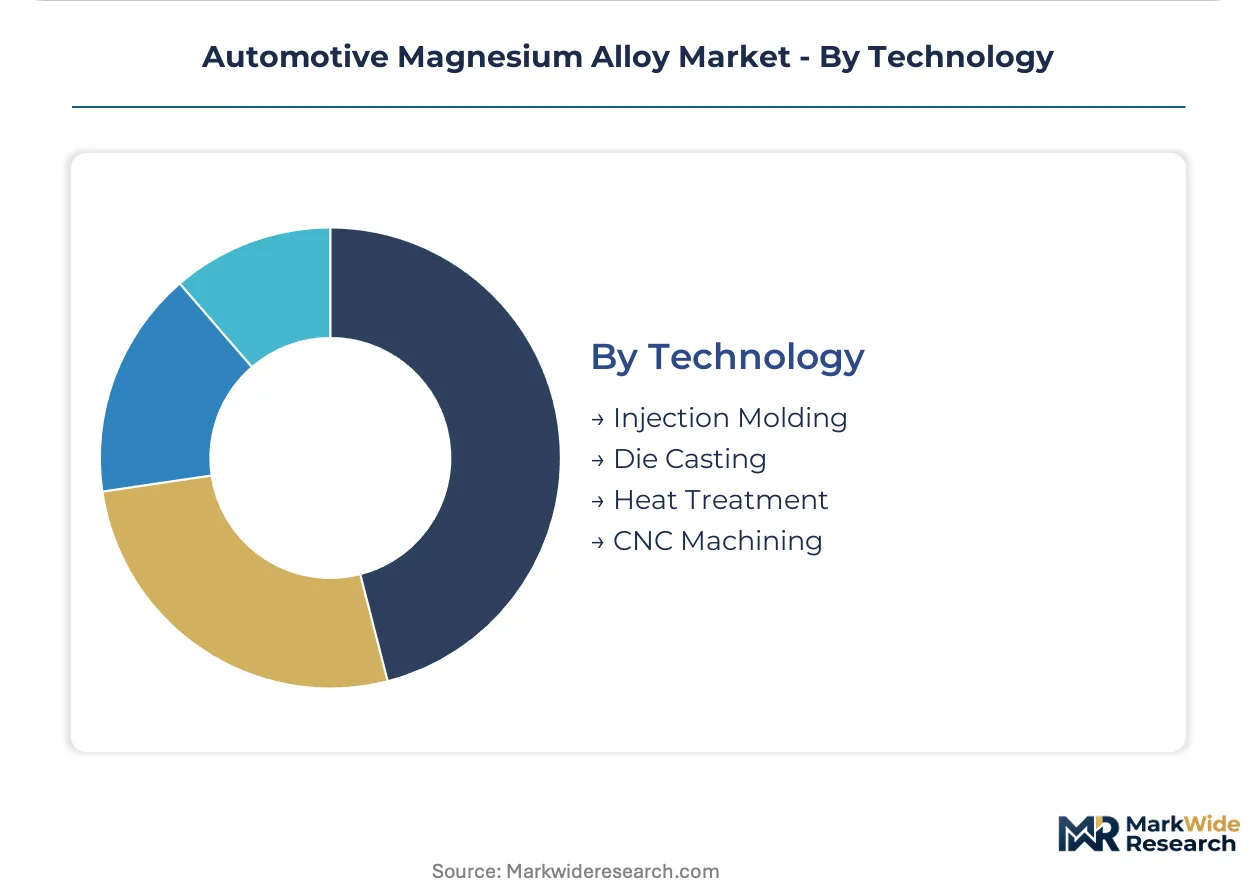
- Die Casting:High-pressure cold chamber processes dominate structural automotive parts, with 4,000-4,500 ton machines enabling battery enclosure and transmission housing geometries exceeding aluminum capability at comparable mass. Germany's automotive supply base maintains the densest installed capacity.
- Injection Molding:Thixomolding technology expands into thinner-walled dashboard carriers and center console structures where material yield demands precision beyond conventional casting. Japanese Tier-1 suppliers lead adoption for electric vehicle interior modules.
- Heat Treatment:T4 and T6 tempering protocols optimize strength-ductility balance for forged and cast components in safety-critical applications.
- CNC Machining:Secondary finishing operations address tight tolerances for mating surfaces and threaded features in powertrain assemblies.
Die casting anchors current volume. Injection molding offers the steepest expansion trajectory for interior applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgy talent clusters in German research universities and Chinese smelter towns anchor regional competitive advantages. Workforce density in rare earth alloy formulation concentrates near Aachen and Baotou. Foundry engineering expertise distributes across Nagoya, Detroit, and Stuttgart industrial corridors.
Germany
BMW, Mercedes-Benz, and Volkswagen operate captive magnesium casting foundries for premium electric platforms. REACH compliance through ECHA redirects R&D toward cerium-based formulations without restricted yttrium additives. The Aachen-Düsseldorf corridor hosts concentrated die-casting engineering talent serving powertrain housing programs.
China
Baotou and Shaanxi province smelters control primary magnesium output for global automotive supply chains. MIIT industrial policy prioritizes domestic EV lightweighting through magnesium-intensive battery enclosures. Yangtze River Delta foundries supply transmission housings to European and North American Tier-1 networks.
United States
EPA tailpipe emissions rules and NHTSA CAFE standards penalize overweight vehicle designs, accelerating magnesium adoption in closure panels. US Magnesium LLC maintains captive smelting capacity in Utah for North American automaker supply security. Detroit-area engineering clusters specialize in high-pressure die casting for transmission and electric drive unit housings.
Japan
Toyota and Nissan engineering teams specify magnesium content targets for platform-level weight reduction in hybrid architectures. METI technology roadmaps prioritize thixomolding process development for interior module applications. Nagoya-based Tier-1 suppliers lead adoption of injection-molded dashboard carriers and center console structures.
India
Domestic electric vehicle production targets under the PLI scheme create demand for magnesium sheet forming partnerships with local OEMs. BIS standards development for automotive magnesium alloys accelerates qualification timelines. Tamil Nadu and Maharashtra automotive clusters attract warm-forming equipment investments for body panel applications.
Automotive Magnesium Alloy Market Competitive Environment
The competitive structure tilts toward integrated material suppliers with captive smelting and alloy development capabilities. Three archetypes dominate: primary magnesium producers with downstream casting integration, Tier-1 automotive suppliers with dedicated magnesium foundry investments, and specialized die-casting engineering houses. Dominant competitive moves include backward integration into primary magnesium supply and strategic partnerships for warm-forming technology access.
Among integrated primary producers, Magnesium Elektron and US Magnesium LLC exemplify the smelter-to-alloy supply chain archetype, anchoring material security for regional automaker networks. Within the Tier-1 supplier tier, Meridian Lightweight Technologies occupies a position representing high-pressure die casting specialization for closure panel programs, while Magna International Inc. sits within the diversified automotive supplier archetype with magnesium capabilities spanning multiple vehicle systems.
| Leading Market Players |
|---|
| Magnesium Elektron |
| Meridian Lightweight Technologies |
| Magna International Inc. |
| GF Casting Solutions |
| Dynacast International |
| AMG Advanced Metallurgical Group |
| Smiths Advanced Metals |
| Shanghai Regal Magnesium Limited |
| US Magnesium LLC |
| Others |
Value Chain & Pricing Dynamics
Primary magnesium ingot costs cascade through three pricing tiers as Chinese smelter concentration in Baotou and Shaanxi province feeds toll-casting relationships, contract offtake agreements, and spot market purchases by North American and European automakers seeking supply security.
Pricing Analysis
Bundled alloy-development services with captive smelting command premium positioning, while unbundled toll-casting from independent foundries competes on unit economics. Price differentiation rests on rare earth content grade and REACH-compliant certification tier, with cerium-based formulations trading at a premium to yttrium-restricted alternatives. Cost compression in standard-grade AZ91D is intensifying as Chinese capacity expansion outpaces German and North American smelter restarts. Mass-market vehicle assemblers exhibit acute price sensitivity, whereas BMW and Mercedes-Benz engineering teams prioritize performance consistency over piece-price optimization.
Supply Chain Analysis
Dual-sourcing requirements mandated by Volkswagen and BMW procurement teams force Tier-1 suppliers to qualify secondary magnesium streams from US Magnesium LLC alongside Chinese primary sources. Geographic supply concentration centers on China, the United States, and Germany, with raw material dependencies spanning dolomite ore, ferrosilicon reducing agents, and rare earth cerium/lanthanum additives. Single-source vulnerability around Chinese smelter concentration exposes automakers to export quota disruptions and maritime logistics chokepoints through the Panama Canal. Distribution runs through captive foundry networks for OEM direct supply, with merchant alloy distributors serving smaller Tier-2 stampers and aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory accelerator where EPA fleet efficiency mandates and NHTSA CAFE standards tighten the cost-of-entry calculus for overweight vehicle designs, forcing material substitution toward magnesium-intensive architectures.
For Market Incumbents: To counter supply security threats from Chinese smelter concentration, Magnesium Elektron and US Magnesium LLC should deepen backward integration into dolomite mining and expand T4/T6 heat treatment capacity in the Aachen-Stuttgart corridor. Captive rare earth alloying metallurgy expertise in cerium-lanthanum formulations represents a defendable moat against REACH-driven reformulation cycles. For New Entrants and Emerging Players: EPA tailpipe emissions rules in the United States open a window for warm-forming equipment specialists to establish sheet alloy partnerships with Detroit-area OEMs pursuing closure panel substitution. India's PLI scheme for domestic electric vehicle production offers the most penetrable geography for first-mover magnesium sheet qualification with Tata Motors and Mahindra. A go-to-market angle targeting battery enclosure thermal management applications bypasses entrenched die casting incumbents in powertrain housings. For Investors and Strategic Acquirers: Consolidation pressure builds where rare earth magnesium formulation talent concentrates within Aachen research institutes and incumbent supplier R&D centers, creating acquisition targets for private equity seeking vertical integration into automotive lightweighting. Long-term viability frames around platform-level magnesium content targets displacing component-by-component procurement, favoring integrated casting-to-assembly partnerships over transactional suppliers. The signal to watch is insurance industry crashworthiness certification timelines for magnesium-intensive body structures, which would validate premium pricing power and accelerate OEM adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Smelting | Captive dolomite-to-alloy supply chains insulate automakers from Chinese export quota volatility. |
| Warm-Forming Equipment Partnerships | Precision-controlled press installations in Tamil Nadu and Maharashtra enable India EV body panel qualification. |
| REACH-Compliant Rare Earth Reformulation | Cerium-lanthanum alloy development secures European market access against ECHA yttrium restrictions. |
| Platform-Level Specification Consolidation | Volkswagen MEB and Hyundai E-GMP magnesium content targets compress supplier negotiation cycles. |
| Thixomolding Process Scale-Up | Japanese Tier-1 adoption for EV interior modules accelerates cycle time compression versus die casting. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down primary magnesium smelter capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 supplier procurement directors, foundry operations managers, and rare earth alloy metallurgists were cross-validated against secondary sources including NHTSA CAFE compliance filings, EPA emissions rulemaking dockets, ECHA REACH substance evaluations, and IHS Markit vehicle registration databases. Trade flow analysis of magnesium ingot and alloy shipments from Chinese customs data provided supply-side triangulation against automotive demand estimates.
Input-output matrices map alloy grade consumption across propulsion architectures, vehicle class segments, and regional production clusters throughout the projection horizon. Segmentation dimensions span cast versus sheet versus extruded alloy categories, transmission housing versus body panel versus battery enclosure applications, and captive OEM foundry versus merchant Tier-1 supply relationships. CAGRs were derived from regression analysis of historical magnesium content per vehicle trends against regulatory mandate trajectories, with electric vehicle platform architectures and warm-forming technology diffusion curves as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese export policy shifts or accelerated insurance industry crashworthiness protocols. Deviation in EPA rulemaking stringency or ECHA substance restriction timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Heavy Duty Engines Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Automotive Lubricants Market