
 Diesel Oxidation Catalyst Market | 2026-2036
Diesel Oxidation Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel Oxidation Catalyst Market Outlook
European substrate producers is broadening output of cordierite and silicon carbide carriers for high-cell-density configurations. BASF SE leverages its precious metals trading arm to secure palladium and platinum supply chains for catalyst manufacturing. Johnson Matthey anchors its position through proprietary catalyzed soot filter integration with oxidation stages. Tenneco competes aggressively in the North American aftermarket through direct OEM replacement channels.
A diesel oxidation catalyst is a flow-through ceramic or metallic substrate coated with platinum-group metals that promotes oxidation of carbon monoxide, hydrocarbons, and soluble organic fraction into carbon dioxide and water at exhaust temperatures above 180°C. Its primary commercial purpose is enabling compression-ignition engines to satisfy tailpipe emission limits without excessive fuel consumption penalty. Coated catalyst formulations command the dominant value share due to precise noble metal distribution control and superior thermal durability under transient engine loads. Heavy-duty vehicle end-use generates the deepest margin pools because fleet operators face mandatory periodic replacement cycles under operating lease agreements and regulatory compliance protocols. Catalytic oxidation technology leads unit volume as the baseline configuration for on-road diesel applications across regulated markets.
The US EPA and California Air Resources Board enforce periodic emission testing protocols that directly determine aftermarket replacement demand intervals for diesel oxidation catalysts. Europe's ECHA REACH restrictions on hexavalent chromium plating and EMA oversight of type-approval durability requirements shape substrate coating chemistry and supplier qualification pathways. China's MEE implements China VI emission standards that mandate onboard diagnostic monitoring of catalyst degradation, creating parallel compliance architecture for domestic and export-oriented manufacturers. Stakeholders must monitor divergence between EPA and Euro VII durability testing protocols when allocating R&D resources across regional product variants.
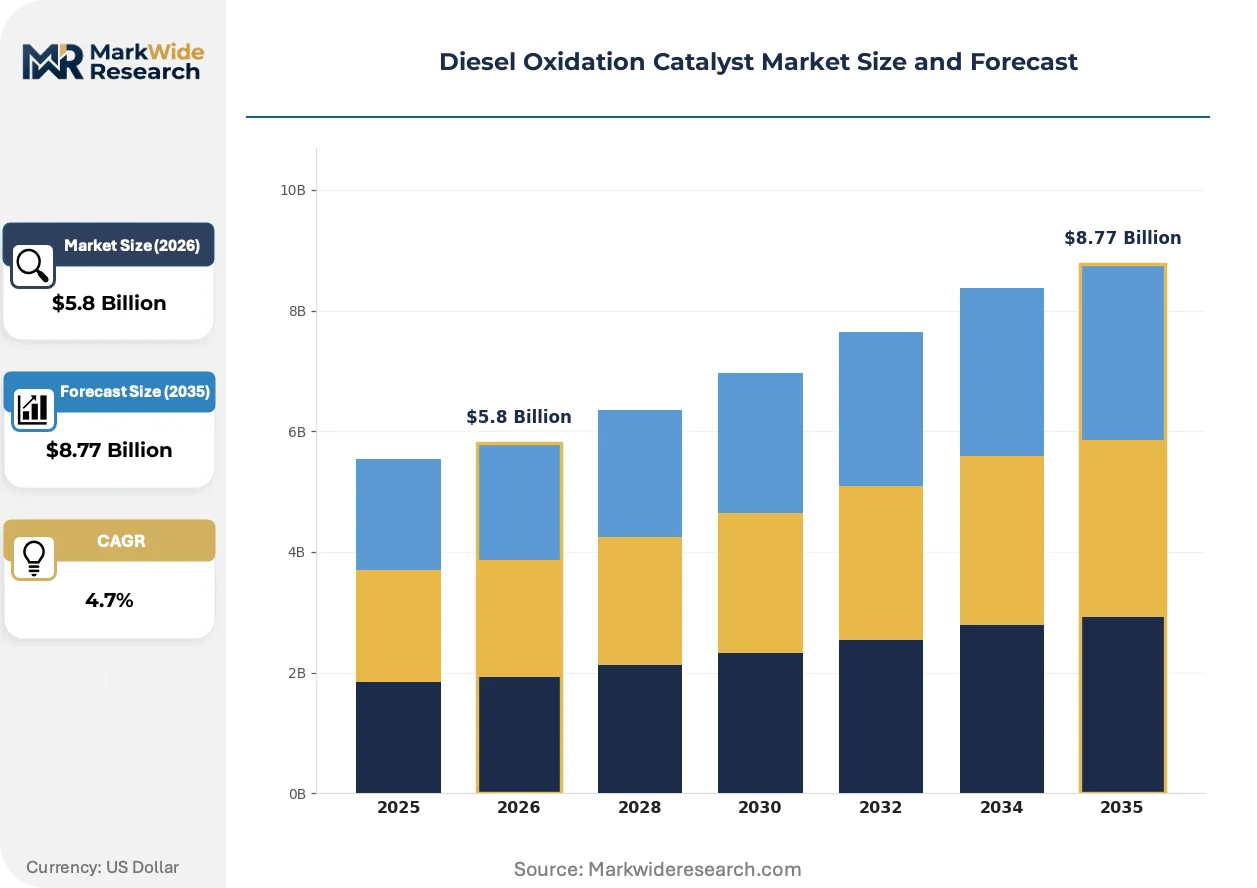
Market Dynamics
EPA Phase 2 greenhouse gas standards are compressing replacement cycles for heavy-duty commercial fleets, forcing substrate producers to accelerate thermal durability testing and platinum-group metal loading optimization to maintain compliance margins under tighter emission verification protocols.
Growth Catalysts
- Retrofit program mandates:North American fleet operators face mandatory catalyst replacement under operating lease agreements tied to EPA emission testing protocols, creating predictable aftermarket demand intervals.
- China VI diagnostic requirements:China's MEE mandates onboard catalyst degradation monitoring, compelling domestic and export-oriented manufacturers to build parallel compliance architectures.
- Low-temperature oxidation efficiency:Platinum-group metal innovations in coated formulations enable effective pollutant conversion at exhaust temperatures above 180°C, reducing fuel consumption penalties for compression-ignition engines.
Market Restraints
- Palladium supply concentration:Precious metal procurement depends on concentrated mining and refining operations, exposing catalyst manufacturers to price volatility and geopolitical supply disruptions.
- ECHA REACH chemical restrictions:Hexavalent chromium plating limitations constrain substrate coating chemistry options, requiring reformulation of corrosion-resistant carrier surfaces.
- Electric powertrain substitution:Battery-electric commercial vehicle development threatens long-term diesel oxidation catalyst demand in medium-duty urban delivery segments.
Strategic Opportunities
- Silicon carbide substrate expansion:High-cell-density SiC carriers offer superior thermal shock resistance for next-generation exhaust systems, opening premium positioning in severe-duty applications.
- Aftermarket direct channels:OEM replacement partnerships bypass traditional distributor networks, capturing margin pools previously allocated to independent exhaust shops.
- Euro VII durability divergence:Anticipated testing protocol differences from EPA methods create first-mover advantage for suppliers building dual-certification capabilities.
Industry Challenges
- Precious metals trading expertise:Catalyst manufacturers must build in-house commodity hedging capabilities or secure captive supply agreements to manage platinum and palladium cost exposure.
- Type-approval timeline compression:Germany's KBA enforces stringent aftermarket exhaust system certification, extending product validation cycles and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel Oxidation Catalyst Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Catalyst, Unsupported Catalyst, Washcoat Catalyst, Substrate Catalyst End User: Heavy-Duty Vehicles, Light-Duty Vehicles, Construction Equipment, Marine Vehicles Technology: Thermal Oxidation, Chemical Oxidation, Catalytic Oxidation, Two-Way Catalyst Application: Automotive Exhaust, Power Generation, Industrial Equipment, On-Road Emissions |
| Companies Covered | Tenneco, Denso, Umicore, NGK Insulators, Eberspächer, BASF SE, Faurecia, Dinex, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel Oxidation Catalyst Market Strategic Shifts
Platinum-group metal distribution control and substrate thermal management are converging to redefine performance benchmarks, while regulatory durability testing divergence is fragmenting product development roadmaps across regional markets.
Catalyzed soot filter integration with oxidation stages is electrifying exhaust aftertreatment architecture. Heavy-duty engine manufacturers are adopting combined DOC-DPF units to reduce packaging volume and thermal mass. This convergence is compressing the addressable market for standalone oxidation catalysts in new equipment while expanding replacement complexity.
California Air Resources Board periodic emission testing protocols are tightening verification stringency for in-use diesel vehicles. Fleet operators must demonstrate catalyst functionality through opacity and pollutant measurement, accelerating replacement demand in states adopting CARB standards. Heavy-duty vehicle end-use segments face the steepest compliance cost escalation.
Service contract unbundling is reshaping aftermarket procurement patterns. Fleet maintenance departments are separating catalyst replacement from bundled engine overhaul agreements, negotiating direct component supply with substrate producers. This disintermediation is most visible in North American long-haul trucking operations with centralized procurement functions.
Diesel Oxidation Catalyst Market Segmentation
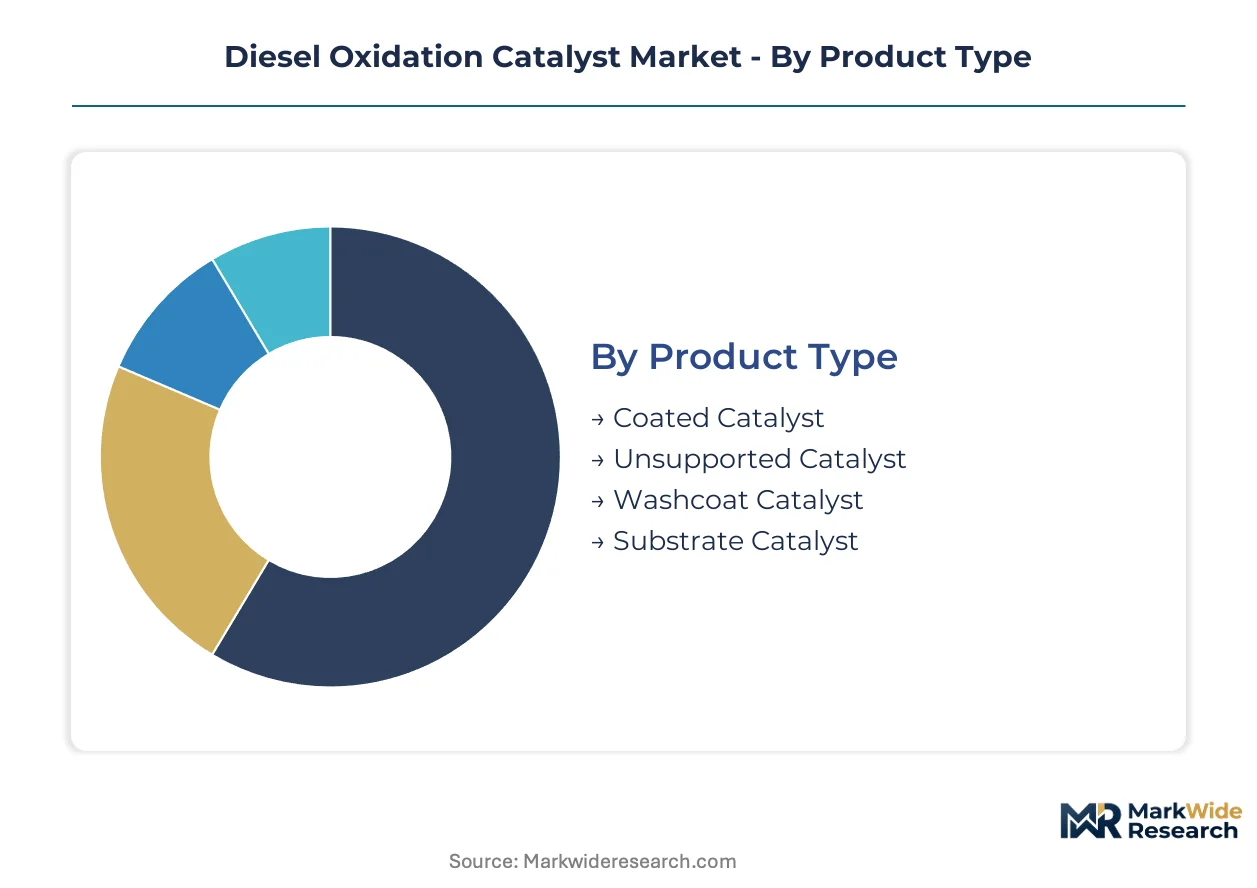
Diesel oxidation catalyst segmentation reflects divergent technical requirements across exhaust system architectures and regulatory compliance tiers. Manufacturers configure platinum-group metal loading, substrate cell density, and coating formulations to match specific duty cycles and emission verification protocols.
Product Type:
Cost tier separates procurement patterns across fleet operators and aftermarket distributors.
- Coated Catalyst:Precise noble metal distribution across ceramic or metallic substrates enables superior thermal durability under transient engine loads. Demand concentrates in Germany where KBA type-approval requirements mandate validated coating adhesion and degradation resistance for aftermarket exhaust systems.
- Unsupported Catalyst:Platinum-group metals applied directly to exhaust pipe surfaces without carrier substrates reduce material cost for price-sensitive retrofit programs. Procurement accelerates in North American heavy-duty commercial fleets facing compressed EPA Phase 2 replacement cycles.
- Washcoat Catalyst:Alumina-based suspension layers provide high surface area for catalytic active sites.
- Substrate Catalyst:Pre-formed cordierite or silicon carbide carriers receive integrated precious metal deposition.
Volume sits with coated catalysts; growth tilts toward unsupported catalysts.
End User:
Application intensity determines margin structure and replacement frequency.
- Heavy-Duty Vehicles:Long-haul trucking and commercial freight operations generate the deepest margin pools through mandatory periodic replacement under operating lease agreements. California Air Resources Board opacity testing protocols force accelerated catalyst verification in states adopting CARB standards.
- Light-Duty Vehicles:Passenger car and light truck applications favor compact packaging with lower platinum-group metal loading. Demand clusters in urban delivery fleets transitioning to hybrid powertrains while maintaining diesel range extenders.
- Construction Equipment:Severe-duty cycles with frequent thermal transients require enhanced substrate thermal shock resistance.
- Marine Vehicles:Saltwater corrosion exposure necessitates specialized substrate coatings and housing materials.
Revenue concentrates in heavy-duty vehicles; expansion accelerates fastest in construction equipment.
Technology:
Performance threshold separates baseline compliance from premium positioning.
- Catalytic Oxidation:Platinum-group metal promotion of carbon monoxide and hydrocarbon conversion at exhaust temperatures above 180°C delivers the baseline configuration for on-road diesel applications. China's MEE mandates onboard diagnostic monitoring of catalyst degradation under China VI standards, compelling parallel compliance architectures.
- Thermal Oxidation:Elevated exhaust temperature requirements without catalytic promotion reduce system cost for stationary power applications. Procurement localizes in power generation sectors with steady-state operating profiles.
- Chemical Oxidation:Additive-assisted pollutant conversion supplements thermal management in cold-start conditions.
- Two-Way Catalyst:Combined oxidation and reduction functionality addresses specific regulatory testing protocols.
Unit volume clusters with catalytic oxidation; technology investment flows toward two-way catalysts.
Application:
Regulatory jurisdiction shapes product certification requirements and channel strategy.
- Automotive Exhaust:Integration with catalyzed soot filters and selective catalytic reduction systems defines contemporary aftertreatment architecture. Combined DOC-DPF units reduce packaging volume while expanding replacement complexity for fleet maintenance departments.
- On-Road Emissions:EPA and CARB periodic testing protocols directly determine aftermarket replacement demand intervals. Service contract unbundling in North American long-haul operations enables direct component procurement from substrate producers.
- Power Generation:Stationary diesel engines for backup and prime power operate under distinct emission verification timelines.
- Industrial Equipment:Material handling and agricultural machinery face fragmented regulatory oversight across operating jurisdictions.
Replacement revenue dominates automotive exhaust; compliance spend climbs fastest in on-road emissions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-group metal refining clusters in South Africa and Russia anchor raw material flows for catalyst manufacturing worldwide. Regional demand patterns diverge sharply based on fleet age profiles, emission enforcement stringency, and domestic substrate production capacity.
United States
Heavy-duty commercial fleet operators dominate procurement volumes through mandatory replacement cycles under EPA Phase 2 greenhouse gas standards. California Air Resources Board opacity testing protocols force accelerated catalyst verification in states adopting CARB standards. Detroit-Warren manufacturing corridor hosts concentrated exhaust aftertreatment assembly operations serving domestic OEM channels.
Germany
KBA type-approval requirements enforce stringent aftermarket exhaust system certification, extending product validation timelines for coated catalyst formulations. ECHA REACH restrictions on hexavalent chromium plating constrain substrate coating chemistry options. Stuttgart industrial region anchors automotive exhaust system R&D clusters with integrated precious metals trading capabilities.
China
Domestic heavy-duty vehicle production scales drive baseline demand for catalytic oxidation configurations under China VI emission standards. MEE mandates onboard diagnostic monitoring of catalyst degradation, compelling parallel compliance architectures for export-oriented manufacturers. Yangtze River Delta concentration of cordierite substrate producers supplies both domestic and overseas catalyst fabricators.
Japan
Domestic engine manufacturers prioritize compact DOC-DPF integration for space-constrained commercial vehicle applications. METI industrial standards shape thermal durability testing protocols for coated substrate formulations. Nagoya-Toyota industrial corridor concentrates ceramic substrate research facilities serving Asian OEM supply chains.
India
Bharat Stage VI implementation compresses replacement intervals for commercial vehicle fleets operating in high-particulate urban corridors. Central Pollution Control Board enforcement of periodic emission testing accelerates aftermarket catalyst demand in Delhi-NCR and Maharashtra industrial zones. Pune-Aurangabad manufacturing belt hosts emerging substrate coating operations targeting cost-sensitive retrofit programs.
Diesel Oxidation Catalyst Market Competitive Environment
Global majors compete with regional champions across precious metals procurement and substrate manufacturing capabilities. Market structure tilts toward consolidated upstream supply with fragmented downstream fabrication tiers. Three archetypes dominate: integrated precious metals traders with captive catalyst production, specialized ceramic substrate manufacturers with coating partnerships, and exhaust system integrators with direct OEM channels. Capacity expansion in silicon carbide substrate production and strategic partnerships for platinum-group metal supply security represent the dominant competitive vectors.
Among diversified chemical conglomerates with precious metals trading arms, BASF SE and Umicore occupy positions exemplifying vertical integration from metal procurement to coated catalyst output. Johnson Matthey anchors the specialist tier through proprietary exhaust aftertreatment integration capabilities. Tenneco represents the exhaust system integrator archetype with established North American aftermarket replacement channels.
| Leading Market Players |
|---|
| Tenneco |
| Denso |
| Umicore |
| NGK Insulators |
| Eberspächer |
| BASF SE |
| Faurecia |
| Dinex |
| Johnson Matthey |
| Others |
Value Chain & Pricing Dynamics
Family-owned substrate producers in Germany's Stuttgart industrial region anchor premium pricing discipline through KBA certification exclusivity, while private-equity-rolled-up North American distributors compress margins via direct fleet procurement channels. This ownership bifurcation creates divergent pricing power between validated European coating specialists and volume-focused aftermarket consolidators.
Pricing Analysis
Warranty bundling separates heavy-duty fleet contracts from independent aftermarket transactions. Three-tier pricing structure across premium, standard, and economy levels reflects platinum-group metal loading density and thermal durability certification tier. Cost compression in unsupported catalyst tiers is intensifying because North American retrofit programs prioritize price over coating adhesion validation. Light-duty vehicle operators exhibit highest price sensitivity, while German commercial fleets absorb premiums for KBA-type-approved systems.
Supply Chain Analysis
Certification gating through Germany's KBA, China's MEE, and California's CARB fragments supplier qualification pathways across regional markets. Raw material flows draw from South African platinum and Russian palladium refining clusters, feeding cordierite substrate production in China's Yangtze River Delta and silicon carbide manufacturing in Japan's Nagoya corridor. Single-source vulnerability concentrates in palladium procurement, where geopolitical disruption risks cascade through coating formulation costs. Distribution runs through OEM captive channels in North America and independent exhaust shops in European aftermarket tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where precious metals trading capabilities determine margin capture. Players are pursuing backward integration into platinum-group metal supply agreements to defend against commodity volatility.
For Market Incumbents: Anticipate regulatory divergence between EPA and Euro VII durability protocols by building dual-certification testing infrastructure. Secure captive palladium supply agreements with South African refiners before commodity volatility escalates. Battery-electric commercial vehicle development threatens medium-duty diesel catalyst demand; counter through silicon carbide substrate expansion in severe-duty segments. For New Entrants and Emerging Players: Begin with unsupported catalyst retrofit programs targeting North American heavy-duty fleets facing compressed EPA Phase 2 replacement cycles. India's Bharat Stage VI implementation creates white-space opportunity in Delhi-NCR commercial corridors. Pursue direct procurement partnerships with fleet maintenance departments unbundling service contracts from engine overhaul agreements. For Investors and Strategic Acquirers: Distressed-cycle entries favor silicon carbide substrate specialists with China VI diagnostic capabilities in the Yangtze River Delta manufacturing belt. Long-term viability hinges on dual-certification architecture spanning EPA and anticipated Euro VII protocols. Watch for palladium price inflection as the signal triggering consolidation among coating-dependent mid-tier fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metals Supply | BASF SE's captive trading arm secures palladium flows against South African supply disruption. |
| Dual-Certification Testing Infrastructure | Parallel EPA and Euro VII validation compresses product launch timelines for export-oriented manufacturers. |
| Silicon Carbide Substrate Capacity Expansion | NGK Insulators' high-cell-density SiC carriers command premium positioning in severe-duty construction applications. |
| Direct Fleet Procurement Channels | Tenneco's OEM replacement partnerships bypass distributor margin extraction in North American aftermarket tiers. |
| Catalyzed Soot Filter Integration | Johnson Matthey's proprietary DOC-DPF units reduce packaging volume while expanding replacement complexity for service departments. |
Study Parameters
Multi-period observation of platinum-group metal price volatility, KBA type-approval timelines, and EPA emission testing protocol amendments anchored the trend analysis, supplemented by interviews with exhaust aftertreatment procurement managers at heavy-duty fleet operators, substrate coating R&D directors, precious metals trading specialists, and aftermarket distribution channel heads. Secondary validation drew from EPA regulatory filings, ECHA REACH substance restriction updates, China VI implementation notices, customs trade data for cordierite and silicon carbide substrates, and SEC disclosures from diversified chemical conglomerates. Bottom-up fleet replacement cycle modeling and top-down emission standard enforcement timelines were triangulated to cross-verify demand interval projections.
Input-output matrices mapped platinum-group metal loading requirements against substrate thermal durability specifications across coated, unsupported, and washcoat formulation tiers. Segmentation dimensions modeled include product type, end-use vehicle class, catalytic versus thermal oxidation technology, and application jurisdiction. CAGRs were derived from regression analysis of historical replacement intervals against regulatory enforcement intensity. Industry-specific forecast inputs incorporated CARB opacity testing adoption rates and China VI onboard diagnostic penetration curves.
Underlying measurement precision varies by segment; heavy-duty vehicle replacement cycles carry tighter precision than light-duty hybrid transition timelines due to mandated lease agreement structures. Forecasts reflect assumptions regarding EPA Phase 2 enforcement continuity and palladium supply chain stability. A model refresh is warranted upon material change in Euro VII durability testing protocol finalization or significant palladium price dislocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Friction Pads Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Struts System Market
Automotive Parts
Global Motorcycle Carbon Ceramic Brake Rotors Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Engine Oil Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
China Automotive Parts Aluminum Die Casting Market