
 Global Advanced Farming Market | 2026-2036
Global Advanced Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Farming Market Intelligence
Demand from large agricultural cooperatives and corporate farms is bifurcating the market away from traditional smallholder purchasing patterns. Deere & Company leverages its extensive equipment install base to integrate proprietary precision agriculture technologies. Trimble Inc. specializes in high-precision GPS and agnostic guidance systems compatible with multiple equipment brands. AGCO Corporation competes through a multi-brand portfolio, allowing it to address distinct regional and crop-specific requirements.
Advanced farming integrates data-centric technologies to optimize agricultural operations. This involves using systems like IoT sensors that provide real-time soil moisture data with sub-meter accuracy to enable variable rate application of inputs. Precision agriculture and robotics technologies are pivotal, with significant investment flowing into automated irrigation and drone-based crop monitoring. Among applications, yield prediction and soil analysis are central to maximizing farm profitability.
Regulatory frameworks like the United States Department of Agriculture (USDA) conservation programs and the EU Green Deal incentivize technology adoption for sustainable practices. China's dual carbon goals also encourage resource efficiency in agriculture, shaping demand for advanced farming systems. Vendor success will depend on aligning hardware and software platforms with evolving data privacy standards and interoperability requirements.
Market Dynamics
The market's structure is being redefined by the convergence of data-centric technologies and sustainability mandates. This shift is driven by regulatory pressures like the EU Green Deal, compelling large agricultural enterprises to adopt precision systems for resource management and operational efficiency.
Growth Catalysts
- EU Green Deal:This framework mandates sustainable resource use, directly spurring adoption of technologies for efficient water and input application in European agriculture.
- IoT Sensor Proliferation:The increasing availability and decreasing cost of sub-meter accuracy sensors enable real-time soil and crop monitoring, which is essential for variable rate applications.
- Cooperative Adoption in the US:Large agricultural cooperatives in the United States are standardizing on advanced farming platforms to optimize yields and reduce operational costs across vast acreages.
Market Restraints
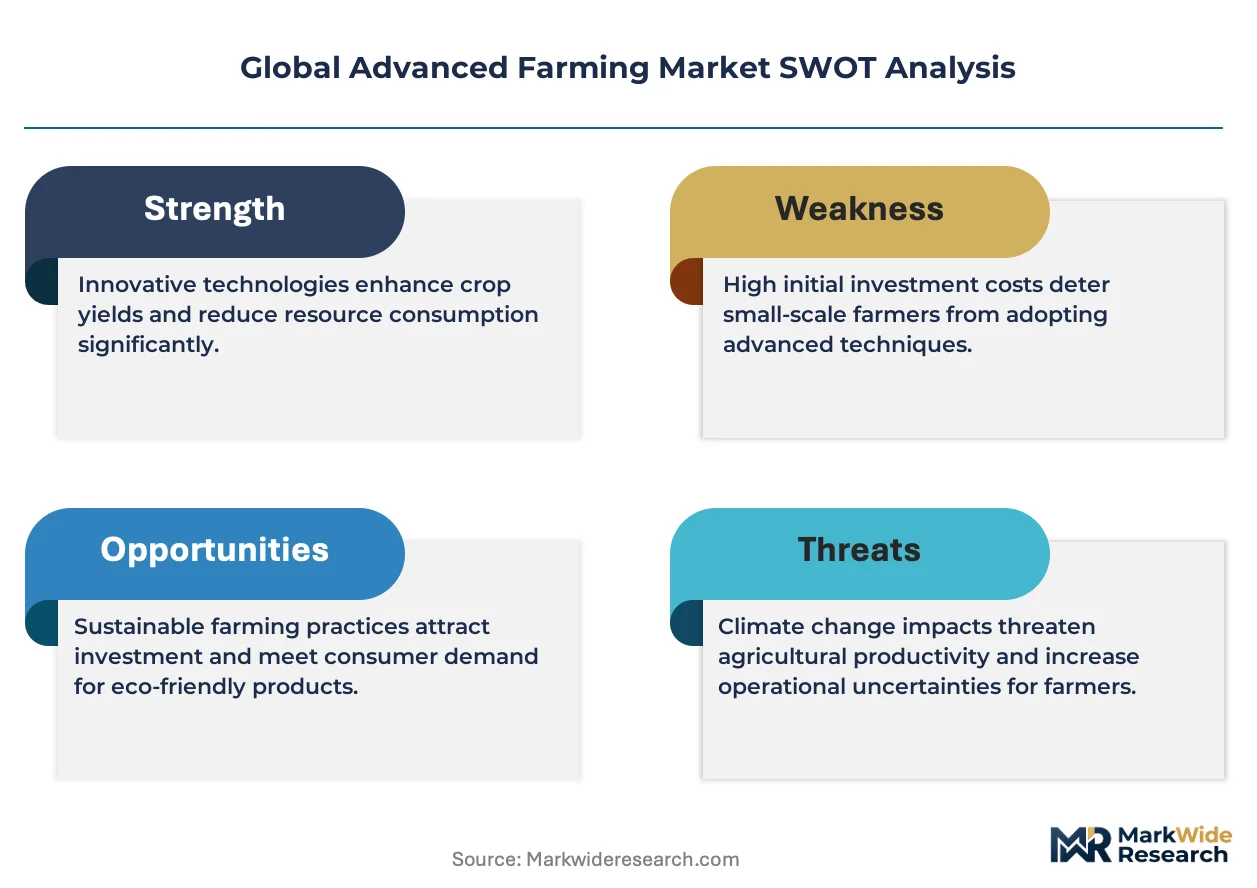
- High Capital Outlay:The significant upfront investment required for precision hardware like GPS guidance systems and robotic implements remains a primary barrier for small and mid-sized farms.
- Data Interoperability Gaps:A lack of common standards between equipment manufacturers creates data silos, preventing seamless integration of different hardware and software platforms on a single farm.
- Data Privacy Compliance:Regulations such as the EU's GDPR impose strict requirements on the collection and management of farm data, complicating operations for global technology vendors.
Strategic Opportunities
- Smallholder Farm Technology:There is a significant opportunity to develop and deploy scaled-down, affordable precision agriculture solutions for smallholder farms in markets like India and Southeast Asia.
- Predictive Analytics for Pest Control:Integrating AI with drone imagery and sensor data offers a new frontier for predicting and managing pest or disease outbreaks before they impact yields.
- China's Carbon Goals:The national dual carbon strategy in China creates strong incentives for adopting technologies that enhance resource efficiency and reduce the carbon footprint of agriculture.
Industry Challenges
- Agronomic Data Science Scarcity:A persistent shortage of professionals who combine agronomy expertise with data science skills limits the ability of farms to translate raw data into actionable insights.
- Legacy System Integration:Integrating modern IoT sensors and software with older, non-connected farm machinery presents significant technical and financial hurdles for many operators.
- Protocol Standardization Delays:The slow development of universal communication protocols for farm equipment hinders the creation of a truly plug-and-play ecosystem for advanced farming technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Farming Market |
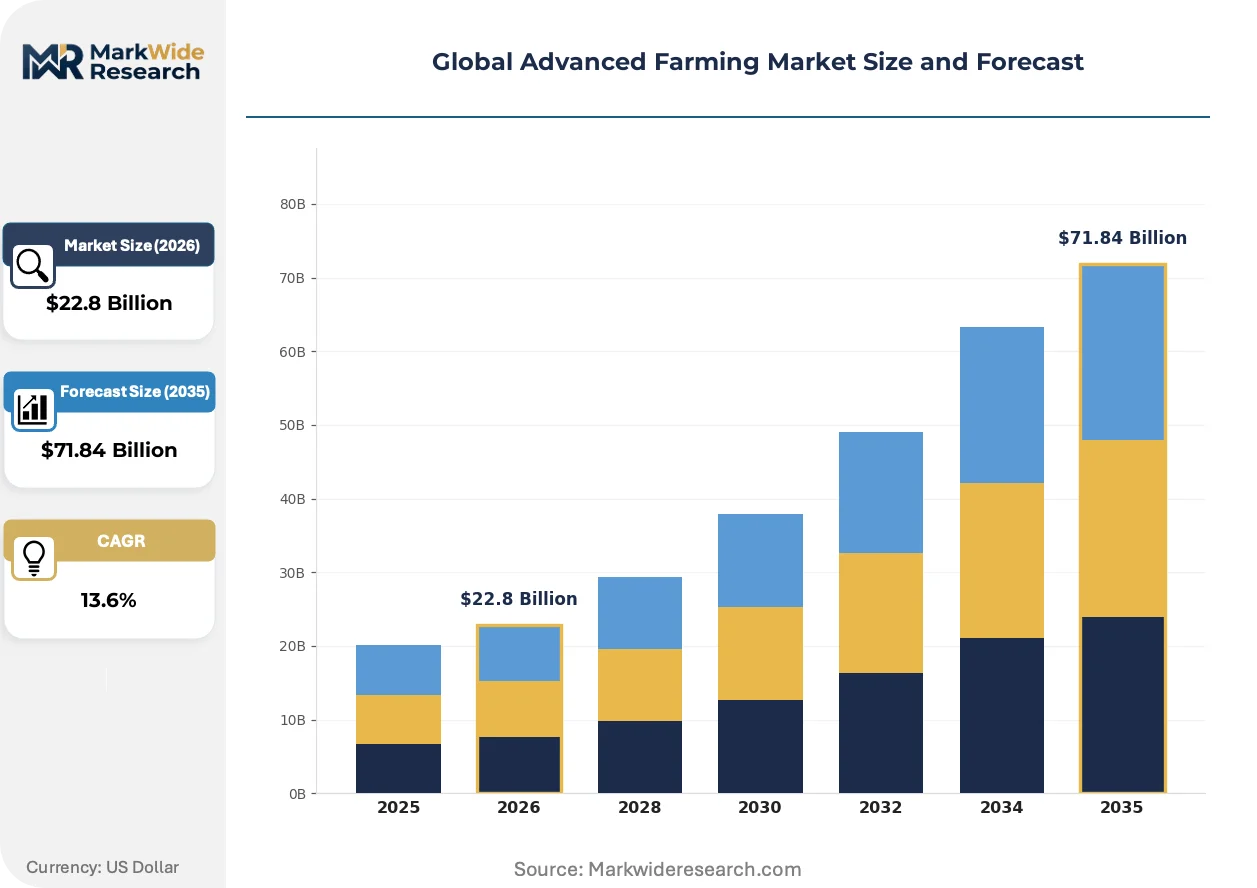
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $71.84 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Precision Agriculture, Drones, IoT Sensors, Automated Irrigation, Robotics, Vertical Farming Application: Crop Monitoring, Soil Analysis, Pest Control, Yield Prediction, Livestock Management, Fertilizer Management End User: Farmers, Agricultural Cooperatives, Research Institutions, Agrochemical Companies, Equipment Manufacturers, Agronomists Deployment: On-Field Solutions, Greenhouse Systems, Remote Monitoring, Weather Stations, Cloud-Based Platforms, Data Analytics |
| Companies Covered | Deere & Company, AGCO Corporation, Trimble Inc., CNH Industrial N.V., Kubota Corporation, Topcon Corporation, Raven Industries, John Deere & Company, Bayer CropScience AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Farming Market Strategic Shifts & Innovations
The convergence of automation, data analytics, and sustainability is fundamentally altering operational models in agriculture. This evolution favors integrated systems that provide measurable efficiency gains and compliance with environmental regulations.
Autonomous robotics provide automated solutions for tasks like irrigation control and drone-based crop monitoring. Large-scale corporate farms are the principal adopters, integrating these systems to manage labor shortages and operational complexity. This automated approach is supplanting traditional, calendar-based farming schedules with dynamic, data-informed operational workflows that optimize resource use in real time.
United States Department of Agriculture (USDA) conservation programs offer financial incentives for adopting sustainable farming practices. These initiatives directly promote investment in technologies that enhance soil health and optimize water usage, such as precision irrigation systems. The soil analysis and yield prediction segments are most affected, as technology vendors align product features with USDA program requirements to capture demand.
A notable shift from one-time hardware sales toward subscription-based models for data analytics and software-as-a-service (SaaS) is occurring. This model disrupts traditional equipment dealer channels by offering farmers access to powerful analytical tools without a large initial capital outlay. The trend is most prominent in North American and European agricultural hubs where operational expenditure is prioritized.
Global Advanced Farming Market Segmentation
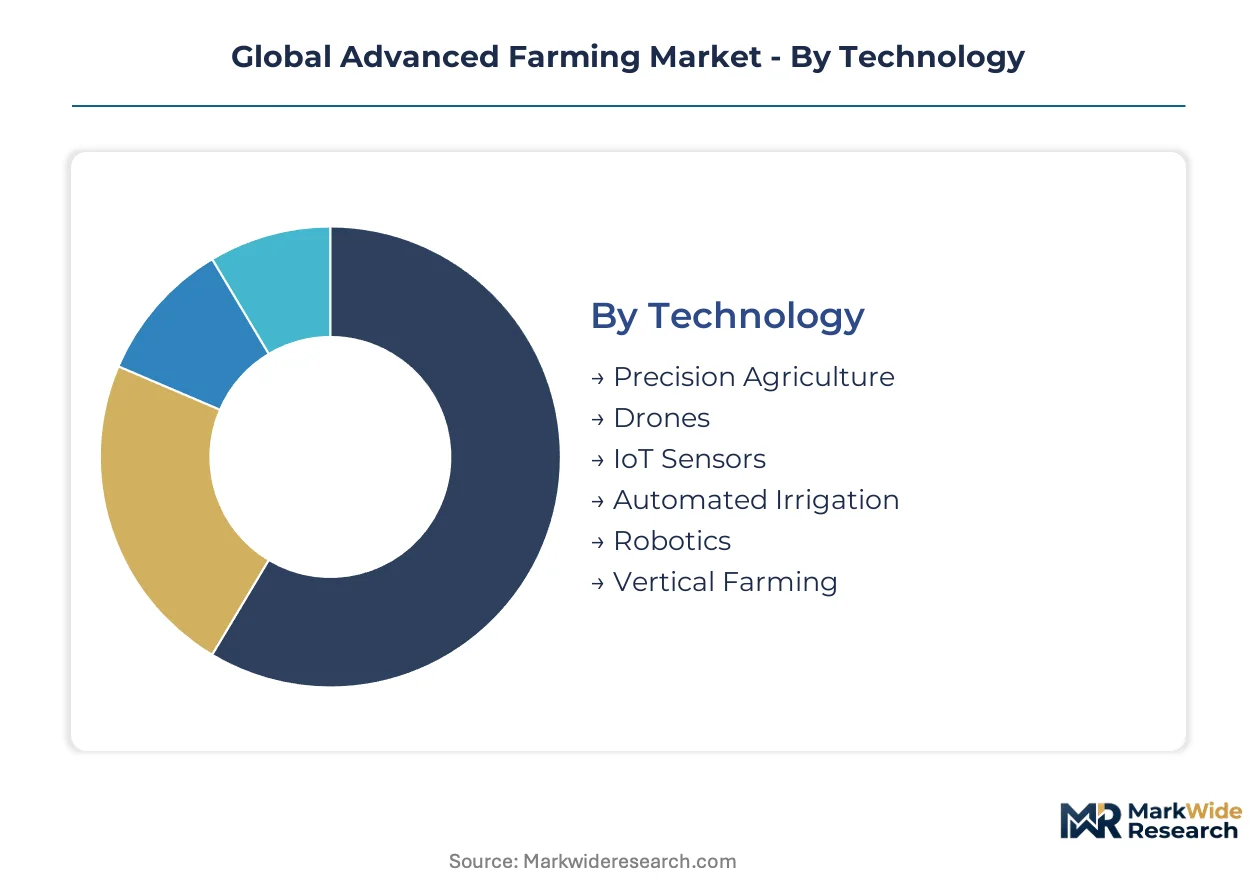
The Global Advanced Farming Market segments across diverse technologies, applications, end users, and deployment models. Each segment reflects distinct operational requirements and investment priorities within the agricultural sector. Understanding these divisions helps stakeholders identify key value pools and strategic growth areas across the global landscape.
Technology:
Margin pools within the technology category often concentrate in solutions offering high data accuracy and automation capabilities. These advanced systems command premium pricing due to their complexity.
- Precision Agriculture:This suite integrates GPS, GIS, and data analytics to optimize farming inputs, customizing treatments for specific soil conditions. Demand concentrates in North America due to farming operation scale.
- IoT Sensors:These devices provide real-time data on soil moisture, nutrient levels, and crop health, enabling dynamic decision-making and variable rate applications. Adoption expands in Europe, driven by EU Green Deal mandates.
- Drones:Unmanned aerial vehicles with multispectral cameras perform rapid crop monitoring and data collection.
- Automated Irrigation:Systems utilize sensors and software to deliver precise water amounts, minimizing waste.
- Robotics:Autonomous machines perform tasks like planting, harvesting, and weeding, addressing labor shortages.
- Vertical Farming:This method cultivates crops in vertically stacked layers, often indoors, optimizing land use.
Precision Agriculture holds installed capacity. Robotics is rotating up the share rankings.
Application:
Cost tiers within application segments vary based on data intensity and real-time processing requirements. Complex predictive analytics applications incur higher operational expenses.
- Crop Monitoring:This involves continuous observation of crop health, growth stages, and potential stressors using sensors, drones, and satellite imagery. Demand is significant in China, driving efficient resource use.
- Yield Prediction:Algorithms analyze historical data, weather patterns, and sensor inputs to forecast crop output, assisting farmers with resource allocation. North American farms widely adopt this application for profitability.
- Soil Analysis:Technologies assess soil composition, nutrient levels, and pH, informing precise fertilizer applications.
- Pest Control:Advanced systems identify and track pest infestations using imagery and AI for targeted intervention.
- Livestock Management:IoT devices monitor animal health, location, and behavior.
- Fertilizer Management:Precision tools ensure optimal nutrient delivery to crops, minimizing waste.
Crop Monitoring is expanding most quickly. Yield Prediction is also gaining significant traction.
End User:
Customer type significantly influences technology adoption patterns, with large-scale corporate farms and cooperatives demonstrating higher investment capacity. Smallholder farmers require affordable, scaled-down solutions.
- Agricultural Cooperatives:These organizations aggregate resources and purchasing power for member farms, facilitating adoption of advanced farming platforms and shared data analytics services. Demand concentrates in the United States, standardizing platforms.
- Farmers:Individual farm operators directly implement advanced farming technologies to improve efficiency and yield. European farmers increasingly adopt these tools, driven by regulatory incentives for sustainable practices.
- Research Institutions:Universities and government bodies develop new agricultural technologies.
- Agrochemical Companies:These firms integrate advanced farming data to optimize chemical product efficacy.
- Equipment Manufacturers:Companies integrate proprietary precision agriculture technologies.
- Agronomists:These experts utilize advanced data to provide tailored advice on crop management, soil health.
Agricultural Cooperatives are gaining share fastest. Equipment Manufacturers are also seeing their role evolve.
Deployment:
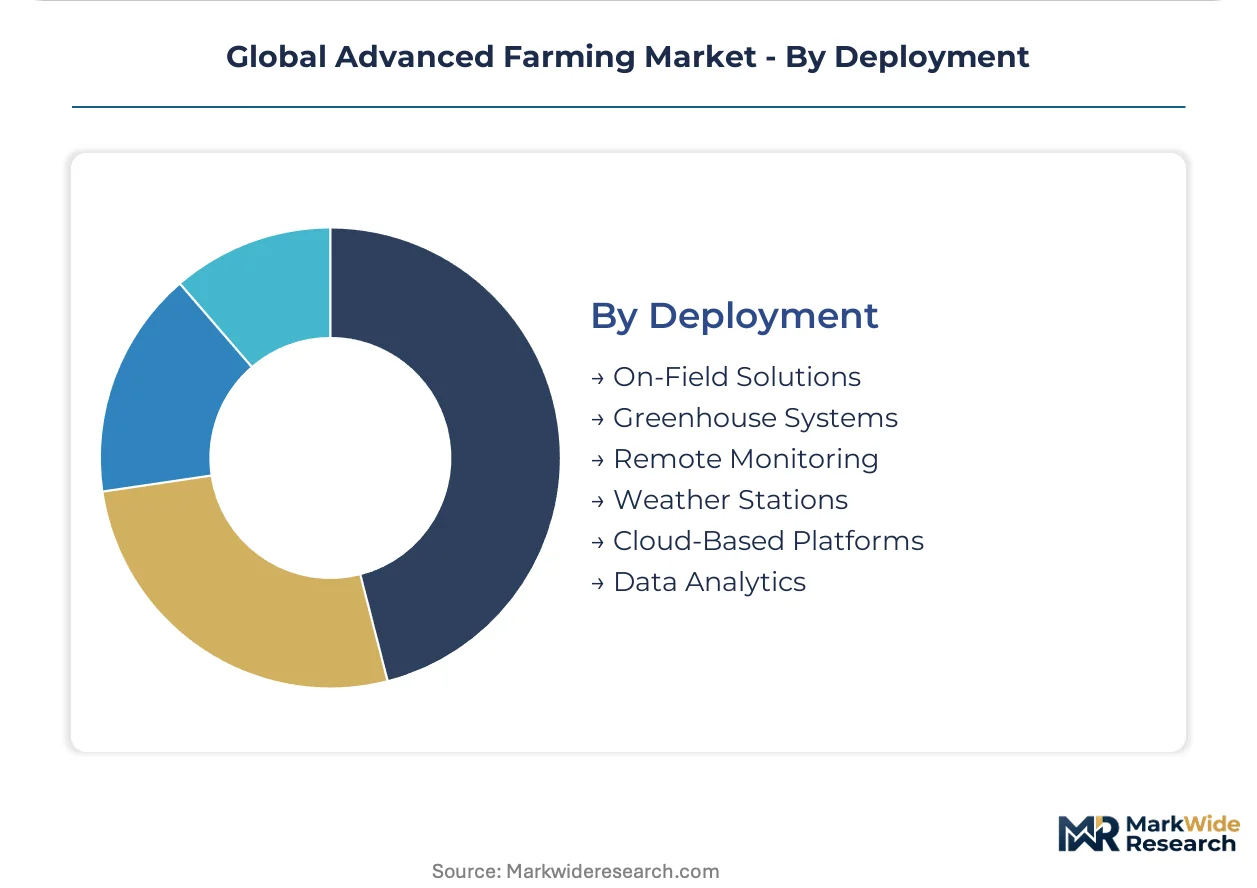
Maturity levels within deployment solutions vary, with established on-field systems providing foundational capabilities and cloud-based platforms representing the frontier of data integration and analytics.
- Cloud-Based Platforms:These solutions host data analytics, farm management software, and AI models, providing remote access to insights and operational control. North American and European agricultural hubs prioritize these platforms for scalability.
- Data Analytics:This segment processes and interprets large datasets from various sources, including sensors, drones, and historical records, to generate actionable insights for farm management. Demand is rising globally for optimizing yield and reducing costs.
- On-Field Solutions:Hardware and software directly installed on agricultural machinery or within the farm for immediate data collection.
- Greenhouse Systems:Controlled environment agriculture deployments optimize conditions for specific crops, integrating climate control.
- Remote Monitoring:Technologies allow farmers to observe and manage operations from off-site locations.
- Weather Stations:Localized weather data collection provides critical information for irrigation scheduling and pest prediction.
Cloud-Based Platforms exhibit the steepest expansion trajectory. Data Analytics also shows strong momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Global Advanced Farming Market exhibits demand concentration in North American agricultural hubs. This dynamic is driven by farming operation scale and strategic technology adoption. European agriculture also shows strong demand, influenced by sustainability mandates.
United States
Demand for advanced farming platforms is high due to large agricultural cooperatives standardizing operations. USDA conservation programs incentivize precision irrigation and soil health technologies. The Midwest region, particularly Iowa, integrates IoT sensors and data analytics in vast corn and soybean operations.
China
China's dual carbon goals significantly drive demand for resource-efficient advanced farming systems. Government policies encourage technology adoption reducing agriculture's carbon footprint. The Yangtze River Delta region sees increased integration of drone-based crop monitoring and automated irrigation to optimize yields.
Germany
German agriculture prioritizes precision agriculture and IoT sensors, spurred by the EU Green Deal's sustainable resource management mandates. This framework compels farms to adopt efficient water and input application technologies. Bavaria, a key agricultural state, is a center for deploying automated field robotics and data analytics solutions.
India
India presents a significant opportunity for scaled-down, affordable precision agriculture solutions for smallholder farms. Government initiatives promote sustainable practices and technology adoption to enhance food security. The Punjab region, known for extensive farming, pilots sensor-based soil analysis and yield prediction systems.
Brazil
Brazilian agribusiness demands advanced farming technologies to optimize large-scale commodity crop production. Policies supporting agricultural export competitiveness encourage GPS guidance systems and automated machinery. Mato Grosso, a major agricultural state, is a primary adopter of precision agriculture for soybean and corn cultivation.
Global Advanced Farming Market Key Industry Players
Concentration sits with established agricultural equipment manufacturers leveraging their extensive install base. The market structure is tiered, featuring these large incumbents alongside specialized technology providers and emerging software-as-a-service firms. Strategic archetypes include integrated hardware-software providers, precision data specialists, and automation solution developers, each competing on different value propositions. Dominant competitive moves involve portfolio diversification and strategic partnerships to integrate diverse technologies and expand geographic reach.
Within the integrated hardware-software provider tier, Deere & Company leverages its extensive equipment install base to offer proprietary precision agriculture technologies. Trimble Inc., a specialist in high-precision GPS and guidance systems, occupies a position as an agnostic technology provider compatible with multiple equipment brands. AGCO Corporation represents a multi-brand portfolio approach, allowing it to address distinct regional and crop-specific requirements across various agricultural markets. These companies exemplify the strategic differentiation employed to capture market share.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| Trimble Inc. |
| CNH Industrial N.V. |
| Kubota Corporation |
| Topcon Corporation |
| Raven Industries |
| John Deere & Company |
| Bayer CropScience AG |
| Others |
Cost & Logistics Intelligence
Subscription-based contracts for advanced farming solutions lock in recurring revenue streams and provide price visibility for ongoing services.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for sustainable farming technologies, incentivizing efficient resource use. Subscription-based models for data analytics and SaaS are prominent, alongside project-based pricing for integrated hardware solutions. Price differentiation stems from data accuracy, system interoperability, and comprehensive after-sales support. Pricing softness stems from the high initial capital outlay required for advanced hardware. Smallholder farms exhibit high price sensitivity; large agricultural cooperatives prioritize value and integration.
Supply Chain Analysis
Just-in-time inventory practices for common components optimize manufacturing efficiency in advanced farming systems. Manufacturing hubs in the United States, Germany, and China produce core components for these technologies. IoT sensors, high-precision GPS modules, and specialized robotic actuators are critical inputs. Single-source vulnerability for advanced sensor technology poses a significant structural risk. Direct sales channels to large corporate farms and established dealer networks serve individual farmers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The advanced farming market presents a compelling service-attach opportunity, with software-as-a-service subscriptions for data analytics expanding faster than hardware sales.
For Market Incumbents: Secure existing customer relationships by integrating proprietary software platforms with installed equipment bases. Acquire specialized data analytics firms to counter emerging pure-play software entrants. Invest strategically in AI-driven predictive analytics R&D to maintain technological leadership. Leverage extensive dealer networks to provide localized after-sales support against rising data interoperability challenges.
For New Entrants and Emerging Players: Lead with affordable, scaled-down precision agriculture solutions tailored for smallholder farms in emerging markets like India. Target the underpenetrated predictive analytics segment for pest and disease control. Deploy cloud-based SaaS models to minimize upfront capital outlay for farmers. Focus on interoperable systems compatible with diverse legacy farm machinery.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technology providers offering subscription-based data analytics and software solutions. Long-term viability in this sector hinges on robust data integration capabilities and compliance with evolving privacy standards. Identify niche AI/ML startups specializing in agronomic data science for strategic acquisition. The signal to watch is the increasing stringency of regulatory mandates from the EU Green Deal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies diverse hardware and software components for seamless farm management. |
| AI-Driven Analytics Development | Enhances yield prediction and pest control through advanced data processing. |
| Smallholder Solution Localization | Adapts precision agriculture technologies for specific regional crop requirements. |
| Data Privacy Certification | Builds farmer trust and ensures compliance with GDPR and other regulations. |
| Ecosystem Partnership | Expands market reach and technological capabilities through strategic alliances. |
Research Approach
A spread of perspectives from agronomists, farm operators, equipment manufacturers, and technology developers converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders were triangulated with secondary validation. Secondary sources included USDA reports, EU Green Deal policy documents, company financial filings, and academic research. Both bottom-up market sizing and top-down validation techniques were employed.
Segmentation dimensions modeled include technology, application, end user, deployment, and regional adoption patterns. The analytical framework integrated market size, growth rates, and competitive intensity across the analysis window. Compound annual growth rates were derived from historical data and projected market drivers. Key forecast inputs included IoT sensor deployment rates and precision agriculture investment trends.
Forecasts assume regulatory continuity in the EU Green Deal and USDA conservation programs; material policy shifts would require re-modeling. The analysis reflects assumptions regarding technological advancements and market adoption rates, with geopolitical instability and data privacy legislation changes posing specific risk factors. Revision becomes warranted when these underlying conditions cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Global Precision Livestock Farming Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Global Digital Agriculture Platform Market