
 Irrigation Testing Kit Market | 2026-2036
Irrigation Testing Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Irrigation Testing Kit Market Foresight
Chinese sensor foundries is restructuring capacity allocation toward agricultural IoT modules, tightening component availability for irrigation testing OEMs. Hanna Instruments leverages its pH and conductivity expertise to dominate water quality tester segments across Latin American export markets. Thermo Fisher Scientific Inc. sustains R&D intensity in portable analytical devices, while LaMotte Company specializes in field-grade colorimetric kits for nutrient monitoring.
An irrigation testing kit comprises calibrated instruments that measure soil moisture tension, hydraulic pressure, volumetric flow, and chemical composition of irrigation water, typically operating across detection ranges from 0 to 200 centibars for tensiometers and 0 to 14 pH for water quality probes. These devices enable precision agriculture by preventing over-irrigation, reducing salinity damage, and optimizing fertilizer delivery through fertigation systems. Soil moisture meters anchor the product mix due to universal deployment across row-crop operations, while wireless sensors represent the fastest-expanding technology segment as farm operators seek real-time telemetry integration. Agricultural irrigation absorbs the dominant share of end-user demand, though environmental consultants are emerging as a high-margin channel for compliance-driven monitoring services.
The EPA enforces Clean Water Act provisions that mandate effluent monitoring near concentrated animal feeding operations, directly stimulating demand for nitrate and phosphate testing capabilities. California's State Water Resources Control Board operates groundwater sustainability agencies that require volumetric accounting, pushing farmers toward flow meter adoption. Stakeholders must monitor how state-level groundwater legislation cascades into equipment specification standards and whether FDA produce safety rules expand microbial water testing requirements beyond current boundaries.
Market Dynamics
Wireless telemetry is compressing replacement cycles for manual soil moisture equipment as farm cooperatives in water-stressed regions mandate real-time volumetric reporting to regulatory agencies.
Growth Catalysts
- California's Sustainable Groundwater Management Act:Groundwater sustainability agencies in the Central Valley require metered extraction documentation, forcing cooperative adoption of flow-calibrated testing arrays.
- Fertigation system proliferation:Precision nitrogen delivery in row-crop operations demands continuous pH and electrical conductivity monitoring at injection points.
- Salinity damage prevention:Coastal agricultural zones deploy sodium adsorption ratio testers to manage irrigation water quality before root-zone degradation occurs.
Market Restraints
- MEMS sensor foundry concentration:Agricultural IoT module demand from Chinese semiconductor fabs is tightening component allocation for tensiometer OEMs.
- Calibration drift in field conditions:pH electrode lifespan degrades rapidly in high-alkalinity irrigation water, elevating total cost of ownership for glass-probe systems.
- Manual method persistence:Smallholder operations in developing agricultural economies continue relying on gravimetric soil sampling rather than capacitance-based meters.
Strategic Opportunities
- Environmental consultant channel expansion:Third-party compliance auditors in the US are bundling irrigation testing services with Clean Water Act effluent monitoring for concentrated animal feeding operations.
- LoRaWAN protocol convergence:Low-power wide-area networks are integrating with soil moisture telemetry to eliminate cellular subscription costs in remote field deployments.
- Brazilian export agriculture:Soybean and sugarcane operations in Mato Grosso are adopting ISO 14001-aligned water stewardship protocols requiring documented irrigation efficiency metrics.
Industry Challenges
- Hydraulic sensor integration complexity:Pressure transducer installation in existing pivot irrigation systems demands specialized plumbing expertise that equipment distributors rarely maintain in-house.
- Cross-jurisdictional certification timelines:Wireless sensor platforms must secure FCC Part 15 approval, CE marking, and ANATEL homologation sequentially, stretching product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irrigation Testing Kit Market |
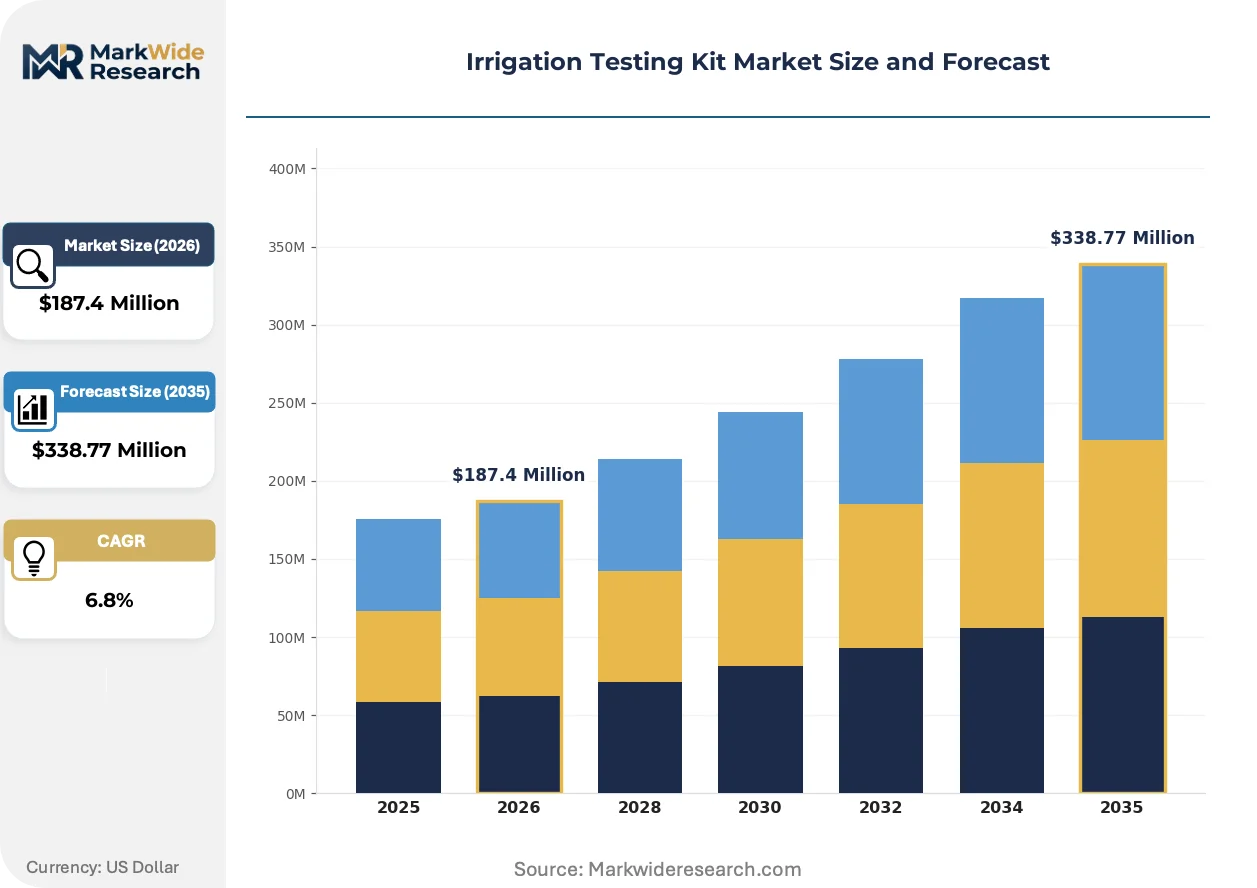
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Moisture Meters, Pressure Gauges, Flow Meters, Water Quality Testers Application: Agricultural Irrigation, Landscape Management, Infrastructure Evaluation, Environmental Monitoring Technology: Wireless Sensors, Automated Systems, Data Loggers, Manual Devices End User: Farmers, Landscapers, Regulatory Agencies, Environmental Consultants |
| Companies Covered | Soilmoisture Equipment Corp, AquaCheck, Hanna Instruments, Netafim, LaMotte Company, Agilent Technologies, Thermo Fisher Scientific Inc., Merck Group, PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irrigation Testing Kit Market Shifts & Advancements
Sensor miniaturization and cloud-native telemetry architectures are collapsing the functional boundary between standalone field instruments and integrated farm management platforms.
Capacitance-based volumetric water content sensors are integrating with edge-computing nodes to enable sub-hourly moisture threshold alerts without cellular backhaul dependency. Large-scale vegetable producers in Spain's Almería greenhouse cluster are deploying these arrays at 50-meter grid densities. The technology is integrating fertigation trigger logic directly into irrigation valve controllers, bypassing traditional farm management software layers.
The EPA's effluent limitation guidelines for concentrated animal feeding operations are mandating continuous nitrate monitoring in discharge channels, compelling livestock integrators to install ion-selective electrode systems previously rare outside municipal water treatment. Equipment suppliers are responding with portable colorimetric backup kits for calibration verification during regulatory inspections. Dairy operations in Wisconsin's Fox River watershed represent the most advanced deployment zone.
Cooperative procurement consortia are aggregating demand across multiple farm operations to negotiate volume-based sensor calibration service contracts. Independent equipment dealers in the US Midwest are losing service revenue to manufacturer-direct subscription models. Nebraska's natural resources districts exhibit the most pronounced shift toward centralized equipment leasing with embedded technical support.
Irrigation Testing Kit Market Segmentation
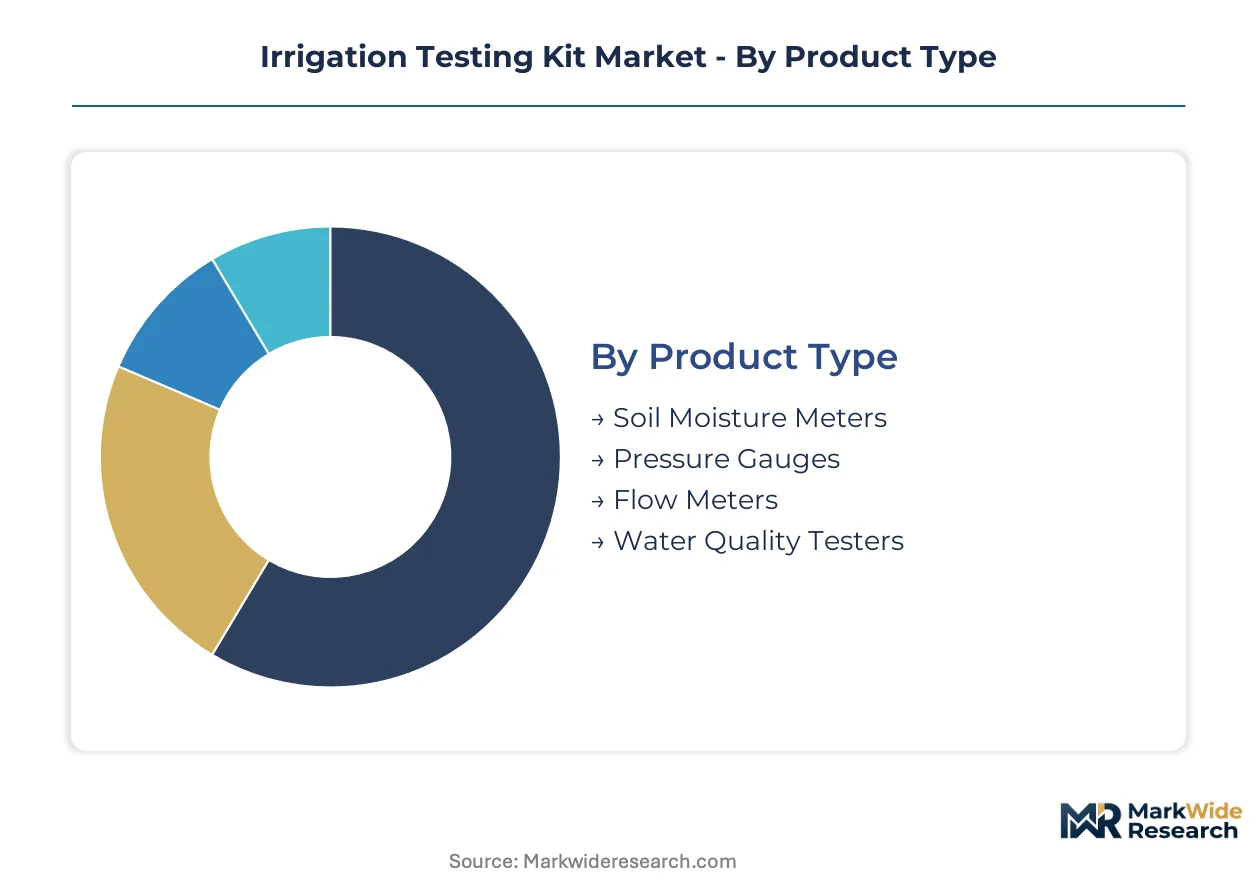
Irrigation testing equipment segments by functional role in water management workflows. Product architecture determines deployment cost, calibration frequency, and integration depth with farm management software.
Product Type:
Buyers differentiate by measurement domain—soil matrix versus hydraulic network versus water chemistry—each demanding distinct sensor physics and maintenance protocols.
- Soil Moisture Meters:Capacitance and tensiometer-based devices measure matric potential and volumetric water content across root zones. California's Central Valley vegetable cooperatives deploy these at 50-meter grid densities to comply with State Water Resources Control Board groundwater accounting mandates.
- Water Quality Testers:Multi-parameter probes monitor pH, electrical conductivity, and sodium adsorption ratio at fertigation injection points. Coastal agricultural zones in Spain's Almería cluster rely on these to prevent root-zone salinity degradation from irrigation water.
- Pressure Gauges:Bourdon tube and digital transducer instruments measure hydraulic head in pressurized distribution systems. Center-pivot operators use these to detect line leaks and nozzle blockages before crop stress manifests.
- Flow Meters:Electromagnetic and ultrasonic devices quantify volumetric extraction for regulatory compliance. Groundwater sustainability agencies in water-stressed regions mandate metered documentation from agricultural pumpers.
Soil moisture meters lead volumes today; water quality testers are gaining share fastest.
Application:
Segmentation by operational context reveals divergent procurement patterns—volume-driven field agriculture versus specification-driven regulatory compliance.
- Agricultural Irrigation:Row-crop and specialty crop operations deploy integrated sensor arrays for precision water delivery. Brazil's Mato Grosso soybean belt is adopting ISO 14001-aligned water stewardship protocols requiring documented efficiency metrics.
- Environmental Monitoring:Third-party auditors bundle irrigation testing with Clean Water Act effluent assessments for concentrated animal feeding operations. EPA enforcement of nitrate discharge limits in Wisconsin's Fox River watershed drives ion-selective electrode installations.
- Landscape Management:Golf courses and municipal parks utilize handheld moisture meters to optimize turf irrigation scheduling. Water conservation ordinances in arid US states accelerate replacement of timer-based controllers with soil-feedback systems.
- Infrastructure Evaluation:Canal operators and irrigation district engineers assess conveyance efficiency through flow measurement and pressure profiling. Aging concrete canal systems in the western United States require periodic hydraulic performance audits.
Agricultural irrigation dominates current procurement; environmental monitoring exhibits the steepest expansion trajectory.
Technology:
Technology tiering separates buyers by connectivity requirements and labor substitution priorities—manual methods persist where capital constraints outweigh efficiency gains.
- Wireless Sensors:LoRaWAN and cellular-enabled soil moisture nodes transmit sub-hourly threshold alerts without farm management software intermediation. Large-scale greenhouse producers in Spain are eliminating cellular subscription costs through low-power wide-area network convergence.
- Manual Devices:Gravimetric soil sampling and portable colorimetric kits remain prevalent in smallholder economies and backup calibration roles. Equipment suppliers provide these for regulatory inspection verification when continuous monitoring systems require field validation.
- Automated Systems:Integrated valve controllers execute irrigation triggers based on sensor-derived moisture thresholds. Fertigation system proliferation in precision nitrogen delivery applications demands continuous pH and conductivity feedback loops.
- Data Loggers:Standalone recording devices capture time-series measurements for retrospective analysis and compliance documentation. Groundwater sustainability agencies accept these for volumetric extraction reporting where real-time telemetry is not mandated.
Manual devices retain installed base dominance; wireless sensors are climbing the fastest.
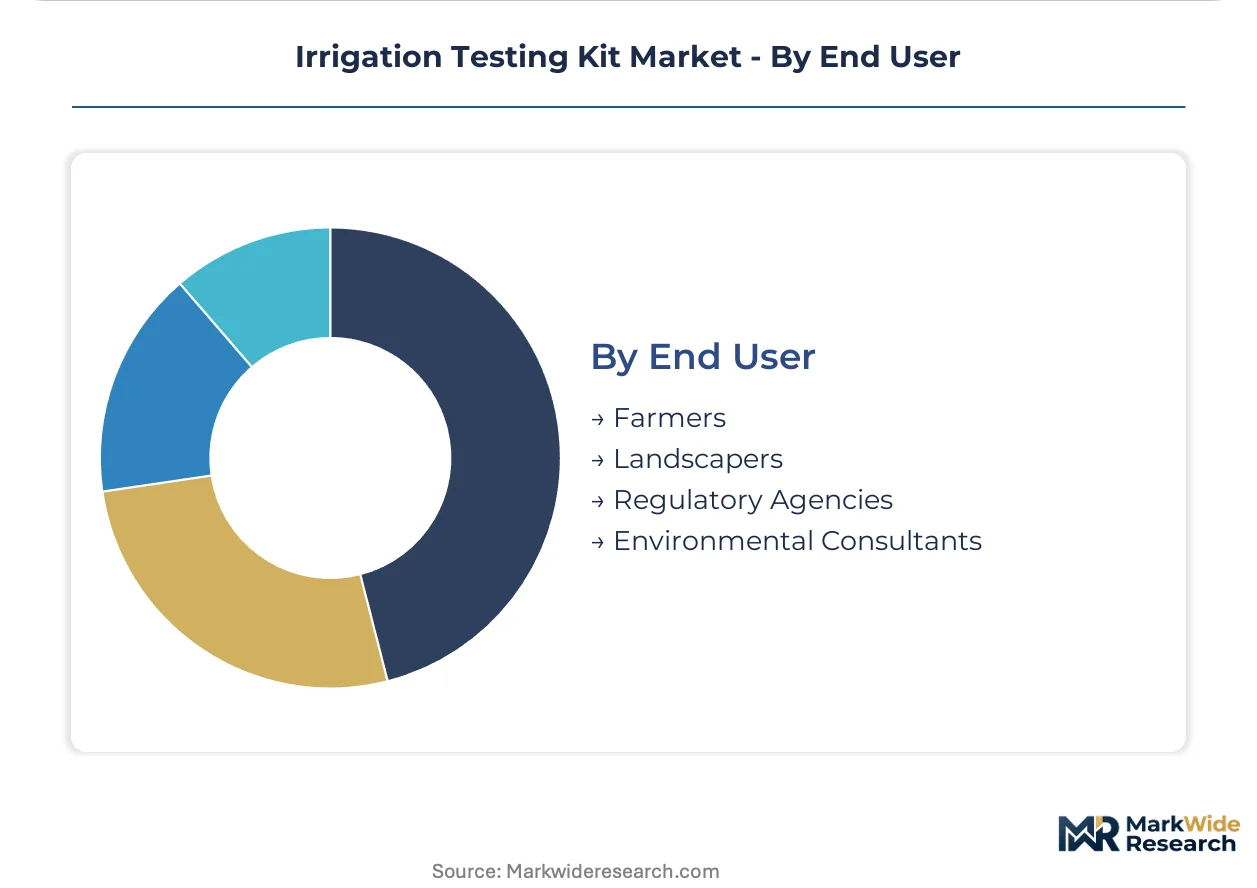
End User:
End-user categories reflect divergent budget authority—individual operators versus institutional procurement with embedded technical support requirements.
- Farmers:Individual and cooperative agricultural operators purchase equipment directly or through leasing arrangements with calibration services. Nebraska's natural resources districts exhibit pronounced shift toward centralized equipment leasing with manufacturer-direct subscription models.
- Regulatory Agencies:State and federal environmental enforcers specify equipment standards for permitted discharge monitoring. The EPA's effluent limitation guidelines for concentrated animal feeding operations mandate continuous nitrate monitoring capabilities.
- Environmental Consultants:Third-party compliance auditors bundle testing services with multi-site monitoring contracts. These stakeholders aggregate demand across operations to negotiate volume-based sensor calibration service agreements.
- Landscapers:Commercial turf management contractors deploy portable meters for client-specific irrigation optimization. Municipal and private golf course contracts drive seasonal equipment replacement cycles.
Farmers represent the largest addressable base; environmental consultants command premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's groundwater sustainability mandates are compressing equipment replacement cycles faster than Brazil's export agriculture protocols, creating divergent procurement rhythms across the two largest agricultural economies.
United States
California's Central Valley vegetable cooperatives deploy soil moisture meters at 50-meter grid densities to satisfy State Water Resources Control Board extraction accounting. The EPA's effluent limitation guidelines for concentrated animal feeding operations mandate continuous nitrate monitoring in Wisconsin's Fox River watershed. Nebraska's natural resources districts are shifting toward centralized equipment leasing with embedded calibration services.
Brazil
Soybean and sugarcane operations in Mato Grosso are adopting ISO 14001-aligned water stewardship protocols requiring documented irrigation efficiency metrics. ANVISA oversees agricultural chemical residue standards that intersect with irrigation water quality testing. The Cerrado agricultural frontier exhibits the fastest sensor deployment velocity as export certification requirements tighten.
Spain
Greenhouse producers in Almería are eliminating cellular subscription costs through LoRaWAN-enabled soil moisture telemetry at sub-hourly alert frequencies. The EU Green Deal's Farm to Fork strategy pressures water-stressed Mediterranean agriculture toward precision irrigation documentation. Andalusian vegetable exporters are deploying capacitance-based sensors with integrated fertigation trigger logic.
China
Sensor foundries are restructuring capacity allocation toward agricultural IoT modules, tightening component availability for tensiometer OEMs serving domestic precision agriculture pilots. MEE water quality standards for agricultural discharge are expanding monitoring obligations in the Yangtze River Delta. Shandong Province's vegetable cooperatives represent the most advanced domestic deployment zone for wireless soil moisture arrays.
Australia
Murray-Darling Basin water buyback programs are forcing irrigators toward metered extraction documentation for entitlement compliance. The country's national environmental regulator enforces salinity intervention thresholds that stimulate sodium adsorption ratio tester procurement. Cotton operations in New South Wales are deploying electromagnetic flow meters for volumetric reporting to basin authorities.
Irrigation Testing Kit Market Competitive Landscape
United States producers anchor one tier; European specialists hold adjacent positions in water chemistry instrumentation. The vendor base organizes around three strategic archetypes: diversified analytical instrument conglomerates, irrigation-focused sensor OEMs, and field-grade portable kit specialists. Competitive maneuvering concentrates on wireless telemetry integration partnerships and manufacturer-direct subscription service models that displace independent dealer networks.
Within the diversified analytical tier, Thermo Fisher Scientific Inc. and Agilent Technologies occupy positions reflecting R&D intensity in portable device architectures. Hanna Instruments exemplifies the water chemistry specialist archetype with pH and conductivity expertise extending across Latin American export markets. LaMotte Company represents the field-grade portable segment, with colorimetric kit specialization for nutrient monitoring applications. Soilmoisture Equipment Corp anchors the soil physics instrumentation tier with tensiometer and capacitance sensor offerings.
| Leading Market Players |
|---|
| Soilmoisture Equipment Corp |
| AquaCheck |
| Hanna Instruments |
| Netafim |
| LaMotte Company |
| Agilent Technologies |
| Thermo Fisher Scientific Inc. |
| Merck Group |
| PerkinElmer Inc. |
| Others |
Supply & Pricing Matrix
California's groundwater sustainability mandates are forcing cooperative procurement consortia toward volume-based sensor calibration service contracts, compelling manufacturers to restructure pricing around embedded technical support rather than transactional equipment sales. This shift is compressing margins for independent equipment dealers while rewarding OEMs with direct subscription capabilities.
Pricing Analysis
Distributor margin compression is accelerating as manufacturer-direct subscription models displace traditional dealer networks in Nebraska's natural resources districts. Three-tier pricing structure across premium, standard, and economy levels separates wireless telemetry-integrated arrays from manual field kits and portable colorimetric backups. Cost compression in the wireless sensor tier is intensifying because Chinese semiconductor fabs are tightening component allocation for agricultural IoT modules. Smallholder operations in developing agricultural economies exhibit the highest price sensitivity, while environmental consultants bundling compliance auditing services command the least.
Supply Chain Analysis
Freight cost volatility from Chinese sensor foundries to North American assembly operations is elevating landed costs for capacitance-based volumetric sensors. Component manufacturing concentrates in China, Malaysia, and Mexico, with final calibration and certification distributed across California, Wisconsin, and Nebraska facilities. Agricultural IoT module production draws from MEMS foundries, glass pH electrode suppliers, and LoRaWAN chipset vendors. Single-source vulnerability in Chinese semiconductor fab capacity represents the dominant structural risk. Distribution runs through cooperative procurement consortia aggregating multi-farm demand and independent equipment dealers losing service revenue to OEM direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between California's regulatory-mandated replacement cycles and Brazil's export-certification-driven efficiency documentation, with cost differentials favoring early positioning in water-stressed jurisdictions with tightening groundwater legislation.
For Market Incumbents: Acquire wireless telemetry integration capabilities to defend against manufacturer-direct subscription models displacing independent dealer networks. Secure captive supply of MEMS sensor components through backward integration into Chinese foundry partnerships or long-term offtake agreements. Invest in LoRaWAN protocol certification to eliminate cellular subscription cost disadvantages against emerging connectivity competitors. For New Entrants and Emerging Players: Environmental consultants bundling Clean Water Act compliance auditing with irrigation testing services represent the most penetrable buyer archetype, given their premium pricing power and aggregated multi-site demand. Target Wisconsin's Fox River watershed dairy operations facing EPA nitrate discharge mandates with portable colorimetric backup kits for calibration verification. Pursue white-label partnerships with cooperative procurement consortia in Nebraska's natural resources districts to bypass established dealer relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with field-grade portable kit specialists possessing colorimetric expertise and regulatory inspection relationships. Long-term viability hinges on positioning against wireless telemetry compression of manual equipment replacement cycles. Target acquisition candidates with established California Central Valley cooperative relationships and embedded calibration service contracts. Watch for EPA expansion of microbial water testing requirements beyond concentrated animal feeding operations as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Telemetry Integration | LoRaWAN protocol convergence eliminates cellular subscription costs for remote Spanish greenhouse deployments. |
| Manufacturer-Direct Subscription Launch | Embedded calibration services displace independent Midwest equipment dealer revenue streams. |
| Cooperative Procurement Consortium Partnership | Volume-based sensor calibration contracts aggregate multi-farm demand across Nebraska natural resources districts. |
| Regulatory Certification Investment | FCC Part 15, CE marking, and ANATEL homologation sequential approval accelerates product launch timelines. |
| Environmental Consultant Channel Expansion | Third-party Clean Water Act auditing bundles irrigation testing with nitrate discharge compliance in Wisconsin watersheds. |
Research Methodology
Bottom-up agricultural irrigation modeling reconciled against top-down wireless sensor OEM tracking forms the analytical core of this study. Primary interviews with farm cooperative procurement officers, environmental compliance auditors, irrigation equipment distributors, MEMS foundry supply managers, and state water resources regulatory staff were combined with secondary validation from EPA effluent limitation guidelines, California State Water Resources Control Board groundwater sustainability agency filings, FCC equipment authorization databases, and Brazilian ANVISA agricultural chemical residue standards. Triangulation between demand-side procurement patterns and supply-side component allocation trends ensures cross-verified output integrity.
Input-output matrices map sensor unit shipments against fertigation system proliferation rates, groundwater sustainability mandate adoption timelines, and export certification requirement trajectories across the analysis window. Segmentation dimensions include product architecture by measurement domain, connectivity tier by telemetry protocol, end-user budget authority structure, and regional regulatory enforcement intensity. CAGRs were derived from regression analysis of replacement cycle compression rates and technology displacement curves. Forecast inputs incorporate LoRaWAN network deployment velocities and state-level groundwater legislation cascading timelines.
Underlying measurement precision varies by segment; wireless sensor arrays and flow meter installations carry tighter precision than manual gravimetric sampling estimates and smallholder economy penetration assumptions. Forecasts reflect documented regulatory enforcement patterns, component supply allocation shifts, and cooperative procurement behavioral models. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Animal Feed Testing Market