
 Global Agriculture Sensors Market | 2026-2036
Global Agriculture Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agriculture Sensors Market Analysis
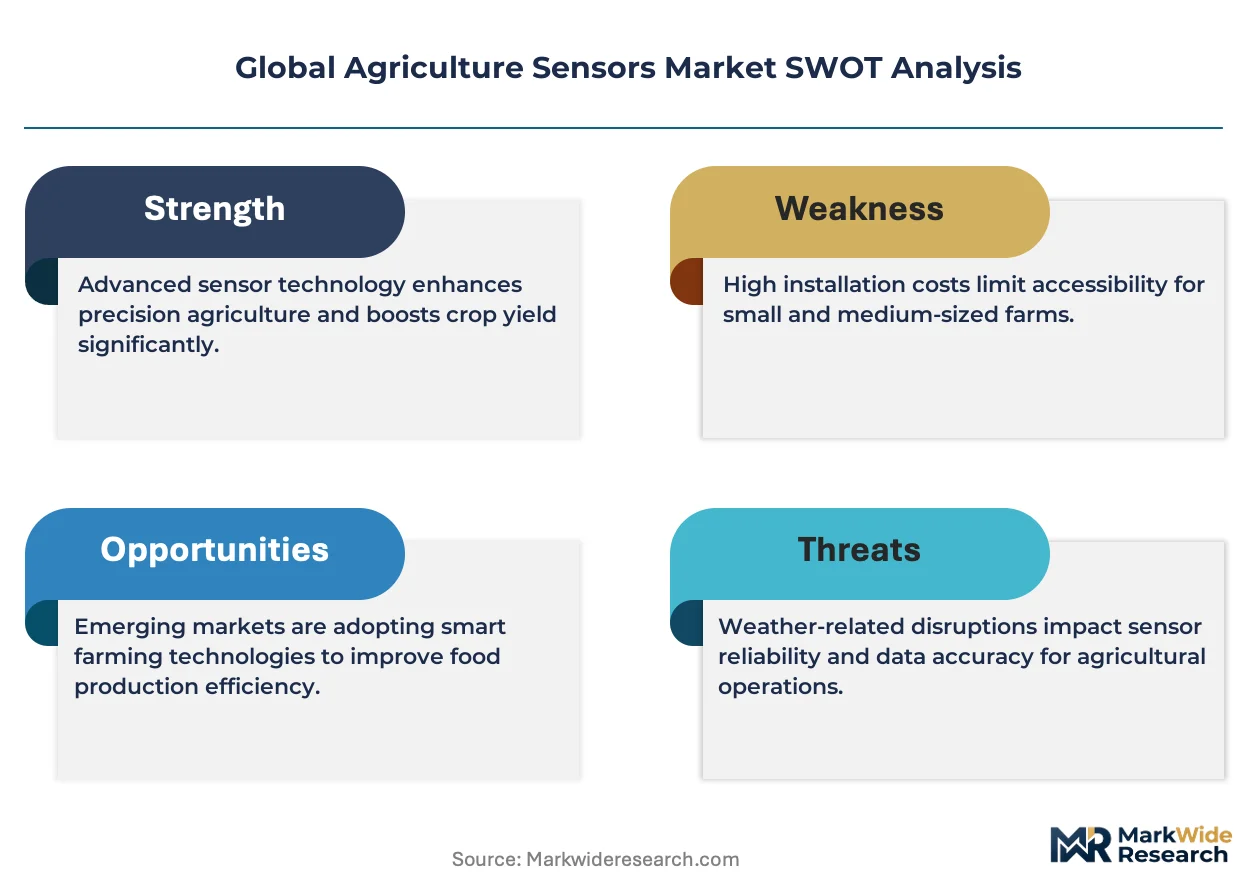
Israel's precision agriculture ecosystem is narrowing the gap between research-grade instrumentation and field-deployable hardware. Deere & Company leverages its dealer network to embed soil and crop sensors directly into tractor and planter OEM configurations. Trimble anchors its positioning in GPS-guided variable-rate application systems that integrate sensor feedback loops. METER Group specializes in dielectric soil moisture probes calibrated for arid-zone irrigation scheduling.
Agriculture sensors comprise electrochemical, spectroscopic, and MEMS-based transducers engineered to measure soil moisture, canopy temperature, ambient humidity, and nutrient ion concentration with ±2% accuracy in uncontrolled field conditions. These devices transmit telemetry via LoRaWAN or cellular IoT protocols to cloud analytics platforms that generate prescriptive irrigation and fertilization directives. Soil sensors command the largest installed base due to universal applicability across row crops and orchards, though crop sensors register the fastest expansion as hyperspectral imaging migrates from aerial platforms to ground-based nodes. IoT connectivity dominates technology architecture while acoustic sensing remains nascent, confined primarily to grain storage monitoring and limited pest detection pilots.
The EPA enforces water quality standards that mandate documented nutrient runoff reduction, compelling growers in the Mississippi River Basin to install verified flow and nitrate sensors. EFSA guidelines on precision agriculture data integrity shape EU member state subsidy eligibility for sensor-equipped farm machinery. India's CEA rural electrification standards determine power availability for sensor networks in unirrigated districts. Stakeholders must weigh interoperability certification against proprietary platform lock-in when selecting hardware vendors for multi-year deployment cycles.
Market Dynamics
Precision livestock operations are compressing sensor deployment cycles from seasonal to continuous monitoring, forcing hardware vendors to engineer devices for 24/7 animal-worn durability rather than periodic soil insertion. This operational shift is redistributing R&D budgets toward MEMS accelerometers and thermal imaging cores.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandatory environmental compliance documentation is compelling European growers to install verified nutrient runoff sensors. Subsidy eligibility now hinges on certified data collection infrastructure.
- Brazil Cerrado soybean operations:Large-scale mechanized farms in this region are driving soil moisture monitoring adoption at densities exceeding North American row-crop averages. Irrigation water scarcity is accelerating probe deployment.
- LoRaWAN protocol maturation:Low-power wide-area networking is eliminating cellular subscription costs for remote field installations. Telemetry reliability in unirrigated districts is improving markedly.
Market Restraints
- Dielectric probe calibration drift:Salinity interference in arid-zone soils degrades soil moisture accuracy below ±2% specifications within 18 months of field deployment. Recalibration service infrastructure remains sparse.
- Israeli component concentration:Precision agriculture sensor R&D clusters in this geography create supply vulnerability for hyperspectral imaging cores and MEMS fabrication.
- CEA rural electrification gaps:Unirrigated districts in India lack grid reliability for continuous sensor network operation. Battery-dependent deployments face replacement logistics.
Strategic Opportunities
- Acoustic sensing pilots:Grain storage monitoring applications are proving viability for pest detection algorithms. Expansion into orchard pest identification represents unpenetrated white space.
- Hyperspectral ground migration:Imaging technology is shifting from aerial platforms to fixed ground nodes. Vineyard and high-value orchard operators are early adopters.
- India PLI scheme extension:Domestic manufacturing incentives for electronics hardware could localize sensor assembly. Import duty structures favor captive production.
Industry Challenges
- Interoperability certification fragmentation:Proprietary platform lock-in complicates multi-vendor deployments. Growers face stranded asset risk when switching analytics providers.
- Field technician scarcity:Installation and recalibration of electrochemical nutrient probes requires agronomy-electronics hybrid skill sets. Training pipelines are underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agriculture Sensors Market |
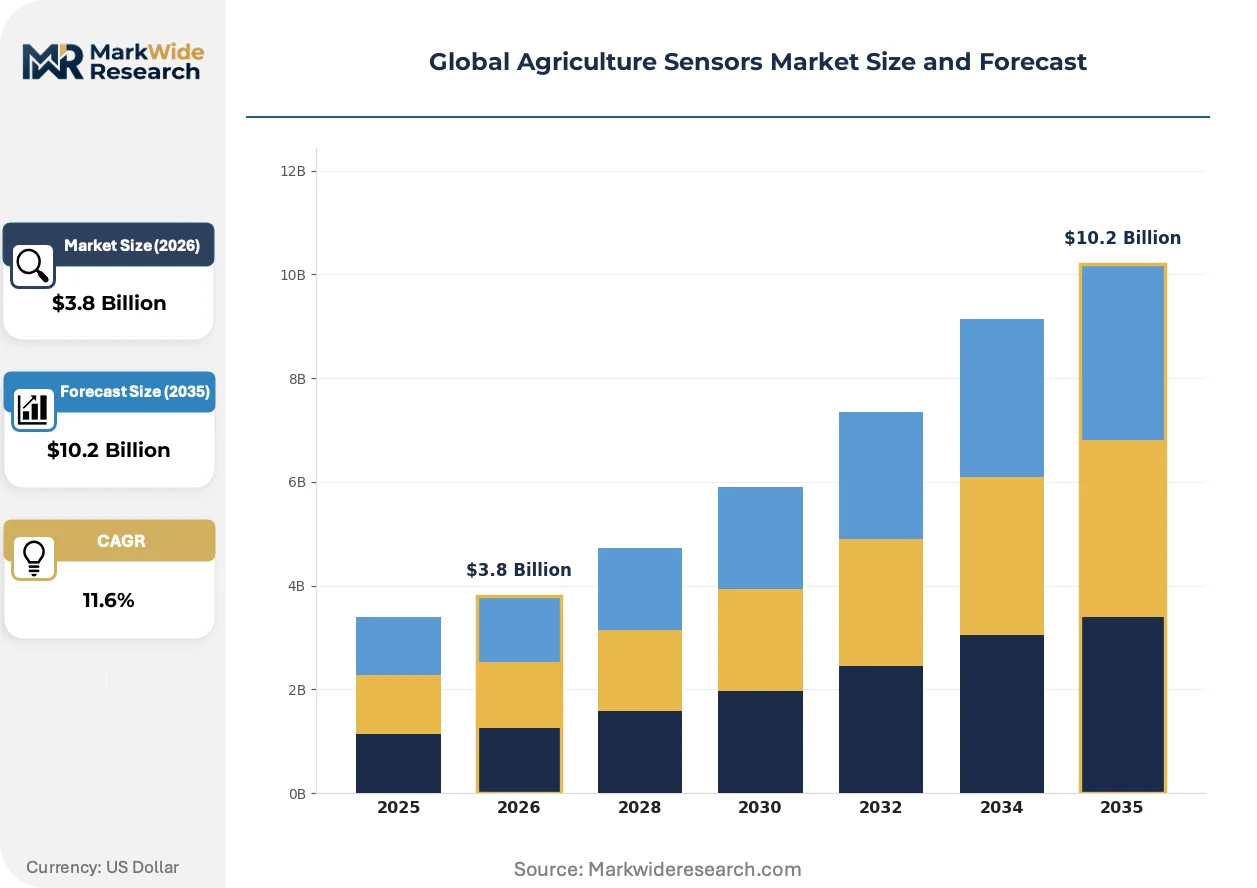
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Sensors, Weather Sensors, Crop Sensors, Water Sensors Technology: IoT, GPS, Remote Sensing, Acoustic Application: Irrigation Management, Yield Monitoring, Soil Monitoring, Pest Management End User: Farmers, Agricultural Research Institutions, Crop Consultants, Government Agencies |
| Companies Covered | CropX, METER Group, Acclima, Pycno, Sentera, Deere & Company, Trimble, Teralytic, Caipos GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agriculture Sensors Market Emerging Trajectories
Ground-based hyperspectral nodes are displacing drone-mounted cameras as the primary data source for canopy health monitoring. This hardware migration is compressing imagery refresh cycles from weekly flights to hourly captures.
Multi-band spectroscopic sensors are rendering obsolete single-wavelength chlorophyll meters in high-value orchard management. Washington State apple growers and Italian wine grape operations are adopting these units at replacement rates exceeding 40% annually. The technology is compressing fertilizer application windows from weeks to days.
EPA water quality enforcement in the Mississippi River Basin is mandating documented nutrient runoff reduction through verified sensor networks. Growers must install flow and nitrate probes with tamper-evident data logging to maintain operating permits. Corn-soy operations in Iowa and Illinois are absorbing the largest compliance costs.
Service unbundling is separating hardware procurement from analytics subscriptions. Dealer networks now offer sensor-only purchases with third-party platform compatibility. Brazilian Cerrado operators are driving this flexibility demand to avoid proprietary data silos.
Global Agriculture Sensors Market Segmentation
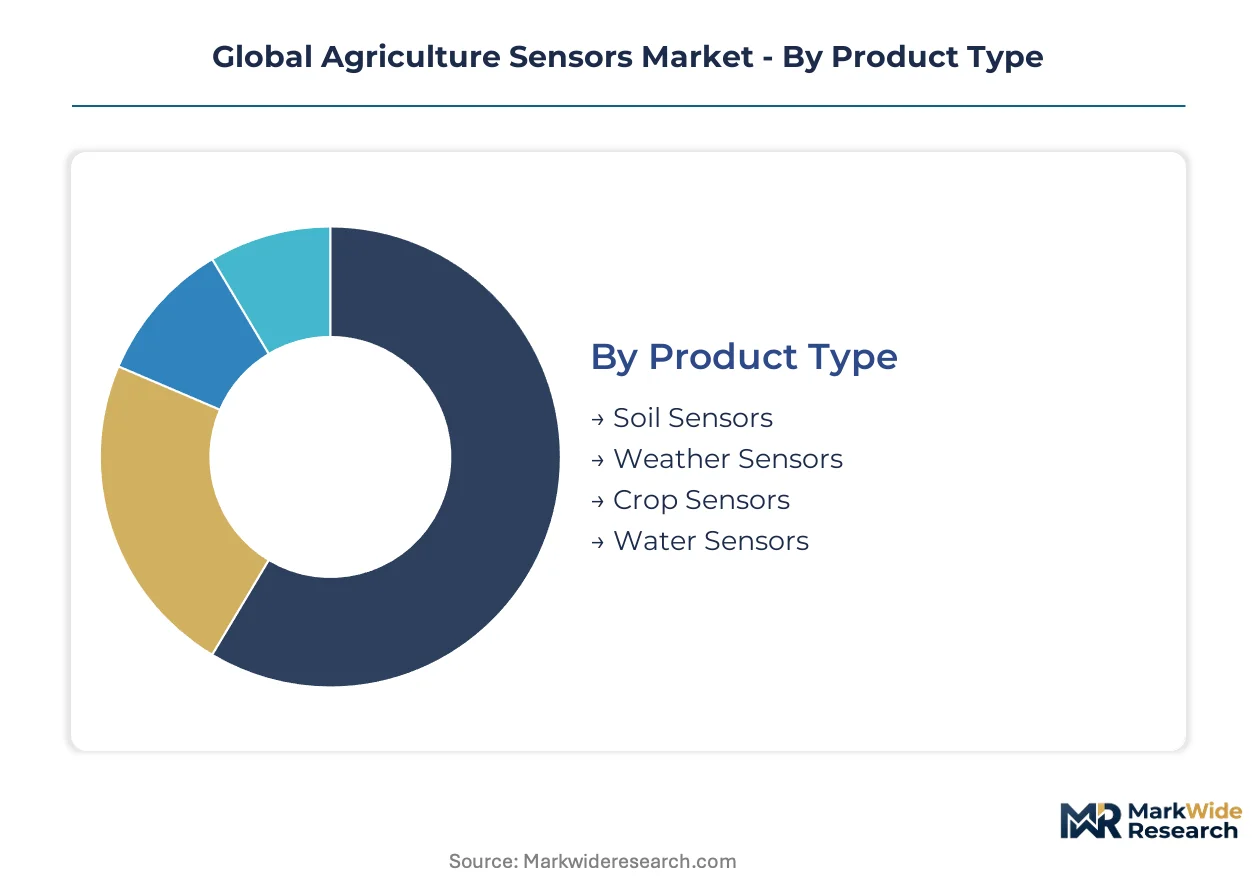
Sensor deployment patterns diverge sharply across product architectures, connectivity protocols, and operational use cases. Procurement decisions hinge on calibration service availability, telemetry reliability, and integration complexity with existing farm management systems.
Product Type:
After-sales calibration intensity varies dramatically—electrochemical probes demand annual recertification while weather stations require minimal field service.
- Soil Sensors:Dielectric and electrochemical transducers measure moisture, salinity, and nutrient ion concentration through direct substrate insertion. Brazil's Cerrado soybean operations deploy these at densities exceeding North American averages, driven by irrigation water scarcity and mechanized farm scale. By volume, Soil Sensors lead. By growth pace, Crop Sensors are ahead.
- Crop Sensors:Hyperspectral imaging and thermal cameras capture canopy health indicators, chlorophyll fluorescence, and water stress signatures. Ground-based nodes in Washington State apple orchards and Italian vineyards are displacing drone-mounted systems, compressing imagery refresh from weekly to hourly. Service intensity concentrates on lens cleaning and spectral recalibration.
- Weather Sensors:Multi-parameter stations track ambient temperature, humidity, precipitation, and wind velocity for microclimate modeling. LoRaWAN-enabled units eliminate cellular subscription costs in remote districts.
- Water Sensors:Flow meters and nitrate probes monitor irrigation delivery and runoff composition. EPA enforcement in the Mississippi River Basin mandates tamper-evident data logging for permit compliance.
Soil Sensors dominate installed base. Crop Sensors are climbing the fastest as hyperspectral technology migrates groundward.
Technology:
Connectivity architecture determines power budgets, telemetry range, and integration pathways with analytics platforms.
- IoT:LoRaWAN and cellular protocols transmit sensor telemetry to cloud platforms for prescriptive irrigation and fertilization directives. India's CEA rural electrification gaps constrain continuous operation in unirrigated districts, forcing battery-dependent deployments with replacement logistics challenges.
- GPS:Positioning cores enable georeferenced data collection and variable-rate application mapping. Trimble anchors its market presence through integration with guidance systems.
- Remote Sensing:Satellite and aerial imagery platforms provide field-scale crop health assessment. Ground-truthing requirements sustain demand for proximal sensor validation.
- Acoustic:Vibration and sound pattern recognition for grain storage pest detection and limited orchard pest identification pilots. Algorithm training datasets remain sparse outside controlled storage environments.
IoT commands deployment volume. Acoustic sensing holds steepest expansion trajectory pending algorithm maturation.
Application:
Use case specificity shapes sensor specification, durability requirements, and data analytics complexity.
- Irrigation Management:Soil moisture and weather data drive automated valve control and scheduling optimization. Israel's precision agriculture ecosystem narrows the gap between research-grade accuracy and field-deployable hardware reliability.
- Yield Monitoring:Mass flow sensors and GPS tagging map harvest variability across fields. OEM integration through dealer networks accelerates adoption.
- Soil Monitoring:Nutrient mapping and compaction sensing guide amendment and tillage decisions. Dielectric probe calibration drift in saline arid-zone soils degrades accuracy below specifications within eighteen months.
- Pest Management:Pheromone traps with image recognition and acoustic detection identify infestation pressure. EFSA guidelines on data integrity shape EU subsidy eligibility for precision agriculture infrastructure.
Irrigation Management leads by deployment scale. Pest Management gains share fastest as regulatory documentation requirements tighten.
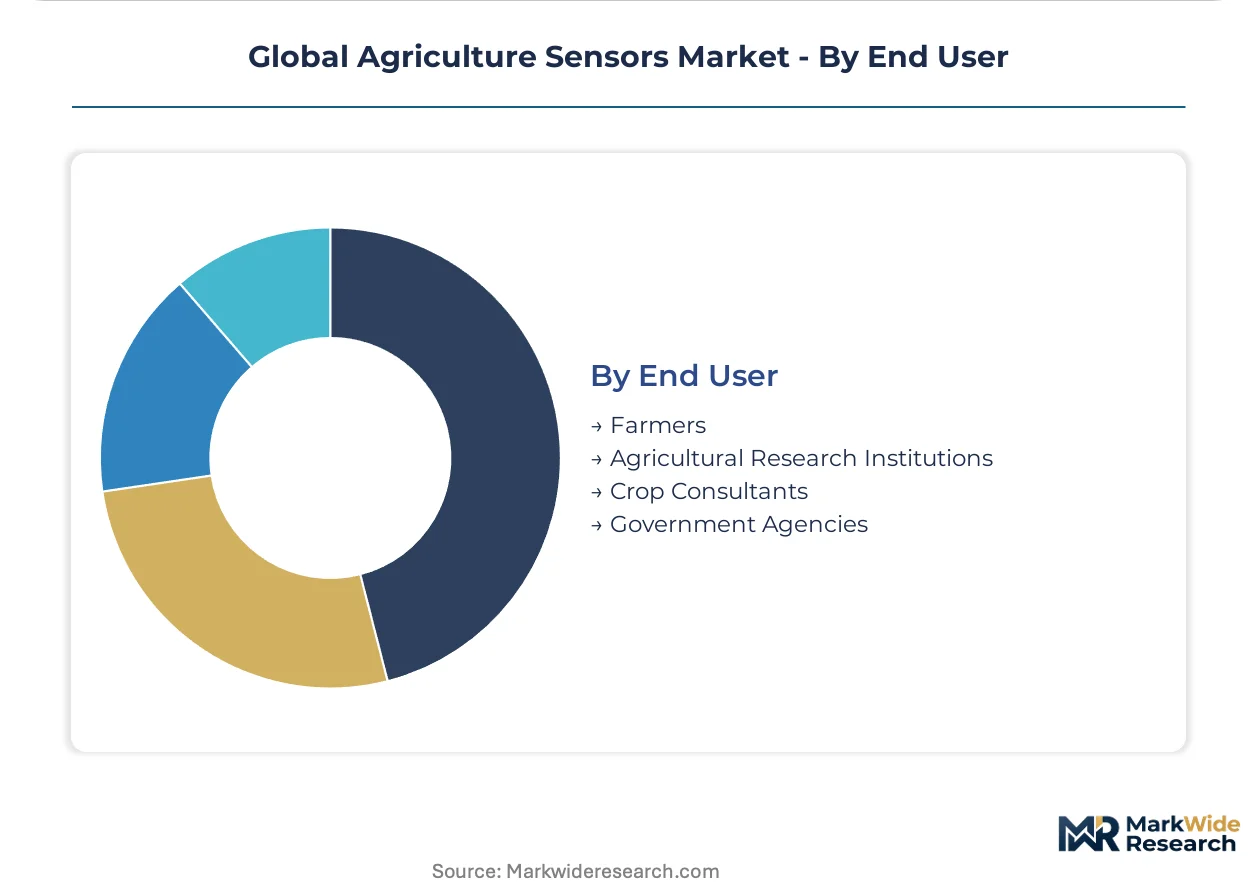
End User:
Buyer sophistication and procurement authority fragment across operational and institutional segments.
- Farmers:Owner-operators and enterprise growers purchase directly or through dealer networks. Brazilian Cerrado operators drive demand for unbundled hardware procurement with third-party platform compatibility.
- Agricultural Research Institutions:Universities and government experiment stations deploy research-grade instrumentation for cultivar trials and agronomic studies. Calibration protocols exceed commercial field standards.
- Crop Consultants:Independent advisors and cooperative extension services install sensor networks for client recommendation services. Interoperability certification reduces stranded asset risk when switching analytics providers.
- Government Agencies:Environmental regulators and agricultural ministries mandate sensor installation for compliance monitoring and subsidy verification. EU Green Deal Farm to Fork strategy compels certified data collection infrastructure.
Farmers represent the largest procurement volume. Government Agencies are expanding fastest through regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli precision agriculture clusters and Brazilian mechanized farming operations concentrate sensor hardware supply and demand respectively. The EU Green Deal's Farm to Fork strategy and India's rural electrification programs are reshaping deployment patterns across regulatory environments. Geographic diversification remains incomplete due to R&D concentration in specific innovation hubs.
United States
EPA water quality enforcement in the Mississippi River Basin mandates flow and nitrate sensor networks for permit compliance. Corn-soy operations in Iowa and Illinois absorb substantial compliance infrastructure costs. Washington State apple growers deploy ground-based hyperspectral nodes for hourly canopy monitoring, displacing weekly drone flights.
Brazil
Large-scale soybean and corn operations in the Cerrado region deploy soil moisture probes at densities exceeding North American averages. Irrigation water scarcity accelerates dielectric sensor adoption across mechanized farms. São Paulo-based dealer networks drive unbundled hardware procurement to avoid proprietary data platform lock-in.
Israel
Precision agriculture R&D clusters narrow the gap between research-grade instrumentation and field-deployable hardware reliability. The country's national agricultural research institutions collaborate with commercial sensor developers on arid-zone calibration protocols. Tel Aviv-area MEMS fabrication facilities supply accelerometer cores for livestock monitoring devices.
Germany
EU Green Deal Farm to Fork strategy mandates certified environmental compliance documentation for subsidy eligibility. EFSA guidelines on precision agriculture data integrity shape federal state-level machinery incentive programs. Bavaria's agricultural technology clusters integrate sensor feedback loops into GPS-guided variable-rate application systems.
India
CEA rural electrification standards determine power availability for sensor networks in unirrigated districts across Maharashtra and Gujarat. Battery-dependent deployments face replacement logistics challenges in grid-unreliable areas. The PLI scheme extension for electronics hardware could localize sensor assembly to reduce import dependency.
Global Agriculture Sensors Market Vendor Landscape
Agricultural equipment OEMs and specialized sensor fabricators split the market between integrated platform ecosystems and modular hardware suppliers. The vendor base organizes around three strategic archetypes: tractor-implement integrators leveraging dealer networks, precision positioning specialists anchoring GPS-guided systems, and dedicated soil science laboratories commercializing research-grade probes. Dominant competitive moves include OEM embedding of sensors into factory configurations and service unbundling that separates hardware procurement from analytics subscriptions.
Within the integrated equipment tier, Deere & Company exemplifies the OEM-embedded archetype through its dealer network distribution model. Trimble occupies a position bridging positioning technology with variable-rate application integration. METER Group, a specialized soil science laboratory, represents the research-to-commercialization pathway with its dielectric probe calibration expertise for arid-zone irrigation scheduling.
| Leading Market Players |
|---|
| CropX |
| METER Group |
| Acclima |
| Pycno |
| Sentera |
| Deere & Company |
| Trimble |
| Teralytic |
| Caipos GmbH |
| Others |
Supply Flow & Price Mechanics
Haifa-to-Rotterdam maritime corridors transmit Israeli MEMS components and Brazilian soybean belt logistics costs into downstream pricing tiers, compressing margins for dielectric probe assemblers while amplifying differentiation power for calibration-certified suppliers serving EPA-monitored watersheds.
Pricing Analysis
EU Green Deal Farm to Fork strategy dictates the pricing tier structure across the agriculture sensors landscape. Three-tier pricing structure across premium, standard, and economy levels separates research-grade hyperspectral nodes from field-calibrated dielectric probes and unbranded OEM-compatible hardware. Price differentiation hinges on EFSA data integrity certification and bundled after-sales recalibration service coverage. Pricing pressure stems from LoRaWAN module commoditization in Brazilian Cerrado procurement. Smallholder cooperatives in India's unirrigated districts exhibit highest price sensitivity; research institutions in Germany's Bavaria cluster demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Israeli MEMS foundries and supply-chain finance facilities at Tel Aviv-area fabrication hubs shape working capital structures for probe assemblers. Component concentration centers on Israel for accelerometer cores, Taiwan for LoRaWAN chipsets, and Germany for GPS positioning modules. Raw material dependencies include silicon wafers, rare-earth magnetics for MEMS, and specialized optical glass for hyperspectral lenses. Single-source vulnerability concentrates in Israeli R&D clusters for livestock-worn thermal imaging cores. Distribution runs through Deere's dealer network for OEM-embedded configurations and unbundled direct procurement for third-party platform compatibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity intensifies as service unbundling separates hardware procurement from analytics subscriptions, creating niches for specialized calibration laboratories and interoperability-certified modular suppliers.
For Market Incumbents: Harden platform stickiness through embedded OEM configurations at the factory level, leveraging dealer network density to lock in replacement cycles. Deepen backward integration into MEMS fabrication to offset Israeli supply concentration risk. Prioritize EFSA-aligned certification investments to secure EU subsidy-linked procurement streams.
For New Entrants and Emerging Players: Pursue acoustic sensing white space in orchard pest detection, where algorithm training datasets remain sparse and incumbent presence is minimal. Target India's PLI scheme extension for electronics hardware to localize assembly and bypass import duty structures. Lead with unbundled hardware-only positioning to capture Brazilian Cerrado demand for third-party platform compatibility.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized soil science laboratories with arid-zone calibration expertise over generalist IoT platform aggregators. Long-term viability rests on defensible measurement accuracy in saline soil conditions and recurring calibration revenue streams. Watch hyperspectral ground-node replacement rates in Washington State apple operations as inflection indicator for aerial-to-proximal imaging migration velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deere's dealer network embeds sensors into factory configurations, locking replacement demand. |
| Backward Integration | METER Group's captive calibration protocols defend margin position in saline-zone irrigation markets. |
| Geographic Expansion | Trimble anchors GPS-guided variable-rate systems in EU Green Deal compliance workflows. |
| Strategic Partnership | LoRaWAN protocol maturation eliminates cellular subscription costs for remote Brazilian deployments. |
| Acquisition of Specialist Firm | Hyperspectral imaging core suppliers in Israeli clusters attract consolidation to secure MEMS supply. |
Methodological Framework
A standing panel of precision agriculture technology officers, irrigation system integrators, farm equipment dealer principals, and regulatory compliance specialists provided ongoing calibration across the primary research phase. This study combined structured interviews with these stakeholders against secondary validation from EPA enforcement databases, EU Green Deal implementation reports, CEA rural electrification standards, and Brazilian agricultural ministry machinery subsidy records. Bottom-up sensor deployment tallies triangulated against top-down equipment OEM revenue segmentation.
Scenario bracketing anchored volume and value outputs across the projection horizon, with sensitivity testing around LoRaWAN adoption velocity and hyperspectral ground-node replacement rates. Segmentation dimensions modeled include product architecture, connectivity protocol, operational application, and end-user procurement authority. CAGRs derived from installed base expansion trajectories and average selling price evolution in calibration-intensive versus commodity hardware tiers. Arid-zone salinity interference patterns and EPA permit compliance mandates served as industry-specific forecast inputs.
Sensitivities concentrate around Israeli supply chain disruption, EU subsidy eligibility rule changes, and algorithm maturation timelines for acoustic pest detection. Forecasts reflect documented assumptions on telemetry reliability improvement and dealer network penetration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Agriculture Drone Software Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Crop Monitoring Market