
 Remote Fertigation Monitoring Services Market | 2026-2036
Remote Fertigation Monitoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Fertigation Monitoring Services Market Analytics
Commercial greenhouse operations is pivoting toward cloud-based fertigation oversight as labor costs rise and export certification demands tighten. Netafim leverages its drip irrigation heritage to anchor integrated monitoring-to-delivery systems across protected agriculture in Israel and Mexico. Jain Irrigation Systems sustains R&D intensity in sensor calibration for tropical humidity conditions, competing with Rivulis in Southeast Asian export vegetable production. CropX Technologies differentiates through soil-moisture-to-nutrient correlation algorithms that occupy the data analytics layer of the value chain.
Remote fertigation monitoring services combine distributed sensor networks, telemetry infrastructure, and algorithmic dosing control to automate nutrient solution delivery in pressurized irrigation systems; these platforms typically integrate electrical conductivity, pH, and flow-rate sensors with cloud-based decision support to maintain target root-zone ion concentrations. The service type dimension shows system monitoring and data analytics capturing expanding margin pools as growers shift from hardware ownership to subscription-based agronomic guidance. Cloud-based delivery models dominate new deployments among mid-scale agriculture enterprises, while on-premises installations persist where connectivity infrastructure remains unreliable.
The EPA enforces Clean Water Act discharge permits for concentrated animal feeding operations and large produce farms, pushing investment in documented nutrient application records. EFSA and REACH frameworks govern allowable fertilizer compositions entering European food production, shaping sensor calibration standards and algorithmic recommendation engines. Stakeholders must monitor how emerging carbon accounting protocols treat precision fertigation as a Scope 3 emissions reduction pathway for downstream food processors.
Market Dynamics
The EPA's Clean Water Act discharge mandates for large produce farms and California's deficit irrigation regulations are compressing adoption timelines for sensor-driven nutrient platforms, forcing capital allocation toward documented application records.
Growth Catalysts
- California Water Scarcity Mandates:Deficit irrigation regulations in the Central Valley accelerate digital fertigation adoption among almond and grape growers seeking compliance.
- EU F-Gas Regulation:Tightening discharge standards for agricultural runoff push greenhouse operators toward closed-loop monitoring systems with automated dosing.
- Cloud Telemetry Infrastructure:Expansion of LoRaWAN and cellular IoT networks in Israel's precision irrigation cluster enables real-time sensor-to-actuator communication.
Market Restraints
- Sensor Calibration Volatility:Electrical conductivity probes degrade rapidly in high-salinity conditions, requiring quarterly replacement in coastal greenhouse zones.
- Connectivity Infrastructure Gaps:Rural vineyard regions in Spain and Italy lack reliable broadband, forcing expensive on-premises server deployments.
- REACH Compliance Burden:ECHA registration requirements for fertilizer additive sensors extend procurement cycles by eight to twelve months.
Strategic Opportunities
- Southeast Asian Export Vegetable Production:Tropical humidity conditions in Vietnam and Thailand create demand for corrosion-resistant sensor housings and localized algorithm training.
- Carbon Accounting Protocols:Emerging Scope 3 emissions frameworks for downstream food processors position precision fertigation as a verifiable reduction pathway.
- Subscription Agronomic Guidance:Mid-scale agriculture enterprises in Mexico's protected agriculture sector shift from hardware ownership to recurring service models.
Industry Challenges
- Interoperability with Legacy Irrigation Infrastructure:Pressurized drip systems from prior decades lack standardized data protocols, complicating sensor integration.
- Specialized Technician Shortage:Calibration of pH and EC sensors requires agronomic chemistry expertise scarce in remote farming regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Fertigation Monitoring Services Market |
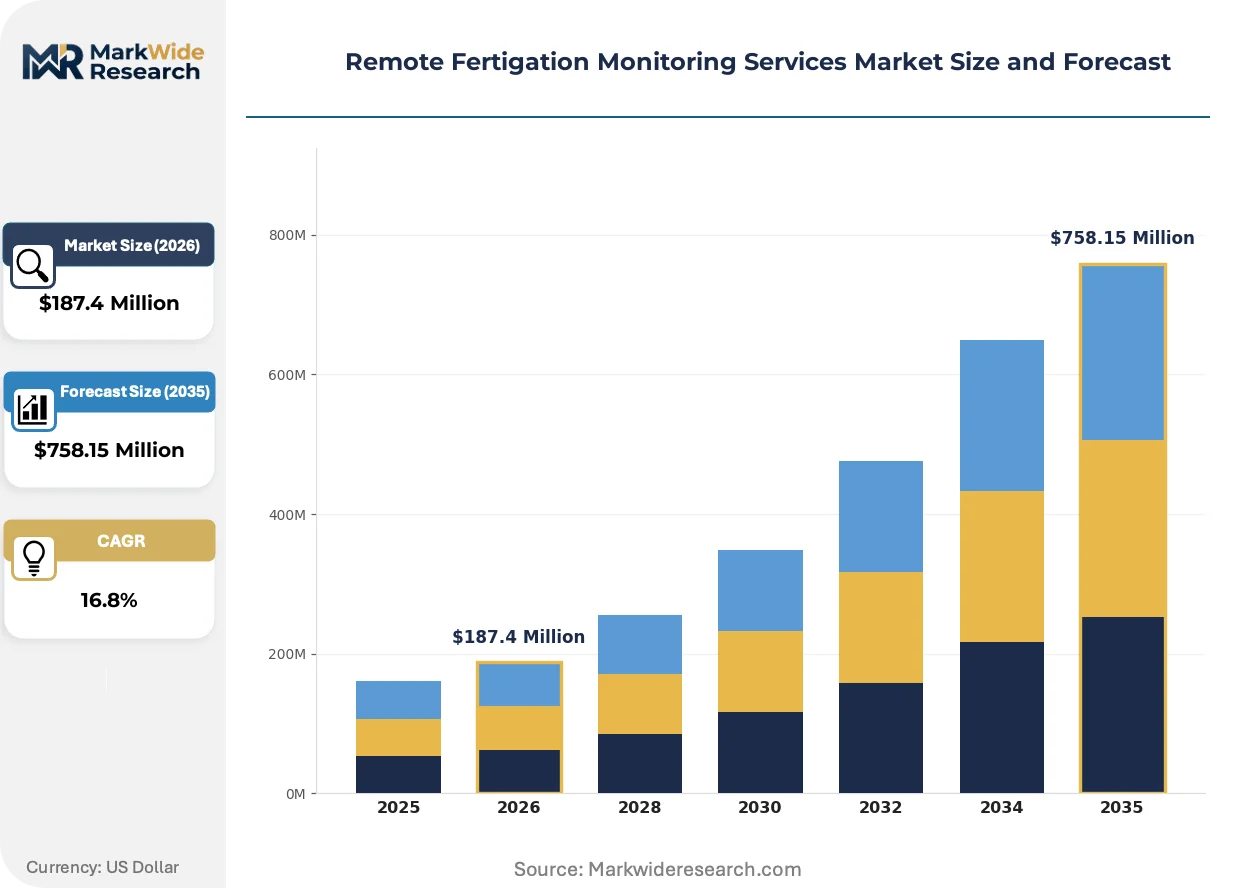
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Water Management, Nutrient Delivery, System Monitoring, Data Analytics Delivery Model: Cloud-Based, On-Premises, Hybrid, Mobile Application End User: Farmers, Agriculture Enterprises, Research Institutions, Nursery Operators Technology: Irrigation Systems, Sensors, IoT Devices, AI Algorithms |
| Companies Covered | Netafim, Jain Irrigation Systems, CropX Technologies, TIMAC AGRO International, SGS, Rivulis, The Toro Company, Valmont Industries, Lindsay Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Fertigation Monitoring Services Market Evolving Landscape
Edge computing architectures and machine learning inference at the sensor level are compressing latency in nutrient dosing decisions, reshaping how greenhouse operators balance automation precision against infrastructure costs.
LoRaWAN-enabled soil-moisture-to-nutrient correlation algorithms are decentralizing decision authority from centralized cloud platforms to field-level gateways. Commercial greenhouse operators in the Netherlands and Belgium are deploying these systems at three-year replacement cycles. This architecture is decentralizing data ownership patterns, allowing growers to retain sensitive yield metrics locally while still accessing predictive analytics.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon-based cooling in controlled-environment agriculture is tightening thermal management requirements for sensor electronics. Greenhouse operators must now specify fertigation monitoring hardware rated for elevated ambient temperatures without active cooling. Protected agriculture facilities in Spain and Italy are responding by sourcing IP67-rated sensor housings with passive heat dissipation designs.
Buyer concentration among supermarket chains and export cooperatives is compressing switching cycles for fertigation service providers. Vineyard managers in France's Champagne region now demand API-accessible nutrient application logs for blockchain traceability compliance. This pattern is most visible in Israel and the Netherlands, where integrated packer-processor networks enforce uniform data standards across supplier tiers.
Remote Fertigation Monitoring Services Market Segmentation
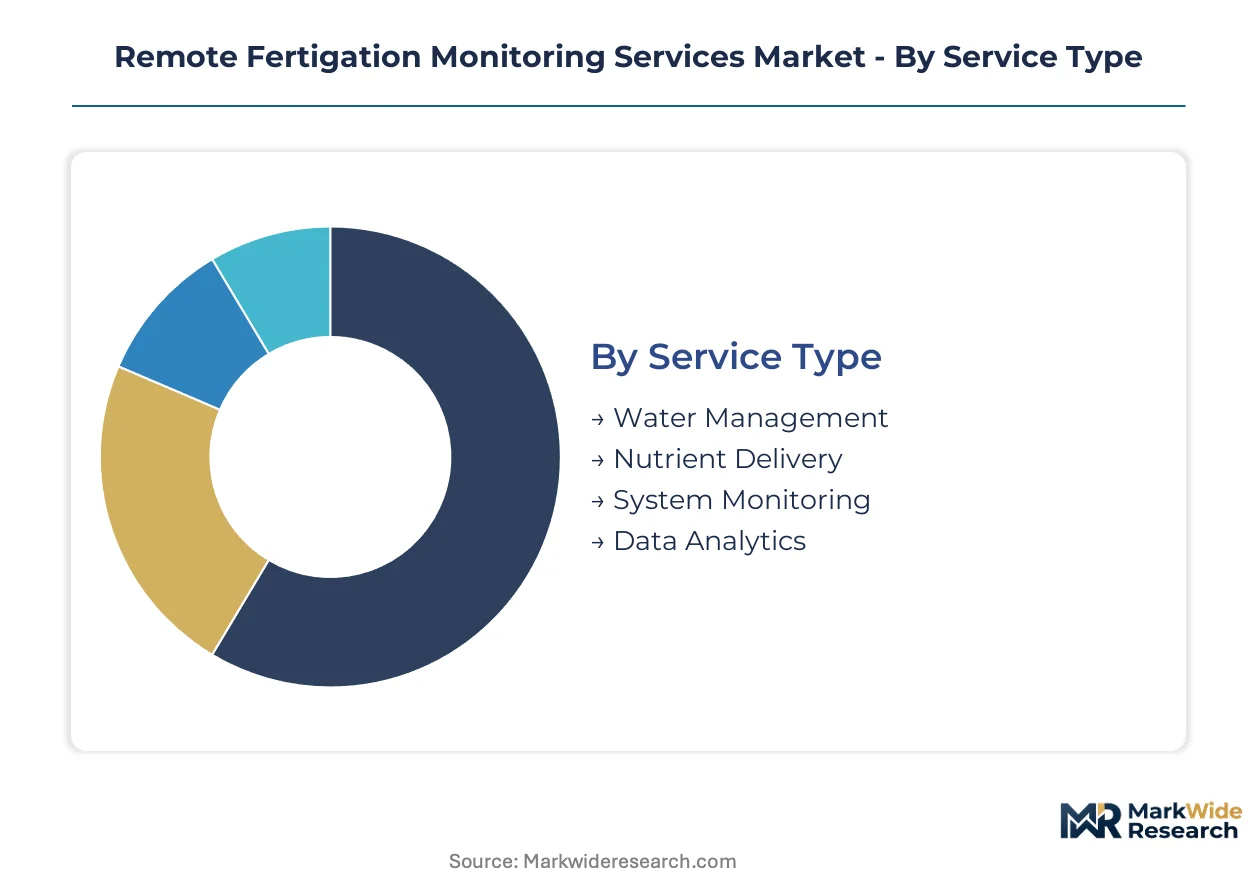
Remote fertigation monitoring services fragment across service architecture, deployment infrastructure, customer scale, and sensing technology. Each dimension carries distinct margin profiles and integration requirements that shape vendor positioning and capital allocation decisions.
Service Type:
Standalone monitoring modules operate independently from dosing hardware, while embedded services integrate directly with valve actuators and pump controllers.
- System Monitoring:Real-time telemetry of pressure differentials, flow rates, and filter status across pressurized distribution networks. California almond growers under deficit irrigation mandates deploy these services to document compliance and trigger automated shutdown sequences during supply interruptions.
- Data Analytics:Correlation engines that translate sensor streams into nutrient prescription maps and yield forecasts. Israel's precision irrigation cluster drives concentrated demand here as export-oriented cooperatives seek predictive optimization for premium crop grades.
- Water Management:Services tracking source allocation, drainage recycling, and discharge quality against regulatory thresholds.
- Nutrient Delivery:Dosing automation and stock solution management for closed-loop hydroponic and substrate systems.
Volume placements concentrate in System Monitoring; the faster expansion belongs to Data Analytics.
Delivery Model:
Cost tiering separates enterprise-grade infrastructure from accessible entry points, with hybrid architectures capturing mid-scale operators seeking staged migration paths.
- Cloud-Based:Subscription telemetry platforms with browser dashboards and API access for third-party farm management software. Mexico's protected agriculture sector and Vietnam's export vegetable zones favor this model for minimal on-site hardware and rapid scaling across dispersed plots.
- Hybrid:Local edge gateways buffering sensor data with periodic cloud synchronization, balancing latency-sensitive dosing decisions against analytics depth. Spain's greenhouse belt adopts these configurations where broadband reliability fluctuates seasonally.
- On-Premises:Dedicated server installations with full data sovereignty for operations handling sensitive variety development or proprietary cultivation protocols.
- Mobile Application:Smartphone-centric interfaces with simplified alerting and manual override capabilities for smaller nursery operators and technician field crews.
Cloud-Based deployments hold the dominant share; Hybrid configurations are climbing the fastest as connectivity infrastructure matures in secondary agricultural regions.
End User:
Customer scale determines service complexity, with procurement authority consolidating among integrated enterprises while research institutions drive specification innovation.
- Agriculture Enterprises:Large-scale operators managing multi-site portfolios with centralized agronomic teams. These buyers negotiate enterprise service agreements spanning sensor maintenance, algorithm retraining, and regulatory documentation across California's Central Valley and Israel's coastal plain.
- Research Institutions:Universities and government experiment stations calibrating sensor algorithms against controlled trials. Their procurement shapes industry standards for pH and electrical conductivity accuracy in saline conditions.
- Farmers:Individual owner-operators adopting monitored fertigation through cooperative purchasing or equipment-leasing arrangements.
- Nursery Operators:Specialized propagation facilities requiring precise EC control for delicate rooting environments and pathogen suppression.
Agriculture Enterprises anchor current revenue; Research Institutions are gaining share fastest as public-private partnerships accelerate algorithm validation.
Technology:
Technology maturity stratifies between proven mechanical systems and emerging inference layers, with integration depth determining data utility.
- Sensors:Distributed measurement nodes for electrical conductivity, pH, temperature, and dissolved oxygen. Ion-selective electrodes with solid-state reference systems dominate new deployments in Thailand's tropical humidity, where traditional glass junctions degrade rapidly.
- AI Algorithms:Machine learning models predicting nutrient uptake curves and detecting irrigation anomalies from multi-sensor fusion. The Netherlands' greenhouse automation sector leads commercial deployment, training models on decades of substrate-grown tomato and pepper data.
- Irrigation Systems:Physical infrastructure of pumps, filters, valves, and distribution laterals that monitoring services overlay.
- IoT Devices:LoRaWAN and cellular telemetry modules enabling wireless sensor networks across expansive vineyard and orchard geometries.
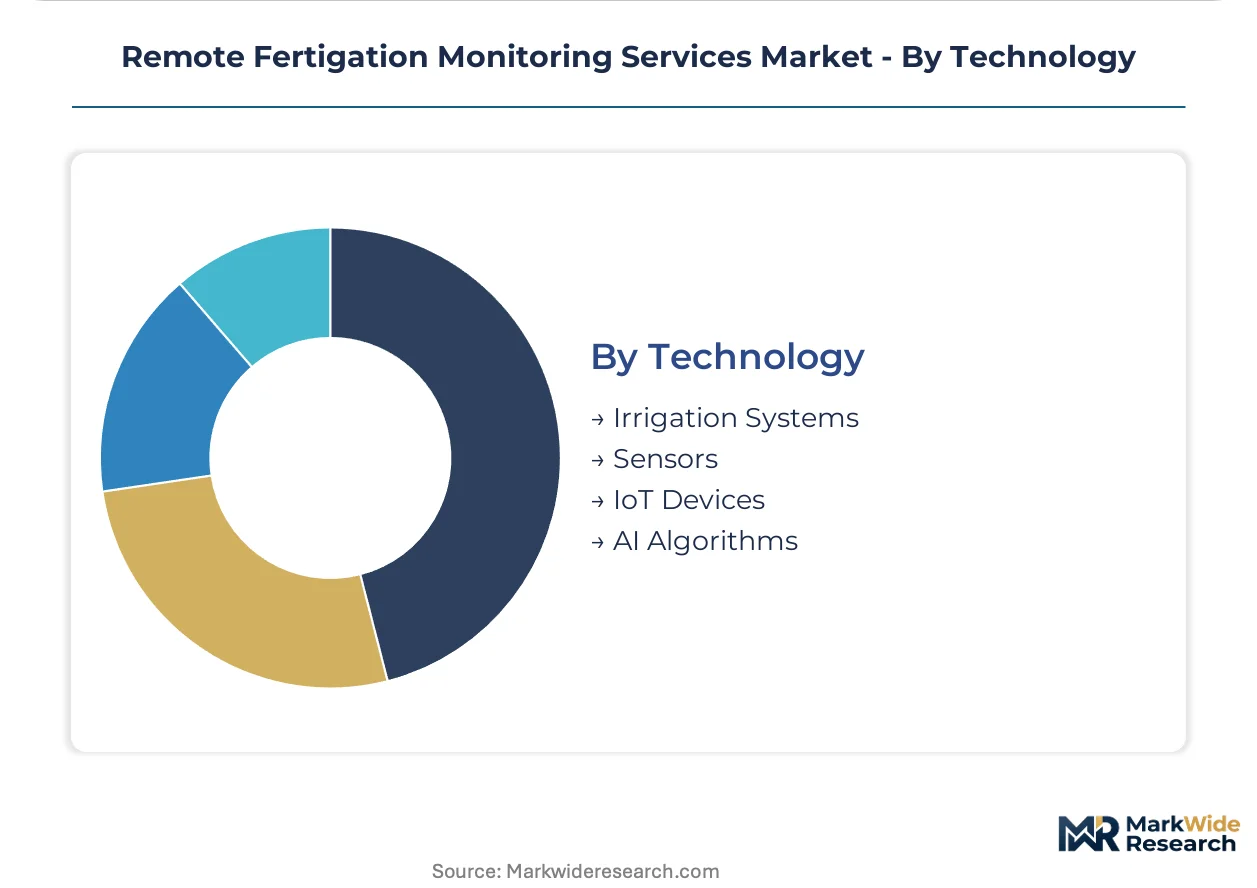
Sensor hardware captures the dominant placement volume; AI Algorithms show the steepest expansion trajectory as inference costs decline and training datasets accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's AgriTech incubation zones and California's agricultural technology tax credits concentrate venture deployment for sensor-to-cloud fertigation platforms. Government-backed irrigation efficiency programs in both jurisdictions accelerate commercial validation timelines for remote monitoring services.
United States
California's Central Valley deficit irrigation mandates force almond and grape growers toward documented nutrient application systems. The EPA enforces Clean Water Act discharge permits for large produce farms, pushing investment in automated dosing records. Fresno and Kern counties host dense clusters of precision agriculture service providers integrating telemetry with existing pressurized drip infrastructure.
Israel
Export-oriented cooperatives along the coastal plain demand predictive optimization for premium crop grades in peppers and tomatoes. National water authority regulations enforce closed-loop irrigation with real-time discharge monitoring. Netafim anchors an integrated monitoring-to-delivery ecosystem across protected agriculture in the Negev Desert and Jordan Valley.
Netherlands
Greenhouse automation in Westland and Aalsmeer drives commercial deployment of machine learning models trained on decades of substrate-grown tomato data. The EU F-Gas Regulation tightens thermal management requirements for sensor electronics in controlled-environment agriculture. Wageningen University partnerships accelerate algorithm validation for nutrient uptake curve prediction.
Spain
Almería's greenhouse belt adopts hybrid cloud-edge configurations where broadband reliability fluctuates seasonally. REACH compliance through ECHA extends procurement cycles for fertilizer additive sensors by eight to twelve months. Valencia and Murcia regions source IP67-rated sensor housings with passive heat dissipation for elevated ambient temperatures.
Mexico
Protected agriculture in Sinaloa and Baja California shifts from hardware ownership to subscription-based agronomic guidance. Water scarcity in northern states accelerates digital fertigation adoption among berry and tomato exporters. Guanajuato's precision irrigation cluster hosts rapid scaling of LoRaWAN-enabled sensor networks across dispersed smallholder plots.
Remote Fertigation Monitoring Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated irrigation heritage players commanding premium positioning in system monitoring while data analytics specialists capture expanding margin pools. The vendor base stratifies into three tiers: full-stack platform providers, sensor hardware specialists, and pure-play algorithm developers. Consolidation pressure intensifies as supermarket chains demand API-accessible nutrient logs for blockchain traceability. Dominant competitive moves include strategic partnerships between telemetry infrastructure providers and farm management software platforms, plus backward integration into sensor calibration services.
Specialists in precision irrigation hardware anchor the integrated platform tier, with Netafim leveraging its drip irrigation heritage and Jain Irrigation Systems sustaining R&D intensity in tropical humidity conditions. Rivulis occupies a position competing for Southeast Asian export vegetable production. CropX Technologies exemplifies the data analytics archetype, correlating soil moisture with nutrient demand through cloud-based algorithms that integrate with third-party farm management systems.
| Leading Market Players |
|---|
| Netafim |
| Jain Irrigation Systems |
| CropX Technologies |
| TIMAC AGRO International |
| SGS |
| Rivulis |
| The Toro Company |
| Valmont Industries |
| Lindsay Corporation |
| Others |
Value Network & Pricing Analysis
Sensor module costs from semiconductor foundries in Taiwan and South Korea cascade through three pricing tiers downstream, with cloud-subscription platforms commanding premiums over on-premises installations as California almond growers and Israeli greenhouse operators absorb connectivity infrastructure markups.
Pricing Analysis
Expedited delivery premiums compress margins for standard-tier hardware as European greenhouse operators under EU F-Gas thermal mandates pay 15-20% uplifts for IP67-rated sensor housings with passive heat dissipation. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade algorithm retraining bundles from basic telemetry subscriptions. Cost compression in the economy tier intensifies because contract manufacturers in Mexico and Vietnam replicate LoRaWAN module designs without calibration services. Mid-scale protected agriculture enterprises in Southeast Asia exhibit highest price sensitivity; research institutions in the Netherlands show lowest sensitivity due to grant-funded procurement cycles.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Netafim and Jain Irrigation Systems, while value-added distributors serve smaller nursery operators requiring localized technical support. Component sourcing concentrates in Taiwan for microcontroller units, Germany for precision pH electrodes, and Israel for telemetry firmware development. Ion-selective electrode membranes and solid-state reference systems draw from specialized chemical suppliers in Switzerland and Japan. Single-source vulnerability runs through Taiwan semiconductor foundries producing edge-computing chipsets for field-level gateways. Distribution runs through agricultural equipment dealerships in California's Central Valley and dedicated AgriTech integrators in Israel's coastal plain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based algorithmic dosing platforms are displacing legacy timer-based fertigation controllers across commercial greenhouse operations, with machine learning inference at the sensor level now enabling sub-minute nutrient adjustments previously impossible with centralized SCADA architectures.
For Market Incumbents: Deploy backward integration into ion-selective electrode manufacturing to secure supply continuity against Taiwan semiconductor bottlenecks. Netafim and Jain Irrigation Systems should consolidate sensor calibration service networks in Southeast Asia before Rivulis captures tropical humidity algorithm training datasets. Defensive patent filings around soil-moisture-to-nutrient correlation methods will raise barriers for pure-play data analytics entrants.
For New Entrants and Emerging Players: API-first integration partnerships with farm management software platforms offer the lowest-friction customer acquisition path. White-space concentration sits in Mexico's dispersed smallholder berry plots lacking LoRaWAN coverage, where mobile-application-centric models bypass infrastructure gaps. Target vineyard managers in Spain's Rioja and Italy's Tuscany regions demanding blockchain-traceable nutrient logs for supermarket chain compliance.
For Investors and Strategic Acquirers: ECHA registration completion for fertilizer additive sensors is the leading indicator that a hardware vendor has cleared eight-to-twelve-month procurement barriers for European greenhouse penetration. Long-term viability hinges on recurring service revenue ratios exceeding 60% of total bookings, separating platform stickiness from transactional hardware cycles. Acquisition target archetype: hybrid cloud-edge specialists with proven deployments in broadband-constrained agricultural regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Calibration Services | Captive control over pH electrode quality reduces replacement frequency in high-salinity coastal zones. |
| API-First Platform Integration | Direct connectivity with John Deere Operations Center and Climate FieldView expands addressable grower base. |
| Geographic Expansion into Southeast Asian Export Vegetable Zones | Corrosion-resistant housing designs for Vietnam and Thailand humidity conditions capture premium positioning. |
| Strategic Partnership with LoRaWAN Infrastructure Providers | Guaranteed telemetry bandwidth in Israel's Negev Desert and Mexico's Sinaloa valleys ensures real-time dosing reliability. |
| Acquisition of Specialist AI Algorithm Developers | Nutrient uptake prediction models trained on Dutch tomato substrate data accelerate commercial deployment timelines. |
Research Methodology
Independent corroboration across greenhouse operator interviews, precision irrigation system engineers, and agricultural cooperative agronomists underwrites the qualitative findings. Primary fieldwork engaged irrigation infrastructure procurement managers at California almond processing cooperatives, sensor calibration technicians in Israel's Central Arava Research and Development Center, and export compliance officers at Dutch vegetable packing stations. Secondary validation drew from EPA Clean Water Act discharge permit databases, ECHA REACH registration filings for fertilizer additive sensors, and LoRaWAN Alliance deployment maps across agricultural regions. Bottom-up sensor shipment tallies and top-down fertigation service revenue estimates were cross-referenced for triangulation.
Rate-of-change decomposition separated hardware replacement cycles from subscription revenue expansion across the projection horizon. Segmentation dimensions modeled include service architecture type, deployment infrastructure tier, customer scale category, and sensing technology maturity. CAGRs were derived from fitted growth curves applied to documented adoption timelines in deficit irrigation regulatory zones. Industry-specific forecast inputs incorporated California State Water Resources Control Board mandate compliance deadlines and EU F-Gas Regulation phase-down schedules for controlled-environment agriculture cooling systems.
The model holds under stable semiconductor supply conditions and sustained LoRaWAN network buildouts; deviation in Taiwan foundry capacity allocation or cellular IoT spectrum licensing delays would shift hardware availability timelines. Forecasts reflect assumptions regarding regulatory enforcement consistency and cloud infrastructure reliability in secondary agricultural regions. Periodic stress-testing of base assumptions is recommended against emerging carbon accounting protocol definitions for Scope 3 emissions reduction verification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
North America Precision Agriculture Market