
 Asia-Pacific Agricultural Shredder Machine Market | 2026-2036
Asia-Pacific Agricultural Shredder Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Shredder Machine Market Analytics
CE marking under the EU machinery directive is bifurcating export-ready manufacturers from domestic-only suppliers across the Asia-Pacific Agricultural Shredder Machine landscape. Kubota Corporation leverages its Japanese manufacturing scale to supply heavy-duty shredders to Australian broadacre farms. Mahindra & Mahindra Limited anchors its position through deep distribution networks across India's cooperative sector. Changzhou Dongfeng Agricultural Machinery Group Co., Ltd competes on cost-optimized diesel platforms for Southeast Asian smallholders.
An agricultural shredder machine mechanically reduces crop residue, branches, and organic waste through rotating blades or hammers, typically processing material from two to twenty centimeters in diameter depending on power rating. These machines convert field waste into mulch or compost feedstock, directly supporting soil carbon retention and reducing open-burning emissions. Heavy-duty shredders dominate revenue pools where Australian and Japanese buyers prioritize throughput and durability, while mini shredders represent the fastest-expanding category among Vietnam and Indonesia's smallholder mechanization programs. Electric power sources are gaining share in South Korea and Japan's grid-connected farming zones, though diesel still occupies the volume lead across India's hinterland.
India's BIS certification mandates safety and performance benchmarks for agricultural machinery sold domestically, while Australia's WorkSafe regulations govern operator protection standards for imported equipment. China's MIIT enforces efficiency labeling under national GB standards that constrain diesel engine eligibility for subsidy programs. Japan's METI coordinates agricultural mechanization roadmaps that prioritize electrification and precision residue management. Stakeholders must monitor how India's PLI scheme revisions and Australia's evolving biosecurity protocols for imported farm equipment reshape supplier qualification requirements and regional sourcing patterns.
Market Dynamics
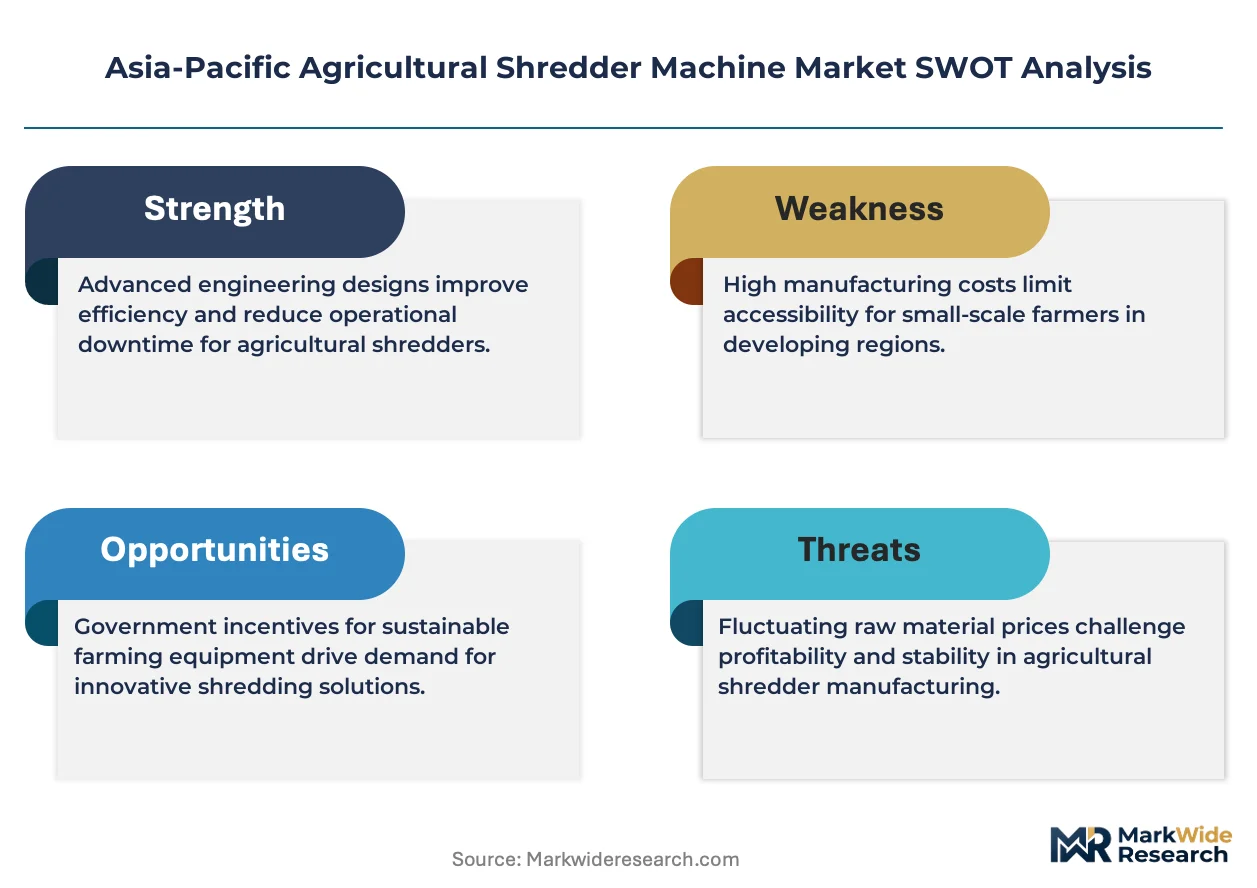
India's PLI scheme revisions and China's dual carbon goals are compressing diesel equipment margins while accelerating electric and solar-powered shredder procurement across cooperative and state-backed channels.
Growth Catalysts
- Subsidy Realignment:India's PLI scheme for farm machinery redirects procurement toward electric platforms, with state agricultural departments mandating efficiency benchmarks for cooperative tenders.
- Carbon Mandates:China's dual carbon goals constrain diesel engine eligibility for national subsidy programs, forcing manufacturers to accelerate electrification roadmaps for residue processing equipment.
- Smallholder Mechanization:Vietnam's Mekong Delta cooperative programs expand mini-shredder distribution through provincial extension services, targeting rice straw management compliance.
Market Restraints
- Battery Cost Volatility:Lithium-ion pack prices fluctuate with raw material sourcing constraints, compressing margins on electric shredder platforms priced for Southeast Asian smallholders.
- Import Dependency:Precision gearboxes and hydraulic systems concentrate in Japanese and German supplier bases, exposing Australian and Indian assemblers to lead-time volatility.
- Grid Connectivity Gaps:India's hinterland electrification deficits limit electric shredder deployment to grid-connected farming zones, preserving diesel dominance in Bihar and eastern Uttar Pradesh.
Strategic Opportunities
- Indonesia's Palm Residue Segment:Underpenetrated processing capacity across Sumatra and Kalimantan plantation belts creates white space for heavy-duty shredder deployment in biomass feedstock preparation.
- Solar-Hybrid Platforms:Convergence of photovoltaic arrays with battery storage enables off-grid electric shredder operation in Australia's remote wheat-growing regions beyond transmission infrastructure.
- Digital Procurement Channels:State agricultural e-marketplaces in India and Vietnam displace traditional dealer networks, enabling direct manufacturer-to-cooperative contracting with transparent specification benchmarking.
Industry Challenges
- Skilled Technician Scarcity:Hydraulic system diagnostics and electric drivetrain maintenance require training programs that rural service networks across India's Punjab-Haryana belt lack.
- Certification Timeline Compression:India's BIS safety certification and Australia's WorkSafe operator protection approvals impose sequential testing protocols that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Shredder Machine Market |
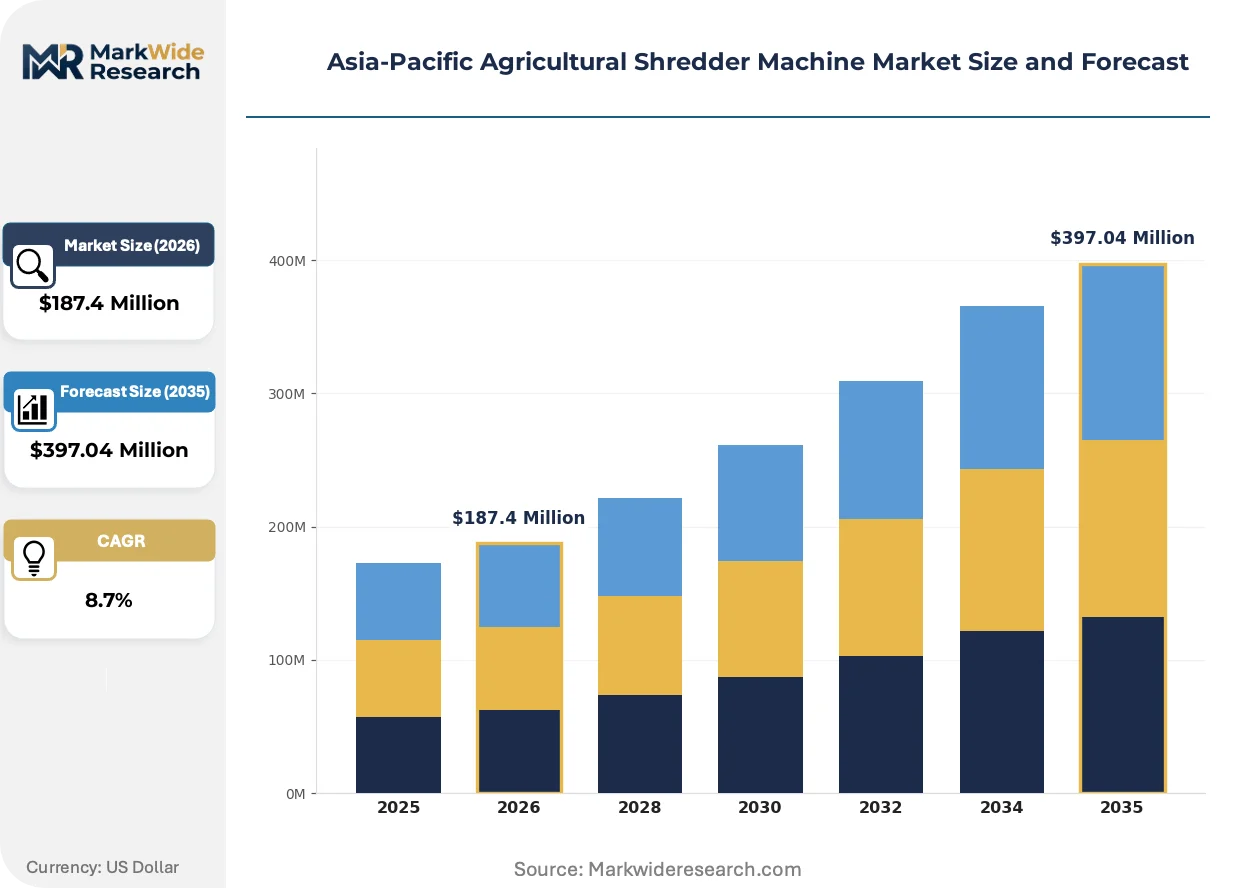
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Shredder, Vertical Shredder, Mini Shredder, Heavy-Duty Shredder End User: Farmers, Agricultural Cooperatives, Landscaping Companies, Government Agencies Application: Crop Residue Management, Waste Reduction, Soil Improvement, Mulching Power Source: Electric, Diesel, Gasoline, Solar |
| Companies Covered | Kubota Corporation, Mahindra & Mahindra Limited, Changzhou Dongfeng Agricultural Machinery Group Co., Ltd, Daedong Industrial Co., Ltd, Iseki & Co., Ltd., GEP Ecotech Co., Ltd., Genox Recycling Tech Co., Ltd., Zhangjiagang Lianda Machinery Co., Ltd., Zhengzhou T-king Machinery Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Shredder Machine Market Evolving Landscape
Electrification architectures and precision residue management protocols are restructuring competitive advantage across Asia-Pacific agricultural shredder supply chains.
Brushless DC drivetrains with integrated power electronics are bifurcating the product landscape between premium grid-connected units and cost-optimized hybrid platforms. South Korean and Japanese broadacre operators adopt these systems for variable-speed torque control during high-moisture residue processing. The technology is bifurcating supplier tiers, separating integrated motor-controller manufacturers from legacy gearbox-assemblers.
China's MIIT efficiency labeling under national GB standards now constrains diesel engine power ratings eligible for provincial subsidy programs. This regulatory tightening forces Southeast Asian exporters to reconfigure supply chains toward electric platforms or forfeit state procurement channels. Indian and Vietnamese buyers increasingly specify GB-compliant efficiency tiers in tender documentation.
Cooperative procurement collectives across India's Punjab-Haryana belt consolidate purchasing power through state agricultural marketing federations. These aggregators unbundle after-sales service contracts from equipment supply, forcing manufacturers to establish captive service networks or forfeit tender participation. The behavioral shift concentrates volume with suppliers offering multi-year service level agreements.
Asia-Pacific Agricultural Shredder Machine Market Segmentation
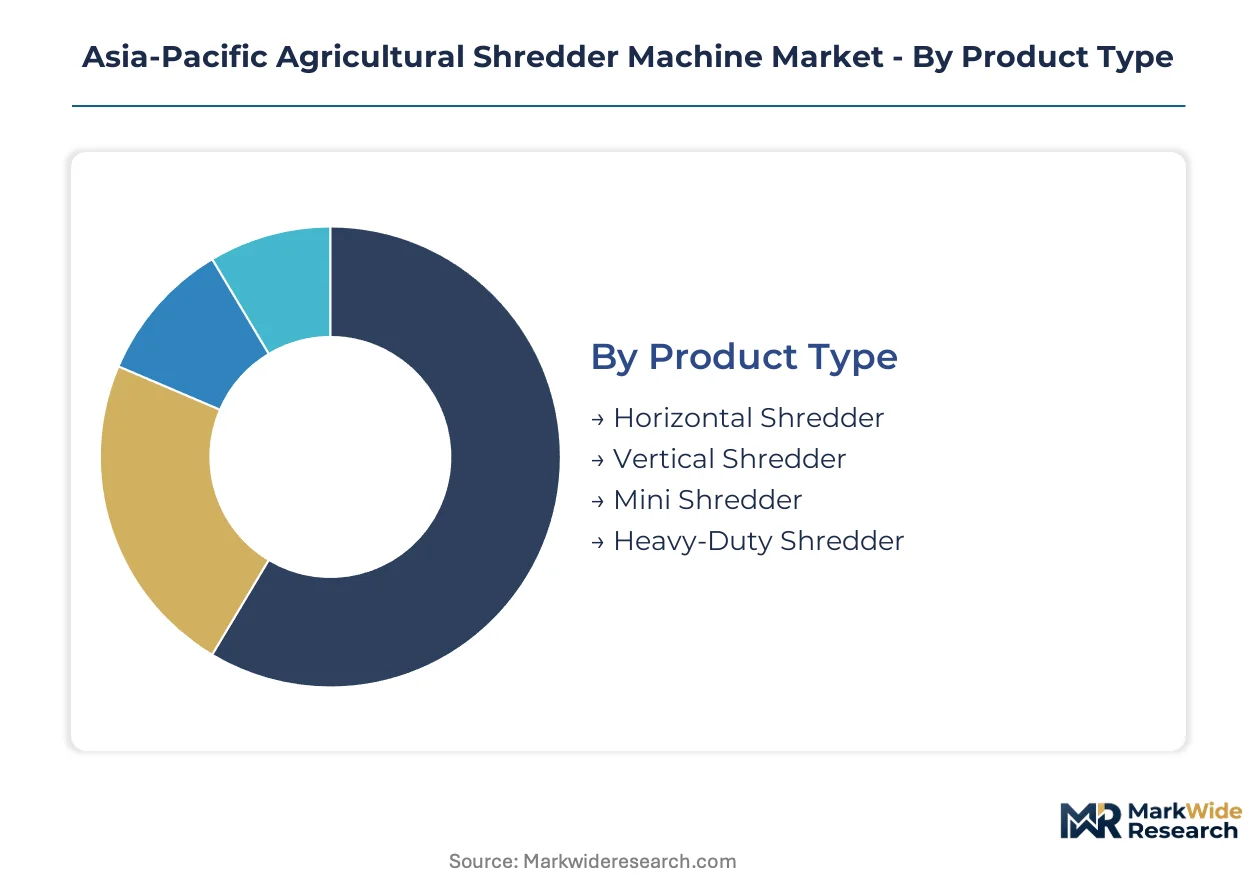
Segmentation reveals how procurement channels and power configurations fragment demand across Asia-Pacific's diverse farming economies. Understanding these divisions exposes where subsidy flows, cooperative purchasing power, and electrification roadmaps reshape supplier positioning.
Product Type:
Channel-mix dynamics concentrate heavy-duty units through Australian broadacre dealers and government tender channels, while mini shredders flow through Vietnam's provincial extension services and Indonesian plantation supply networks.
- Heavy-Duty Shredder:These machines process material up to twenty centimeters in diameter through reinforced hammer mills and dual-rotor configurations. Australian wheat-growing regions and Japanese broadacre operations prioritize throughput durability, routing procurement through Kubota's dealer network and state-backed equipment tenders. China's MIIT efficiency labeling constrains diesel variants from national subsidy eligibility.
- Mini Shredder:Compact units with sub-10 horsepower ratings target smallholder residue processing. Vietnam's Mekong Delta cooperative programs and Indonesia's rice-straw compliance initiatives drive fastest expansion through provincial agricultural extension channels. Electric variants gain share in South Korea's grid-connected zones.
- Horizontal Shredder:Side-feed drum designs suit continuous operation in palm oil plantations across Sumatra and Kalimantan. These units flow through plantation group procurement offices rather than retail channels.
- Vertical Shredder:Gravity-fed hopper configurations dominate India's Punjab-Haryana belt for wheat and rice straw processing. Mahindra's cooperative sector distribution anchors volume here.
By volume, heavy-duty units lead. By growth pace, mini shredders are climbing the fastest.
End User:
Cost-tier stratification separates premium service-contract buyers from price-sensitive cash purchasers across the procurement landscape.
- Agricultural Cooperatives:Consolidated purchasing through India's state agricultural marketing federations and Vietnam's provincial unions unbundles equipment supply from after-sales service. These buyers mandate multi-year service level agreements, concentrating volume with captive-network suppliers. China's dual carbon goals redirect cooperative tenders toward electric platforms.
- Farmers:Individual smallholders across India's Bihar and eastern Uttar Pradesh prioritize diesel affordability over electrification, constrained by grid connectivity gaps. Financing through microcredit channels shapes procurement timing.
- Government Agencies:Australia's biosecurity protocols and India's PLI scheme revisions impose certification timelines that filter supplier participation in state tender programs.
- Landscaping Companies:Urban and peri-urban operators in Japan and South Korea specify brushless DC drivetrains for noise-sensitive environments, purchasing through specialized equipment distributors.
Cooperatives dominate absolute volume. Government agencies are expanding most quickly as subsidy realignment accelerates.
Application:
Volume concentration tracks compliance mandates and soil carbon incentives across distinct agricultural zones.
- Crop Residue Management:Regulatory bans on open burning across India's northern states and Vietnam's Mekong Delta mandate mechanical processing. Australia's carbon farming initiatives reward residue retention, driving heavy-duty shredder deployment in wheat belts. China's dual carbon goals amplify state procurement for straw-to-biomass programs.
- Soil Improvement:Mulch incorporation for moisture retention and carbon sequestration concentrates demand in Australia's broadacre regions and Japan's precision farming zones. Outcome-based soil health metrics reshape equipment specifications.
- Mulching:Orchard and vineyard applications in South Korea and Japan's fruit-growing regions specify fine particle size output, requiring screen-equipped shredder configurations.
- Waste Reduction:Plantation biomass preparation across Indonesia's palm oil sector creates demand for high-throughput residue processing ahead of pelletization or composting.
Residue management commands the largest installed base. Soil improvement applications are gaining share fastest as carbon incentives mature.
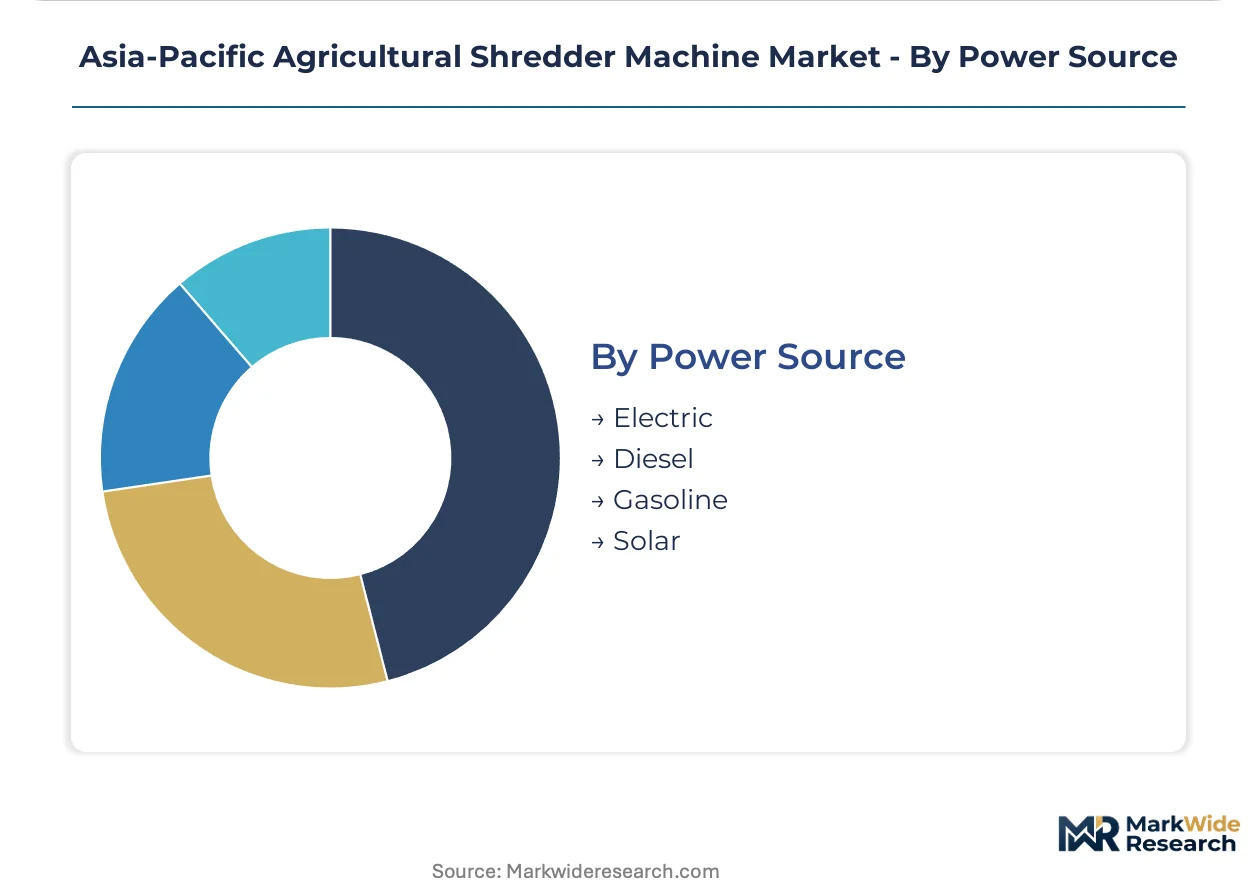
Power Source:
Supply concentration in battery and precision drivetrain components exposes margin compression risks across electrification transitions.
- Electric:Brushless DC architectures with integrated power electronics dominate South Korea and Japan's grid-connected farming zones. Battery cost volatility from lithium-ion raw material constraints compresses margins on units priced for Southeast Asian smallholders. India's PLI scheme redirects cooperative procurement toward electric platforms.
- Diesel:Cost-optimized engines from Changzhou Dongfeng Agricultural Machinery Group supply India's hinterland and Southeast Asian smallholders. China's MIIT efficiency labeling and GB standards constrain eligibility for provincial subsidy programs, shrinking addressable market share.
- Solar:Photovoltaic-battery hybrid configurations enable off-grid operation in Australia's remote wheat-growing regions beyond transmission infrastructure. High capital costs limit penetration to grant-funded demonstration projects.
- Gasoline:Portable units serve landscaping contractors and peri-urban smallholders in Indonesia and the Philippines where grid reliability and diesel supply chains remain uneven.
Diesel retains volume leadership. Electric platforms show the steepest expansion trajectory as subsidy alignment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for farm machinery and China's dual carbon goals redirect procurement toward electric and solar-powered shredders across Asia-Pacific cooperative and state-backed channels.
India
Punjab-Haryana belt cooperatives consolidate purchasing through state agricultural marketing federations. BIS certification mandates safety and performance benchmarks for domestic machinery sales. Eastern Uttar Pradesh and Bihar retain diesel dominance due to grid connectivity gaps limiting electric deployment.
China
MIIT efficiency labeling under national GB standards constrains diesel engine eligibility for provincial subsidy programs. Dual carbon goals accelerate state procurement for straw-to-biomass processing equipment. Shandong Peninsula manufacturers reconfigure supply chains toward electrification to retain government tender access.
Japan
METI coordinates agricultural mechanization roadmaps prioritizing precision residue management and electrification. Brushless DC drivetrains with integrated power electronics penetrate Kanto and Kansai grid-connected farming zones. Nagoya-area equipment distributors specify variable-speed torque control for high-moisture processing.
Australia
WorkSafe regulations govern operator protection standards for imported farm equipment entering broadacre wheat-growing regions. Carbon farming initiatives reward residue retention, driving heavy-duty shredder deployment. Remote Western Australian operations test solar-hybrid platforms beyond transmission infrastructure.
Vietnam
Mekong Delta cooperative programs expand mini-shredder distribution through provincial extension services targeting rice straw management compliance. State agricultural e-marketplaces displace traditional dealer networks. Ho Chi Minh City-based procurement offices consolidate tender specifications toward GB-compliant efficiency tiers.
Asia-Pacific Agricultural Shredder Machine Market Competitive Landscape
Player mix skews toward diversified agricultural machinery conglomerates with captive distribution networks. Structure concentrates around three tiers: premium integrated manufacturers, cost-optimized diesel assemblers, and specialized recycling technology firms. Strategic moves center on electrification roadmaps and multi-year service level agreements unbundled from equipment supply.
Among Japanese diversified manufacturers, Kubota Corporation and Iseki & Co., Ltd. occupy positions exemplifying premium-tier integrated production. Mahindra & Mahindra Limited anchors the India-centric archetype through cooperative sector penetration. Chinese fabricators including Changzhou Dongfeng Agricultural Machinery Group Co., Ltd. and Zhangjiagang Lianda Machinery Co., Ltd. represent cost-optimized diesel platform specialization for Southeast Asian smallholders. Daedong Industrial Co., Ltd. sits within the Korean machinery exporter tier.
| Leading Market Players |
|---|
| Kubota Corporation |
| Mahindra & Mahindra Limited |
| Changzhou Dongfeng Agricultural Machinery Group Co., Ltd |
| Daedong Industrial Co., Ltd |
| Iseki & Co., Ltd. |
| GEP Ecotech Co., Ltd. |
| Genox Recycling Tech Co., Ltd. |
| Zhangjiagang Lianda Machinery Co., Ltd. |
| Zhengzhou T-king Machinery Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Brushless DC drivetrains replacing legacy gearbox-assemblers simultaneously shift procurement geography toward Japanese and South Korean precision motor suppliers while compressing price premiums on electric platforms destined for Southeast Asian smallholders. This substitution dynamic bifurcates supplier tiers and reconfigures margin pools across electrification roadmaps.
Pricing Analysis
Certification level under India's BIS safety benchmarks and Australia's WorkSafe operator protection standards creates the primary spread between export-ready and domestic-only equipment tiers. Three-tier pricing structure across premium integrated manufacturers, cost-optimized diesel assemblers, and specialized recycling technology firms anchors transactional dynamics. Cost compression in electric platforms is intensifying because lithium-ion raw material constraints squeeze margins on units priced for Vietnam's provincial extension channels. Agricultural cooperatives consolidated through India's state marketing federations exhibit lowest price sensitivity due to unbundled service contracts, while individual smallholders across Bihar and eastern Uttar Pradesh remain most price-constrained.
Supply Chain Analysis
Container availability fluctuations across Shanghai-Ningbo and Busan trade lanes expose Australian and Indian assemblers to lead-time volatility for precision gearboxes and hydraulic systems. Manufacturing concentration rests on China's Shandong Peninsula for diesel engine fabrication, Japan's Nagoya industrial corridor for brushless DC drivetrains, and Germany's Baden-Württemberg region for precision hydraulics. Raw material dependencies center on rare-earth magnets for motor assemblies, high-grade steel for hammer mill rotors, and lithium carbonate for battery packs. Single-source vulnerability concentrates in Japanese precision gearbox suppliers. Distribution runs through state agricultural e-marketplaces in India and Vietnam that displace traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from solar-hybrid platforms and digital procurement channels that bypass established dealer relationships. Defense requires repositioning around service-level bundling and electrification roadmaps.
For Market Incumbents: Shield installed base relationships by establishing captive service networks across India's Punjab-Haryana belt before cooperative tenders fully unbundle after-sales contracts from equipment supply. Accelerate backward integration into brushless DC motor-controller production to reduce dependency on Japanese precision suppliers facing allocation constraints. Vertical integration of this tier protects margin pools from lithium-ion cost volatility. For New Entrants and Emerging Players: BIS certification fast-track through India's PLI scheme for farm machinery opens state tender participation previously blocked by sequential testing protocols. Indonesia's palm residue segment across Sumatra and Kalimantan plantation belts offers the most penetrable white space for heavy-duty shredder deployment. Direct manufacturer-to-cooperative contracting through Vietnam's state agricultural e-marketplaces bypasses entrenched dealer networks. For Investors and Strategic Acquirers: The market sits at an electrification transition phase that favors suppliers with captive battery integration capabilities and multi-year service level agreement infrastructure. Acquisition targets should demonstrate proven deployment in Australia's carbon farming incentive zones or India's cooperative procurement channels. Watch India's PLI scheme revision timing as the inflection signal for subsidy flow redirection toward electric platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Roadmap Acceleration | MIIT efficiency labeling under China's GB standards constrains diesel eligibility for provincial subsidies. |
| Captive Service Network Establishment | India's cooperative sector tenders now mandate multi-year service level agreements unbundled from supply. |
| Solar-Hybrid Platform Development | Photovoltaic-battery convergence enables off-grid deployment in Australia's remote wheat-growing regions. |
| Digital Procurement Channel Integration | State agricultural e-marketplaces in Vietnam and India displace traditional dealer networks with transparent benchmarking. |
| Precision Drivetrain Backward Integration | Brushless DC architectures with integrated power electronics separate integrated manufacturers from legacy assemblers. |
Research Methodology
A standing panel of agricultural cooperative procurement managers, state extension service officers, OEM aftermarket service heads, and plantation group equipment engineers provided ongoing calibration across primary fieldwork. Secondary validation drew from India's BIS certification registries, Australia's WorkSafe equipment approval databases, China's MIIT efficiency labeling disclosures, and customs records tracking precision gearbox import flows. Bottom-up equipment shipment tracking triangulated against top-down subsidy allocation data across the analysis window.
Consistency checks validated volume and value outputs against cooperative tender award disclosures and state agricultural machinery procurement budgets. Segmentation dimensions modeled encompass product type, power source configuration, end-user procurement channel, and application compliance mandate across regional regulatory clusters. CAGRs were derived from fitted growth curves applied to equipment deployment trajectories, with cross-reference to electrification subsidy ramp rates and carbon incentive program maturation.
Decision-makers should treat outputs as directional under assumptions of continued PLI scheme funding and stable lithium-ion raw material sourcing; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as China's dual carbon goal enforcement intensity and India's grid connectivity expansion pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Poultry Processing Equipment Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Hemp Processing Equipment Market