
 Asia-Pacific Agricultural Sensors Market | 2026-2036
Asia-Pacific Agricultural Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Sensors Market Outlook
Sensor-as-a-service subscription models for soil moisture analytics is pivoting how vendors monetize field hardware. AGCO leverages its dealer network to bundle telemetry subscriptions with original equipment sales. DJI anchors its agritech division with multispectral drone platforms that feed data into recurring software tiers. XAG competes through autonomous spraying systems that integrate proprietary crop-scouting sensors.
Asia-Pacific agricultural sensors comprise electrochemical, optical, and mechanical transducers engineered to detect soil pH, canopy reflectance, and microclimate variables with precision thresholds of 0.1 pH units or 0.5°C. These devices automate decision loops in irrigation, fertilization, and pest intervention across fragmented landholdings and plantation estates. Soil Sensors dominate installed bases where salinity and moisture stress constrain yields across Australia's Murray-Darling Basin and India's Deccan Plateau. IoT-enabled gateways represent the fastest-expanding technology layer as cellular LPWAN coverage extends into rural Vietnam and Indonesia. Crop Health Monitoring applications command premium pricing due to their linkage with variable-rate input prescriptions and insurance-linked yield guarantees.
India's BIS certification mandates for electronic agricultural equipment are raising compliance barriers for unbranded imports. China's MIIT spectrum allocations for agricultural IoT are shaping device radio configurations across manufacturing clusters in Shenzhen and Hangzhou. Australia's ACCC consumer guarantees and Water Act compliance requirements influence sensor durability specifications and telemetry audit trails. Stakeholders must weigh regulatory divergence against platform standardization when scaling across multiple Asia-Pacific jurisdictions.
Market Dynamics
Sensor-as-a-service monetization is restructuring vendor economics across Asia-Pacific, displacing upfront hardware transactions with recurring telemetry subscriptions that lock in multi-year customer relationships and flatten revenue volatility.
Growth Catalysts
- India's PLI scheme for agri-tech hardware:Production-linked incentives are accelerating domestic manufacturing capacity for soil moisture and canopy monitoring devices, reducing import dependence for Deccan Plateau farming cooperatives.
- China's MIIT spectrum allocations for agricultural IoT:Dedicated radio frequency bands are enabling standardized LPWAN device configurations across Shenzhen and Hangzhou manufacturing clusters, lowering interoperability costs for smart greenhouse operators.
- Variable-rate input prescriptions:Crop health monitoring applications are commanding premium pricing through linkage with precision fertilization systems and insurance-linked yield guarantees across Australian broadacre operations.
Market Restraints
- Cellular LPWAN coverage gaps:Rural Vietnam and Indonesia lack reliable connectivity infrastructure, forcing sensor deployments onto expensive satellite backhaul or offline data logging with manual retrieval cycles.
- BIS certification timelines:India's Bureau of Indian Standards mandates for electronic agricultural equipment are extending product launch cycles by 8-14 months for unbranded import channels, advantaging early-certified domestic assemblers.
- Salinity sensor drift:Electrochemical transducers in Australia's Murray-Darling Basin require quarterly recalibration against rapid soil chemistry shifts, elevating total cost of ownership beyond smallholder budget thresholds.
Strategic Opportunities
- Indonesia's plantation digitization gap:Palm oil and rubber estates in Sumatra and Kalimantan remain underpenetrated by canopy monitoring systems, presenting first-mover advantage for multispectral drone-integrated sensor networks.
- Autonomous spraying convergence:Integration of proprietary crop-scouting sensors with unmanned aerial application systems is opening subscription bundles that combine hardware, flight operations, and agronomic analytics.
- Australia's Water Act compliance mandates:Telemetry audit trail requirements for irrigation extraction licensing are creating mandatory upgrade cycles for legacy flow monitoring installations across Murray-Darling Basin water markets.
Industry Challenges
- Agronomic data science talent scarcity:Sensor vendors struggle to recruit interpreters capable of translating raw pH and reflectance signals into actionable input prescriptions for fragmented smallholder extension networks.
- Legacy irrigation controller integration:Proprietary communication protocols from 1990s-era center-pivot systems block seamless sensor-to-actuator automation, requiring expensive gateway retrofits or complete control system replacement.
- Cross-border certification fragmentation:Divergent electromagnetic compatibility testing between China's GB standards and Australia's ACMA requirements force hardware variants that fragment production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Sensors Market |
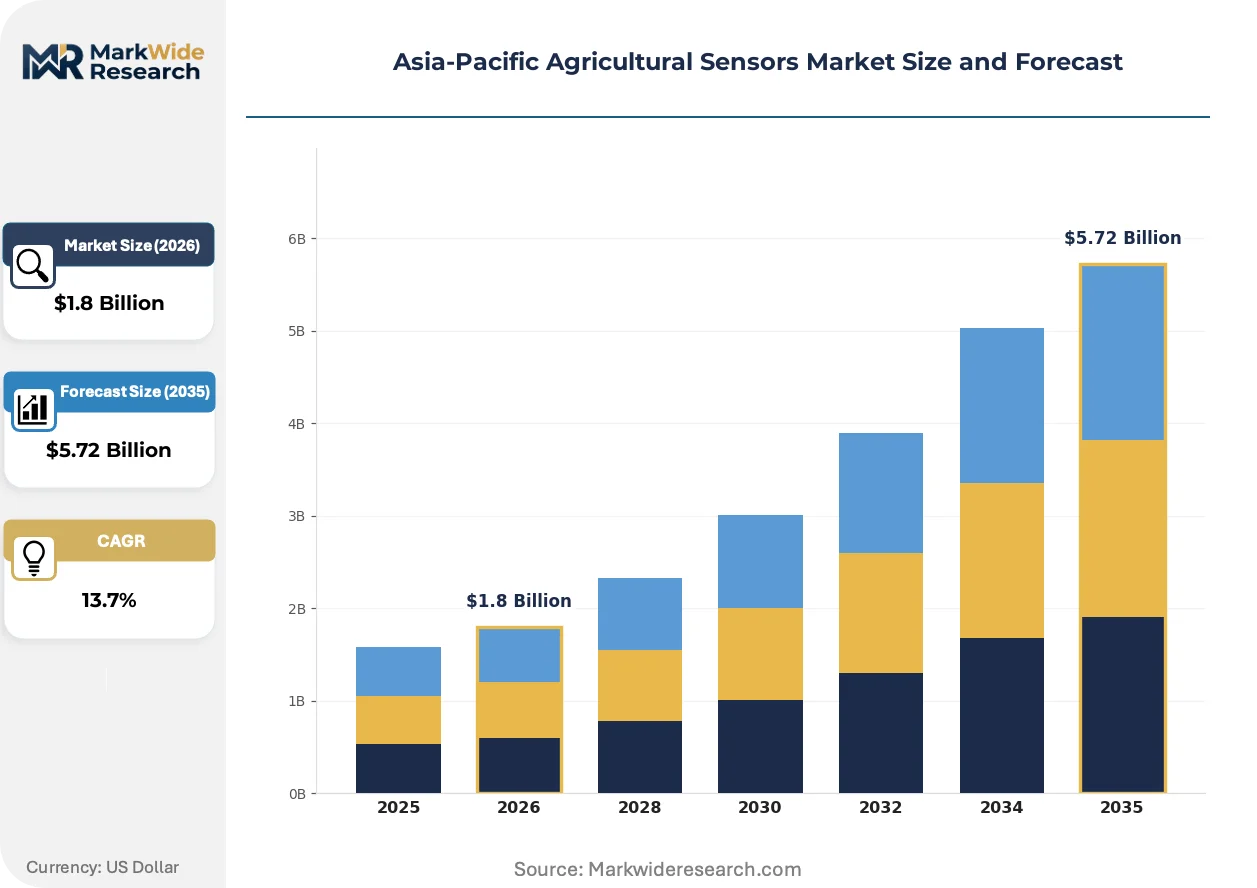
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Sensors, Weather Stations, Crop Sensors, Livestock Monitoring Technology: Bluetooth, IoT, GPS, RFID End User: Farmers, Agricultural Cooperatives, Research Institutions, Agribusinesses Application: Irrigation Management, Crop Health Monitoring, Yield Prediction, Soil Quality Assessment |
| Companies Covered | Konica Minolta, Inc., AGCO, Ningbo Fujin garden irrigation equipment Co. Ltd, Libelium Comunicaciones Distribuidas Sl, Pycno, XAG, Cropin, Hunan Rika Electronic Tech Co., Ltd, DJI, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Sensors Market Strategic Shifts
Edge computing architectures are redistributing analytical workloads from cloud servers to field-deployed gateways, compressing decision latency for irrigation triggers and pest intervention alerts while reducing cellular data costs.
Mesh networking protocols are decentralizing sensor-to-gateway communication across fragmented landholdings. Australian cotton growers are deploying LoRa-enabled soil moisture arrays that self-heal around single-node failures, eliminating the cost-prohibitive cellular subscriptions that previously constrained coverage density on remote station properties.
China's MIIT spectrum allocations for agricultural IoT are mandating unified radio configurations for sub-GHz device operation. Manufacturers in Hangzhou clusters are consolidating previously fragmented 470-510 MHz module designs, enabling cross-brand interoperability that reduces systems integration labor for Yangtze River Delta smart agriculture demonstration zone contractors.
Subscription bundling is displacing discrete hardware procurement in dealer channels. AGCO's telemetry-as-a-service model attaches recurring analytics fees to original equipment sales, converting one-time tractor transactions into multi-year data relationships that capture fertilizer and chemical input recommendations previously ceded to independent agronomists.
Asia-Pacific Agricultural Sensors Market Segmentation
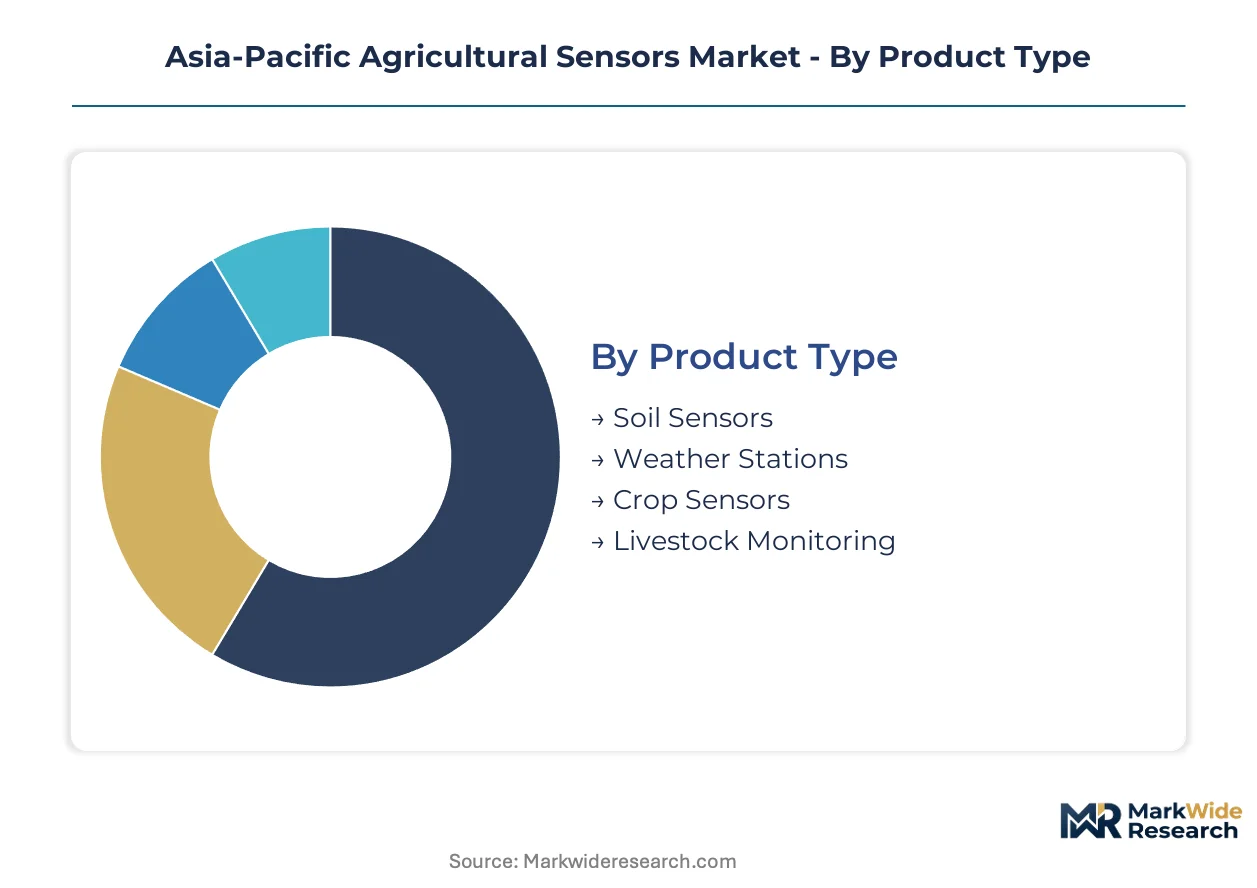
Sensor deployment patterns across Asia-Pacific fragment sharply by product type, connectivity technology, and end-user scale. Capital intensity and regulatory compliance requirements vary dramatically between broadacre mechanized operations and smallholder cooperative networks.
Product Type:
Soil Sensors command the heaviest upfront capital outlays due to burial-grade housing specifications and multi-depth probe arrays required for salinity profiling.
- Soil Sensors:Electrochemical and capacitance-based transducers measure moisture, pH, and electrical conductivity at 15-60cm depths. Australia's Murray-Darling Basin water markets and India's Deccan Plateau farming cooperatives drive installed base expansion as irrigation licensing mandates tighten telemetry requirements.
- Crop Sensors:Multispectral and thermal imaging devices mount on drones or fixed masts to capture canopy reflectance indices. China's Yangtze River Delta smart agriculture demonstration zones concentrate procurement for variable-rate nitrogen prescriptions linked to provincial carbon reduction targets.
- Weather Stations:Microclimate monitoring arrays track temperature, humidity, wind, and solar radiation for pest modeling and frost alerts. Indonesian palm oil estates in Sumatra deploy solar-powered units with satellite backhaul where cellular coverage fails.
- Livestock Monitoring:Collar-mounted accelerometers and rumen boluses track animal health, estrus, and location across Australian cattle stations and New Zealand dairy operations.
Soil Sensors absorb the bulk of installed capacity; Crop Sensors are expanding most quickly.
Technology:
Radio configuration choices directly determine interoperability costs and rural deployment feasibility across fragmented Asia-Pacific regulatory environments.
- IoT:Cellular LPWAN and mesh-enabled gateways aggregate field sensor data for cloud analytics platforms. Vietnam's expanding NB-IoT coverage and China's MIIT-mandated sub-GHz bands are standardizing module designs from Shenzhen manufacturing clusters.
- Bluetooth:Short-range protocols connect handheld diagnostic tools and smartphone-configured soil probes for smallholder extension networks. India's Krishi Vigyan Kendras distribute Bluetooth-enabled pH meters to bypass unreliable rural internet.
- GPS:RTK-corrected positioning enables centimeter-level tractor guidance and drone flight planning for precision input application across Australian broadacre properties.
- RFID:Passive and active tags track seed genetics, chemical batches, and livestock pedigree through supply chain audit trails demanded by Chinese supermarket procurement standards.
IoT-enabled connectivity claims the steepest expansion trajectory; Bluetooth retains dominance in lowest-cost smallholder toolkits.
End User:
Procurement scale and technical sophistication diverge sharply between plantation estates with dedicated agronomy teams and fragmented smallholder networks.
- Agribusinesses:Integrated plantation operators and input suppliers deploy enterprise sensor networks with dedicated data science teams. Wilmar International's Indonesian palm oil operations and COFCO's Chinese grain procurement divisions anchor regional demand for canopy monitoring systems.
- Agricultural Cooperatives:Pooled purchasing enables India's Farmer Producer Organizations and Australian irrigation trusts to access telemetry subscriptions previously priced beyond individual member means.
- Farmers:Individual operators select entry-level soil moisture probes and weather stations through dealer financing programs. Australia's Rabobank equipment lending and India's NABARD refinance schemes shape affordability thresholds.
- Research Institutions:CSIRO's agricultural robotics program and China's Chinese Academy of Agricultural Sciences validate sensor calibration protocols for commercialization pathways.
Agribusinesses concentrate the highest-value deployments; Agricultural Cooperatives are climbing the fastest as subscription models democratize access.
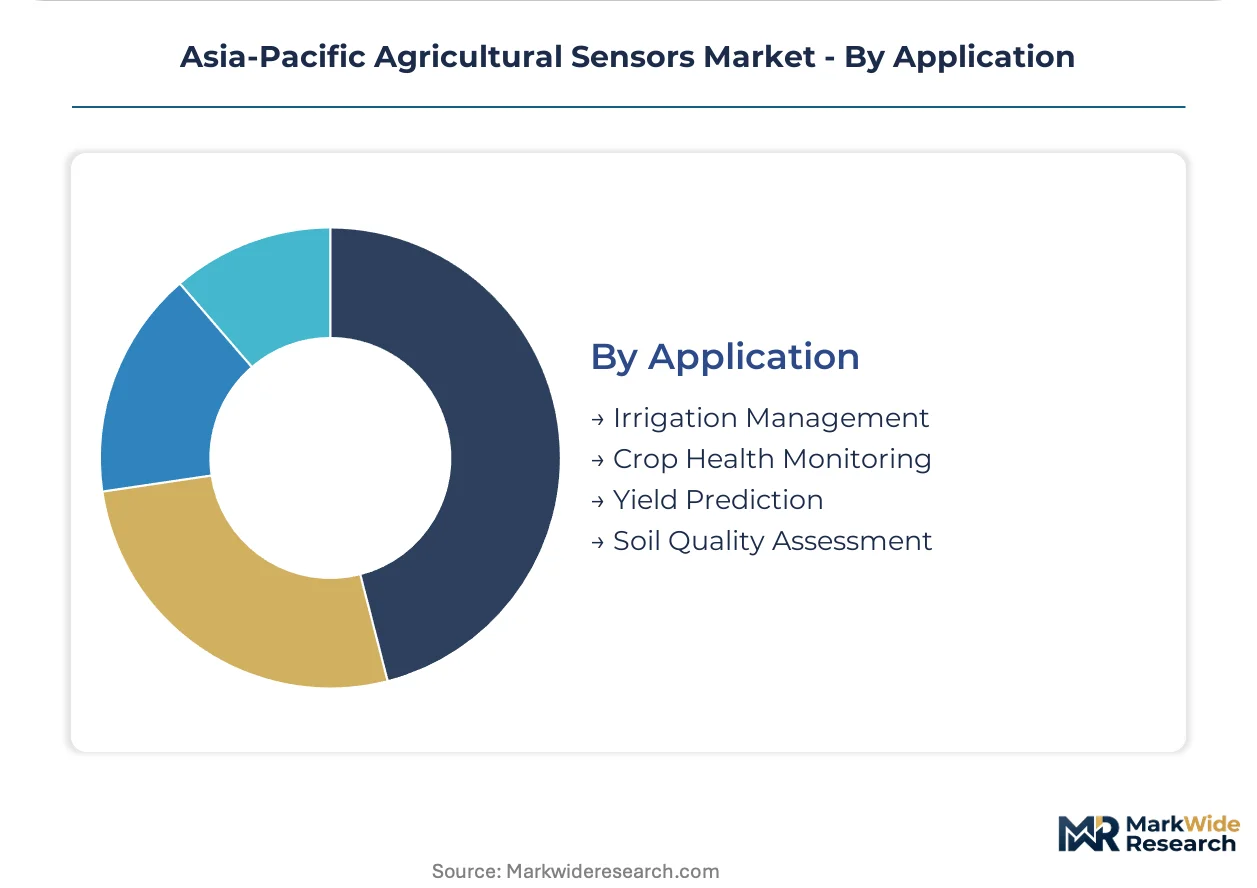
Application:
Revenue per hectare varies dramatically by whether sensor outputs trigger automated actuation or merely inform manual decision timelines.
- Irrigation Management:Soil moisture-driven valve automation and pump scheduling deliver immediate water cost savings. Australia's Water Act compliance mandates for extraction metering create mandatory upgrade cycles across Murray-Darling Basin water markets.
- Crop Health Monitoring:Multispectral vegetation indices guide fungicide timing and variable-rate nitrogen application. Chinese provincial carbon accounting frameworks increasingly subsidize precision input reduction documented through sensor audit trails.
- Soil Quality Assessment:pH and salinity mapping enables lime and gypsum prescription for long-term productivity maintenance across India's alkaline Deccan Plateau soils.
- Yield Prediction:Canopy biomass models and weather-driven simulation platforms support crop insurance pricing and forward contracting for Australian wheat and Chinese rice procurement.
Irrigation Management captures the largest installed base; Crop Health Monitoring is gaining share fastest through linkage with carbon reduction incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in China's eastern seaboard clusters while consumption disperses across Australia's water-stressed basins, India's cooperative networks, and Southeast Asian plantation belts. Shenzhen and Hangzhou foundries supply electrochemical transducers to regional integrators who configure devices for local soil chemistry and spectrum regulations. This production-consumption split shapes logistics costs and compliance complexity for vendors scaling across jurisdictions.
China
MIIT spectrum allocations for agricultural IoT mandate unified sub-GHz radio configurations that lower interoperability costs for smart greenhouse contractors. The Yangtze River Delta demonstration zones concentrate procurement of canopy monitoring systems linked to provincial carbon accounting frameworks. Hangzhou manufacturing clusters consolidate previously fragmented module designs, enabling cross-brand compatibility that reduces systems integration labor.
India
BIS certification timelines for electronic agricultural equipment extend product launch cycles by 8-14 months, advantaging early-certified domestic assemblers over unbranded import channels. PLI scheme incentives accelerate manufacturing capacity for soil moisture and canopy monitoring devices across Deccan Plateau farming cooperatives. Karnataka and Maharashtra host emerging assembly operations that bypass import dependence for regional distribution.
Australia
Water Act compliance mandates for irrigation extraction licensing create mandatory upgrade cycles for legacy flow monitoring installations across Murray-Darling Basin water markets. ACCC consumer guarantees influence sensor durability specifications and telemetry audit trail requirements. Queensland and New South Wales broadacre operations drive demand for soil salinity profiling arrays that withstand rapid chemistry shifts.
Indonesia
Palm oil and rubber estates in Sumatra and Kalimantan remain underpenetrated by canopy monitoring systems, presenting first-mover positioning for drone-integrated sensor networks. Cellular LPWAN coverage gaps force deployments onto satellite backhaul or offline data logging with manual retrieval cycles. Jakarta-based systems integrators increasingly bundle hardware with flight operations subscriptions for plantation operators.
Vietnam
Expanding NB-IoT coverage in the Mekong Delta enables standardized gateway deployments that reduce reliance on expensive satellite connectivity for rice paddy monitoring. Provincial agricultural extension services pilot Bluetooth-enabled soil probes distributed through Krishi Vigyan Kendra analogs. Ho Chi Minh City technology distributors aggregate demand from fragmented smallholder networks for volume procurement negotiations.
Asia-Pacific Agricultural Sensors Market Competitive Environment
Capital-heavy producers compete with asset-light designers across sensor manufacturing and analytics platform layers. Foundry-dependent fabricators in Shenzhen and Hangzhou supply electrochemical transducers to regional integrators who configure housing and telemetry for local compliance. Three archetypes dominate: integrated equipment manufacturers bundling telemetry subscriptions with original machinery sales; autonomous systems specialists converging crop-scouting sensors with unmanned aerial application platforms; and pure-play analytics vendors aggregating third-party sensor streams into prescription algorithms. Competitive moves concentrate on backward integration into module manufacturing and geographic expansion through dealer network partnerships.
Among integrated equipment manufacturers, AGCO exemplifies the subscription-bundling archetype through telemetry-as-a-service models attached to original machinery transactions. DJI and XAG anchor the autonomous systems tier, representing the convergence of multispectral aerial platforms with proprietary sensing hardware and flight operation services. These three companies occupy positions that span hardware manufacturing, recurring software revenue, and field service deployment, illustrating the sector's vertical complexity.
| Leading Market Players |
|---|
| Konica Minolta, Inc. |
| AGCO |
| Ningbo Fujin garden irrigation equipment Co. Ltd |
| Libelium Comunicaciones Distribuidas Sl |
| Pycno |
| XAG |
| Cropin |
| Hunan Rika Electronic Tech Co., Ltd |
| DJI |
| Others |
Value Chain & Pricing Dynamics
Electrochemical transducer costs from Shenzhen foundries cascade through three distinct pricing tiers as they reach Australian broadacre operators, Indian farming cooperatives, and Indonesian plantation estates, with BIS certification premiums and satellite backhaul surcharges layering onto base hardware economics.
Pricing Analysis
Margin tightening in the sensor-as-a-service tier reflects the shift from upfront hardware transactions to recurring telemetry subscriptions. Pricing stratifies across premium certified-installation, standard dealer-bundled, and economy direct-import tiers, with BIS certification timelines and MIIT spectrum compliance driving differentiation. Cost compression accelerates in the economy tier as Hangzhou manufacturing clusters consolidate module designs. Smallholder cooperatives in India's Deccan Plateau exhibit highest price sensitivity; Australian agribusinesses with Water Act compliance mandates show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Australian irrigation trusts and Indian Farmer Producer Organizations mandate qualification of at least two module suppliers, fragmenting procurement across Shenzhen and Hangzhou clusters. Electrochemical transducers, LPWAN radio modules, and burial-grade housing polymers anchor bill-of-materials. Single-source vulnerability concentrates in sub-GHz radio configurations where MIIT allocations constrain alternative suppliers. Distribution runs through agricultural equipment dealer networks and Jakarta-based systems integrators bundling hardware with flight operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification mandates function as a cost-of-compliance moat, advantaging early-certified domestic assemblers over unbranded import channels and restructuring competitive economics across the regional market.
For Market Incumbents: Deploy backward integration into electrochemical transducer manufacturing to capture margin from Shenzhen foundries and buffer against MIIT spectrum allocation shifts. Fortify dealer network exclusivity in Australia's Murray-Darling Basin water markets where Water Act telemetry mandates create captive upgrade cycles. Counter XAG and DJI autonomous spraying convergence through bundled sensor-to-actuator subscription packages that lock in multi-year relationships. For New Entrants and Emerging Players: Begin with Indonesia's Sumatra and Kalimantan plantation belts where canopy monitoring penetration remains underdeveloped and cellular LPWAN gaps force satellite-dependent deployments that incumbent pricing has not optimized for. Target palm oil estates with drone-integrated sensor networks sold through flight-operations-as-a-service models. Leverage Jakarta-based systems integrators as channel partners to bypass direct dealer network buildout costs. For Investors and Strategic Acquirers: Accelerating PLI scheme disbursements in Karnataka and Maharashtra is the leading indicator that domestic Indian assembly capacity is reaching scale economics viable for regional export. Five-to-ten year viability hinges on sensor-as-a-service recurring revenue capture rather than hardware transaction multiples. Acquisition target archetype: asset-light analytics platforms with proprietary prescription algorithms and established agronomic data science teams. Watch for BIS certification backlogs clearing as signal of competitive shakeout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-as-a-Service Subscription Launch | AGCO's telemetry bundling converts one-time tractor sales into recurring multi-year data relationships. |
| Autonomous Spraying Convergence | XAG integrates proprietary crop-scouting sensors with unmanned aerial application platforms. |
| Domestic Manufacturing Scale-Up | India's PLI scheme accelerates soil moisture and canopy monitoring assembly in Deccan Plateau clusters. |
| Dealer Network Exclusivity Expansion | AGCO leverages agricultural equipment channels to bundle telemetry with original machinery sales. |
| MIIT Spectrum Compliance Investment | Hangzhou manufacturers consolidate 470-510 MHz module designs for Yangtze River Delta smart agriculture zones. |
Study Parameters
Independent corroboration across sensor vendor executives, agricultural cooperative procurement leads, and irrigation trust technical officers underwrites the qualitative findings. Primary fieldwork with Deccan Plateau farming cooperatives, Murray-Darling Basin water market participants, and Sumatra plantation operators combined with secondary validation from BIS certification filings, MIIT spectrum allocation records, and Water Act compliance audit trails. Bottom-up installed base enumeration and top-down agricultural GDP attribution triangulate market sizing.
Comparable-period anchoring to historical sensor deployment trajectories in Australian broadacre operations and Chinese smart agriculture demonstration zones structured the projection horizon. Segmentation modeling spans product type, connectivity technology, end-user scale, and application intensity across the analysis window. CAGRs derive from fitted adoption curves calibrated to PLI scheme disbursement velocities and NB-IoT coverage expansion timelines in Vietnam's Mekong Delta.
Underlying measurement precision varies by segment; IoT-enabled gateway deployments carry tighter precision than offline data logging estimates. Forecasts reflect assumptions about cellular LPWAN infrastructure buildout and BIS certification processing throughput. Deviation in MIIT spectrum reallocation or Water Act telemetry mandate enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Agricultural Mapping Services Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
North America Precision Agriculture Market