
 Glufosinate Ammonium Market | 2026-2036
Glufosinate Ammonium Market Size, Share, and Industry Trends Forecast 2026-2036
Glufosinate Ammonium Market Foresight
The EU Green Deal is recalibrating herbicide registration timelines across European agriculture, forcing manufacturers to front-load toxicology and environmental fate data. BASF SE leverages its integrated glufosinate production chain from precursor chemicals to formulated products, sustaining cost advantages in technical grade supply. Bayer AG anchors its position through LibertyLink seed-trait bundling, while Syngenta competes via differentiated water-dispersible granule formulations for specialty crop segments.
Glufosinate ammonium functions as a broad-spectrum, post-emergent herbicide inhibiting glutamine synthetase, causing rapid ammonia accumulation and plant cell death; it is typically manufactured through stereoselective synthesis of phosphinothricin followed by ammonium salt formation, yielding active ingredients with purity thresholds exceeding 95 percent for technical grade material. Technical grade supply dominates volume flows into agrochemical manufacturer channels, where margin pools concentrate in formulated concentrate conversion for row-crop applications. Cereals and grains absorb the largest application share, though oilseeds represent the fastest-growing demand vector as glufosinate-tolerant soybean and canola hectares expand.
EPA residue tolerance settings and EU REACH chemical registration requirements jointly shape product label specifications and maximum residue limits for export-compliant crops. China's MEE enforces wastewater discharge standards on phosphinothricin intermediate production, constraining capacity additions from domestic manufacturers such as Lier Chemical. Stakeholders must monitor evolving regulatory divergence between jurisdictions that accept glufosinate-tolerant biotech traits and those restricting broad-spectrum herbicide approvals.
Market Dynamics
Glyphosate resistance proliferation across major soybean and corn belts is forcing rapid rotation toward glufosinate-tolerant trait systems, compressing farmer switching timelines and reordering herbicide procurement hierarchies.
Growth Catalysts
- Herbicide-tolerant biotech traits:LibertyLink and other glufosinate-tolerant seed systems in soybeans and corn are accelerating farmer uptake as glyphosate-resistant weed populations expand across North American and Brazilian farmland.
- EU Green Deal recalibration:The Farm to Fork strategy is narrowing approval pathways for competing broad-spectrum chemistries, creating relative regulatory space for glufosinate-based alternatives with established residue databases.
- Water-dispersible granule formulations:Advanced delivery formats reduce drift liability and improve handler safety profiles, opening specialty crop segments previously closed to liquid concentrate applications.
Market Restraints
- Phosphinothricin intermediate supply concentration:Technical grade production clusters in China, where MEE wastewater discharge standards constrain capacity expansion and create input bottlenecks for downstream formulators.
- EU authorization friction:EFSA renewal assessments for broad-spectrum herbicides under Farm to Fork timelines extend registration uncertainty, freezing investment in European formulation infrastructure.
- Glyphosate cost competition:Generic glyphosate pricing in Brazil and Argentina retains cost advantage for non-resistant weed control, limiting glufosinate penetration in price-sensitive soybean regions.
Strategic Opportunities
- Canola expansion corridors:Canadian prairie provinces and Australian wheat belts are accelerating glufosinate-tolerant canola adoption, creating demand vectors outside saturated soybean markets.
- Precision application integration:Drone-based spot-spraying systems are converging with real-time weed identification, enabling glufosinate deployment at sub-field scales that reduce per-hectare active ingredient rates.
- Seed-trait bundling architectures:Stacked herbicide tolerance traits combining glufosinate and dicamba resistance are creating premium pricing tiers for integrated weed management programs.
Industry Challenges
- Toxicology data regeneration:EU REACH and EPA re-registration requirements demand updated chronic exposure studies, compressing timelines for dossier submission and straining regulatory affairs capacity.
- Cross-resistance management protocols:Agronomists must design rotation sequences that preserve glufosinate efficacy against weeds developing metabolic resistance, requiring sophisticated field-level implementation support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glufosinate Ammonium Market |
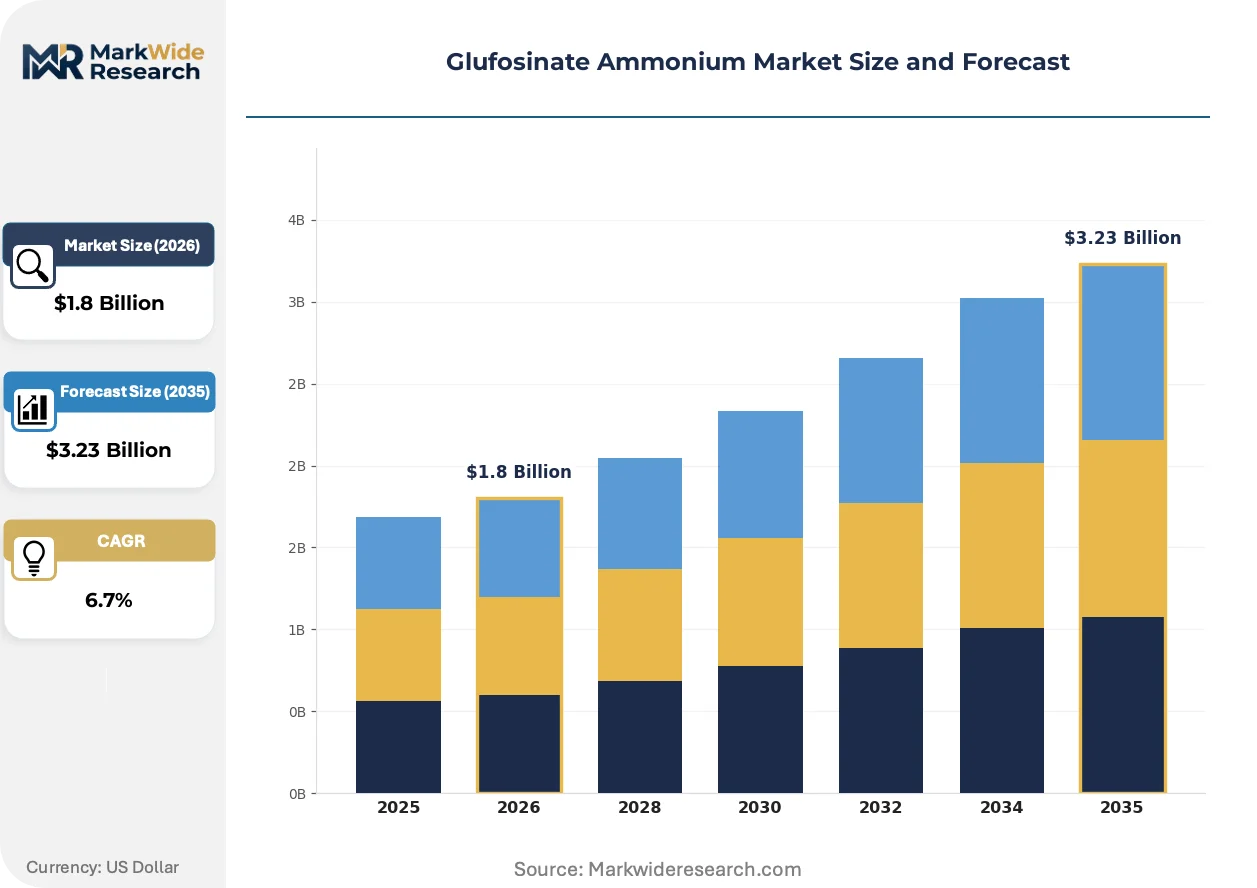
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Formulated Concentrate, Water-Dispersible Granules, Wettable Powder Application: Cereals & Grains, Vegetables, Oilseeds, Pulses, Turf & Ornamentals Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate End User: Agrochemical Manufacturers, Crop Producers, Contract Research Organizations, Agricultural Distributors |
| Companies Covered | BASF SE, Bayer AG, Syngenta, Corteva Agriscience, UPL, Nufarm, Lier Chemical, Zhejiang Yongnong Chem, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glufosinate Ammonium Market Shifts & Advancements
Formulation chemistry advances and digital agriculture integration are reshaping how glufosinate reaches field applications, with precision delivery systems displacing broadcast methods.
Water-dispersible granule technology is expanding into specialty vegetable and fruit crop segments where drift sensitivity previously excluded broad-spectrum herbicides. Greenhouse operators in Spain and Italy are adopting these low-dust formulations for post-emergent weed control between crop rows. The format is enabling formulators to capture margin pools in high-value horticulture that liquid concentrates cannot access.
EPA residue tolerance settings and EU REACH chemical registration requirements are jointly tightening maximum residue limit specifications for export-compliant soybeans and corn. This regulatory convergence is forcing manufacturers to harmonize label specifications across jurisdictions, raising compliance costs for multi-destination exporters. Brazilian and Argentine grain handlers are investing in pre-shipment testing infrastructure to verify compliance with divergent destination-market standards.
Farmer procurement of herbicide-tolerant seed systems now precedes and constrains chemical selection, reversing traditional input purchasing sequences. Seed distributors in Iowa and Mato Grosso are bundling glufosinate supply commitments with trait licensing agreements, locking in multi-season chemical offtake. This channel consolidation is compressing independent agrochemical retailer margins and shifting volume flows toward integrated seed-chemistry platforms.
Glufosinate Ammonium Market Segmentation
Glufosinate ammonium traverses multiple product formats and application contexts, each commanding distinct margin structures and regulatory obligations. Segmentation clarity exposes where technical grade supply concentrates versus where formulation value-add accumulates.
Product Type:
Integration depth separates precursor chemicals destined for captive use from finished goods sold into retail channels.
- Technical Grade:Phosphinothricin-derived active ingredient exceeding 95% purity serves as the foundational input for downstream formulation. Chinese manufacturers dominate intermediate production, though MEE wastewater standards now constrain capacity additions and tighten supply availability for external formulators.
- Formulated Concentrate:Liquid concentrates blended for row-crop broadcast application capture the largest volume flows in North American and Brazilian soybean systems. Bayer's LibertyLink bundling programs and BASF's supply chain integration anchor procurement hierarchies around multi-season offtake commitments.
- Water-Dispersible Granules:Low-dust solid formulations reduce drift liability and handler exposure, opening specialty crop segments in Spanish greenhouse operations and Italian horticulture previously closed to liquid applications.
- Wettable Powder:Traditional powder format retains cost-sensitive demand in emerging market smallholder contexts where application equipment limitations favor dry mixing protocols.
Volume placements concentrate in Technical Grade; the faster expansion belongs to Water-Dispersible Granules.
Application:
Herbicide-tolerant trait penetration rates diverge sharply across crop categories, reshaping demand concentration.
- Cereals & Grains:Wheat and rice applications remain constrained by limited glufosinate-tolerant biotech trait commercialization, leaving this segment dependent on post-emergent spot treatments rather than systemic broadcast programs.
- Oilseeds:Soybean and canola hectares with LibertyLink or stacked tolerance traits are climbing the fastest, particularly in Brazilian expansion zones and Canadian prairie provinces where glyphosate resistance has forced rotation urgency.
- Vegetables:High-value protected cropping in Spain, Italy, and Mexico adopts water-dispersible granule formats for between-row weed management where crop sensitivity excludes conventional herbicide options.
- Pulses:Lentil and chickpea applications remain niche, constrained by limited trait development and rotational crop restrictions in major producing regions.
- Turf & Ornamentals:Golf course and landscape maintenance in the United States and Japan absorbs premium-formulation volumes where aesthetic tolerance for weed pressure approaches zero.
Current volume leadership sits with Cereals & Grains; Oilseeds demonstrate the steepest expansion trajectory as trait adoption accelerates.
Formulation:
Physical state determines application equipment compatibility and drift regulatory exposure across jurisdictions.
- Liquid:Soluble concentrates and suspension concentrates dominate large-scale mechanized agriculture in Brazil, Argentina, and the United States Midwest, where ground rig and aerial application infrastructure favors fluid handling systems.
- Granular:Solid granule formats reduce packaging and transport costs for export shipments to distant markets, with particular traction in Australian and South African distribution networks.
- Powder:Dry flowables retain relevance in manual backpack sprayer contexts across Southeast Asian smallholder systems where water access constraints complicate liquid mixing logistics.
- Emulsifiable Concentrate:Oil-based carrier systems improve rainfastness and leaf surface retention in tropical high-rainfall zones, commanding formulation premiums in Indonesian and Malaysian palm oil intercropping applications.
Granular shipments are gaining share fastest in export-oriented supply chains; Liquid retains dominant placement in integrated seed-chemistry platforms.
End User:
Procurement authority separates bulk chemical purchasers from specification-driven retail channel operators.
- Agrochemical Manufacturers:Technical grade buyers with captive formulation capacity—BASF, Bayer, Syngenta—source phosphinothricin intermediates under long-term supply agreements that lock in margin structures across production cycles.
- Crop Producers:Direct farmer procurement is consolidating around seed-trait bundling architectures, reversing traditional input purchasing sequences and compressing independent retailer margins.
- Agricultural Distributors:Independent retail channels in Iowa, Mato Grosso, and Ukraine retain residual volume for non-traited crop applications and replacement spot-spray demand.
- Contract Research Organizations:Field trial operators and regulatory submission consultants absorb reference standard and analytical grade volumes for residue study and environmental fate assessment protocols.
Procurement volume concentrates in Agrochemical Manufacturers; Crop Producers are expanding most quickly as channel consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu Province anchors phosphinothricin intermediate manufacturing, with Yancheng chemical industrial parks processing the bulk of technical grade supply feeding downstream formulators worldwide.
China
Domestic glufosinate technical grade production clusters in Jiangsu and Shandong provinces, where phosphinothricin synthesis facilities face tightening MEE wastewater discharge enforcement. The Ministry of Ecology and Environment's 2023 discharge standard revisions have frozen capacity expansions at several intermediate producers. Yancheng chemical industrial parks now require zero-liquid-discharge compliance, elevating capital requirements for new entrants and consolidating supply among incumbents with captive treatment infrastructure.
United States
Iowa and Illinois seed-chemistry bundling programs are compressing independent agrochemical retailer margins as LibertyLink trait licensing locks in multi-season glufosinate offtake. EPA residue tolerance settings for soybeans and corn are tightening maximum residue limit specifications for export-compliant grain. The Des Moines agribusiness corridor now hosts expanded pre-shipment testing infrastructure to verify compliance with divergent EU and Asian destination-market standards.
Brazil
Mato Grosso soybean expansion zones are driving the fastest glufosinate-tolerant trait adoption as glyphosate-resistant Palmer amaranth spreads across Cerrado farmland. ANVISA pesticide re-registration timelines are extending label uncertainty for competing chemistries, creating relative regulatory space for established glufosinate formulations. The Rondonópolis logistics hub is consolidating import volumes for distribution into Paraguay and Bolivia transshipment corridors.
Germany
BASF's Ludwigshafen integrated production chain sustains cost advantages from precursor chemicals through formulated products, anchoring European technical grade supply. EFSA renewal assessments under EU Green Deal Farm to Fork timelines are extending broad-spectrum herbicide registration uncertainty, freezing investment in regional formulation infrastructure. The Rhine-Neckar chemical cluster is pivoting toward water-dispersible granule R&D to capture specialty crop segments with lower regulatory exposure.
Canada
Alberta and Saskatchewan prairie provinces are accelerating glufosinate-tolerant canola adoption, creating demand vectors outside saturated soybean markets. Health Canada PMMA residue limit harmonization with EPA standards is simplifying label specifications for cross-border grain trade. The Saskatoon ag-tech corridor is developing precision application protocols for drone-based spot-spraying systems that reduce per-hectare active ingredient rates in variable weed pressure zones.
Glufosinate Ammonium Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and seed-trait bundling depth, with technical grade supply concentration creating divergent margin pools. The vendor base separates into three tiers: integrated multinationals with captive intermediate production, regional formulators dependent on external technical grade supply, and generic manufacturers competing on price in emerging markets. Strategic archetypes include seed-chemistry platform integrators, formulation technology specialists, and phosphinothricin intermediate suppliers. Dominant competitive moves encompass backward integration into precursor chemical production and precision application technology partnerships that lock in farmer switching costs.
Among the integrated multinational tier, BASF SE and Bayer AG exemplify divergent platform strategies, with the former leveraging Ludwigshafen production integration and the latter anchoring position through seed-trait licensing architectures. Syngenta occupies a formulation-specialist position, competing via differentiated delivery formats for specialty crop segments. Chinese technical grade suppliers including Lier Chemical and Zhejiang Yongnong Chem represent the intermediate-supplier archetype, though MEE enforcement is compressing their capacity expansion flexibility and tightening supply availability for external formulators.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta |
| Corteva Agriscience |
| UPL |
| Nufarm |
| Lier Chemical |
| Zhejiang Yongnong Chem |
| DuPont de Nemours |
| Others |
Supply & Pricing Matrix
Technical grade purity thresholds exceeding 95 percent create a bifurcated margin structure between phosphinothricin intermediate suppliers and downstream formulators, with MEE wastewater discharge standards in China's Jiangsu and Shandong provinces concentrating supply among incumbents with captive treatment infrastructure while locking out price-competitive entrants. This certification ladder simultaneously elevates technical grade pricing power for compliant Chinese manufacturers and compresses formulation margins for external buyers dependent on spot market procurement.
Pricing Analysis
Yield-per-hectare outcomes anchor value-based pricing for glufosinate-tolerant seed-trait bundles, with Bayer's LibertyLink licensing commanding premium tiers against generic technical grade spot purchases. Price differentiation separates EPA residue-compliant formulations for export soybeans from domestic-only label specifications, while Brazilian and Argentine price sensitivity intensifies cost compression in non-resistant weed control zones where glyphosate generics retain cost advantage. Formulators with backward integration into phosphinothricin production capture margin pools unavailable to external technical grade buyers.
Supply Chain Analysis
Zero-liquid-discharge certification requirements at Yancheng chemical industrial parks gate entry for new phosphinothricin intermediate capacity, concentrating technical grade supply among incumbent Chinese producers with compliant infrastructure. Raw material flows draw from phosphinothricin synthesis facilities, ammonium salt formation units, and formulated concentrate blending operations, with single-source vulnerability emerging from Jiangsu Province's dominance in stereoselective synthesis capacity. Distribution runs through integrated seed-chemistry platforms in Iowa and Mato Grosso, where trait bundling locks in multi-season offtake commitments ahead of independent retailer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH chemical registration and EPA re-registration requirements erect a cost-of-compliance moat around glufosinate ammonium manufacturing, with toxicology data regeneration demands freezing investment from undercapitalized entrants while rewarding incumbents with established dossier libraries and regulatory affairs capacity.
For Market Incumbents: Lock in phosphinothricin intermediate supply through long-term offtake agreements with MEE-compliant Chinese manufacturers before zero-liquid-discharge standards tighten further. Defend formulation margins by accelerating water-dispersible granule R&D for specialty crop segments with lower regulatory exposure, countering glyphosate cost competition in Brazilian price-sensitive zones.
For New Entrants and Emerging Players: The premium-to-economy gap in canola-tolerant trait systems offers white-space entry for regional formulators with precision application partnerships. Target Canadian prairie provinces and Australian wheat belts where glufosinate-tolerant canola adoption accelerates outside saturated soybean markets. Pursue drone-based spot-spraying integration as a differentiated go-to-market angle that reduces per-hectare active ingredient rates.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of MEE-certified Chinese technical grade producers with stranded capacity advantages. Long-term viability hinges on regulatory compliance durability across EU Green Deal and EPA renewal timelines. Watch EFSA broad-spectrum herbicide assessment outcomes as the inflection signal for European formulation infrastructure investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphinothricin | Captive intermediate supply locks in margin structures against MEE-constrained Chinese spot markets. |
| Water-Dispersible Granule R&D | Specialty crop penetration in Spanish greenhouses and Italian horticulture opens premium formulation tiers. |
| Seed-Trait Bundling Architectures | LibertyLink licensing programs in Iowa and Mato Grosso reverse traditional input purchasing sequences. |
| Precision Application Partnerships | Drone-based spot-spraying integration with Saskatoon ag-tech corridors reduces active ingredient rates. |
| Long-Term Supply Agreements | Multi-season offtake commitments secure technical grade allocation ahead of zero-liquid-discharge capacity freezes. |
Research Methodology
Multi-period observation of phosphinothricin intermediate capacity additions, MEE wastewater enforcement actions, and LibertyLink trait licensing volumes anchored the trend analysis, supplemented by interviews with agrochemical procurement directors, seed-trait licensing managers, EPA regulatory affairs leads, and Brazilian distributor operations heads. Secondary validation drew from customs/trade data, SEC 10-K filings, ANVISA registration databases, and EFSA renewal assessment timelines. Bottom-up technical grade supply modeling triangulated against top-down formulated product demand forecasts across the analysis window.
Input-output matrices segmented volume and value projections by product type, application crop category, formulation physical state, and end-user procurement authority. CAGRs were derived from fitted growth curves against historical trait adoption rates and regulatory approval trajectories. Key forecast inputs included glyphosate resistance spread indices in North American and Brazilian farmland, plus EU Green Deal Farm to Fork implementation pacing across member state competent authorities.
Inputs from Chinese MEE discharge standard revisions and EFSA broad-spectrum herbicide assessment protocols were available through the study window; gaps in real-time trait licensing contract terms introduce uncertainty bands around seed-chemistry bundling volume forecasts. Forecasts reflect documented assumptions regarding regulatory renewal timelines and resistance management protocol adoption. A model refresh is warranted upon material change in EPA residue tolerance settings or EU REACH authorization outcomes for competing chemistries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Global Turf Protection Market
Crop Protection
Europe Fungicide Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Europe Insecticides Market
Crop Protection
South America Insecticide Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Larvicides Market
Crop Protection
Microbial Pesticides Market