
 Global Chlorpyrifos Market | 2026-2036
Global Chlorpyrifos Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chlorpyrifos Market Analysis
Aftermarket technical support revenue is narrowing as generic manufacturers erode branded service premiums. BASF SE leverages its formulation expertise to sustain premium positioning in emulsifiable concentrate variants. Bayer CropScience anchors its portfolio through integrated pest management bundles that combine chlorpyrifos with biological adjuvants. Corteva Agriscience differentiates via geographic concentration in regions with less restrictive residue protocols.
Chlorpyrifos is an organophosphate insecticide with the chemical formula C9H11Cl3NO3PS, functioning as an acetylcholinesterase inhibitor that disrupts nervous system function in target arthropods. The compound is manufactured through a multi-step synthesis involving phosphoryl chloride and 3,5,6-trichloro-2-pyridinol intermediates, with purity grades typically exceeding 95 percent for agricultural formulations. Emulsifiable concentrate formulations dominate commercial volumes due to established blending infrastructure and field application familiarity, while wettable powder variants face contraction as drift concerns prompt regulatory scrutiny. Agricultural crops absorb the majority of chlorpyrifos offtake, with row-crop applications in corn and soy generating the most consistent demand cycles among end-user segments.
The EPA governs chlorpyrifos tolerance levels under the Federal Insecticide, Fungicide, and Rodenticide Act, with recent administrative rulings oscillating between revocation and partial reinstatement of food residue allowances. Brazil's ANVISA maintains independent maximum residue limits that frequently diverge from US standards, creating arbitrage opportunities for exporters with multi-jurisdictional registration portfolios. EU REACH restrictions and the F-Gas Regulation framework have eliminated chlorpyrifos applications across member states, redirecting surplus volumes toward Asian and Latin American markets. Stakeholders must monitor pending court decisions on EPA administrative orders to anticipate abrupt supply disruptions or reopened market access.
Market Dynamics
Regulatory arbitrage between jurisdictions with divergent maximum residue limits is fragmenting product flows and forcing manufacturers to maintain parallel registration portfolios for the same active ingredient.
Growth Catalysts
- Brazilian soybean expansion:Farmers in Mato Grosso and Paraná states continue applying chlorpyrifos for soil pest management where alternative chemistries lack equivalent efficacy against wireworms and root borers.
- REACH phase-out redirection:Surplus volumes formerly destined for EU member states are being reallocated to Asian and Latin American markets, sustaining global production scale.
- Emulsifiable concentrate infrastructure:Established blending plants and field application equipment lock in demand for EC formulations despite wettable powder alternatives.
Market Restraints
- EPA tolerance volatility:Oscillating administrative rulings on food residue allowances create inventory risk and deter long-term procurement commitments from agricultural cooperatives.
- Generic manufacturer erosion:Unbranded suppliers are compressing service premiums and technical support margins that historically sustained differentiated positioning.
- Organophosphate substitution:Neonicotinoid and pyrethroid alternatives are capturing share in corn and cotton applications where registration pathways remain open.
Strategic Opportunities
- Integrated pest management bundles:Combining chlorpyrifos with biological adjuvants creates defensible positioning in regions where standalone applications face scrutiny.
- ANVISA-EPA arbitrage:Exporters with dual registration portfolios can exploit divergence in Brazil's and the United States' maximum residue limits for premium pricing.
- Soil pest control gaps:Limited alternative chemistries for subterranean arthropod management preserve demand in Argentina's grain belt and Australia's winter cereal regions.
Industry Challenges
- Multi-jurisdictional compliance:Maintaining current registrations across ANVISA, EPA, and emerging market regulators requires dedicated regulatory affairs capacity and unpredictable re-registration expenditures.
- Formulation expertise attrition:Generic competitors lack the technical personnel to replicate complex emulsifiable concentrate stability profiles, yet price pressure forces branded manufacturers to defend margins without full service differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chlorpyrifos Market |
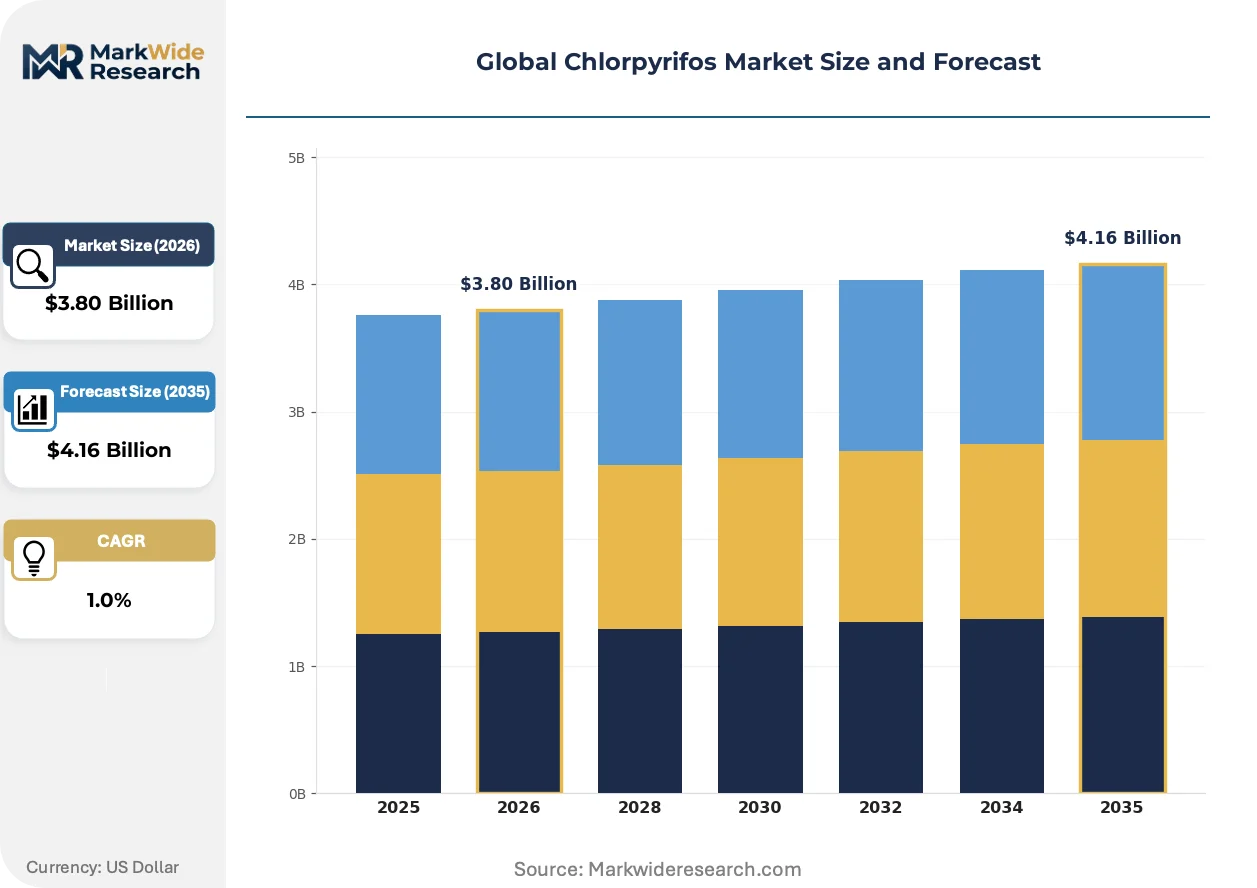
| Market Size in 2026 | $3.80 Billion |
| Market Size in 2035 | $4.16 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Emulsifiable Concentrate, Suspension, Wettable Powder Application: Agricultural Crops, Residential Pest Control, Turf Management, Public Health End User: Farmers, Agricultural Cooperatives, Pest Control Companies, Government Agencies Distribution Channel: Online Retail, Specialty Stores, Distributors, Wholesale |
| Companies Covered | BASF SE, Bayer CropScience, Syngenta, Dow AgroSciences, Corteva Agriscience, FMC Corporation, Nufarm Limited, UPL Limited, Adama Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chlorpyrifos Market Emerging Trajectories
Formulation chemistry and regulatory positioning are diverging sharply as manufacturers seek to preserve commercial viability while jurisdictions impose incompatible residue protocols. Three active developments are restructuring competitive advantage.
Microencapsulation technology is extending chlorpyrifos persistence in soil matrices while reducing surface water mobility. Large-scale row-crop operators in Brazil and Argentina are adopting these variants for extended protection against soil-dwelling pests. The technology is hybridizing conventional organophosphate chemistry with controlled-release delivery systems that command formulation premiums.
Brazil's ANVISA maintains independent maximum residue limits that frequently exceed EPA stringency for soybean and corn commodities. This divergence creates parallel supply chains where exporters must segregate production lots by destination jurisdiction. Brazilian agricultural cooperatives are responding by demanding batch-specific certification documentation that traces residue compliance from synthesis through export.
Agricultural cooperatives are consolidating procurement decisions across larger geographic footprints, compressing supplier negotiation cycles and unbundling technical advisory services from product purchases. Distributor networks in the United States Midwest and Brazilian Cerrado are losing their traditional service-based lock-in as buyers centralize purchasing through direct manufacturer relationships. This concentration is most visible in Iowa and Illinois grain belts where cooperative mergers have reduced the number of independent decision-makers by half over the past decade.
Global Chlorpyrifos Market Segmentation
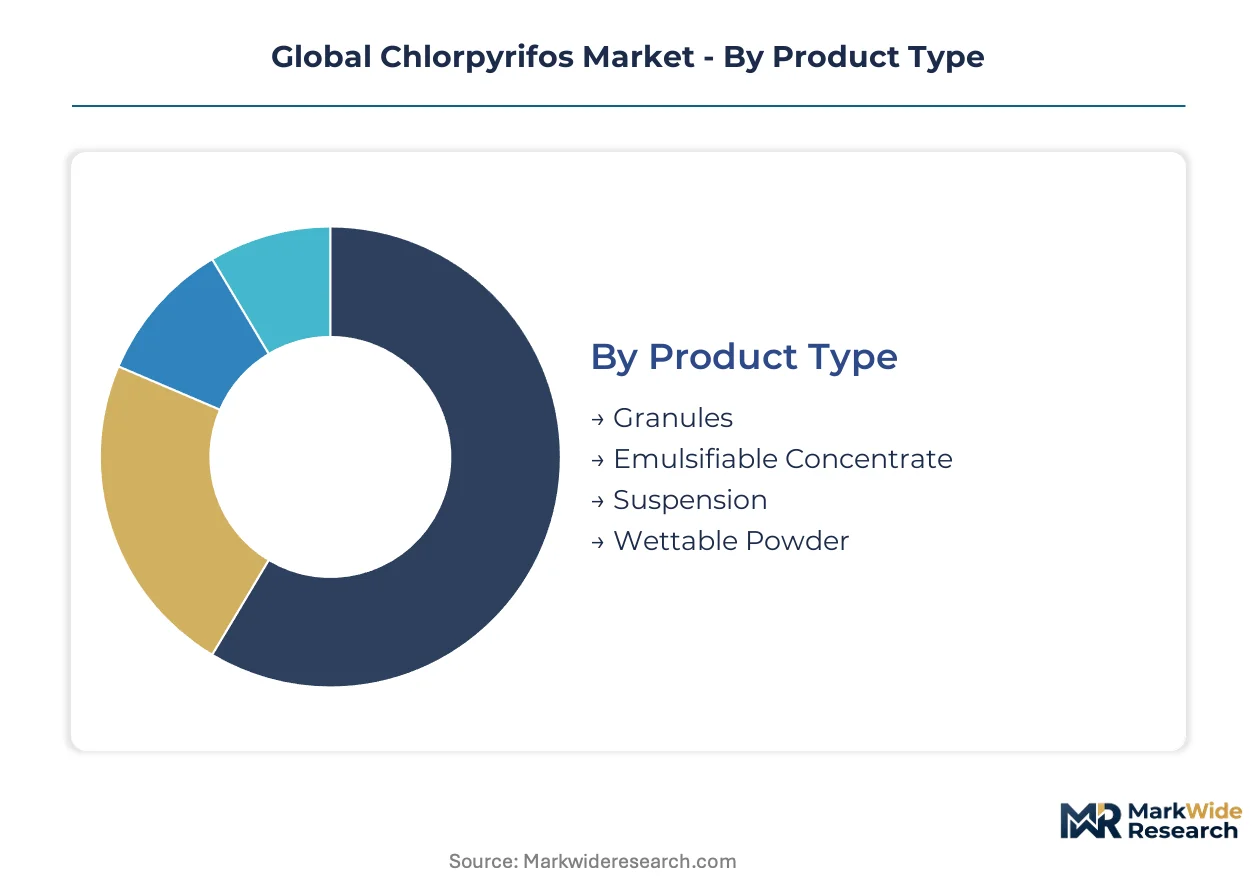
Chlorpyrifos demand fragments across formulation technologies, application contexts, and procurement channels. Each segment carries distinct regulatory exposure and margin profiles that reshape supplier priorities.
Product Type:
Use-case spectrum spans soil-incorporated granules to aerial-spray emulsifiable concentrates, with formulation choice locking in application infrastructure and residue behavior.
- Granules:Slow-release matrix formulations incorporate chlorpyrifos into clay or polymer carriers for soil-banding applications. Demand concentrates in Brazil's soybean belt where subsurface placement reduces surface water runoff concerns under ANVISA protocols.
- Emulsifiable Concentrate:Oil-in-water systems blending technical-grade active ingredient with aromatic solvents and emulsifiers dominate commercial volumes. Established blending infrastructure across Iowa, Illinois, and Mato Grosso states locks in procurement patterns despite drift-related regulatory scrutiny.
- Suspension:Aqueous dispersion formulations reduce solvent exposure for applicator safety. Adoption is climbing fastest in Australian winter cereal regions where ground-rig spraying predominates.
- Wettable Powder:Dry-flowable granules requiring tank-mix hydration face contraction as particulate drift triggers EPA buffer zone expansions.
Established volume favors Emulsifiable Concentrate; emerging adoption favors Suspension.
Application:
Cost tier separation is pronounced: high-volume row-crop agriculture subsidizes specialized turf and public health segments that carry premium pricing but smaller absolute volumes.
- Agricultural Crops:Corn and soybean applications generate consistent demand cycles through soil pest management and foliar rescue treatments. EPA tolerance volatility for food residue allowances creates inventory risk that compresses long-term procurement commitments from Midwest grain cooperatives.
- Residential Pest Control:Perimeter barrier and structural applications face near-complete phase-out in jurisdictions following EU REACH precedents. Surviving demand concentrates in Brazilian urban markets where ANVISA maintains distinct registration pathways.
- Turf Management:Golf course and sod farm applications require low-odor formulations that command formulation premiums. Regulatory pressure from surface water monitoring programs is redirecting procurement toward microencapsulated variants.
- Public Health:Mosquito control programs and vector management operations utilize ultra-low volume formulations. Procurement runs through government tenders with multi-year contract structures that insulate suppliers from annual price volatility.
Margin concentration sits with Public Health; volume concentration sits with Agricultural Crops.
End User:
Customer type determines service bundling intensity: cooperatives demand technical advisory while government agencies prioritize compliance documentation.
- Farmers:Individual operators below cooperative scale purchase through distributor networks with seasonal credit terms. Generic manufacturer erosion of service premiums forces direct manufacturer relationships for price-sensitive accounts.
- Agricultural Cooperatives:Consolidated procurement across Iowa, Illinois, and Paraná state footprints compresses negotiation cycles. Centralized purchasing unbundles technical advisory services from product transactions.
- Pest Control Companies:Licensed applicators require liability insurance alignment with residue limit protocols. Regulatory arbitrage between EPA and ANVISA standards creates certification complexity for multi-jurisdictional operators.
- Government Agencies:Vector control districts and agricultural extension services mandate batch-specific documentation tracing synthesis through application. Tender structures favor suppliers with established regulatory affairs capacity.
Procurement scale favors Agricultural Cooperatives; compliance intensity favors Government Agencies.
Distribution Channel:
Supply concentration varies sharply: wholesale channels capture agricultural bulk while specialty stores retain turf and residential advisory functions.
- Online Retail:E-commerce platforms face regulatory friction as EPA and ANVISA require licensed applicator verification for restricted-use formulations. Surviving transactions concentrate on wettable powder variants with lower regulatory classification.
- Specialty Stores:Independent agricultural supply retailers in the US Midwest and Brazilian Cerrado maintain formulation expertise and tank-mix advisory services. Cooperative mergers reducing independent decision-makers threaten this channel's volume share.
- Distributors:Regional warehousing networks bridge manufacturer scale to end-user accessibility. Inventory risk from EPA tolerance volatility forces just-in-time stocking protocols that elevate logistics costs.
- Wholesale:Direct manufacturer relationships with agricultural cooperatives and government agencies bypass intermediary margins. This channel is expanding fastest as procurement centralization accelerates.
Service integration favors Specialty Stores; volume throughput favors Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil's soybean belt display the lowest price elasticity, accepting formulation premiums for soil pest control, while Midwest US grain cooperatives compress margins through centralized procurement and unbundled technical services.
United States
Corn and soybean applications in Iowa and Illinois sustain emulsifiable concentrate demand through established blending infrastructure. EPA tolerance volatility for food residue allowances creates inventory risk that deters long-term procurement commitments from agricultural cooperatives. Midwest grain belt cooperative mergers have reduced independent decision-makers by half over the past decade, compressing supplier negotiation cycles.
Brazil
Mato Grosso and Paraná state farmers apply chlorpyrifos for wireworm and root borer management where alternative chemistries lack equivalent efficacy. ANVISA maintains independent maximum residue limits that frequently exceed EPA stringency for soybean commodities. Brazilian agricultural cooperatives now demand batch-specific certification documentation tracing residue compliance from synthesis through export.
Argentina
Winter cereal regions in Buenos Aires and Córdoba provinces preserve demand for soil pest control amid limited alternative chemistries for subterranean arthropod management. The country's national agricultural regulator enforces residue protocols that diverge from neighboring Brazil, creating cross-border arbitrage complexity. Pampas grain belt operators are consolidating procurement through direct manufacturer relationships, bypassing traditional distributor networks.
Australia
Ground-rig spraying in Western Australian wheat belts drives suspension formulation adoption for applicator safety. The country's national chemical regulator maintains distinct maximum residue limits for winter cereal exports to Asian markets. New South Wales and Victoria grain regions are adopting microencapsulated variants for extended soil persistence against soil-dwelling pests.
China
Domestic production of technical-grade active ingredient supplies formulation manufacturers across Asia and Latin America. The Ministry of Ecology and Environment enforces environmental compliance standards that redirect surplus volumes toward export markets following EU REACH phase-outs. Shandong and Jiangsu province chemical clusters concentrate multi-step synthesis capacity involving phosphoryl chloride and 3,5,6-trichloro-2-pyridinol intermediates.
Global Chlorpyrifos Market Vendor Landscape
Capability concentration sits with integrated agrochemical conglomerates possessing formulation expertise and multi-jurisdictional registration portfolios; scale advantage sits with generic manufacturers eroding service premiums through price compression. The market structures around three archetypes: premium-formulation specialists defending emulsifiable concentrate stability profiles, dual-registered exporters exploiting ANVISA-EPA arbitrage, and unbranded suppliers capturing price-sensitive accounts. Dominant competitive moves include geographic concentration in less restrictive residue jurisdictions and integrated pest management bundling with biological adjuvants.
Within the premium-formulation tier, BASF SE and Bayer CropScience occupy positions anchored by emulsifiable concentrate expertise and integrated pest management portfolio architecture. Corteva Agriscience exemplifies geographic concentration strategy, sitting within regions where residue protocols permit sustained market access. These three entities represent divergent responses to regulatory fragmentation: formulation premium defense, biological bundling, and jurisdictional arbitrage respectively.
| Leading Market Players |
|---|
| BASF SE |
| Bayer CropScience |
| Syngenta |
| Dow AgroSciences |
| Corteva Agriscience |
| FMC Corporation |
| Nufarm Limited |
| UPL Limited |
| Adama Agricultural Solutions |
| Others |
Supply Flow & Price Mechanics
Shandong and Jiangsu province chemical clusters in China concentrate multi-step synthesis capacity for phosphoryl chloride and 3,5,6-trichloro-2-pyridinol intermediates, anchoring global technical-grade supply and downstream pricing power for formulators across Brazil and the United States.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between agricultural cooperatives and integrated manufacturers, insulating volume commitments from spot volatility. Price differentiation rests on formulation grade and ANVISA-EPA dual-registration certification, with emulsifiable concentrate stability profiles commanding premiums over generic alternatives. Cost compression in unbranded tiers is intensifying because generic manufacturers erode service premiums without equivalent technical support. Midwest grain cooperatives exhibit the highest price sensitivity through centralized procurement, while Brazilian soybean belt buyers accept formulation premiums for wireworm management efficacy.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Shandong and Jiangsu province manufacturers support working capital for Brazilian and Argentine distributors. Raw material dependencies draw from phosphorus trichloride, pyridine derivatives, and chlorination reagents. Single-source vulnerability concentrates in Chinese intermediate production following EU REACH phase-outs that eliminated European supply alternatives. Distribution runs through regional warehousing networks bridging manufacturer scale to agricultural cooperative accessibility, with inventory risk from EPA tolerance volatility forcing just-in-time stocking protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where multi-jurisdictional registration portfolios create prohibitive switching costs for new entrants and sustain incumbent pricing power.
For Market Incumbents: Harden formulation expertise barriers by investing in microencapsulation R&D and backward integration into 3,5,6-trichloro-2-pyridinol intermediate production. Defend against generic manufacturer erosion through integrated pest management bundles that combine chlorpyrifos with biological adjuvants, creating service differentiation that unbranded competitors cannot replicate. For New Entrants and Emerging Players: Soil pest control gaps in Argentina's Pampas grain belt and Australia's Western Australian wheat regions represent the most penetrable entry points where limited alternative chemistries preserve demand. Target suspension formulation segments for ground-rig spraying applications with lower regulatory classification than emulsifiable concentrates. Pursue direct manufacturer relationships with consolidating agricultural cooperatives bypassing traditional distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between ANVISA and EPA maximum residue limits creates persistent premium pricing opportunities for dual-registered exporters. Acquisition targets should possess formulation expertise in emulsifiable concentrate stability profiles and established regulatory affairs capacity across Latin American jurisdictions. Monitor pending EPA administrative court decisions as the critical inflection signal for abrupt supply disruptions or reopened market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Captive supply of 3,5,6-trichloro-2-pyridinol reduces exposure to Chinese price volatility. |
| Microencapsulation Technology Investment | Extended soil persistence commands formulation premiums in Brazilian soybean applications. |
| Dual-Registration Portfolio Expansion | ANVISA-EPA arbitrage enables premium pricing for residue-compliant export lots. |
| Integrated Pest Management Bundling | Biological adjuvant combinations defend margins against generic price compression. |
| Direct Cooperative Relationship Development | Bypassing distributor networks captures volume from Midwest and Cerrado consolidation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with agricultural cooperative procurement directors, formulation plant managers at BASF SE and Bayer CropScience, ANVISA regulatory affairs specialists, and Midwest distributor network heads. Secondary validation drew from EPA administrative rulings, ANVISA residue limit protocols, customs trade data on phosphoryl chloride flows, and SEC 10-K filings of listed agrochemical conglomerates. Bottom-up volume estimates from end-user segments were triangulated against top-down production capacity assessments across Shandong and Jiangsu province chemical clusters.
Calibration against historical tolerance volatility episodes and REACH phase-out redirection patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation technology, application context, end-user procurement scale, and regional regulatory cluster. CAGRs were derived through regression analysis of volume-price elasticities and substitution threat trajectories, incorporating wireworm infestation cycles in Mato Grosso and cooperative merger patterns in Iowa and Illinois as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Chinese environmental enforcement intensity, or EPA administrative litigation outcomes would shift the trajectory. Forecasts reflect documented assumptions on registration continuity and intermediate supply availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Fogger Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Pest Control Services Market
Crop Protection
Crop Bactericides Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Europe Insecticides Market
Crop Protection
Vietnam Herbicide Market