
 North America Molluscicides Market | 2026-2036
North America Molluscicides Market Size, Share, and Industry Trends Forecast 2026-2036
North America Molluscicides Market Analytics
Asset-light distribution leasing is rewriting competitive economics for regional molluscicide suppliers. Bayer leverages its crop science infrastructure to sustain channel control across Midwest row-crop territories. American Vanguard Corporation anchors its position through backward integration into active ingredient sourcing. Neudorff USA Inc specializes in iron phosphate formulations for organic-certified operations.
North America molluscicides comprise chemical and biological formulations designed to control gastropod pests, with metaldehyde and iron phosphate serving as the dominant active ingredients through neurotoxic or desiccant modes of action. These products protect high-value agricultural and ornamental plantings from yield losses exceeding threshold damage levels in temperate and subtropical growing zones. Iron phosphate formulations now lead product type demand as regulatory pressure on metaldehyde intensifies across multiple jurisdictions. Application in turf and ornamentals represents a concentrated margin pool where residential and golf-course end users command premium pricing. Agricultural crop applications retain volume dominance through integrated pest management protocols in specialty vegetable production.
EPA Office of Chemical Safety and Pollution Prevention oversees molluscicide registration under FIFRA, with state-level departments of agriculture in California, Florida, and New York imposing supplemental use restrictions that fragment compliance requirements. Health Canada PMRA maintains parallel regulatory thresholds for cross-border product approval, creating dual-track submission burdens for suppliers serving both national markets. Stakeholders must monitor pending EPA ecological risk assessments for metaldehyde and position formulation portfolios toward lower-toxicity chemistries before restrictive determinations crystallize.
Market Dynamics
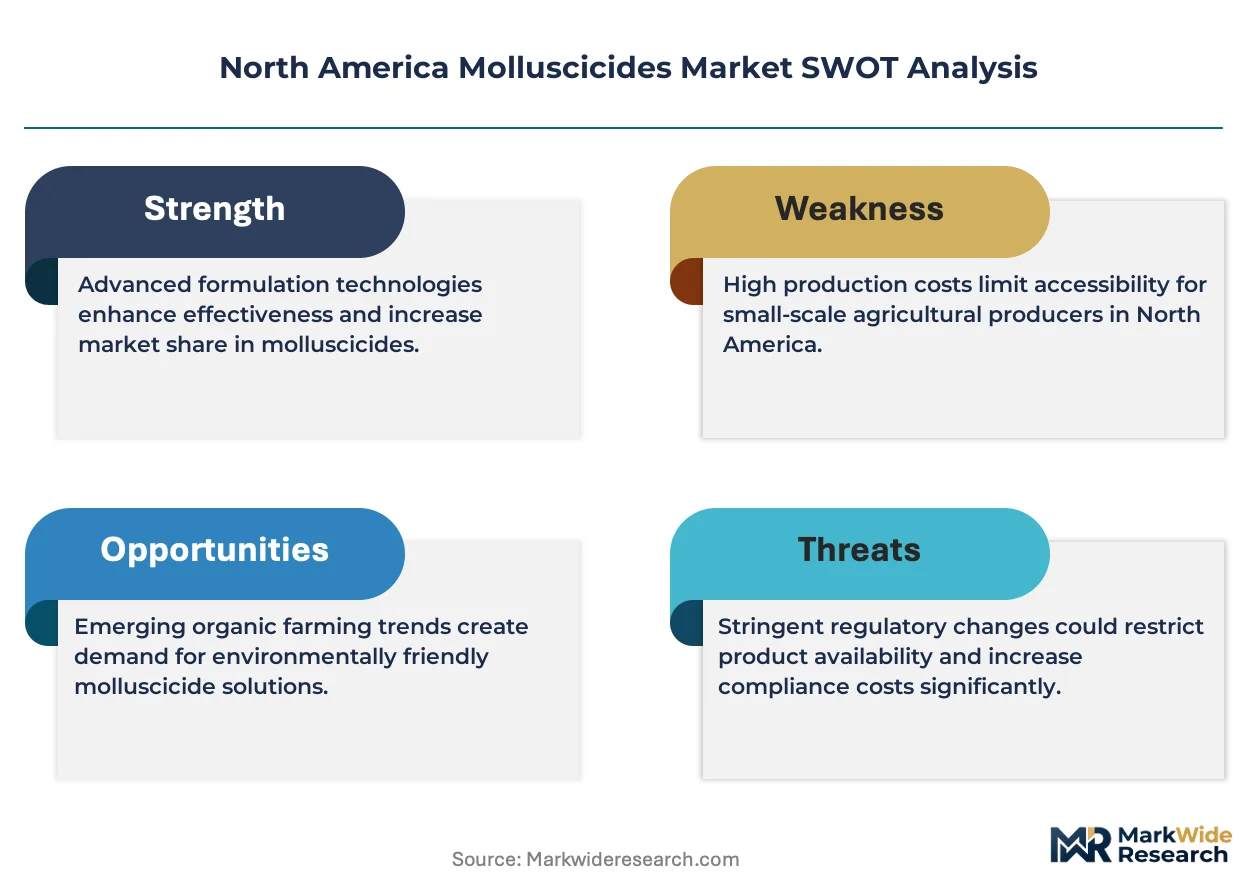
EPA ecological risk assessments for metaldehyde are accelerating formulation portfolio pivots toward iron phosphate alternatives, compressing product development timelines and reshaping competitive positioning across state-level regulatory patchworks.
Growth Catalysts
- California Department of Pesticide Regulation restrictions:State-level use limitations on neurotoxic chemistries create immediate demand pull for desiccant-mode alternatives in specialty vegetable production corridors.
- Organic-certified acreage expansion:Iron phosphate formulations capture volume as certified operations in the Pacific Northwest and Northeast corridors face gastropod pressure thresholds.
- Integrated pest management protocol adoption:Specialty crop growers in Florida embed molluscicide applications within broader pest control frameworks, sustaining recurring purchase cycles.
Market Restraints
- Active ingredient supply concentration:Technical-grade metaldehyde production concentrates among limited European suppliers, exposing formulators to cross-border shipment delays and input cost volatility.
- Dual-track registration burden:Health Canada PMRA maintains distinct efficacy and residue thresholds from EPA FIFRA requirements, forcing redundant toxicology studies and submission costs for cross-border suppliers.
- Biological substitute efficacy gaps:Nematode-based gastropod controls demonstrate inconsistent performance across variable soil moisture conditions, limiting displacement of chemical formulations in high-pressure growing zones.
Strategic Opportunities
- Underpenetrated golf course superintendent channel:Turf and ornamental applications in the Desert Southwest and Southeast corridors remain below saturation, offering premium pricing capture for targeted formulation development.
- Drone-based precision application convergence:Unmanned aerial systems paired with GIS-mapped infestation zones enable variable-rate molluscicide deployment, reducing per-acre chemical load while improving efficacy outcomes.
- USDA Organic certification tailwinds:Federal procurement preferences for organically produced commodities cascade through supply chains, mandating input chemistry restrictions that favor iron phosphate adoption.
Industry Challenges
- Formulation chemist talent scarcity:Expertise in gastropod-specific bait matrix optimization sits with aging technical specialists, constraining R&D pipeline velocity for next-generation products.
- State-by-state label expansion complexity:California, New York, and Florida impose supplemental data requirements beyond federal registration, fragmenting compliance workflows and extending commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Molluscicides Market |
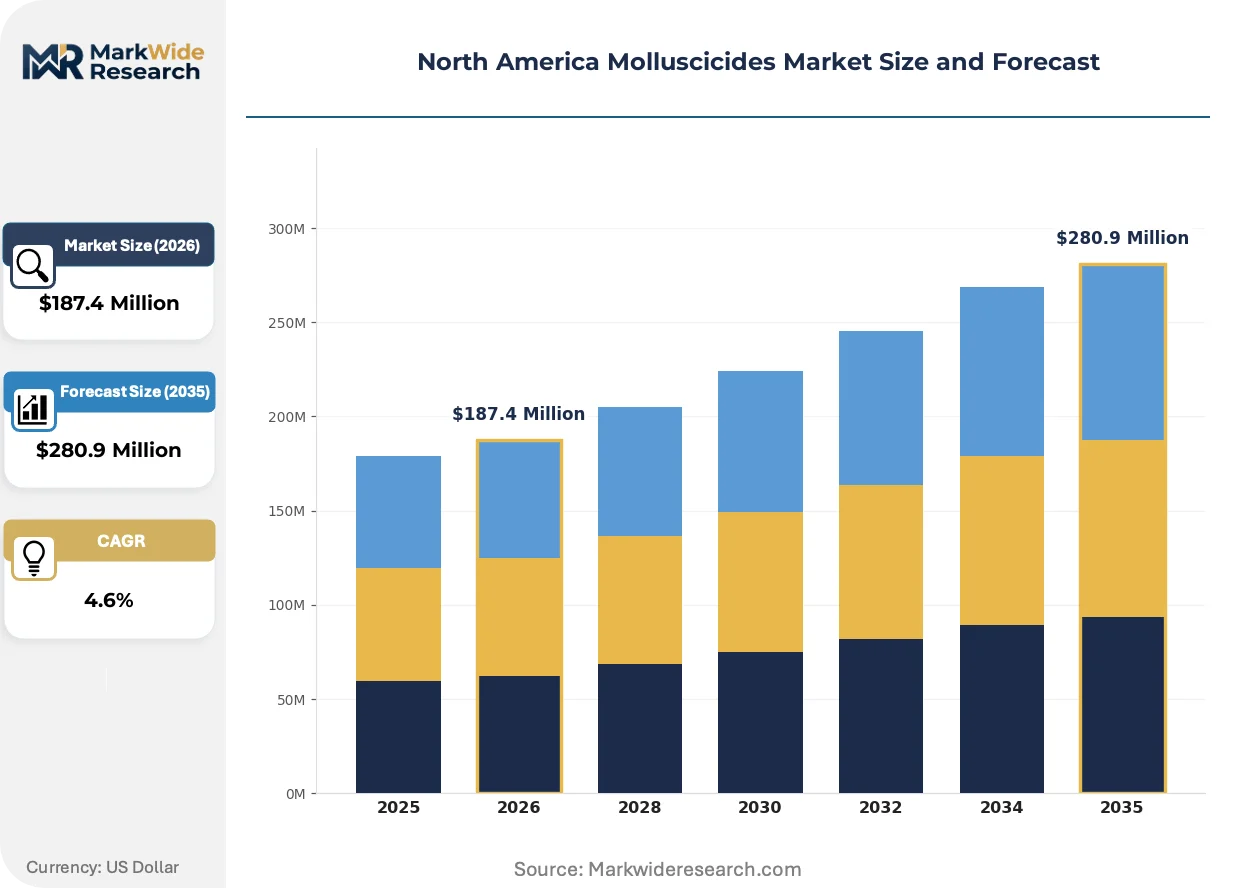
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Phosphate, Metaldahyde, Sodium Ferric EDTA, Natural Molluscicides Application: Agricultural Crop, Horticultural Crop, Turf & Ornamentals, Aquatic Systems End User: Farmers, Commercial Growers, Government Agencies, Residential Users Distribution Channel: Online Retail, Specialty Stores, Agricultural Supply Stores, Direct Sales |
| Companies Covered | Bayer, Arxada, American Vanguard Corporation, Spectrum Brands Inc, Certis USA LLC, Neudorff USA Inc, Monterey Lawn & Garden, Amvac Chemical Corporation, Farmco Agritrading Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Molluscicides Market Evolving Landscape
Formulation science and application technology are compressing the performance gap between conventional neurotoxic chemistries and lower-toxicity alternatives, while digital tools reshape how growers monitor gastropod pressure and time interventions.
Microencapsulated iron phosphate delivery systems with enhanced moisture resistance are rendering obsolete the efficacy advantage historically held by metaldehyde in wet-climate growing zones. Specialty lettuce and strawberry operations in coastal California are adopting these formulations at accelerated rates. The technology is compressing the premium pricing window that metaldehyde commanded for decades.
EPA Office of Chemical Safety and Pollution Prevention pending determinations on metaldehyde ecological risk are forcing preemptive portfolio rebalancing among established suppliers. The industrial consequence is accelerated R&D allocation toward biological and desiccant-mode alternatives before restrictive labels crystallize. Agricultural crop applications face the most acute exposure, with suppliers diversifying active ingredient sourcing to reduce concentration risk.
Subscription-based agronomic advisory services bundled with molluscicide procurement are displacing traditional distributor-led transactions in high-value specialty crop segments. These integrated offerings combine pest pressure monitoring, application timing optimization, and just-in-time product delivery. The model has gained strongest traction among medium-scale vegetable operations in the Central Coast and Imperial Valley production clusters.
North America Molluscicides Market Segmentation
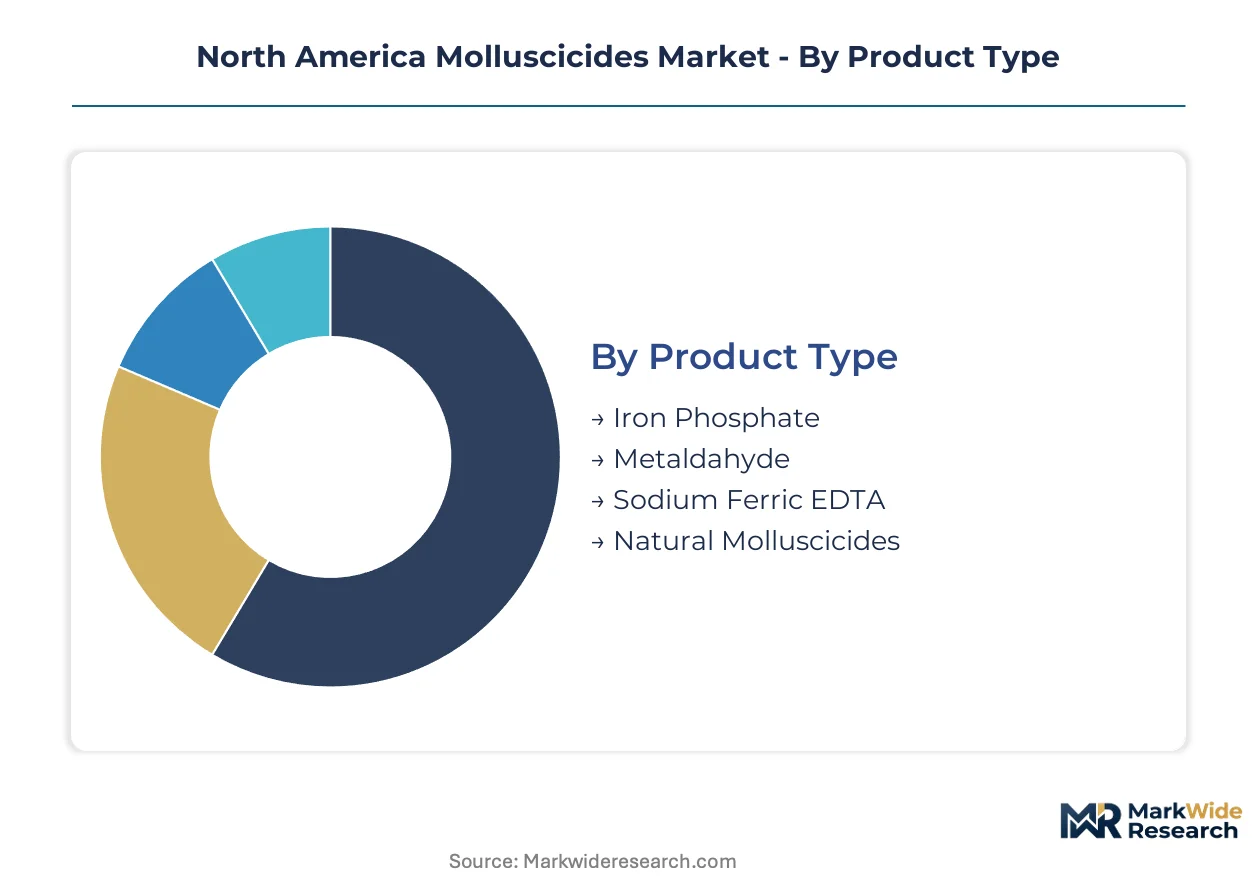
Segmentation in the North America molluscicides market reveals how regulatory pressure, end-use economics, and channel dynamics fragment demand across distinct buyer profiles and application contexts. Understanding these splits enables suppliers to align formulation portfolios with the specific compliance thresholds and performance expectations governing each segment.
Product Type:
Use-case spectrum spans neurotoxic chemistries for conventional agriculture through desiccant-mode alternatives serving organic-certified operations and state-restricted jurisdictions.
- Iron Phosphate:Desiccant-mode formulation triggering mucus secretion and dehydration in target gastropods. Demand concentrates in California specialty vegetable corridors and Pacific Northwest certified organic acreage as state-level metaldehyde restrictions tighten. EPA ecological risk assessments accelerate grower migration toward this lower-toxicity chemistry.
- Metaldehyde:Neurotoxic active ingredient disrupting acetylcholinesterase function in gastropod nervous systems. Florida strawberry and tomato operations retain volume share where moisture resistance and rapid knockdown remain critical, though California Department of Pesticide Regulation restrictions compress accessible geography.
- Sodium Ferric EDTA:Chelated iron formulation combining efficacy with reduced non-target toxicity profile. Northeast corridor golf courses and residential applications favor this chemistry amid municipal runoff concerns.
- Natural Molluscicides:Plant-derived extracts and biological fermentation products targeting certified organic operations. Inconsistent batch potency and variable field performance limit penetration beyond niche greenhouse applications.
Established volume favors metaldehyde; emerging adoption favors iron phosphate.
Application:
Margin structure diverges sharply between high-frequency agricultural protocols and premium-priced amenity turf installations.
- Agricultural Crop:Integrated pest management protocols in lettuce, strawberry, and tomato production drive recurring application cycles. California Central Coast and Imperial Valley operations generate concentrated demand for labeled chemistries compliant with export residue thresholds.
- Horticultural Crop:Greenhouse and nursery operations require precision bait placement in controlled-environment systems. Pacific Northwest ornamental producers prioritize iron phosphate formulations to maintain organic certification eligibility.
- Turf & Ornamentals:Golf course superintendents and residential lawn care operators command premium pricing for rapid-acting formulations. Desert Southwest and Southeast corridors show underpenetrated superintendent channels with above-average margin capture potential.
- Aquatic Systems:Specialized formulations for irrigation reservoirs and water features face EPA aquatic toxicity testing requirements that extend registration timelines and limit supplier participation.
Volume concentration sits with agricultural crop applications; steepest expansion trajectory emerges in turf and ornamentals.
End User:
Procurement sophistication ranges from price-sensitive residential consumers through technical buyers demanding efficacy documentation and regulatory compliance support.
- Farmers:Row-crop and specialty vegetable operators purchasing through cooperative buying groups and agricultural supply stores. Midwest grain producers show sporadic demand tied to no-till adoption and residue management protocols.
- Commercial Growers:Large-scale greenhouse and nursery operations with dedicated pest management staff. These buyers demand batch consistency data and prefer direct supplier relationships for technical support.
- Government Agencies:Vector control districts and park management authorities procuring through formal bid processes. California county agricultural commissioners influence local use patterns through supplemental permitting requirements.
- Residential Users:Homeowners purchasing small-format retail products through big-box and online channels. Price sensitivity dominates with limited brand loyalty and minimal technical knowledge.
Procurement scale favors commercial growers; regulatory influence favors government agencies.
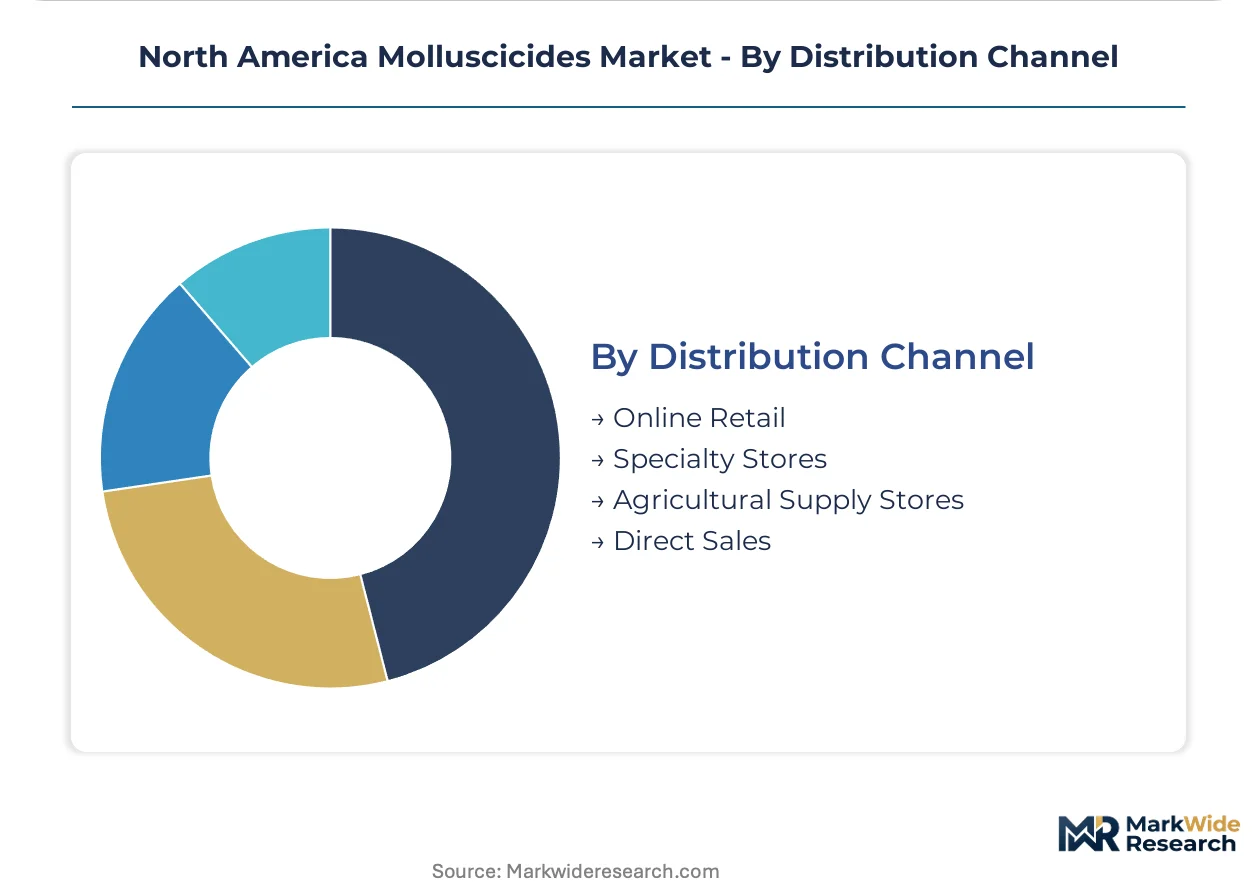
Distribution Channel:
Channel selection reflects buyer technical requirements, urgency of need, and access to application guidance.
- Online Retail:E-commerce platforms capturing residential and small-scale commercial demand with 24-48 hour fulfillment. Product reviews and comparison tools displace traditional dealer recommendations for non-technical buyers.
- Specialty Stores:Independent garden centers and farm supply retailers providing localized expertise and immediate product availability. Northeast and Midwest independent networks retain loyalty among established growers.
- Agricultural Supply Stores:Regional cooperatives and input distributors serving commercial farming operations with credit terms and volume pricing. These channels bundle molluscicide procurement with broader crop protection purchasing.
- Direct Sales:Manufacturer field representatives engaging large commercial accounts and government procurement officers. Technical consultation and custom formulation services accompany direct relationships.
Transaction velocity favors online retail; technical support integration favors agricultural supply stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level regulatory divergence across North America is accelerating regional specialization in molluscicide formulation preferences and channel strategies.
United States
California specialty vegetable corridors and Florida strawberry belts drive concentrated demand for EPA-compliant chemistries. The California Department of Pesticide Regulation imposes supplemental use restrictions beyond federal FIFRA requirements. Central Coast lettuce operations and Imperial Valley tomato clusters are pivoting toward iron phosphate formulations ahead of pending metaldehyde ecological risk determinations.
Canada
Health Canada PMRA maintains distinct efficacy and residue thresholds that force redundant toxicology studies for cross-border suppliers. British Columbia certified organic acreage and Ontario greenhouse operations generate parallel demand for lower-toxicity alternatives. The PMRA registration timeline for new active ingredients extends commercialization windows by 12-18 months relative to EPA pathways.
Mexico
Baja California export-oriented vegetable production and Sinaloa tomato corridors require residue profiles aligned with US import thresholds. Mexican federal pesticide regulator CICOPLAFEST coordinates with EPA through NAFTA-era harmonization protocols. Guanajuato strawberry clusters are adopting integrated pest management protocols that embed molluscicide applications within broader crop protection frameworks.
North America Molluscicides Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified agrochemical conglomerates with crop science infrastructure, specialty formulators with backward integration into active ingredient sourcing, and regional distributors with asset-light leasing models. Competitive positioning depends on EPA registration velocity and state-level label expansion capabilities. M&A activity concentrates on formulation technology acquisitions, while geographic expansion targets underpenetrated golf course superintendent channels in the Desert Southwest.
Among diversified agrochemical conglomerates, Bayer leverages existing crop science infrastructure to sustain channel control across Midwest row-crop territories. American Vanguard Corporation anchors the specialty formulator tier through upstream control over active ingredient sourcing. Neudorff USA Inc exemplifies the regional specialist archetype with focused iron phosphate formulation capabilities for organic-certified operations.
| Leading Market Players |
|---|
| Bayer |
| Arxada |
| American Vanguard Corporation |
| Spectrum Brands Inc |
| Certis USA LLC |
| Neudorff USA Inc |
| Monterey Lawn & Garden |
| Amvac Chemical Corporation |
| Farmco Agritrading Ltd |
| Others |
Value Network & Pricing Analysis
Underutilized technical-grade metaldehyde capacity in European manufacturing hubs is compressing input costs for conventional formulators while accelerating migration toward iron phosphate alternatives among price-insensitive organic-certified buyers. This divergence is fragmenting supplier pricing power across state-level regulatory boundaries.
Pricing Analysis
Certification level (organic versus conventional) creates the primary spread between premium iron phosphate formulations and commodity metaldehyde baits. Three-tier pricing structure across premium, standard, and economy levels captures volume discounts for agricultural cooperatives, brand premiums for golf course channels, and compliance-driven premiums for California Department of Pesticide Regulation-restricted jurisdictions. Cost compression in metaldehyde tiers is intensifying because European feedstock oversupply is extending contract pricing windows. Residential retail channels exhibit highest price sensitivity; commercial growers with export residue requirements show lowest.
Supply Chain Analysis
Technical-grade metaldehyde feedstock concentrates in Germany, France, and Italy among limited specialty chemical manufacturers. Iron phosphate draws from domestic mining operations in Minnesota and Utah, with chelated variants sourcing from Chinese ferric EDTA processors. Single-source vulnerability sits with European neurotoxic active ingredient suppliers exposed to cross-border shipment delays. Distribution runs through agricultural supply cooperatives bundling molluscicide procurement with broader crop protection purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist expertise in gastropod-specific bait matrix optimization has contracted to a narrow cohort of aging specialists, constraining R&D velocity and amplifying acquisition premiums for technical talent. This scarcity is reshaping competitive moats around incumbent suppliers.
For Market Incumbents: Harden EPA registration velocity capabilities through preemptive toxicology investment ahead of ecological risk determinations. Deepen backward integration into iron phosphate sourcing to reduce European metaldehyde concentration exposure. Channel control through subscription-based agronomic advisory bundling defends margin position against distributor disintermediation. For New Entrants and Emerging Players: Desert Southwest golf course superintendent channels offer the most penetrable white-space target, with above-average pricing tolerance and limited incumbent technical service presence. Drone-based precision application convergence enables differentiated go-to-market positioning through variable-rate deployment partnerships with unmanned aerial systems operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-model agronomic advisory services bundling pest pressure monitoring with just-in-time product delivery. Long-term viability over the five-to-ten year window favors formulators with diversified active ingredient portfolios ahead of restrictive metaldehyde label crystallization. Acquisition target archetype: regional iron phosphate specialists with California Department of Pesticide Regulation label expansion capabilities. The signal to watch is EPA Office of Chemical Safety and Pollution Prevention publication timeline for pending ecological risk assessments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Sourcing | Captive supply of iron phosphate reduces European metaldehyde dependency and input cost volatility. |
| Drone-Based Precision Application Partnership | Unmanned aerial systems integration enables variable-rate deployment and technical service differentiation. |
| Subscription Agronomic Advisory Launch | Recurring-revenue bundling displaces transactional distributor relationships in specialty crop segments. |
| California Label Expansion Investment | Supplemental data submissions ahead of metaldehyde restrictions secure Central Coast lettuce corridor access. |
| Formulation Chemist Talent Acquisition | Technical R&D pipeline velocity depends on scarce gastropod bait matrix optimization expertise. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with EPA registration consultants, formulation R&D directors, agricultural supply cooperative procurement managers, and golf course superintendent purchasing committees; and secondary validation through EPA FIFRA registration databases, Health Canada PMRA submission records, California Department of Pesticide Regulation use reports, and SEC 10-K filings of listed agrochemical suppliers. Bottom-up volume triangulation across product type and application segments was cross-checked against top-down market sizing.
Forecast inputs considered active ingredient regulatory status trajectories, organic-certified acreage expansion patterns, and integrated pest management protocol adoption rates across the projection horizon. Segmentation dimensions modeled include product chemistry mode of action, end-use application intensity, buyer procurement sophistication, and state-level regulatory restrictiveness. CAGRs were derived from segment-level volume buildups calibrated to historical registration timelines and grower switching cost assumptions.
Practitioners should monitor EPA ecological risk assessment publication schedules and state-level metaldehyde restriction enactment timelines for early signals of portfolio rebalancing urgency. Forecasts reflect assumptions regarding regulatory harmonization between EPA and Health Canada PMRA pathways that may not materialize. Cross-checking against USDA National Agricultural Statistics Service certified organic acreage reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Tebuconazole Market
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
Fumigation Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Azoxystrobin Market
Crop Protection
Iprodione Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Larvicides Market
Crop Protection
Pest Control Services Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
South America Nematicides Market