
 Europe Fungicide Market | 2026-2036
Europe Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fungicide Market Insights
Vineyard protection and specialty vegetable cultivation is rebalancing demand toward targeted systemic chemistries across Southern Europe. Bayer AG leverages extensive field trial networks to sustain registration advantages for triazole-based portfolios. BASF SE anchors its position through proprietary SDHI molecule pipelines. Syngenta Group competes on integrated disease management platforms that bundle fungicides with seed treatments.
Fungicides constitute biocidal or plant protection agents formulated to inhibit or eradicate fungal pathogens affecting crops, ornamentals, and turf, typically containing active ingredients such as azoles, strobilurins, or microbial antagonists applied at specified dose rates per hectare. Their primary commercial purpose centers on yield preservation and post-harvest quality maintenance in intensive agricultural systems. Systemic fungicides occupy the dominant value share due to curative activity and extended protection windows, while biological fungicides represent the fastest-expanding category as organic hectarage multiplies under EU subsidy realignment. Liquid formulations lead volume consumption in arable applications, though granular formats gain traction in precision horticulture where root-zone targeting reduces drift exposure.
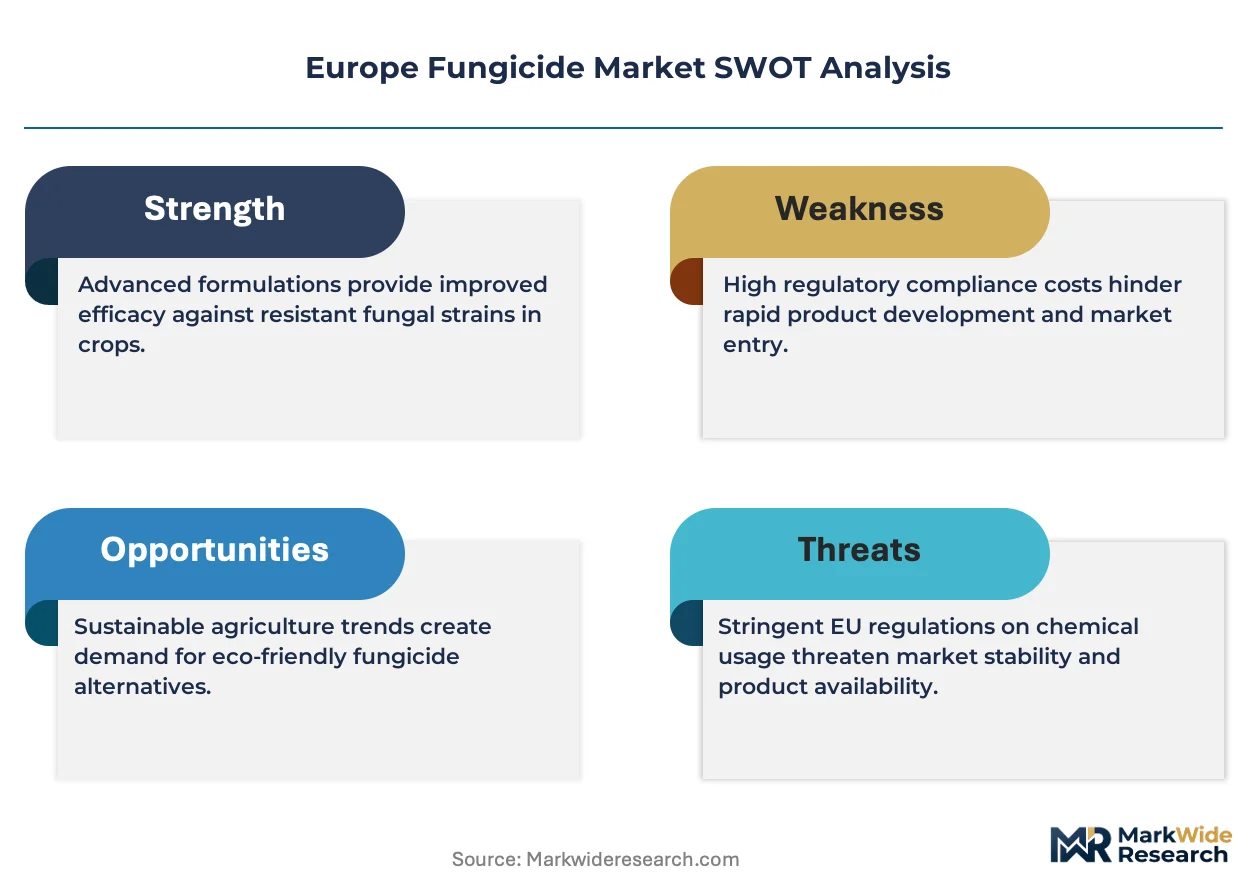
The European Food Safety Authority and national regulators under EU Regulation 1107/2009 govern active substance approval, while the EU Green Deal's pesticide reduction targets reshape product portfolios toward low-risk candidates. REACH compliance adds toxicity testing burdens that filter marginal suppliers from the registration pipeline. Stakeholders must monitor the accelerating substitution of conventional multisite fungicides with biocontrol agents and assess how resistance management mandates in France and Germany will restructure portfolio priorities without explicit phase-out calendars.
Market Dynamics
EU Regulation 1107/2009 and the Green Deal's pesticide reduction targets are compressing the registration pipeline for conventional chemistries while elevating biological alternatives to commercial viability. This regulatory compression is redrawing competitive boundaries between synthetic incumbents and microbial newcomers.
Growth Catalysts
- EU Green Deal targets:The Farm to Fork Strategy mandates 50% pesticide reduction by 2030, accelerating grower transition to low-risk biological formulations and creating regulatory tailwinds for microbial antagonists.
- France's resistance management protocols:Mandatory rotation schemes in cereal-intensive regions force product diversification, sustaining demand for novel mode-of-action chemistries and tank-mix combinations.
- SDHI molecule pipelines:Proprietary succinate dehydrogenase inhibitors deliver curative activity against septoria and rust pathogens, commanding premium positioning in German and Polish wheat systems.
Market Restraints
- Active substance approval timelines:EFSA risk assessment backlogs stretch registration cycles to 8-11 years, freezing pipeline investments for mid-tier developers lacking regulatory war chests.
- Chinese technical grade concentration:Over 70% of azole and strobilurin intermediates originate from Shandong and Jiangsu provinces, exposing formulators to freight volatility and geopolitical friction.
- Cross-resistance limitations:Widespread CYP51 mutations in powdery mildew populations across Northern Italy vineyards render older triazoles ineffective, compressing viable chemistry pools.
Strategic Opportunities
- Spanish precision horticulture:Almería's greenhouse cluster generates concentrated demand for root-zone targeted granular formulations with drift-minimizing application systems.
- CSRD disclosure mandates:Corporate sustainability reporting requirements push food processors to audit supply chain residue profiles, creating preference premiums for certified low-residue programs.
- RNA interference convergence:Spray-induced gene silencing technology paired with existing biological delivery infrastructure opens new target specificity in specialty crop protection.
Industry Challenges
- Field trial capacity constraints:Efficacy demonstration requirements under zonal authorization procedures outstrip available trial station capacity in Central and Eastern Europe, delaying dossier submissions.
- Biological formulation stability:Shelf-life limitations for live microbial products complicate inventory management through existing agrochemical distribution networks built for synthetic chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fungicide Market |
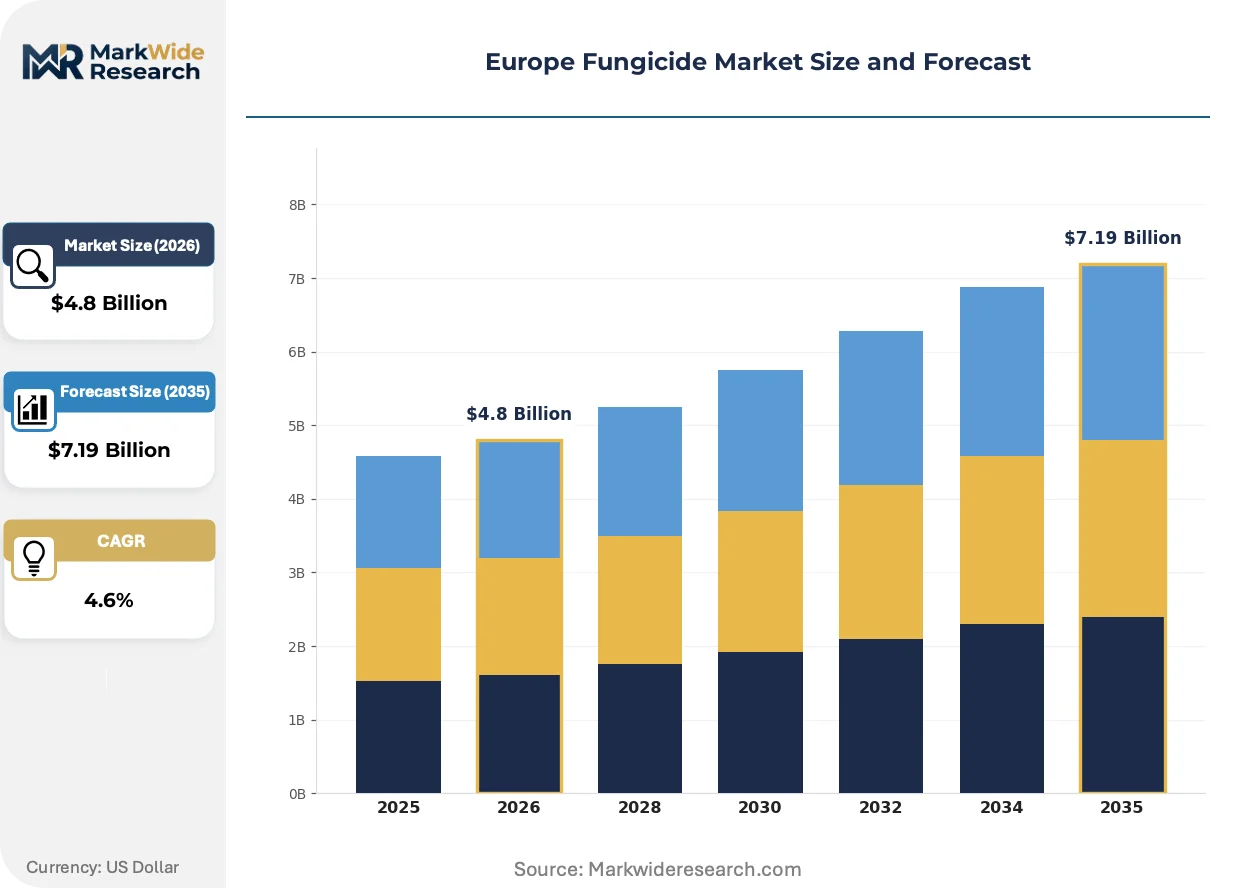
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Fungicides, Systemic Fungicides, Biological Fungicides, Combination Fungicides End Use Industry: Agriculture, Horticulture, Turf Management, Forestry Chemical Composition: Synthetic Fungicides, Organic Fungicides, Mineral Fungicides, Others Formulation Type: Liquid Formulations, Powder Formulations, Granular Formulations, Emulsifiable Concentrates |
| Companies Covered | Corteva Agriscience, FMC Corporation, Syngenta Group, ADAMA Agricultural Solutions Ltd, Nufarm Ltd, BASF SE, UPL Limited, Sumitomo Chemical Co. Ltd, Bayer AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fungicide Market Trends and Innovations
Biological fungicide platforms are maturing from niche organic applications into mainstream integrated pest management protocols, driven by residue compliance pressures and subsidy realignment. Formulation chemistry and delivery precision now determine competitive differentiation as much as active ingredient efficacy.
Microbial antagonists derived from Trichoderma and Bacillus species are overtaking conventional multisite protectants in vineyard and greenhouse applications. Spanish and Italian growers facing export market Maximum Residue Limits are adopting these biocontrol agents at twice the rate of Northern European cereal producers. The technology is compressing synthetic fungicide application windows and forcing incumbents to bundle biological components into proprietary disease management platforms.
REACH authorization requirements are tightening toxicity testing burdens for co-formulants and impurities, not just active substances. ECHA's 2024-2025 substance evaluation work program prioritizes endocrine disruptor screening, forcing reformulation of several triazole-based products before renewal deadlines. Vineyards in France's Champagne and Bordeaux appellations are most affected, with cooperatives accelerating trials on reduced-rate programs and biological alternation.
Consolidated buying through agricultural cooperatives and processor-backed grower associations is displacing independent distributor relationships in key cereal regions. French cooperative groups and German Raiffeisen structures now contract directly with manufacturers for volume commitments, extracting price concessions and technical service bundling. This concentration is most visible in Poland's maturing farm sector, where 500+ hectare operations negotiate supply agreements bypassing traditional retail channels.
Europe Fungicide Market Segmentation
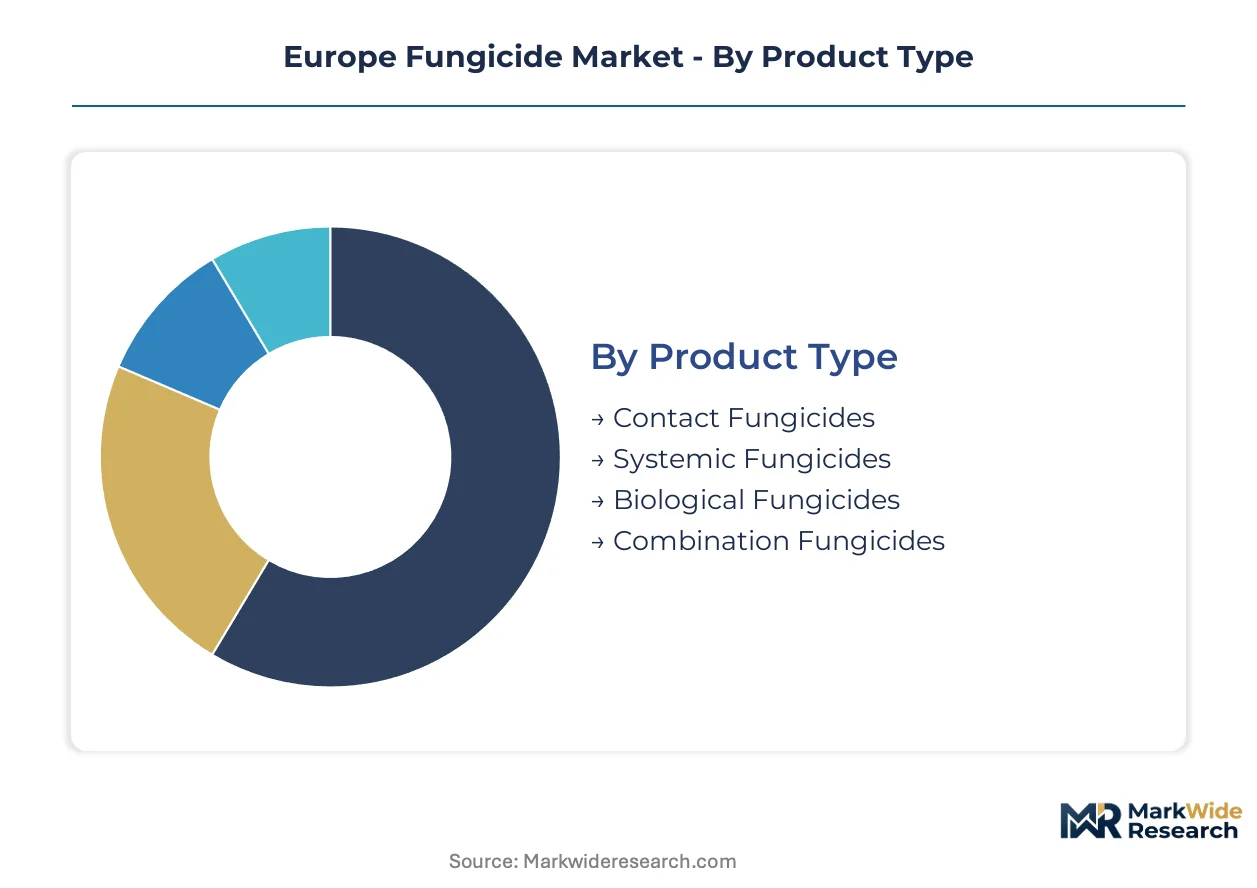
Fungicide segmentation in Europe reflects divergent pressure points: residue compliance tightening under EFSA protocols, resistance management mandates in France and Germany, and the subsidy-driven expansion of organic hectarage. Product chemistry, application method, and end-use intensity each reshape procurement priorities across Mediterranean specialty crops and Northern cereal belts.
Product Type:
Technology sophistication determines protection windows and curative capacity, with uptake patterns splitting between established synthetic platforms and emerging biological alternatives.
- Systemic Fungicides:These chemistries translocate through plant vascular systems to eradicate established infections, commanding dominant value share in French wheat and German vineyard corridors where septoria and downy mildew pressure necessitate curative intervention. EFSA renewal timelines and resistance management protocols in Champagne and Bordeaux force rotation with novel SDHI molecules.
- Biological Fungicides:Microbial antagonists derived from Trichoderma and Bacillus species deliver residue-free protection aligned with EU Green Deal targets, expanding most quickly in Spanish greenhouse clusters and Italian organic vineyards where export market MRLs constrain synthetic options. Shelf-life limitations complicate distribution through networks built for chemical stability.
- Contact Fungicides:Surface-acting protectants form physical barriers against pathogen entry, retaining niche positioning in Polish cereal programs and Almería vegetable production where preventive schedules dominate.
- Combination Fungicides:Pre-mixed formulations blending multiple modes of action simplify tank-mix logistics for cooperatives managing resistance protocols across extensive hectarage.
Mature deployment sits with Systemic Fungicides. Newer deployment is concentrated in Biological Fungicides.
End Use Industry:
Intensity of disease pressure and export market exposure drive segmentation, with value-per-hectare diverging sharply between commodity grains and protected horticulture.
- Agriculture:Extensive cereal cultivation across France's Beauce region and Germany's North German Plain generates volume demand for azole and strobilurin-based protection, with cooperative procurement consolidation extracting price concessions from manufacturers.
- Horticulture:High-value greenhouse vegetables in Spain's Almería province and Italian protected crops command precision application systems and root-zone targeted formulations, generating premium pricing for drift-minimizing technologies.
- Turf Management:Golf course and sports field maintenance in the UK and Netherlands sustains steady demand for broad-spectrum contact fungicides with rapid knockdown properties.
- Forestry:Plantation protection in Nordic countries and Alpine regions employs specialized formulations against needle cast and rust pathogens in low-intensity management systems.
Volume concentration favors Agriculture. Margin expansion concentrates in Horticulture.
Chemical Composition:
Regulatory risk stratification under EU Regulation 1107/2009 and REACH authorization tiers restructures portfolio composition toward low-risk candidates.
- Synthetic Fungicides:Manufactured azoles, strobilurins, and SDHI molecules deliver reliable efficacy against resistant pathogen populations, though ECHA endocrine disruptor screening forces reformulation of several triazole-based products before renewal deadlines.
- Organic Fungicides:Copper-based and sulfur-based protectants retain authorization under organic certification schemes, dominating residue-sensitive export supply chains from Italian and Spanish specialty producers.
- Mineral Fungicides:Kaolin and other inorganic barriers provide physical protection with minimal biological impact, finding application in transition-zone organic operations.
- Others:Experimental chemistries and RNA interference platforms occupy pre-commercial development pipelines.
Regulatory pressure is heaviest on Synthetic Fungicides. Certification tailwinds favor Organic Fungicides.
Formulation Type:
Application precision and drift exposure concerns reshape physical form preferences across arable and protected cropping systems.
- Liquid Formulations:Suspension concentrates and soluble liquids dominate French and German arable applications, integrating readily with existing sprayer infrastructure and variable-rate technologies across cooperative-managed cereal zones.
- Granular Formulations:Root-zone targeted delivery systems minimize operator exposure and environmental drift, gaining traction in Spanish precision horticulture where greenhouse automation enables controlled substrate incorporation.
- Powder Formulations:Wettable powders retain cost-sensitive positioning in Eastern European markets and smallholder vineyard operations.
- Emulsifiable Concentrates:Oil-based carriers enhance rainfastness in Mediterranean climates, sustaining demand in Italian and Greek vineyard protection programs.
Scale economies concentrate in Liquid Formulations. Precision agriculture tailwinds favor Granular Formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Beauce cereal belt and Germany's Rhine-Ruhr agrochemical corridor concentrate fungicide demand through cooperative procurement networks. EFSA renewal timelines and national resistance protocols reshape product registration priorities across member states.
France
Septoria pressure in wheat-intensive Beauce and Champagne regions sustains azole and SDHI consumption. ANSM enforces strict endocrine disruptor screening under REACH, forcing reformulation of legacy triazole products. Bordeaux vineyard cooperatives accelerate biological alternation trials to meet export MRL requirements.
Germany
Downy mildew management in Rhineland-Palatinate vineyards and rust protection across North German Plain cereal operations drive systemic chemistry demand. KBA-aligned federal protocols mandate resistance rotation schemes. Bayer Leverkusen and BASF Ludwigshafen anchor domestic formulation capacity.
Spain
Almería's greenhouse cluster generates concentrated demand for root-zone targeted granular formulations with drift-minimizing application systems. Ministry of Agriculture subsidy realignment accelerates biological fungicide adoption in organic export supply chains. Andalusian precision horticulture commands premium pricing for substrate-incorporated delivery.
Italy
Powdery mildew resistance in Northern Italy vineyards compresses viable triazole chemistry pools. Ministry of Health enforces EU Green Deal pesticide reduction targets through regional extension services. Emilia-Romagna protected vegetable operations adopt Trichoderma-based biocontrol at twice the rate of cereal producers.
Poland
Consolidated 500+ hectare operations in Greater Poland and Masovia negotiate direct manufacturer contracts bypassing retail channels. National Plant Health Inspectorate implements zonal authorization procedures stretching field trial capacity. Cooperative procurement concentration extracts price concessions and technical service bundling from suppliers.
Europe Fungicide Market Competitive Landscape
Top-tier vendors anchor synthetic chemistry portfolios, while biological specialists and generic formulators occupy mid-market positions. The vendor base stratifies across three tiers: integrated agrochemical conglomerates with proprietary molecule pipelines, regional formulators leveraging Chinese technical grade supply, and microbial technology platforms scaling through greenhouse partnerships. Strategic archetypes include SDHI innovators defending patent cliffs, biological platform builders capturing organic subsidy realignment, and cooperative-facing distributors consolidating procurement influence. Dominant competitive moves encompass M&A targeting microbial antagonist pipelines and capacity expansion into precision formulation infrastructure.
Within the integrated agrochemical tier, Bayer AG and BASF SE exemplify synthetic chemistry incumbents navigating EFSA renewal pressures, while Syngenta Group occupies a position bridging conventional and biological platform development. These entities represent divergent responses to regulatory compression: proprietary molecule defense versus integrated disease management bundling. UPL Limited and ADAMA Agricultural Solutions Ltd exemplify generic-specialist archetypes leveraging technical grade sourcing flexibility. Corteva Agriscience anchors the crop protection-dedicated structure, reflecting agricultural portfolio purity distinct from diversified chemical conglomerates.
| Leading Market Players |
|---|
| Corteva Agriscience |
| FMC Corporation |
| Syngenta Group |
| ADAMA Agricultural Solutions Ltd |
| Nufarm Ltd |
| BASF SE |
| UPL Limited |
| Sumitomo Chemical Co. Ltd |
| Bayer AG |
| Others |
Pricing and Supply Chain Analysis
Formulation chemist concentrations in Germany's Rhine-Ruhr corridor and technical-grade sourcing specialists in China's Shandong province create labor-cost differentials that spread pricing tiers across premium proprietary SDHI molecules, mid-market azole formulations, and economy-grade strobilurin generics. This geographic skill stratification compresses margins at the generic end while sustaining premium capture for novel mode-of-action pipelines.
Pricing Analysis
Short lead-time premiums for biological fungicides with live microbial content command 15-25% markups over equivalent synthetic chemistries due to cold-chain logistics and shelf-life constraints. Three-tier pricing structure across premium, standard, and economy levels separates patented SDHI molecules from post-patent azoles and commodity strobilurin generics. Price differentiation hinges on EFSA low-risk certification status and cooperative volume commitments. Polish cereal cooperatives exhibit highest price sensitivity, while Spanish greenhouse operators accept premium positioning for drift-minimizing granular formats.
Supply Chain Analysis
Dual-sourcing mandates from French cooperative groups and German Raiffeisen structures require formulators to qualify at least two technical-grade suppliers for azole and strobilurin intermediates. Over 70% of these active pharmaceutical ingredients originate from Shandong and Jiangsu provinces in China, with secondary sourcing from Indian Gujarat-based manufacturers. Raw material dependencies center on pyridine derivatives, chlorinated aromatics, and fermentation substrates for biological production. Single-source vulnerability concentrates in Chinese intermediate supply, exposing formulators to freight volatility and geopolitical friction. Distribution runs through agricultural cooperatives in France and Germany, bypassing traditional retail channels in Poland's consolidating farm sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe fungicide market sits in a technology-transition phase where RNA interference platforms and microbial antagonist pipelines are displacing legacy triazole chemistries constrained by EFSA endocrine disruptor screening and vineyard resistance profiles.
For Market Incumbents: Hedge synthetic chemistry exposure by accelerating microbial antagonist pipeline acquisitions before EU Green Deal subsidy realignment tilts procurement entirely toward biologicals. Prioritize backward integration into fermentation capacity for Trichoderma and Bacillus production to secure supply autonomy as Chinese technical-grade concentration intensifies tariff exposure. Lock cooperative procurement relationships through bundled disease management platforms that embed biological components.
For New Entrants and Emerging Players: RNA interference delivery technology paired with existing biological formulation infrastructure offers entry wedge against entrenched synthetic incumbents. Target Spanish Almería greenhouse clusters where precision horticulture demands root-zone targeted granular formats with minimal drift exposure. Partner with Italian organic vineyard cooperatives facing export market Maximum Residue Limits to establish residue-free credentialing before scaling northward.
For Investors and Strategic Acquirers: Re-rating potential sits with microbial platform specialists given EU Farm to Fork Strategy mandates accelerating grower transition to low-risk biological formulations. Five-to-ten year viability favors companies with proprietary fermentation IP and established greenhouse partnerships over generic formulators tethered to Chinese intermediate supply. Watch EFSA substance evaluation work program announcements as inflection indicators for triazole renewal risk and biological substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Pipeline Acquisition | Microbial antagonist portfolios capture EU Green Deal subsidy realignment toward low-risk candidates. |
| Fermentation Capacity Expansion | In-house Trichoderma and Bacillus production reduces dependency on Chinese technical-grade supply concentration. |
| Precision Formulation Infrastructure | Granular root-zone delivery systems command premium positioning in Spanish Almería greenhouse automation. |
| Cooperative Procurement Partnerships | Direct contracts with French and German agricultural cooperatives bypass retail channel margin extraction. |
| RNA Interference Platform Development | Spray-induced gene silencing technology opens target specificity in specialty crop protection applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with crop protection R&D directors, agricultural cooperative procurement managers, EFSA regulatory affairs specialists, and Spanish greenhouse operations managers. Bottom-up triangulation combined manufacturer shipment data with cooperative purchasing records, while top-down validation cross-referenced Cefic chemical industry reports, EU pesticide usage statistics, and national plant protection agency registrations.
Granularity-level modeling disaggregated volume and value across the projection horizon by product type, chemical composition, formulation format, and end-use intensity. Segmentation dimensions included systemic versus biological versus contact fungicides, synthetic versus organic versus mineral chemistries, liquid versus granular versus powder formulations, and agriculture versus horticulture versus turf management applications. CAGRs were derived from trend extrapolation of hectarage expansion, resistance management protocol adoption, and subsidy realignment trajectories. Industry-specific forecast inputs incorporated EFSA renewal timelines, zonal authorization procedure completion rates, and organic certification growth curves.
Several conditions sit outside the modeled scope, including unannounced EFSA substance non-renewals, abrupt Chinese export restriction impositions, and novel pathogen strain emergences resistant to existing mode-of-action classes. Forecasts reflect documented assumptions regarding regulatory trajectory continuity and cooperative procurement consolidation velocity. A model refresh is warranted upon material change in EU Green Deal implementation pace or ECHA endocrine disruptor screening outcome reversals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Japan Crop Protection Chemicals Market
Crop Protection
South America Nematicides Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Pest Control Market
Crop Protection
US Insecticide Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Global Insecticides Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Global Acephate Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Microbial Pesticides Market