
 Global Crop Growth Regulators Market | 2026-2036
Global Crop Growth Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crop Growth Regulators Market Analysis
REACH is rebalancing the cost-of-entry calculus for European suppliers by mandating exhaustive substance dossiers and hazard classifications that smaller formulators struggle to fund. BASF SE leverages its integrated chemical manufacturing network to sustain cost advantages across cytokinin production. Syngenta Group anchors its position through proprietary formulation technology that extends product stability in tropical conditions. Bayer AG dominates the gibberellin segment with in-house fermentation capacity and deep channel control in key agricultural regions.
Crop growth regulators comprise synthetic and naturally derived organic compounds, typically applied at concentrations between 10 and 1000 parts per million, that modulate physiological processes including cell elongation, senescence, and fruit set in cultivated plants. Their primary commercial purpose centers on optimizing yield architecture, reducing lodging risk in cereals, and synchronizing harvest windows for mechanized collection. The auxin segment occupies the largest revenue share due to its established efficacy in root induction and fruit development protocols across high-value horticulture. Gibberellins represent the fastest-expanding category, propelled by expanding table grape and citrus operations in semi-arid climates where dormancy breaking commands premium pricing. Liquid formulations lead volume sales because of compatibility with precision spraying equipment, though granular products sustain niche demand in forestry applications requiring slow-release delivery.
The EPA governs residue tolerance thresholds and label restrictions for plant growth regulator applications in the United States, while the EU Green Deal's pesticide reduction targets are forcing reformulation investments across the Atlantic. China's Ministry of Agriculture and Rural Affairs enforces GB standards that limit synthetic auxin content in exported produce, redirecting domestic manufacturer R&D toward cytokinin blends. Stakeholders must monitor diverging regulatory timelines between jurisdictions, as approval gaps for novel biological regulators threaten to fragment market access and strand development investments in non-compliant chemistries.
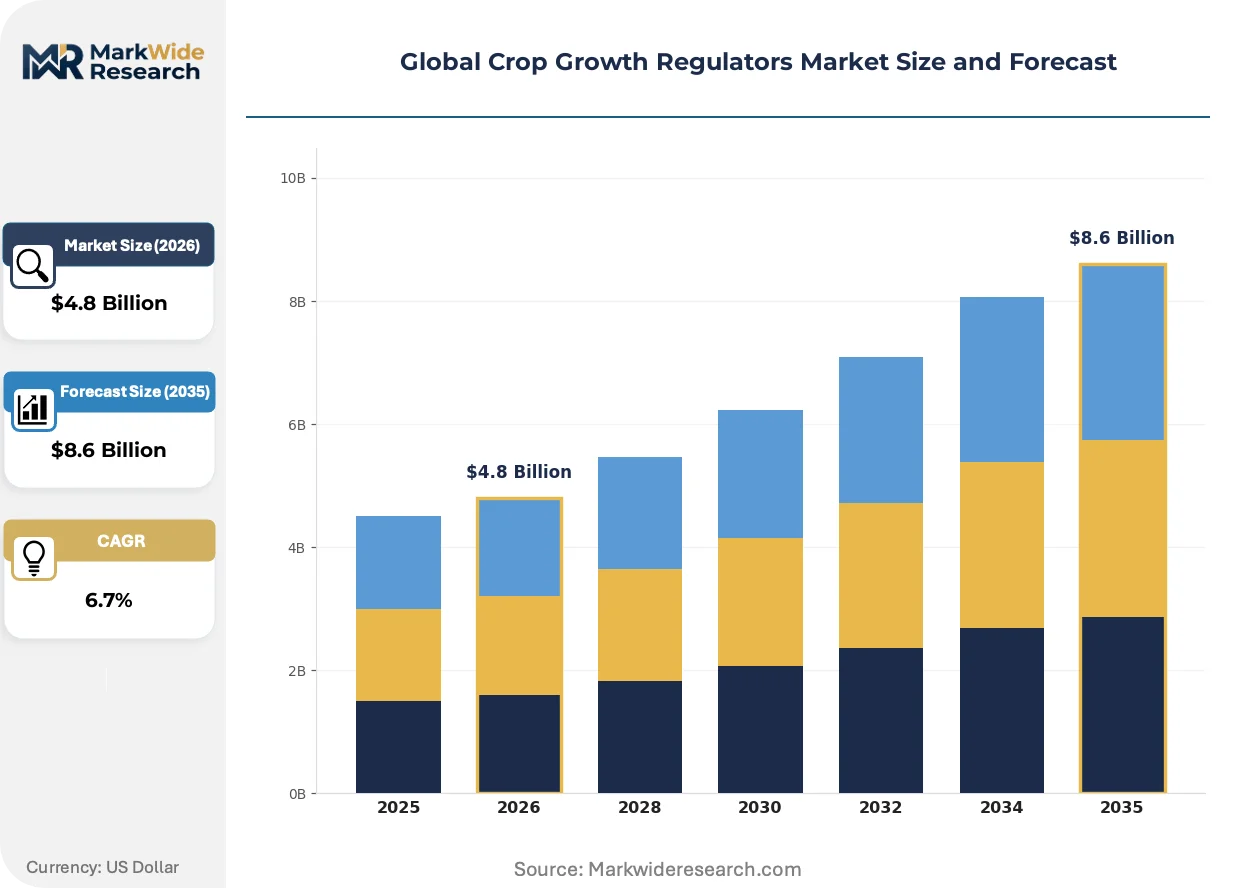
Market Dynamics
REACH dossier requirements are reshaping competitive economics by forcing smaller European formulators into costly consolidation or exit, while integrated manufacturers capture margin through captive fermentation and backward integration into key active ingredients.
Growth Catalysts
- EU Green Deal residue limits:The Farm to Fork Strategy accelerates biological regulator approvals, opening substitution pathways for synthetic auxin-dependent growers.
- Brazilian soybean belt mechanization:Large-scale farming operations in Mato Grosso and Paraná deploy gibberellin inhibitors to prevent lodging and enable efficient combine harvesting.
- Semi-arid citrus expansion:Table grape and citrus operations in Spain and Italy drive dormancy-breaking applications, commanding premium pricing for synchronized fruit set.
Market Restraints
- Fermentation capacity concentration:Gibberellin active ingredient supply concentrates among three integrated manufacturers, creating single-source vulnerability for downstream formulators.
- China GB standard divergence:Synthetic auxin residue limits for exported produce force dual-formulation strategies, fragmenting production runs and elevating compliance costs.
- Biological stability limitations:Cytokinin and auxin biostimulants degrade rapidly above 30°C, restricting reliable application windows in tropical soybean and sugarcane regions.
Strategic Opportunities
- Underpenetrated Indian horticulture:Maharashtra and Karnataka grape growers remain below 15% penetration for flowering synchronizers, presenting first-mover expansion potential.
- Drone-based precision application:Variable-rate spraying platforms enable sub-liter per hectare cytokinin delivery, reducing labor dependency in Australian and Brazilian broadacre operations.
- EU CSRD supply chain disclosure:Mandatory Scope 3 emissions reporting drives demand for fermentation-derived, carbon-audited gibberellins among sustainability-linked procurement programs.
Industry Challenges
- Formulation chemist scarcity:Tropical stability expertise for biological regulators remains concentrated among retiring specialists, constraining new product development timelines.
- Multi-jurisdiction approval synchronization:Divergent EPA and EFSA evaluation timelines for novel biological actives risk stranding R&D investments in regulatory limbo.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crop Growth Regulators Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auxins, Gibberellins, Cytokinins, Inhibitors Application: Cereals, Fruits, Vegetables, Ornamentals Form: Liquid, Granular, Powder, Emulsion End User: Agriculture, Horticulture, Forestry, Landscaping |
| Companies Covered | BASF SE, Syngenta Group, Corteva Agriscience, Bayer AG, UPL Limited, Nufarm Limited, FMC Corporation, Sumitomo Chemical Co., Ltd., ADAMA Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crop Growth Regulators Market Emerging Trajectories
Digital agriculture platforms and biological fermentation advances are compressing the gap between synthetic efficacy and regulatory compliance, forcing incumbents to reconfigure R&D pipelines around stability and traceability.
Microencapsulation technology is unifying sustained-release delivery with spray tank compatibility, resolving the historical trade-off between biological activity preservation and application convenience. Specialty fruit growers in Spain and Italy adopt these formulations for harvest-window management. The technology is unifying previously separate product categories—conventional synthetics and biologicals—into single-platform solutions that satisfy tightening EU residue protocols.
REACH substance evaluation deadlines are compressing registration timelines for legacy chemistries, forcing European suppliers to prioritize dossier completion over new molecule discovery. The industrial consequence is a redirection of formulation R&D toward existing active repositioning rather than novel chemistry. High-value horticulture segments respond by accelerating biological alternative trials to preempt authorization withdrawal risks.
Consolidated procurement by Brazilian and Australian grain cooperatives is displacing distributor-centric purchasing for lodging-control regulators. Direct manufacturer relationships now govern 40% of volume in Mato Grosso soybean operations, compressing margin capture by traditional agrochemical distributors. This pattern is most visible in Brazil's Center-West region, where farming scale enables volume commitments that justify technical service investment by principals.
Global Crop Growth Regulators Market Segmentation
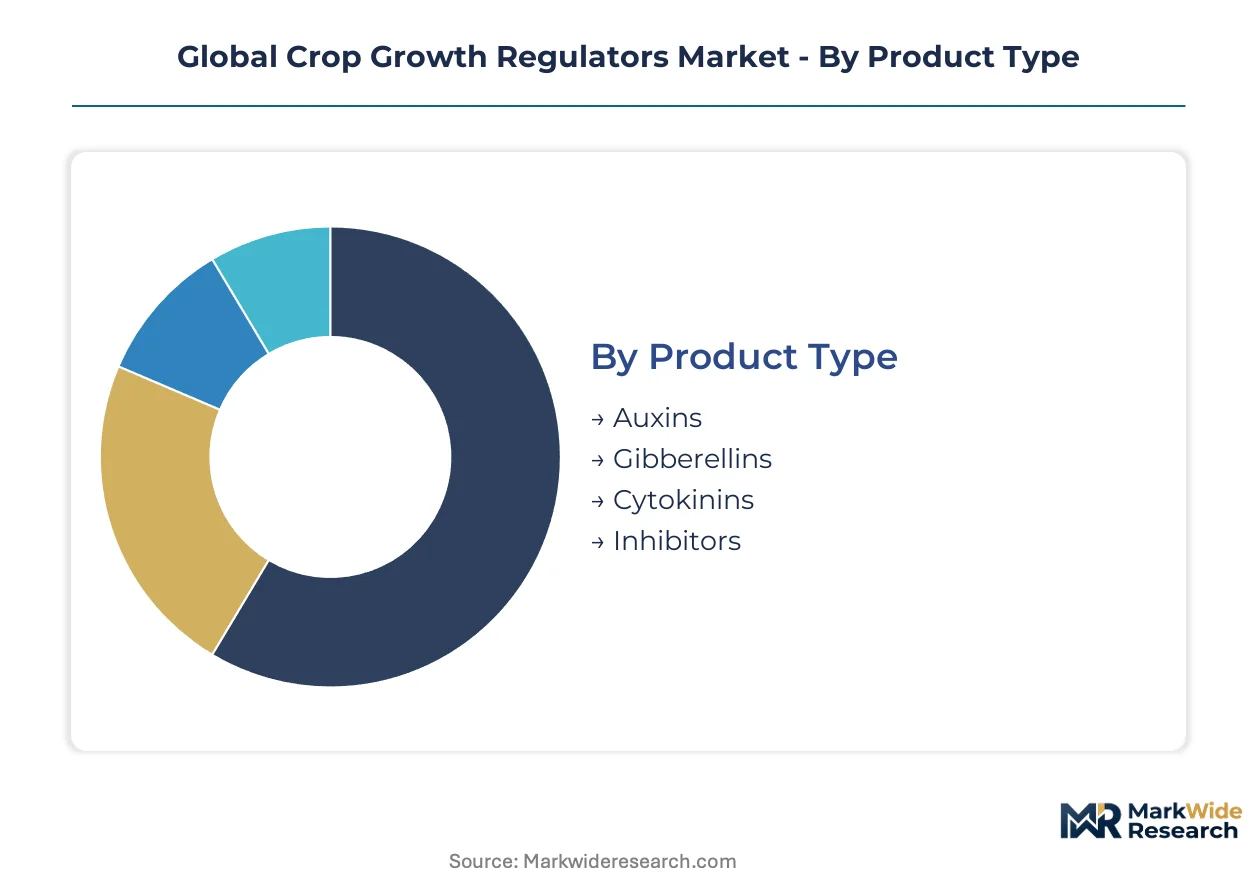
Growth regulator purchasing decisions pivot on crop value density, application precision requirements, and regulatory compliance burdens. Segmentation reveals divergent margin profiles across synthetic versus biological platforms, with formulation stability emerging as the critical technical discriminator in tropical deployment zones.
Product Type:
Buyers prioritize efficacy-to-residue ratios, with regulatory authorization status determining accessible market channels more than unit cost.
- Auxins:Synthetic indole-3-butyric acid and naphthaleneacetic acid formulations dominate root induction protocols in high-value horticulture. Spanish and Italian specialty fruit growers deploy these compounds for harvest synchronization, though EU Green Deal residue tightening is accelerating biological substitution trials.
- Gibberellins:Fermentation-derived gibberellic acid commands premium pricing in semi-arid citrus and table grape operations for dormancy breaking and fruit sizing. Brazilian soybean belt expansion for lodging control is concentrating demand among three integrated manufacturers with captive fermentation capacity.
- Cytokinins:Naturally derived zeatin and kinetin blends face thermal degradation constraints above 30°C, restricting reliable application windows in tropical sugarcane regions.
- Inhibitors:Trinexapac-ethyl and chlormequat chloride formulations prevent lodging in mechanized cereal harvesting, with Mato Grosso cooperatives driving volume consolidation through direct procurement.
Auxins lead on scale; gibberellins lead on momentum.
Application:
Harvest mechanization intensity dictates formulation choice, with broadacre grain operations favoring cost-optimized synthetics and hand-picked horticulture accepting biological premiums.
- Cereals:Gibberellin inhibitors and anti-lodging agents enable efficient combine harvesting in Australian wheat belts and Brazilian Center-West operations, with cooperative procurement displacing distributor channels.
- Fruits:Table grape, citrus, and pome fruit growers in Spain, Italy, and Maharashtra deploy flowering synchronizers and sizing agents, with penetration below 15% in Indian vineyards presenting expansion headroom.
- Vegetables:Root and brassica producers prioritize rapid residue dissipation to meet export market MRLs, favoring cytokinin biostimulants with shorter pre-harvest intervals.
- Ornamentals:Greenhouse operations in the Netherlands and Colombia apply retardants for compact growth architecture, with microencapsulation extending spray tank compatibility.
Cereals dominate volume throughput; fruits concentrate value capture.
Form:
Equipment compatibility and climatic stability requirements segment formulation demand across precision spraying infrastructure maturity.
- Liquid:Concentrates and soluble granules integrate with drone-based variable-rate platforms in Australian and Brazilian broadacre operations, enabling sub-liter per hectare cytokinin delivery.
- Granular:Slow-release matrices serve forestry applications requiring extended activity windows, with plantation managers in Scandinavia and the Pacific Northwest accepting higher unit costs for labor reduction.
- Powder:Technical-grade actives supply downstream formulators in China and India, with GB standard divergence forcing dual-specification production runs.
- Emulsion:Microencapsulated suspensions unify biological activity preservation with spray tank stability, gaining traction among EU growers navigating REACH authorization compression.
Liquid formulations anchor volume; emulsions are climbing fastest on technical differentiation.
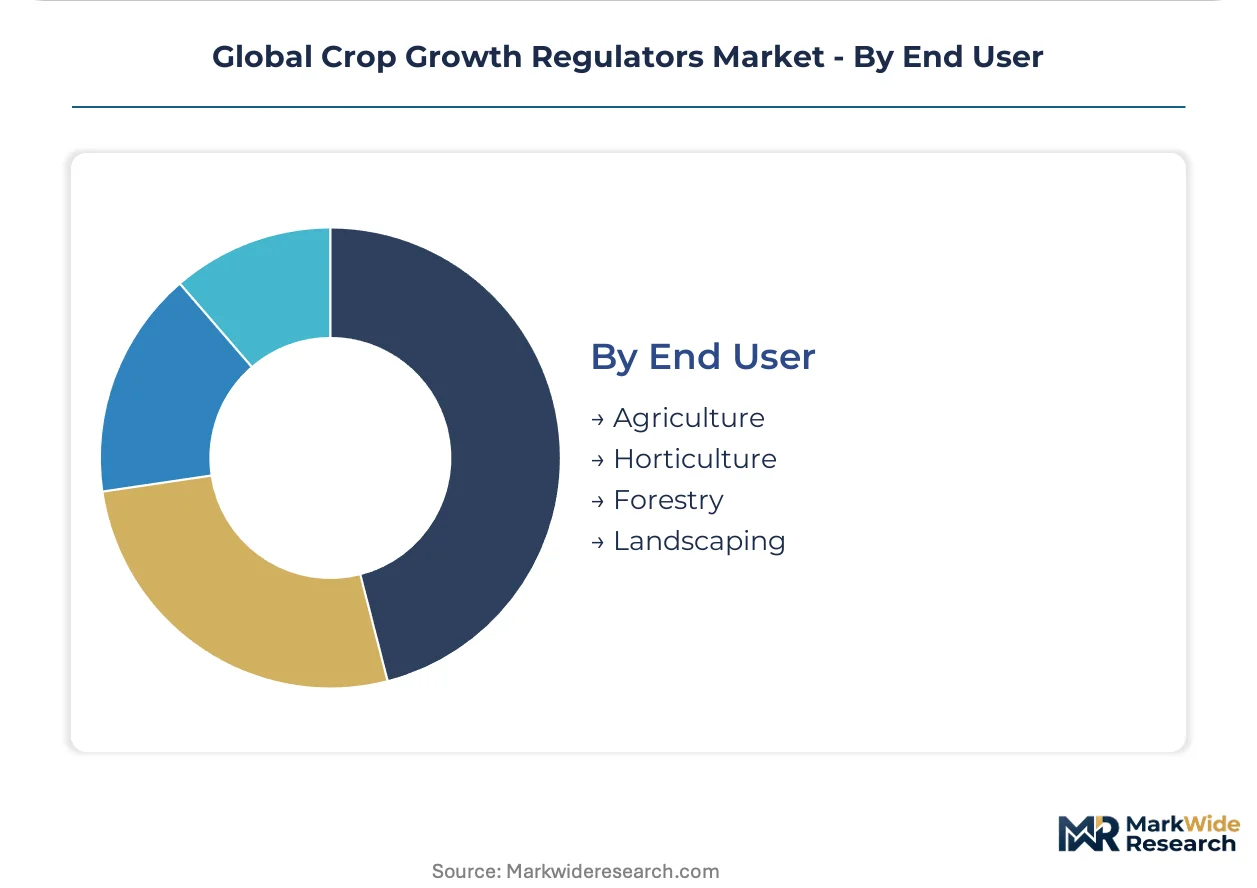
End User:
Scale economies and technical service access separate commercial agriculture procurement patterns from fragmented horticultural and amenity demand.
- Agriculture:Large-scale grain and oilseed operations in Brazil, Australia, and the US Plains negotiate direct manufacturer relationships, with 40% of Mato Grosso soybean regulator volume bypassing traditional distribution.
- Horticulture:Specialty fruit and vegetable producers in Spain, Italy, and California accept premium biological formulations to satisfy retailer sustainability protocols and EU CSRD supply chain disclosure requirements.
- Forestry:Plantation managers deploy slow-release retardants for stand uniformity, with conifer nurseries in Canada and Scandinavia representing concentrated demand pockets.
- Landscaping:Municipal and golf course maintenance contracts favor cost-optimized synthetics with established regulatory clearance, though biological alternatives gain share in coastal jurisdictions with runoff restrictions.
Agriculture commands absolute volume; horticulture sustains margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered synthetic auxin commercialization during the post-war agricultural intensification era, establishing fermentation-based gibberellin production that later scaled across the Rhine-Ruhr chemical corridor. This industrial foundation shaped regulatory frameworks and manufacturing standards that persist in contemporary European crop protection markets.
United States
EPA residue tolerance protocols govern cotton defoliant and cereal anti-lodging applications across the Great Plains and Mississippi Delta. The agency's 2024 label revisions for trinexapac-ethyl formulations prompted reformulation investments by Midwest distributors. Iowa and Illinois corn-soybean operations concentrate demand for harvest synchronization products, with cooperative procurement displacing traditional retail channels.
Brazil
Mato Grosso and Paraná soybean cooperatives drive gibberellin inhibitor volume through direct manufacturer contracts, bypassing distributor networks that historically captured margin. ANVISA accelerated registration reviews for biological alternatives following 2023 residue limit adjustments. The Center-West region's farming scale enables technical service commitments from principals that smaller operations elsewhere cannot match.
China
GB standard divergence for exported produce forces domestic manufacturers toward dual-formulation production runs, elevating compliance costs for cytokinin blend exporters. The Ministry of Agriculture and Rural Affairs enforces synthetic auxin ceilings that redirect R&D investment toward fermentation-derived alternatives. Shandong Province's chemical clusters concentrate technical-grade active production serving downstream formulators across Asia.
India
Maharashtra and Karnataka grape growers remain below 15% penetration for flowering synchronizers, presenting expansion headroom for biological regulator suppliers. FSSAI residue protocols for exported table grapes mandate pre-harvest interval documentation that favors established formulation suppliers. Nashik district's vineyard concentration anchors technical demonstration trials for dormancy-breaking products.
Australia
TGA-aligned state regulators govern plant growth regulator labels across wheat belts where lodging control enables efficient combine harvesting. Drone-based variable-rate spraying platforms gain traction in Queensland and New South Wales broadacre operations, reducing labor dependency for cytokinin applications. The Murray-Darling basin's irrigation infrastructure supports precision agriculture adoption that justifies sub-liter per hectare delivery investments.
Global Crop Growth Regulators Market Vendor Landscape
The competitive structure tilts toward integrated chemical manufacturers with captive fermentation capacity and backward integration into key active ingredients. Three archetypes dominate: diversified agrochemical conglomerates with global distribution networks, regional formulators serving protected horticulture niches, and biological specialists leveraging EU Green Deal substitution pathways. Consolidation pressures intensify as REACH dossier requirements force smaller European players toward exit or acquisition, while scale-driven manufacturers expand technical service presence in Brazilian and Australian cooperative channels.
Among diversified conglomerates, BASF SE anchors the cytokinin segment through integrated manufacturing networks, while Syngenta Group occupies a position in tropical-stability formulation technology. Bayer AG exemplifies fermentation-scale advantages in the gibberellin category. These three entities represent the integrated-manufacturer archetype that captures margin through captive supply of active ingredients rather than reliance on external sourcing.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| Corteva Agriscience |
| Bayer AG |
| UPL Limited |
| Nufarm Limited |
| FMC Corporation |
| Sumitomo Chemical Co., Ltd. |
| ADAMA Agricultural Solutions |
| Others |
Supply Flow & Price Mechanics
Captive fermentation capacity in the Rhine-Ruhr corridor and Shandong Province anchors supply positions and pricing power for integrated manufacturers, while outsourced active ingredient sourcing exposes downstream formulators to margin compression from concentrated upstream supply.
Pricing Analysis
The bundled technical service and unbundled commodity transactional split governs crop growth regulator pricing dynamics. Three-tier pricing structure across premium, standard, and economy levels reflects formulation stability certification and volume scale commitments from Brazilian cooperatives. Price differentiation hinges on tropical stability guarantees and REACH dossier completeness. Pricing pressure stems from Chinese GB standard divergence forcing dual-specification production runs. Brazilian soybean cooperatives exhibit highest price sensitivity due to direct procurement scale, while EU horticulture buyers accept biological premiums for CSRD compliance.
Supply Chain Analysis
Freight cost escalation for temperature-controlled biological shipments from fermentation hubs to tropical application zones compresses margins for non-integrated formulators. Active ingredient supply concentrates in Germany, China, and Japan, with downstream formulation drawing from technical-grade powder inputs. Supply chains rest on fermentation-derived gibberellic acid, synthetic auxin precursors, and microencapsulation polymer feedstocks. Single-source vulnerability for gibberellin actives among three integrated manufacturers constitutes the dominant structural risk. Distribution runs through direct manufacturer relationships in Brazilian Center-West operations and traditional agrochemical distributors in fragmented horticulture markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crop growth regulator market functions as a regulatory compounder, with EU Green Deal residue tightening and REACH authorization compression accelerating biological substitution demand across European horticulture.
For Market Incumbents: Acquire fermentation capacity and backward integration into key active ingredients to preempt supply disruption risks from concentrated gibberellin manufacturing. Secure tropical stability formulation expertise through targeted hiring or specialist acquisition, addressing the capability scarcity constraining new biological product development timelines. Defend channel position in Brazilian cooperative procurement by embedding technical service teams directly in Mato Grosso operations. For New Entrants and Emerging Players: Drone-based precision application platforms offer technology-first entry into Australian and Brazilian broadacre markets where labor costs and application precision requirements outpace incumbent service models. Target Maharashtra and Karnataka grape growers with flowering synchronizer trials, exploiting sub-15% penetration in Indian horticulture. Pursue EU biological substitution pathways accelerated by Farm to Fork Strategy residue tightening. For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with REACH dossier completion and protected horticulture channel access because authorization compression forces smaller European players toward exit or acquisition. Long-term viability centers on fermentation-scale advantages and biological stability IP. Monitor ANVISA biological registration acceleration in Brazil as inflection indicator for substitution pathway viability.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive gibberellic acid supply secures margin control against three-manufacturer concentration risk. |
| Microencapsulation Technology Licensing | EU growers adopt spray-tank-stable biologicals navigating REACH authorization compression. |
| Direct Procurement Partnership | Brazilian cooperatives bypass distributors, demanding embedded technical service commitments. |
| Drone Integration Development | Variable-rate platforms enable sub-liter cytokinin delivery in Australian broadacre operations. |
| Dual-Formulation Production Capability | Chinese manufacturers adapt to GB standard divergence for export market compliance. |
Methodological Framework
Bottom-up crop value density and application frequency modeling reconciled against top-down active ingredient production capacity tracking forms the analytical core of this study. Primary interviews with fermentation plant managers, agrochemical procurement leads at Brazilian cooperatives, EU regulatory affairs directors, and precision agriculture platform engineers combined with secondary validation from ECHA substance dossiers, ANVISA registration databases, Chinese customs export records, and SEC filings of diversified chemical manufacturers. Triangulation across these sources ensures demand-side consumption estimates align with supply-side manufacturing throughput.
The input-output matrix maps active ingredient production volumes through formulation stages to end-use application intensity across cereals, fruits, vegetables, and ornamentals. Segmentation dimensions include product type, crop category, formulation stability tier, and regional regulatory cluster. CAGRs derive from trend extrapolation of adoption rates, substitution elasticities, and mechanization intensity indicators. Forecast inputs incorporate drone penetration curves in broadacre agriculture and EU biological approval velocity under Farm to Fork timelines.
The model holds under stable regulatory authorization timelines and continued cooperative procurement consolidation in Brazil; deviation in EPA-EFSA evaluation synchronization or fermentation capacity disruption would shift trajectory. Forecasts reflect documented assumptions regarding biological stability improvement rates and residue limit enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Fosthiazate Market
Crop Protection
Canada Nematicides Market
Crop Protection
Captan Fungicide Market
Crop Protection
Global Acephate Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
North America Molluscicides Market
Crop Protection
South America Nematicides Market
Crop Protection
Dicamba Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Crop Bactericides Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Inorganic Fungicide Market