
 Europe Seed Treatment Market | 2026-2036
Europe Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Seed Treatment Market Analysis
The capital-intensity divergence between integrated agrochemical conglomerates and specialized seed technology firms is rotating competitive dynamics across Europe. Bayer CropScience leverages its crop science pipeline to sustain integrated treatment platforms from discovery to field delivery. Germains Seed Technology specializes in film-treatment and priming equipment, occupying niche positions where precision application commands premium positioning. BASF competes through its fungicide-insecticide seed treatment portfolio, anchoring volume in cereal protection across northern European markets.
Europe seed treatment encompasses chemical, biological, and physical processes applied to seeds before sowing to protect against pathogens, enhance germination, and improve early-stage plant vigor, typically involving active ingredient loadings of 0.5-5 grams per kilogram of seed. The primary commercial purpose centers on reducing field mortality rates and minimizing subsequent crop protection interventions during critical establishment phases. Pesticide-based coating retains dominant share in cereal applications, though biostimulant inoculants represent the fastest-expanding product category as farmers seek nitrogen-fixation benefits in pulse and oilseed rotations. Film-treatment application methods command margin premiums over conventional coating due to reduced dust-off and precise active ingredient placement on seed surfaces.
EMA and EFSA govern residue thresholds and active substance approvals under REACH and the EU Green Deal's pesticide reduction targets, directly constraining chemical treatment portfolios while creating regulatory pathways for biological alternatives. CE marking requirements for seed treatment machinery under MDR-equivalent frameworks shape equipment investment cycles among application service providers. Stakeholders must monitor evolving substance ban lists and national derogation timelines to align R&D pipelines with compliance windows.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is forcing chemical pesticide substitution across European cereal production, redirecting R&D investment toward microbial inoculants and accelerating biological seed treatment adoption in France and Germany's intensive farming regions.
Growth Catalysts
- Farm to Fork pesticide reduction targets:The EU Green Deal mandates 50% chemical pesticide reduction by 2030, creating immediate substitution demand for biological alternatives in cereal and oilseed rotations.
- Rhine corridor precision agriculture adoption:German cereal producers in Baden-Württemberg and Bavaria are deploying film-treatment equipment to reduce active ingredient waste and comply with EFSA residue thresholds.
- Nitrogen-fixation biostimulants:Pulse and oilseed farmers across France's cereal belt are integrating rhizobium and azotobacter inoculants to reduce synthetic fertilizer dependency under REACH fertilizer regulations.
Market Restraints
- Active substance approval timelines:EFSA's 3-5 year substance evaluation process under REACH creates regulatory lag, delaying biological product commercialization versus chemical alternatives.
- Petrochemical coating feedstock volatility:Polymer binders and film-forming agents for seed coatings face price instability tied to European refinery output fluctuations.
- Biological formulation shelf-life constraints:Microbial inoculants require cold-chain distribution infrastructure absent in Eastern European distribution networks, limiting geographic penetration.
Strategic Opportunities
- Poland and Romania underpenetrated zones:These markets exhibit sub-15% biological treatment penetration in cereals versus 35% in Germany, presenting volume expansion potential for application service providers.
- Drone-based seed treatment application:UAV spraying systems are emerging as a channel innovation for precision inoculant delivery in fragmented Polish and Hungarian farm structures.
- CSRD sustainability reporting mandates:Corporate sustainability disclosure requirements are pushing large agribusiness buyers to demand certified biological treatments for supply chain Scope 3 emissions reduction.
Industry Challenges
- Microbial formulation expertise scarcity:European universities produce insufficient strain stabilization and encapsulation specialists to support biological product pipeline expansion.
- CE marking compliance for equipment:Seed treatment machinery manufacturers face MDR-equivalent certification delays averaging 14-18 months, constraining service provider fleet modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Seed Treatment Market |
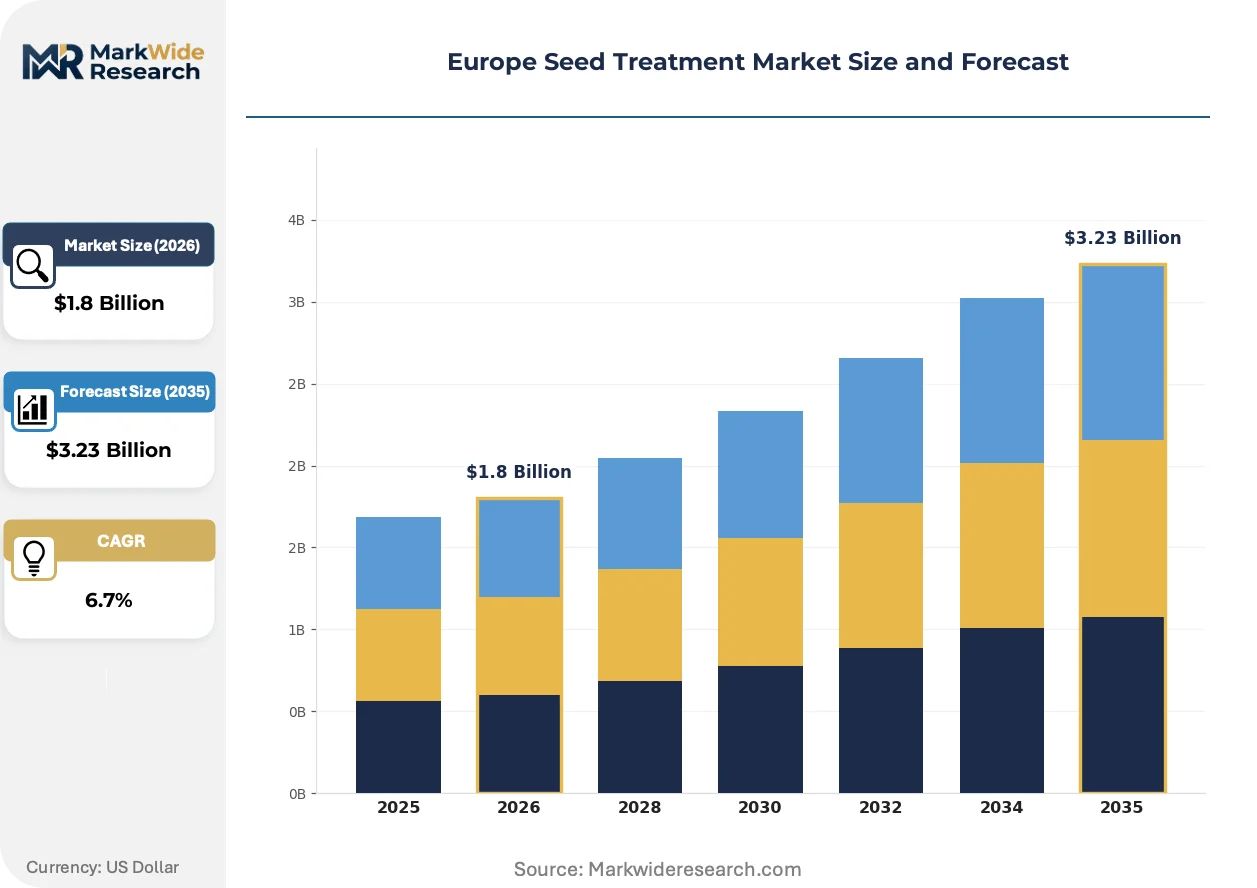
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Fertilizers, Inoculants, Biostimulants Application Method: Coating, Pelleting, Film-Treatment, Priming Seed Type: Cereal, Vegetables, Pulses, Oilseeds End User: Agricultural Producers, Retailers, Distributors, Farmers |
| Companies Covered | Bayer CropScience, Syngenta, BASF, Corteva Agriscience, UPL, Adama Agricultural Solutions, Nufarm, Incotec Group, Germains Seed Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Seed Treatment Market Emerging Trajectories
Biological active ingredient platforms are fragmenting traditional chemical-dominated treatment portfolios, while regulatory acceleration and buyer procurement evolution reshape competitive positioning across the European value chain.
Polymer-encapsulated microbial inoculants are fragmenting conventional liquid formulation dominance in biological seed treatment. French pulse producers in the Paris Basin are adopting these shelf-stable alternatives at accelerating rates. This technology is fragmenting supply chain requirements, forcing distributors to invest in ambient-temperature logistics networks previously unnecessary for chemical portfolios.
REACH authorization restrictions on neonicotinoid seed treatments are compressing chemical product lifecycles in cereal protection. The regulation is redirecting Bayer CropScience and BASF R&D expenditure toward fungicide-biological combination products. Northern European markets, particularly Denmark and the Netherlands, are responding fastest through national derogation negotiations and accelerated biological registration pathways.
Cooperative procurement consortia among French cereal growers are consolidating purchase volume and unbundling treatment services from input bundles. Application service providers in the Champagne-Ardenne region are losing bundled margin capture as farmer groups negotiate direct biological inoculant supply contracts. This pattern is most visible in France's cereal belt where cooperative membership exceeds 60% of arable hectares.
Europe Seed Treatment Market Segmentation
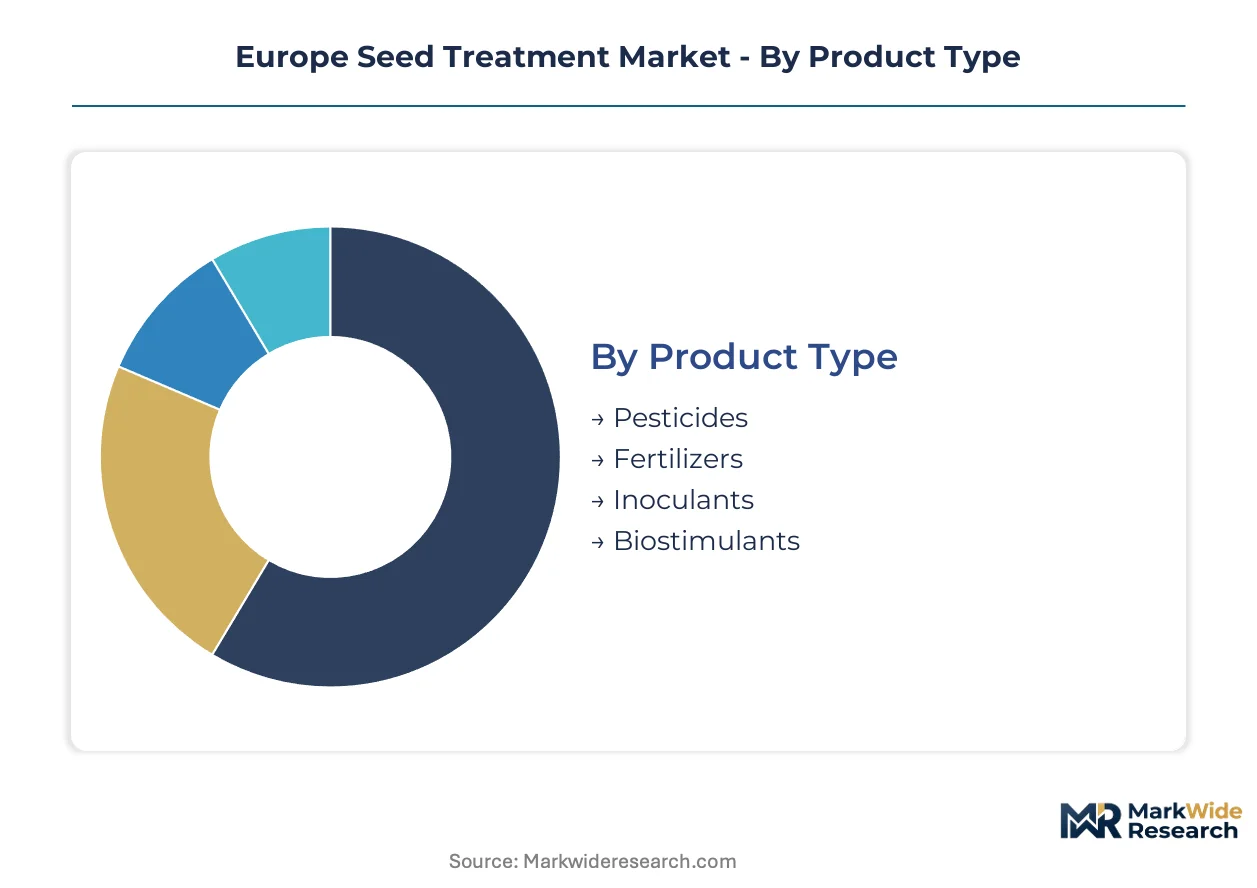
Segmentation reveals how regulatory pressure fragments demand across treatment technologies and crop categories. Substitution dynamics vary sharply by product chemistry and application method, reshaping supplier portfolios across the European value chain.
Product Type:
Pesticides face the steepest substitution threat from biological alternatives under EU Green Deal mandates, while fertilizer-compatible treatments gain defensive positioning against input cost volatility.
- Pesticides:Chemical active ingredients including neonicotinoids and fungicides dominate cereal protection in Germany and France. EFSA residue thresholds and REACH authorization delays are compressing product lifecycles and redirecting R&D expenditure toward combination formulations.
- Fertilizers:Nutrient-loaded coatings integrate phosphorus and potassium for early-stage root establishment. Rhine corridor producers deploy these treatments to reduce synthetic fertilizer volumes under Germany's fertilizer ordinance compliance windows.
- Inoculants:Microbial strain formulations containing rhizobium and azotobacter enable nitrogen fixation in pulse rotations. Cold-chain distribution gaps in Eastern Europe constrain geographic penetration.
- Biostimulants:Seaweed extracts and protein hydrolysates enhance stress tolerance without plant protection classification. France's cereal belt cooperative buyers are certifying these inputs for CSRD Scope 3 reporting.
Pesticides anchor the volume base while biostimulants gain share at the steepest rate.
Application Method:
Cost tiers separate precision application technologies from commodity coating equipment, with margin structures diverging based on active ingredient retention performance and dust-off reduction.
- Coating:Conventional polymer-based application loads 0.5-5 grams of active ingredient per kilogram of seed. BASF and Bayer CropScience anchor volume in this segment across northern European cereal markets.
- Pelleting:Encapsulation in inert carriers protects fragile seeds during mechanical sowing. Vegetable producers in the Netherlands and Belgium specify pelleting for precision drilling compatibility.
- Film-Treatment:Ultra-thin polymer layers reduce active ingredient waste and achieve EFSA residue compliance. German application service providers in Baden-Württemberg command premium pricing for film-treatment precision.
- Priming:Controlled hydration triggers pre-germination metabolic activation. Germains Seed Technology specializes in priming equipment for high-value vegetable seed markets.
Coating captures the highest throughput volumes while film-treatment commands the widest margin premiums.
Seed Type:
Application intensity varies by crop value and establishment risk, with cereals offering volume scale against specialty crops providing technology testing grounds.
- Cereal:Wheat, barley, and maize dominate treatment volumes across France's cereal belt and Germany's Rhine corridor. EU Green Deal pesticide reduction targets are accelerating biological substitution in this segment.
- Vegetables:High-value brassicas and solanaceous crops justify precision priming and pelleting investments. Dutch greenhouse producers specify film-treated vegetable seeds for automated transplanting systems.
- Pulses:Pea and faba bean rotations integrate rhizobium inoculants for nitrogen fixation. French pulse producers in the Paris Basin are adopting polymer-encapsulated formulations for shelf stability.
- Oilseeds:Rapeseed and sunflower treatments focus on flea beetle and sclerotinia protection. CE marking delays for application equipment constrain service provider fleet modernization in Polish oilseed regions.
Cereals generate the treatment volume base while pulses show the steepest biological adoption trajectory.
End User:
Procurement consolidation among cooperative structures is unbundling treatment services from input bundles, compressing distributor margins while elevating direct manufacturer relationships.
- Agricultural Producers:Large-scale arable operations in France and Germany operate in-house treatment facilities. These buyers negotiate direct biological inoculant supply contracts bypassing traditional distribution.
- Retailers:Agricultural input merchants bundle seed and treatment services for smaller farm customers. Cooperative procurement consortia are eroding retailer margin capture in France's cereal belt.
- Distributors:Regional logistics providers manage cold-chain infrastructure for biological formulations. Ambient-temperature network investments are fragmenting distributor capital allocation.
- Farmers:Fragmented Polish and Hungarian farm structures are adopting drone-based application services for precision inoculant delivery.
Agricultural producers anchor demand concentration while farmers in fragmented markets are diversifying service access channels most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish and Romanian buyers exhibit the highest price elasticity, squeezing distributor margins on biological formulations, while German and French producers absorb premium film-treatment costs to secure EFSA compliance and CSRD certification advantages.
Germany
Baden-Württemberg and Bavaria cereal producers drive precision agriculture adoption, deploying film-treatment equipment to minimize active ingredient waste. Germany's fertilizer ordinance compels Rhine corridor farmers to reduce synthetic nitrogen loads through seed-applied nutrient coatings. Application service providers in Stuttgart and Mannheim command premium pricing for residue-compliant treatment services.
France
Paris Basin pulse growers integrate polymer-encapsulated rhizobium inoculants for nitrogen fixation in pea and faba bean rotations. The EU Green Deal's Farm to Fork strategy accelerates chemical pesticide substitution across Champagne-Ardenne and Île-de-France cereal belts. Cooperative procurement consortia in northern France consolidate 60% of arable hectares, unbundling treatment services from traditional input bundles.
Poland
Fragmented farm structures in Masovia and Greater Poland regions sustain sub-15% biological treatment penetration versus German benchmarks. Drone-based UAV application services emerge as channel innovation for precision inoculant delivery. Cold-chain infrastructure gaps constrain microbial formulation distribution beyond Warsaw and Kraków logistics hubs.
Romania
Danube Delta and Transylvanian cereal producers exhibit lowest biological adoption rates in the EU-27, tethered to commodity coating price points. National rural development programs under CAP Pillar II subsidize precision equipment acquisition. Bucharest-based distributors struggle to justify ambient-temperature network investments for shelf-stable encapsulated products.
Netherlands
Greenhouse vegetable producers in Westland and North Brabant specify film-treated brassica and solanaceous seeds for automated transplanting compatibility. Dutch national derogation negotiations accelerate biological registration pathways ahead of EU baseline timelines. Wageningen University clusters anchor microbial strain stabilization research for European formulation pipelines.
Europe Seed Treatment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with agrochemical conglomerates leveraging crop science pipelines against equipment-focused firms commanding precision-application premiums. The upper tier sustains end-to-end treatment platforms from active ingredient discovery through field delivery. Mid-scale specialists occupy niche positions where film-treatment and priming technologies justify margin capture. Consolidation pressure intensifies through R&D partnership formations and biological portfolio acquisitions.
Among integrated agrochemical leaders, Bayer CropScience and BASF anchor the volume-driven chemical protection segment across northern European cereal markets. Germains Seed Technology exemplifies the specialist archetype, occupying premium positioning through precision equipment for high-value vegetable seed applications. Syngenta sits within the hybrid tier, bridging chemical seed treatment heritage with expanding biological formulation portfolios.
| Leading Market Players |
|---|
| Bayer CropScience |
| Syngenta |
| BASF |
| Corteva Agriscience |
| UPL |
| Adama Agricultural Solutions |
| Nufarm |
| Incotec Group |
| Germains Seed Technology |
| Others |
Supply Flow & Price Mechanics
CE marking compliance under MDR-equivalent frameworks gates both equipment qualification and service pricing tiers simultaneously, compressing margins for uncertified application providers while elevating premium capture for residue-compliant film-treatment operators across Germany's Rhine corridor.
Pricing Analysis
After-sales service contracts for precision equipment calibration and maintenance drive lifetime value for application service providers in Baden-Württemberg and Bavaria. Pricing stratifies across premium film-treatment, standard polymer coating, and economy commodity coating tiers based on EFSA residue compliance certification and active ingredient retention performance. Cost compression in the economy tier intensifies as Polish and Romanian buyers squeeze distributor margins on biological formulations. Agricultural cooperatives in France's cereal belt exhibit lowest price sensitivity, absorbing premium costs for CSRD-certifiable biostimulant treatments.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container terminals constrain polymer binder and film-forming agent availability for seed coating manufacturers. Supply concentrates in Germany, France, and the Netherlands for precision application equipment, while microbial strain production feeds from Wageningen University clusters and Danish fermentation facilities. Single-source vulnerability sits with cold-chain distribution infrastructure for live inoculants, particularly acute in Eastern European networks. Distribution runs through cooperative procurement consortia in northern France and independent agricultural retailers in fragmented Polish markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through EFSA substance approval timelines and CE marking requirements creates defensive moats for incumbent equipment manufacturers and established biological formulation houses with compliant product pipelines.
For Market Incumbents: Secure backward integration into microbial strain stabilization capabilities to defend against biological product pipeline expansion by specialized fermentation houses. Anchor capacity addition in the Netherlands near Wageningen research clusters to capture accelerated biological registration pathways. Lock long-term supply agreements with Rhine corridor application service providers to forestall cooperative procurement unbundling. For New Entrants and Emerging Players: Dutch national derogation fast-tracks offer regulatory arbitrage against EU baseline timelines for biological seed treatment registration. Target Poland's Masovia and Greater Poland regions where sub-15% biological penetration and drone-based application innovation create white-space for precision inoculant delivery services. Pursue direct-to-cooperative sales models bypassing traditional retail bundling in France's cereal belt. For Investors and Strategic Acquirers: The EU Green Deal's 2030 pesticide reduction targets reshape the acquisition landscape toward biological formulation expertise and cold-chain distribution infrastructure. Five-to-ten year viability favors vertically integrated specialists with strain stabilization IP and ambient-temperature encapsulation technology. Watch EFSA substance ban list expansions as the inflection signal for chemical portfolio stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation Acquisition | Microbial strain libraries from Wageningen clusters accelerate EU Green Deal compliance pipelines. |
| Cold-Chain Infrastructure Buildout | Ambient-temperature logistics networks in Poland and Romania unlock geographic penetration for shelf-stable inoculants. |
| Film-Treatment Equipment Certification | CE marking under MDR-equivalent frameworks commands premium positioning in Germany's precision agriculture corridor. |
| Cooperative Procurement Partnership | Direct supply contracts with French cereal belt consortia bypass retailer margin capture. |
| Drone Application Service Launch | UAV precision delivery addresses fragmented farm structures in Hungarian and Polish oilseed regions. |
Methodological Framework
A spread of perspectives from seed treatment equipment engineers, biological formulation scientists, cooperative procurement managers, and EFSA regulatory affairs specialists converged on the working assumptions. Primary interviews with application service providers in Stuttgart, Mannheim, and Champagne-Ardenne combined with secondary validation from EMA substance approval databases, REACH authorization records, and CE marking compliance registries. Bottom-up triangulation across product-type shipment volumes and top-down cross-checks against national fertilizer ordinance implementation timelines anchored the analytical framework.
Segmentation dimensions modeled include product chemistry tier, application method precision level, seed crop category, and end-user procurement structure across the analysis window. CAGRs were derived from trend-line extrapolation of biological substitution rates under Farm to Fork mandates, calibrated against historical chemical treatment volume declines in neonicotinoid-restricted markets. Industry-specific forecast inputs incorporated Rhine corridor precision agriculture adoption curves and Polish drone-service penetration assumptions.
Underlying assumptions cover EFSA evaluation timeline stability and CAP Pillar II subsidy continuity, with deviation risk concentrated in national derogation negotiation outcomes and petrochemical feedstock price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
North America Nematicides Market
Crop Protection
Grape Fungicides Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Global Insecticides Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Europe Molluscicides Market
Crop Protection
US Pest Control Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
Europe Soil Treatment Market
Crop Protection
Specialty Pesticides Market
Crop Protection
IPM Pheromones Market
Crop Protection
Dicamba Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
Grain and Cereal Crop Protection Market