
 Global 5G in Healthcare Market | 2026-2036
Global 5G in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global 5G in Healthcare Market Foresight
Telemedicine engineering talent is bifurcating between legacy network architects and low-latency wireless specialists, creating recruitment bottlenecks for hospital IT departments rolling out 5G infrastructure. Ericsson leverages its Open RAN portfolio to anchor European healthcare network deployments. Huawei Technologies Co., Ltd. competes on integrated baseband-to-edge systems for hospital campus networks. Qualcomm specializes in modem chipsets that sustain ultra-reliable low-latency communication for remote surgical robotics.
5G in healthcare denotes the deployment of fifth-generation cellular networks with sub-1 millisecond latency and 99.999% reliability to transmit high-definition medical video, real-time biometric streams, and haptic feedback for robotic procedures. Network Infrastructure dominates capital expenditure as hospitals replace Wi-Fi backbone systems with 5G private networks capable of supporting ten thousand connected devices per square kilometer. Software Platforms represent the fastest-expanding margin pool, particularly orchestration layers that manage quality-of-service slicing across emergency and routine traffic on shared spectrum.
The FDA regulates 5G-connected medical devices under its Software as a Medical Device framework, while the EU AI Act imposes conformity requirements on autonomous diagnostic algorithms running over 5G edge nodes. China's NMPA and MIIT jointly certify hospital private networks using dedicated 5G spectrum bands, creating a dual-approval pathway that shapes vendor selection. Stakeholders must monitor spectrum allocation decisions by national regulators, as localized mid-band licenses determine whether hospitals can deploy standalone networks or remain dependent on carrier-managed services.
Market Dynamics
Hospital IT departments face a structural squeeze as legacy Wi-Fi infrastructure proves inadequate for real-time surgical robotics and ten-thousand-device densities per square kilometer. The transition to 5G private networks demands simultaneous spectrum negotiation, vendor selection, and clinical workflow reengineering.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway compresses premarket review timelines for 5G-enabled surgical systems, accelerating commercialization for remote procedure platforms.
- China's Municipal Co-Funding Model:Yangtze River Delta governments subsidize hospital 5G upgrades, concentrating deployment capital in Shanghai, Hangzhou, and Suzhou medical clusters.
- Sub-Millisecond Latency Specification:Ultra-reliable low-latency communication enables haptic feedback loops for telesurgery, expanding addressable procedures beyond diagnostic imaging into interventional therapeutics.
Market Restraints
- Mid-Band Spectrum Scarcity:Localized license allocation determines whether hospitals deploy standalone networks or remain tethered to carrier-managed services with quality-of-service uncertainty.
- Radio Frequency Hardware Concentration:Baseband chipset and antenna module supply chains concentrate in East Asian manufacturing hubs, exposing procurement to geopolitical friction.
- EU AI Act Conformity Burden:Autonomous diagnostic algorithms running over 5G edge nodes face dual certification under MDR and AI Act frameworks, extending validation timelines.
Strategic Opportunities
- Rural Hospital Connectivity Gap:Secondary and tertiary facilities in India's tier-2 cities lack fiber backhaul, creating demand for 5G fixed-wireless as primary infrastructure.
- Network Slicing Orchestration:Software platforms that partition emergency and routine traffic on shared spectrum represent the fastest-expanding margin pool in hospital IT procurement.
- South Korea's K-New Deal:National digital health investment mandates 5G integration in public hospital construction, creating regulatory tailwind for infrastructure vendors.
Industry Challenges
- Telemedicine Engineering Bifurcation:Recruitment bottlenecks emerge as hospital IT departments compete for low-latency wireless specialists against telecom and autonomous vehicle sectors.
- Interoperability with Legacy PACS:Picture archiving and communication systems require gateway reconfiguration to ingest 5G-streamed high-definition video without workflow disruption.
- Clinical Validation Requirements:Telesurgical robotics demand procedure-specific evidence packages for institutional review boards, slowing adoption beyond demonstration pilots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 5G in Healthcare Market |
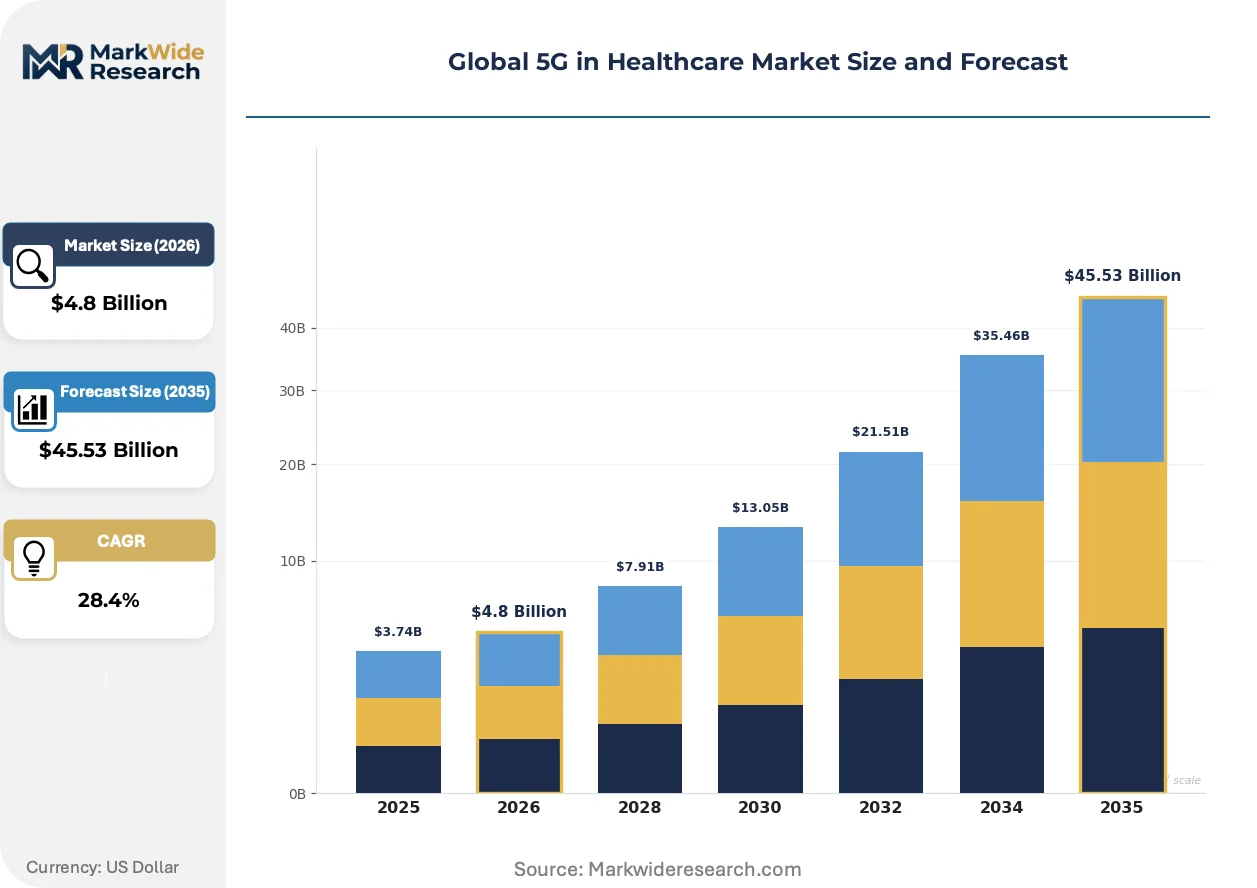
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $45.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Infrastructure, Medical Devices, Software Platforms, Connectivity Solutions Application: Remote Surgery, Teleconsultation, Patient Monitoring, Medical Imaging End User: Hospitals, Diagnostic Centers, Clinics, Emergency Services Deployment: Private Network, Public Network, Hybrid Network, Mobile Network |
| Companies Covered | AT&T Inc., Verizon Communications, China Mobile Limited, Ericsson, Nokia Corporation, Huawei Technologies Co., Ltd., Qualcomm, Cisco Systems, Inc., Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 5G in Healthcare Market Shifts & Advancements
Open RAN architectures are reshaping how hospitals procure network infrastructure, decoupling hardware from software and enabling multi-vendor deployments. This disaggregation creates new configuration complexity while reducing single-source dependency.
Private 5G networks are fragmenting the traditional carrier-hospital relationship. Teaching hospitals in Germany and South Korea now operate campus-wide standalone systems with dedicated spectrum, bypassing public network congestion. This shift compresses latency guarantees but requires in-house radio frequency engineering capabilities that most institutions lack.
The EU AI Act imposes conformity requirements on autonomous diagnostic algorithms processing patient data at 5G edge nodes. Device manufacturers must demonstrate algorithmic transparency and risk classification compliance before network deployment. European hospital procurement committees now prioritize vendors with pre-certified AI-integrated imaging platforms.
Subscription-based network service models are displacing capital-intensive ownership structures among mid-sized hospital systems. Third-party managed private networks reduce upfront spectrum and hardware investment while transferring operational risk to specialized telecom integrators. This transformation is most visible in Brazil's emerging hospital clusters, where ANVISA-regulated facilities favor operational expenditure frameworks over balance-sheet infrastructure assets.
Global 5G in Healthcare Market Segmentation
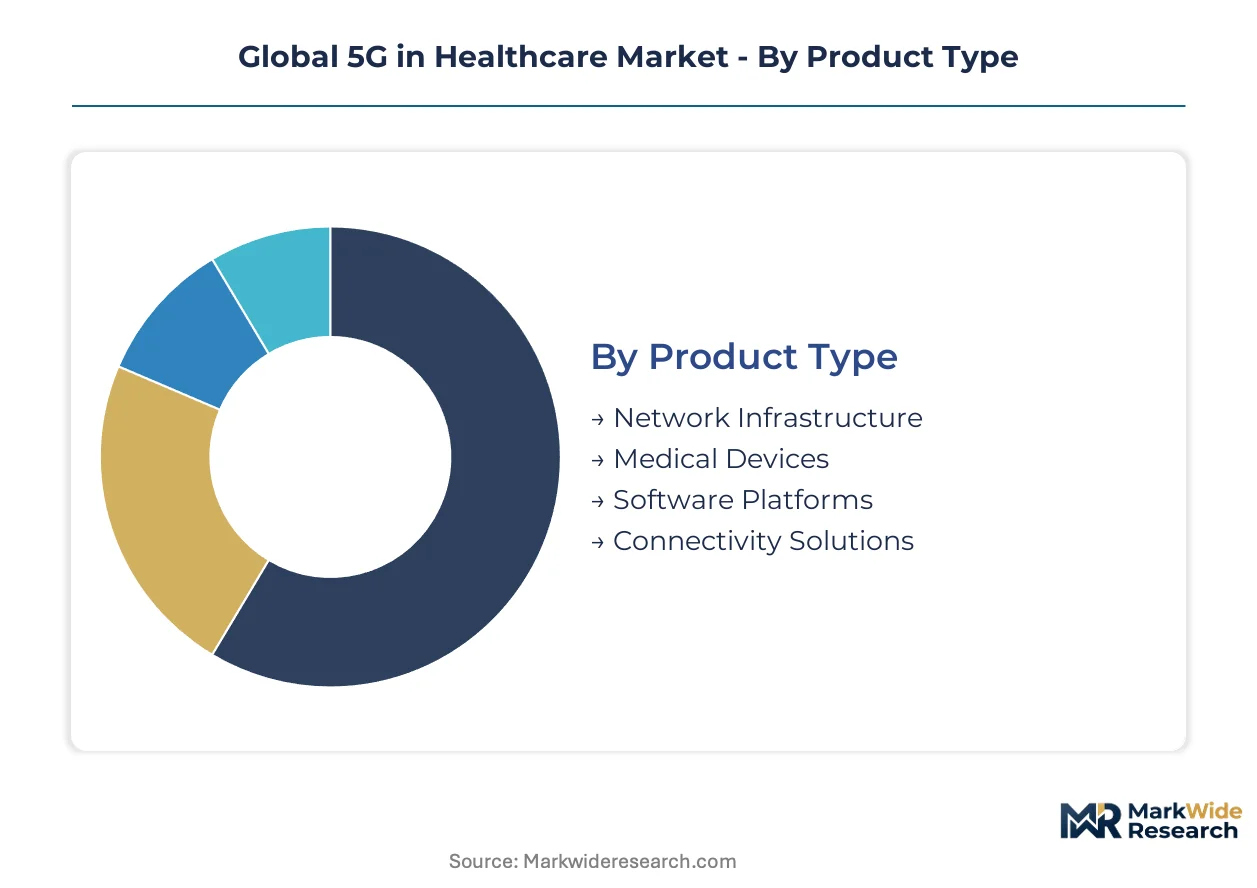
Segmentation in 5G healthcare reveals divergent capital intensity and regulatory exposure across product types and deployment models. Hospital procurement committees prioritize segments offering standalone spectrum control and FDA-validated clinical pathways.
Product Type:
Network Infrastructure concentrates manufacturing in East Asian hubs and drives cross-border procurement exposure. Software Platforms scale domestically through hospital IT departments with minimal hardware dependency.
- Network Infrastructure:Baseband chipsets, radio units, and antenna modules form the physical layer of hospital 5G deployments. German university hospitals and South Korean medical centers anchor import demand for Open RAN-compatible hardware. Spectrum licensing timelines determine whether facilities deploy standalone or carrier-managed architectures.
- Software Platforms:Orchestration layers manage quality-of-service slicing across emergency and routine traffic. China's Yangtze River Delta municipalities co-fund these deployments through public-private partnerships with tier-3 hospitals. Revenue concentrates in subscription-based network-as-a-service contracts.
- Medical Devices:5G-integrated surgical robotics and wearable diagnostic sensors require FDA breakthrough device validation.
- Connectivity Solutions:Fixed-wireless access bridges fiber gaps in India's tier-2 hospital clusters.
Network Infrastructure commands the established base. The steepest expansion runs through Software Platforms.
Application:
Cost tier stratification separates capital-intensive surgical robotics from operational-expense teleconsultation services. High-acuity applications demand dedicated spectrum slices; routine monitoring tolerates shared public networks.
- Remote Surgery:Telesurgical robotics transmit haptic feedback through sub-1 millisecond ultra-reliable low-latency communication links. South Korea's K-New Deal mandates 5G integration in public hospital construction, accelerating validation timelines for interventional platforms.
- Teleconsultation:High-definition video conferencing and asynchronous specialist review run over standard 5G enhanced mobile broadband. Brazil's ANVISA-regulated facilities favor operational expenditure frameworks for these services, displacing capital-intensive ownership structures.
- Patient Monitoring:Continuous biometric streaming from wearable sensors supports chronic disease management.
- Medical Imaging:Real-time transmission of uncompressed DICOM datasets requires edge node processing.
Teleconsultation commands the established base. Remote Surgery climbs the fastest as latency specifications harden.
End User:
Customer type determines procurement authority and integration complexity. Teaching hospitals with in-house radio frequency engineering bypass carrier dependencies; smaller clinics rely on managed service aggregators.
- Hospitals:Tertiary care centers deploy campus-wide private 5G networks with dedicated mid-band spectrum. Germany's Charité and Seoul National University Hospital operate standalone systems supporting ten-thousand-device densities per square kilometer.
- Diagnostic Centers:Imaging-focused facilities prioritize high-throughput backhaul for picture archiving and communication system integration. India's tier-2 cities drive fixed-wireless demand where fiber remains uneconomical.
- Clinics:Primary care settings adopt hybrid models balancing cost control with clinical functionality.
- Emergency Services:Ambulance-based 5G enables pre-hospital stroke diagnosis and trauma triage.
Hospitals command the established base. Diagnostic Centers gain share fastest through imaging workflow digitization.
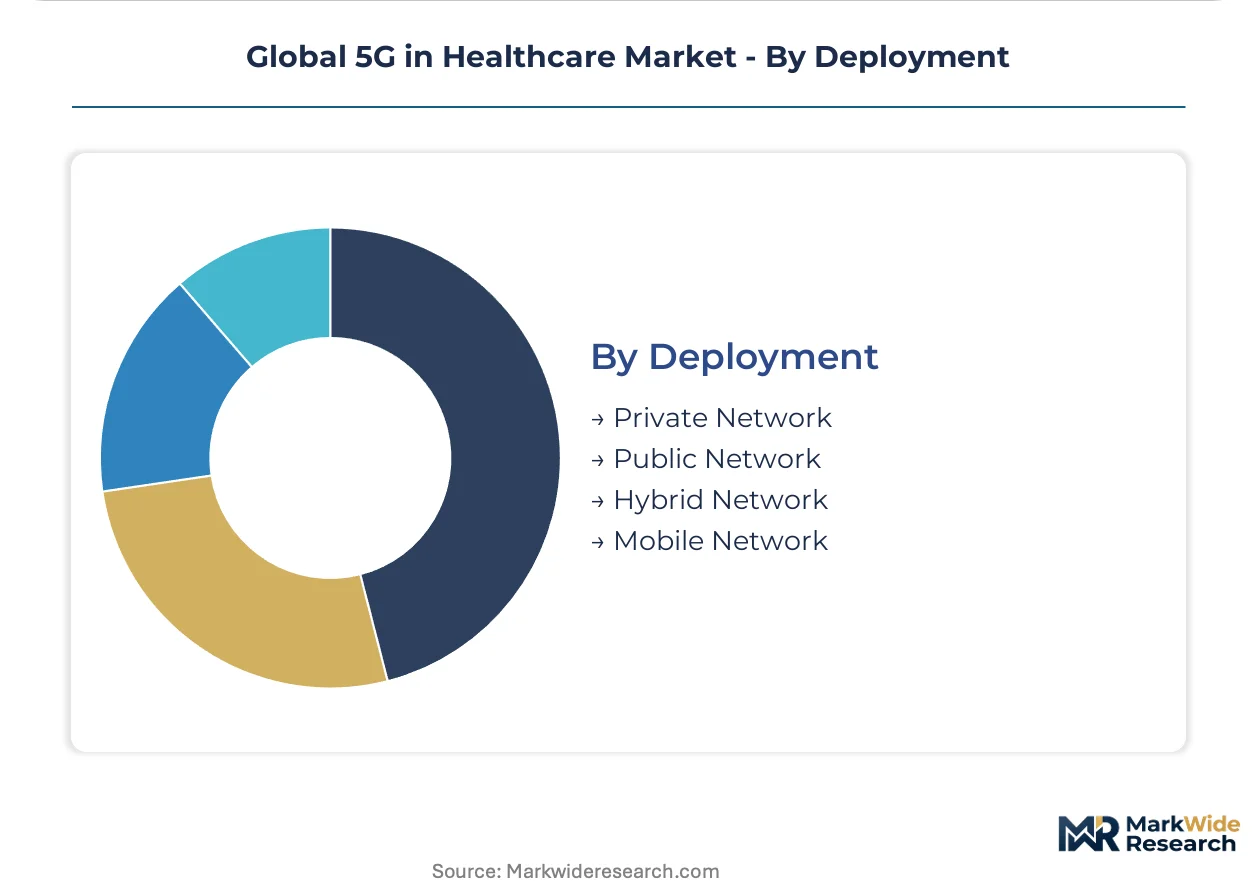
Deployment:
Supply concentration in baseband chipset manufacturing shapes procurement risk profiles. Private networks demand upfront spectrum investment; public deployments trade control for capital efficiency.
- Private Network:Standalone campus systems guarantee quality-of-service through dedicated spectrum licenses. China's NMPA and MIIT jointly certify hospital private networks, creating a dual-approval pathway that concentrates vendor selection among domestic champions.
- Public Network:Carrier-managed services reduce capital burden but introduce congestion risk during mass casualty events. Brazil's emerging hospital clusters favor this model under ANVISA operational expenditure frameworks.
- Hybrid Network:Critical traffic routes through private slices while administrative data uses public infrastructure.
- Mobile Network:Nomadic deployments support field hospitals and disaster response scenarios.
Public Network commands the established base. Private Network climbs the fastest as latency guarantees harden for surgical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations anchor United States demand for 5G-enabled surgical systems. The regulator's compressed review timelines accelerate commercialization for remote procedure platforms. This regulatory tailwind concentrates deployment capital in tertiary care centers.
United States
Teaching hospitals in Boston and Houston deploy campus-wide private 5G networks for telesurgical robotics. FDA breakthrough pathways compress premarket validation for haptic feedback systems. The Mayo Clinic and Cleveland Clinic anchor standalone network demand in the Upper Midwest.
Germany
Charité Berlin and university hospitals in Munich operate Open RAN-compatible infrastructure for ten-thousand-device densities. The EU AI Act imposes conformity requirements on autonomous diagnostic algorithms at 5G edge nodes. Bavaria's medical technology corridor concentrates baseband hardware procurement.
China
Yangtze River Delta municipalities co-fund hospital 5G upgrades through public-private partnerships. NMPA and MIIT jointly certify private networks using dedicated mid-band spectrum. Shanghai, Hangzhou, and Suzhou medical clusters dominate deployment velocity.
South Korea
Seoul National University Hospital operates standalone systems supporting haptic feedback loops for interventional therapeutics. The K-New Deal mandates 5G integration in public hospital construction. Busan-Ulsan medical centers anchor validation timelines for surgical robotics.
Brazil
ANVISA-regulated facilities in São Paulo favor operational expenditure frameworks for teleconsultation services. Third-party managed private networks reduce upfront spectrum investment. Emerging hospital clusters in Minas Gerais and Rio de Janeiro displace capital-intensive ownership structures.
Global 5G in Healthcare Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in hospital 5G procurement. Tier-one vendors bundle spectrum negotiation with hardware deployment, while tier-two players focus on software orchestration layers. Three archetypes dominate: telecom carriers with licensed spectrum holdings, infrastructure vendors with Open RAN portfolios, and semiconductor specialists with ultra-reliable low-latency communication chipsets. Competitive moves center on strategic partnerships with hospital systems and geographic expansion into municipal co-funding zones.
Within the integrated infrastructure tier, Ericsson anchors European healthcare network deployments through its Open RAN portfolio. Huawei Technologies Co., Ltd. occupies a position in integrated baseband-to-edge systems for hospital campus networks. Qualcomm exemplifies the semiconductor specialist archetype with modem chipsets sustaining ultra-reliable low-latency communication for remote surgical robotics.
| Leading Market Players |
|---|
| AT&T Inc. |
| Verizon Communications |
| China Mobile Limited |
| Ericsson |
| Nokia Corporation |
| Huawei Technologies Co., Ltd. |
| Qualcomm |
| Cisco Systems, Inc. |
| Samsung Electronics Co., Ltd. |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with East Asian baseband chipset manufacturers lock in supply access for hospital 5G deployments while anchoring price visibility across multi-year procurement cycles. These agreements transfer inventory risk upstream and shield European and North American integrators from spot-market volatility in radio frequency hardware.
Pricing Analysis
Geographic price spreads widen between carrier-managed public network services and standalone private 5G deployments, with the latter commanding premiums of 40-60% for dedicated spectrum guarantees. Subscription-based network-as-a-service models dominate procurement among mid-sized hospital systems, particularly in Brazil's ANVISA-regulated facilities, while tier-1 teaching hospitals favor capital-intensive ownership. Price differentiation hinges on FDA breakthrough device certification tier and spectrum license exclusivity level. Pricing pressure intensifies in the software orchestration layer as open-source alternatives commoditize quality-of-service slicing functions. Public hospital systems in South Korea exhibit lowest price sensitivity due to K-New Deal co-funding; India's tier-2 diagnostic centers face acute budget constraints.
Supply Chain Analysis
Baseband chipset fabrication concentrates in Taiwan, South Korea, and mainland China, creating single-source vulnerability for hospital 5G radio units. Radio frequency front-end modules and antenna arrays draw from Japanese substrate suppliers and German precision component manufacturers. Supply chain risk centers on export control friction affecting semiconductor equipment access. Distribution runs through telecom integrators who bundle spectrum negotiation with hardware deployment, compressing direct hospital-vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment. FDA and EU AI Act certification timelines create switching costs that cement incumbent positions once hospital procurement committees validate vendor platforms.
For Market Incumbents: Secure spectrum holdings in China's Yangtze River Delta and South Korea's K-New Deal zones ahead of municipal co-funding allocation cycles. Deepen backward integration into baseband chipset supply through strategic foundry partnerships, insulating against East Asian manufacturing concentration. Counter open-source orchestration threats by embedding proprietary AI diagnostics at 5G edge nodes, raising hospital switching costs through workflow dependency. For New Entrants and Emerging Players: Differentiate on rural hospital connectivity gaps in India's tier-2 cities, where fixed-wireless backhaul substitutes for uneconomical fiber deployment. Target diagnostic center imaging workflow digitization as the fastest-expanding end-user segment with lower certification barriers than surgical robotics. Pursue white-label network-as-a-service partnerships with established telecom integrators to bypass direct hospital sales cycle complexity. For Investors and Strategic Acquirers: Semiconductor specialists with ultra-reliable low-latency communication patent portfolios represent prime acquisition targets as haptic feedback specifications harden for telesurgery. Long-term viability favors vendors with dual regulatory track records across FDA breakthrough pathways and EU AI Act conformity frameworks. Watch for inflection when NMPA-MIIT joint certification timelines compress, signaling China's acceleration of hospital private network deployment.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates premarket review for 5G-enabled surgical robotics, compressing time-to-revenue for remote procedure platforms. |
| Hospital System Partnership | Locks in multi-year private network deployments at Charité Berlin and Seoul National University Hospital, creating reference architecture pull-through. |
| Software Companion Development | Integrates AI diagnostics at 5G edge nodes, satisfying EU AI Act transparency requirements for autonomous imaging algorithms. |
| Spectrum License Acquisition | Secures dedicated mid-band allocation in China's Yangtze River Delta ahead of municipal co-funding disbursement windows. |
| Reimbursement Strategy | Aligns telesurgical robotics with CMS and national health service payment codes, unlocking hospital capital expenditure authorization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital IT directors, biomedical engineers, GPO contracts managers, and telecom integration specialists; and secondary validation against FDA 510(k) and breakthrough device filings, EU MDR and AI Act conformity databases, NMPA-MIIT joint certification registries, and hospital procurement contract disclosures. Bottom-up demand modeling triangulated against top-down spectrum allocation forecasts and infrastructure vendor shipment data.
Across the analysis window, forecasts incorporated segmentation by product type, application acuity tier, end-user procurement authority, and deployment architecture. CAGRs derived from hospital capital expenditure survey data, municipal co-funding commitment tracking, and regulatory approval velocity indices. Industry-specific inputs included telesurgical robotics validation timelines and private 5G spectrum license issuance rates by national regulator.
The analysis sits within stated boundaries; outcomes outside sustained mid-band spectrum availability and stable East Asian semiconductor equipment access would require recalibration. Forecasts reflect assumptions regarding FDA breakthrough pathway continuity and EU AI Act enforcement intensity. Revision becomes warranted when geopolitical friction crosses thresholds affecting baseband chipset supply chain integrity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Transport Networks Market
Telecommunications
Fixed LTE Market
Telecommunications
Germany Critical Communication Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
Global Premium A2P and P2A Messaging Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Belgium Telecom Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Telecom Services Market
Telecommunications
International Wholesale Voice Carrier Market