
 5G Network and Service Assurance Market | 2026-2036
5G Network and Service Assurance Market Size, Share, and Industry Trends Forecast 2026-2036
5G Network and Service Assurance Market Insights
The direct-to-telco software channel is rewriting how assurance vendors reach network operators. Ericsson leverages its installed base of radio infrastructure to bundle performance management suites with hardware contracts. Nokia Corporation competes through cloud-native architectures that anchor multi-vendor interoperability. EXFO Inc. specializes in test and measurement instrumentation that extends into real-time monitoring for fiber-intensive 5G transport networks.
5G Network and Service Assurance encompasses systems that verify service-level agreements across virtualized radio access networks using telemetry streams, synthetic probes, and AI/ML-driven root-cause analysis operating at sub-second latency thresholds. These platforms enable telecommunication providers to automate remediation before subscriber-impacting degradation occurs. Network Slicing assurance commands premium positioning because each slice requires isolated performance contracts with distinct fault domains. AI/ML Analytics represents the fastest-expanding technology segment as operators deploy inference engines at the edge to reduce backhaul costs. Service Orchestration sits at the margin pool intersection where assurance workflows merge with intent-based network automation.
The FCC mandates network reliability reporting that shapes how US operators procure fault management platforms with audit-ready telemetry retention. ETSI standards and the EU AI Act constrain automated decision systems in European networks, forcing explainability layers into assurance algorithms. Stakeholders must decide whether to build sovereign AI inference stacks or accept cloud-dependent analytics architectures with cross-border data governance exposure.
Market Dynamics
Network slicing complexity is fragmenting fault domains into isolated performance contracts, forcing assurance vendors to rebuild architectures around slice-specific telemetry pipelines rather than monolithic network monitoring.
Growth Catalysts
- EU AI Act compliance mandates:European operators must deploy explainable AI layers in automated root-cause analysis, creating replacement demand for legacy black-box systems.
- Industrial private 5G deployment:German manufacturing clusters require specialized service orchestration tools that verify SLA isolation across dedicated campus networks.
- Edge inference engines:AI/ML analytics operating at sub-second latency thresholds reduce backhaul costs for telecommunication providers managing distributed radio access networks.
Market Restraints
- Optical transport component concentration:Fiber-intensive 5G backhaul depends on specialized photonic hardware with limited qualified supplier bases in East Asian manufacturing hubs.
- Cross-border data governance exposure:Cloud-dependent analytics architectures face sovereignty restrictions that fragment operational visibility across national network boundaries.
- Virtualized radio access complexity:Disaggregated RAN architectures multiply the number of fault correlation points, stretching engineering teams across multi-vendor integration layers.
Strategic Opportunities
- FCC reliability reporting mandates:US operators must maintain audit-ready telemetry retention, opening subscription revenue for compliance-as-a-service assurance platforms.
- Intent-based network automation convergence:Service orchestration workflows merging with assurance systems create margin pool capture at the control plane layer.
- Multi-vendor interoperability gaps:Cloud-native architectures that anchor heterogeneous equipment environments address procurement fragmentation among tier-two operators.
Industry Challenges
- ML operations talent scarcity:Deployment of inference engines at network edge requires scarce data engineering skills that compete with hyperscaler compensation packages.
- Synthetic probe infrastructure capex:Continuous active monitoring of slice performance demands dedicated hardware investments that strain capital allocation committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Network and Service Assurance Market |
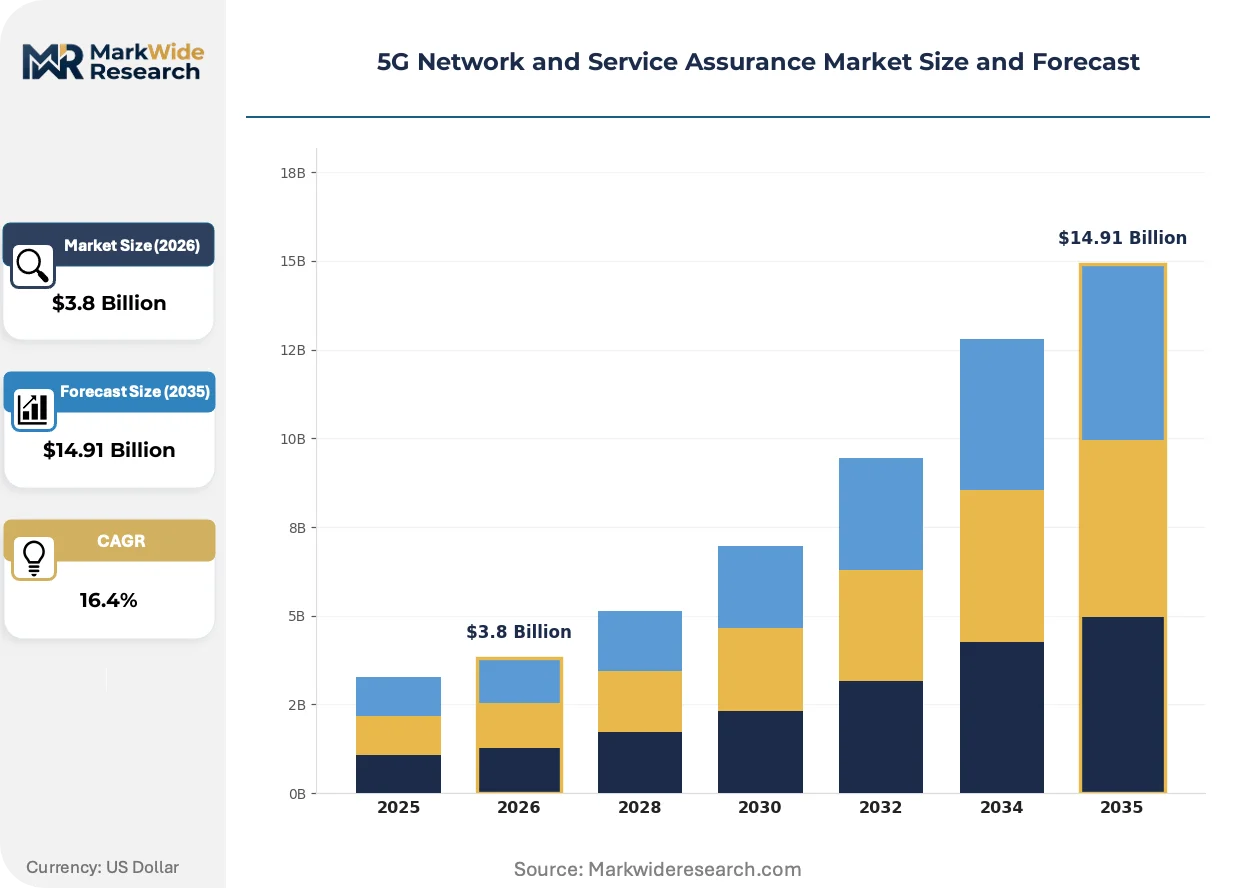
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Monitoring, Performance Management, Service Orchestration, Fault Management Technology: Network Slicing, Edge Computing, Cloud RAN, AI/ML Analytics End User: Telecommunication Providers, Enterprises, Government Agencies, Managed Service Providers Deployment Model: Private Network, Public Network, Hybrid Network, On-Premise |
| Companies Covered | Amdocs, EXFO Inc., Ericsson, Oracle Corporation, RADCOM Ltd., Nokia Corporation, NEC Corporation, VIAVI Solutions Inc., NETSCOUT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Network and Service Assurance Market Trends and Innovations
Intelligent assurance platforms are compressing the gap between fault detection and automated remediation, eliminating human-in-the-loop delays that previously defined network operations center workflows.
Telemetry stream processing is collapsing the latency budget for root-cause analysis from minutes to milliseconds. Telecommunication providers operating fiber-intensive transport networks now ingest synthetic probe data through stream-processing engines that correlate anomalies across virtualized radio access layers. This compression eliminates the batch-analysis windows that previously delayed subscriber-impacting degradation alerts.
ETSI standards for network function virtualization are mandating standardized assurance interfaces across European deployments. The EU AI Act adds algorithmic explainability requirements that force vendors to expose decision pathways in automated remediation systems. Operators in Germany and France now specify interpretable ML models in procurement tenders, rejecting opaque neural network architectures.
Buyer concentration among tier-one operators is forcing assurance vendors to unbundle perpetual licenses into consumption-based pricing. Telecommunication procurement teams now negotiate metered contracts tied to monitored slice volume rather than network element count. This shift is most visible in US operator RFPs, where finance departments demand opex alignment with subscriber growth volatility.
5G Network and Service Assurance Market Segmentation
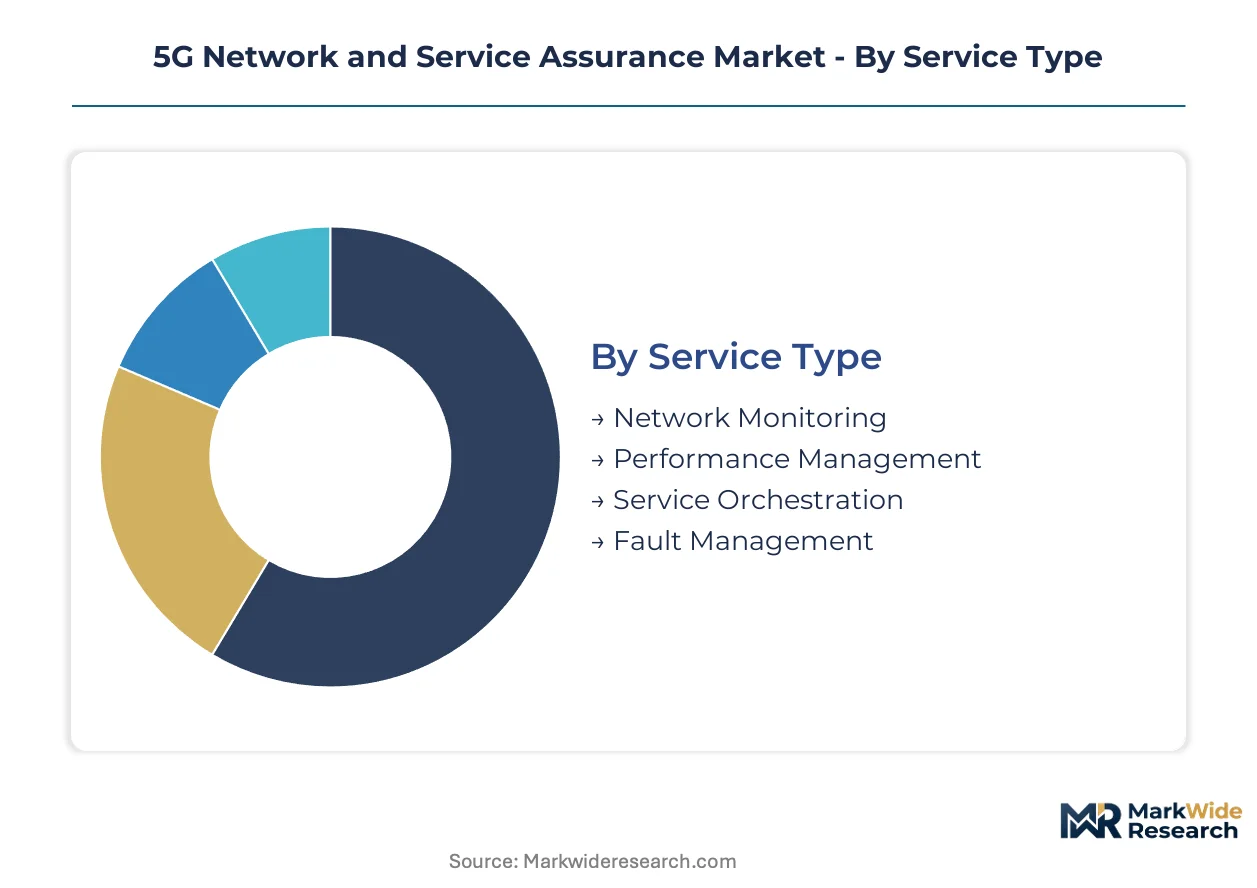
5G Network and Service Assurance segmentation reveals how vendor architectures align with distinct operational requirements across network layers. Each dimension exposes different margin structures and procurement decision criteria.
Service Type:
Service type segmentation maps directly to operational workflows inside network operations centers, with each function commanding different integration depth and pricing power.
- Network Monitoring:Continuous telemetry ingestion from radio access network elements provides baseline visibility into subscriber-facing performance metrics. Telecommunication providers in Germany prioritize this capability for industrial private 5G campus deployments where SLA verification demands real-time dashboards.
- Performance Management:Synthetic probe infrastructure and subscriber experience scoring enable proactive degradation detection before ticket generation. US operators facing FCC reliability reporting mandates concentrate procurement here to maintain audit-ready telemetry retention with automated threshold alerting.
- Service Orchestration:Intent-based automation workflows that translate business policies into network configuration changes across multi-vendor environments.
- Fault Management:Correlation engines that compress mean-time-to-repair through automated root-cause analysis and ticket enrichment.
The dominant share belongs to Network Monitoring, while Performance Management is closing the gap fastest.
Technology:
Technology segmentation tracks how assurance architectures evolve from passive observation toward predictive intervention.
- Network Slicing:Isolated performance contracts with distinct fault domains require slice-specific telemetry pipelines rather than monolithic monitoring. German manufacturing clusters drive demand for specialized orchestration tools that verify SLA isolation across dedicated campus networks.
- AI/ML Analytics:Inference engines deployed at network edge reduce backhaul costs while enabling sub-second root-cause analysis. European operators under EU AI Act compliance mandates specify explainable ML models in procurement tenders, rejecting opaque neural network architectures.
- Edge Computing:Distributed processing nodes that host assurance functions closer to radio access network elements.
- Cloud RAN:Virtualized baseband processing architectures that multiply fault correlation points across disaggregated infrastructure layers.
AI/ML Analytics commands the steepest expansion trajectory as operators replace legacy rule-based systems, though Network Slicing captures the premium pricing tier.
End User:
End user segmentation exposes how buyer sophistication and procurement authority shape vendor engagement models.
- Telecommunication Providers:Tier-one operators with centralized procurement teams negotiate metered contracts tied to monitored slice volume. US operator finance departments demand opex alignment with subscriber growth volatility, forcing unbundling of perpetual licenses.
- Enterprises:Manufacturing and logistics clusters deploying private 5G networks require specialized service orchestration with simplified operational interfaces.
- Government Agencies:Sovereign network deployments with classified traffic isolation requirements and domestic data residency constraints.
- Managed Service Providers:Multi-tenant assurance platforms that aggregate monitoring across disparate client infrastructures.
Telecommunication Providers retain the largest contract values, while Enterprises are gaining procurement velocity fastest.
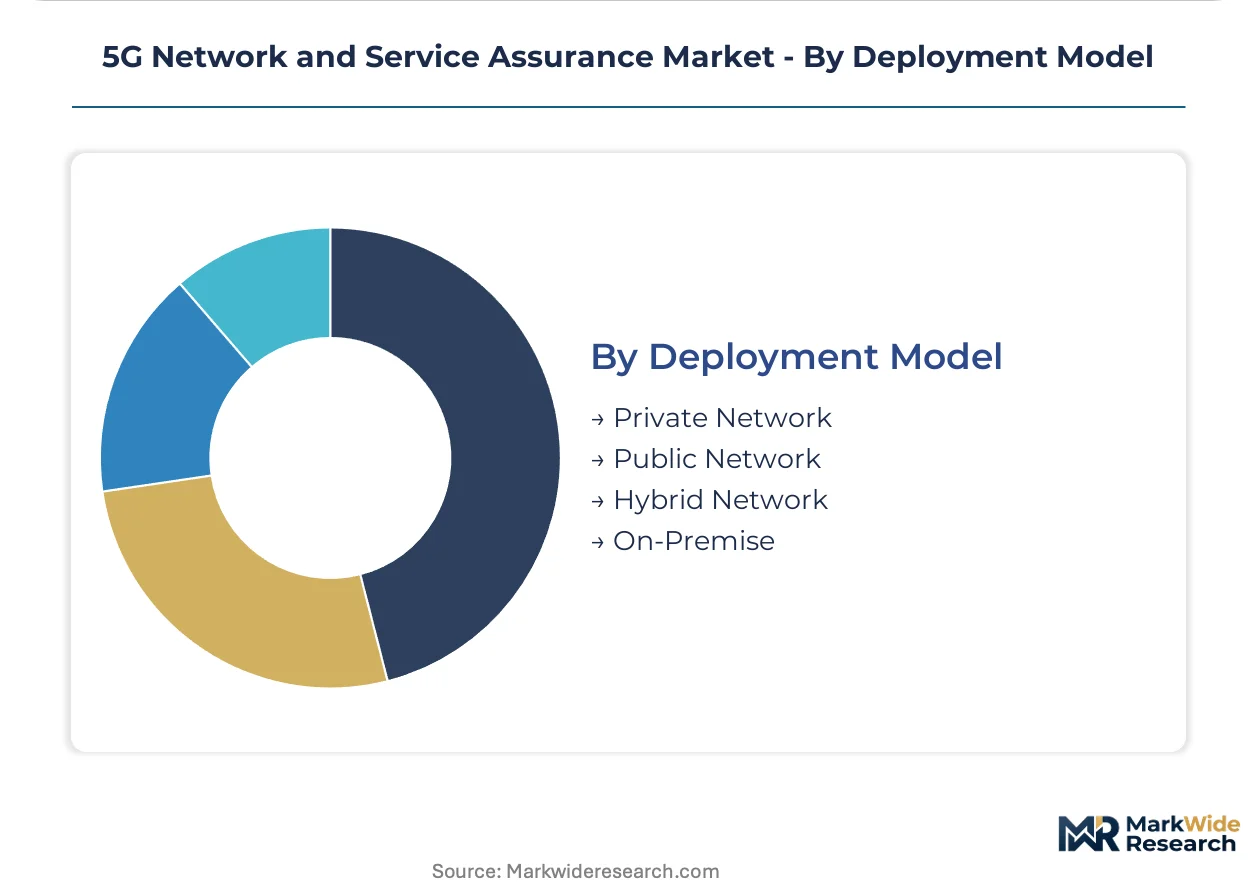
Deployment Model:
Deployment model segmentation reflects tension between operational control and capital efficiency in infrastructure decisions.
- Private Network:Dedicated assurance stacks deployed within campus boundaries for complete data sovereignty and customizable SLA frameworks.
- Public Network:Shared infrastructure monitoring where operators subscribe to assurance capabilities as-a-service without hardware ownership.
- Hybrid Network:Split architectures that retain sensitive analytics on-premise while leveraging cloud scale for non-critical processing workloads.
- On-Premise:Fully captive installations addressing cross-border data governance exposure in jurisdictions with strict sovereignty restrictions.
Hybrid Network configurations are expanding most quickly as operators balance latency requirements against cloud economics, while On-Premise retains preference in regulated European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landing stations in Portugal anchor transatlantic data flows that underpin European 5G backhaul capacity. Dense fiber corridors between Frankfurt and Amsterdam create low-latency pathways for network slicing traffic. These infrastructure assets shape where assurance vendors prioritize platform deployment.
United States
Major carriers in the United States operate disaggregated RAN architectures across 50 states that multiply fault correlation complexity. The FCC mandates network reliability reporting with audit-ready telemetry retention periods. Verizon and AT&T procurement teams in Dallas and Atlanta negotiate metered assurance contracts tied to monitored slice volume rather than element count.
Germany
Industrial private 5G deployments at Volkswagen's Wolfsburg campus and BASF's Ludwigshafen complex require specialized service orchestration tools. The EU AI Act forces explainable AI layers into automated root-cause analysis systems. Manufacturing clusters in Bavaria and Baden-Württemberg specify interpretable ML models in procurement tenders, rejecting opaque neural network architectures.
China
China Mobile and China Unicom operate cloud-native RAN deployments across 31 provincial-level divisions with centralized procurement authority. MIIT standards mandate interoperability testing for multi-vendor assurance platforms. Shenzhen and Shanghai host the dominant concentration of edge inference engine deployments for sub-second latency analytics.
Japan
NTT Docomo and KDDI manage network slicing for industrial automation across the Tokyo-Osaka corridor with strict latency requirements. METI guidelines promote domestic AI chip development for sovereign inference stacks. Yokohama and Nagoya manufacturing ports drive demand for campus network assurance with customizable SLA frameworks.
India
Reliance Jio and Bharti Airtel deploy massive MIMO infrastructure across 22 telecom circles with fragmented vendor ecosystems. TRAI regulations mandate quality of service monitoring with public disclosure thresholds. Bengaluru and Hyderabad tech corridors attract assurance vendors targeting cloud-native orchestration for emerging enterprise private networks.
5G Network and Service Assurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in test instrumentation and probe hardware. The vendor landscape consolidates around three distinct tiers: infrastructure incumbents with radio hardware installed bases, pure-play software vendors with cloud-native architectures, and test equipment specialists extending into real-time monitoring. Strategic moves concentrate on unbundling perpetual licenses into consumption-based pricing and building multi-vendor interoperability layers that reduce procurement fragmentation.
Within the infrastructure-integrated tier, Ericsson and Nokia Corporation represent archetypes of bundled hardware-software positioning. EXFO Inc. anchors the test-to-assurance extension strategy among measurement specialists. These three companies exemplify how geographic origin and corporate structure shape competitive approach: Swedish and Finnish telecom infrastructure heritage versus Canadian instrumentation specialization.
| Leading Market Players |
|---|
| Amdocs |
| EXFO Inc. |
| Ericsson |
| Oracle Corporation |
| RADCOM Ltd. |
| Nokia Corporation |
| NEC Corporation |
| VIAVI Solutions Inc. |
| NETSCOUT |
| Others |
Pricing and Supply Chain Analysis
The trans-Pacific fiber optic cable corridor linking Los Angeles to Yokohama carries synthetic probe hardware and edge inference engines that anchor supply costs for assurance vendors. This logistics pathway concentrates procurement leverage among tier-one telecommunication providers while fragmenting pricing power across metered SaaS tiers, volume-scaled perpetual licenses, and project-based professional services.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade network slicing assurance from mid-market performance management and entry-level monitoring dashboards. Pricing stratifies across premium, standard, and economy tiers based on SLA customization depth and AI/ML explainability certification levels. Cost compression in the standard tier intensifies because cloud-native vendors are displacing legacy appliance-based contracts. Tier-one telecommunication providers exhibit lowest price sensitivity due to bundled hardware-software procurement authority, while tier-two operators and enterprise private network deployers negotiate aggressively on per-slice metering rates.
Supply Chain Analysis
Contract-manufacturing concentration rests with Foxconn and Jabil for edge computing hardware, while specialized photonic component foundries in Taiwan and South Korea hold capacity for fiber-intensive transport instrumentation. Raw material dependencies include silicon photonics chips, high-frequency RF components, and rare-earth doped fiber amplifiers. Single-source vulnerability in East Asian photonic hardware suppliers exposes assurance platform vendors to tariff exposure and logistics chokepoints at Shanghai and Busan port complexes. Distribution runs through direct-to-telco software channels and systems integrator partnerships that bundle assurance suites with radio infrastructure contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in industrial private 5G deployments, where manufacturing clusters demand specialized service orchestration tools that diverge from standardized telco-grade platforms. Network slicing complexity creates niche openings for vendors with campus-specific SLA verification capabilities.
For Market Incumbents: Insulate installed-base revenue by embedding assurance functions deeper into radio hardware contracts, countering cloud-native disaggregation threats from pure-play software vendors. Prioritize backward integration into synthetic probe manufacturing to capture margin pool compression at the instrumentation layer. Accelerate explainable AI certification investments to preempt EU AI Act compliance displacement of black-box root-cause analysis systems.
For New Entrants and Emerging Players: Campus networks in India and Southeast Asia represent underpenetration where fragmented vendor ecosystems and price-sensitive procurement create white-space openings. Target tier-two telecommunication providers in emerging markets with multi-vendor interoperability guarantees that reduce integration risk. Deploy consumption-based pricing models that align with opex-preferred finance structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from infrastructure incumbents spinning off non-core assurance software units to focus on radio hardware core competencies. Long-term viability favors vendors with sovereign AI inference stacks that address cross-border data governance restrictions. Monitor TRAI quality-of-service disclosure mandates and FCC reliability reporting enforcement as inflection indicators for compliance-driven replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Merging assurance workflows with intent-based network automation captures control plane margins at Ericsson and Nokia. |
| Acquisition of Specialist Firm | Test equipment vendors like EXFO extend real-time monitoring capabilities through synthetic probe technology tuck-ins. |
| Geographic Expansion | German manufacturing clusters drive specialized service orchestration tools for industrial private 5G campus deployments. |
| Product Launch | Explainable AI layers address EU AI Act mandates and displace opaque neural network architectures in European tenders. |
| Strategic Partnership | Multi-vendor interoperability agreements reduce procurement fragmentation among tier-two operators with heterogeneous equipment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ETSI standardization documents, FCC enforcement releases, and telecommunication operator procurement databases. Conversations with network operations center directors, cloud-native assurance vendors, systems integration specialists, and industrial private 5G deployers informed demand-side validation. SEC filings from infrastructure incumbents, MIIT interoperability testing records, and hyperscaler edge computing capex disclosures provided supply-side triangulation against bottom-up segment sizing.
Forecast inputs include network slicing deployment trajectories, AI/ML analytics adoption curves, and service orchestration convergence patterns across the projection horizon. Segmentation dimensions modeled encompass service type, technology layer, end-user sophistication, and deployment model architecture. CAGRs derive from iterative reconciliation of operator capex guidance, vendor booking disclosures, and regulatory mandate timelines without assuming technological discontinuities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscalers entering network assurance or sovereign AI stack mandates from national regulators would shift outcomes. Quarterly review of ETSI standardization progress, FCC enforcement actions, and industrial private 5G spectrum allocation auctions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Hungary ICT Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Myanmar ICT Market
Telecommunications
Global 5G Services Market
Telecommunications
Kenya Telecom Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Chile Telecom Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Denmark ICT Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Satellite Broadband Communication in Public Safety Market