
 Global Premium A2P and P2A Messaging Market | 2026-2036
Global Premium A2P and P2A Messaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Premium A2P and P2A Messaging Market Foresight
Enterprise buyers in banking and e-commerce are reorganizing procurement priorities around omnichannel messaging orchestration. Twilio Inc. leverages its cloud-native platform architecture to capture developer-centric adoption across North American fintech deployments. Sinch anchors European market presence through direct carrier integrations with Deutsche Telekom AG and Vodafone Limited. Infobip competes on emerging market density, particularly in Southeast Asia and Latin America where USSD-to-smartphone transitions create upgrade pathways.
Premium A2P and P2A messaging encompasses application-to-person and person-to-application communication protocols that route structured content through carrier-grade signaling infrastructure with guaranteed delivery timestamps and sender authentication. The technology stack spans SMS fallback, RCS rich media channels, and OTT messaging APIs, serving critical functions in payment confirmation, fraud alerts, and conversational commerce workflows. Transactional messaging dominates volume flows due to banking and e-commerce platform dependency on one-time password delivery, while RCS technology is capturing margin concentration as Apple and Google expand interoperability standards. Cloud-based deployment mode is displacing on-premise installations among mid-market enterprises seeking elastic capacity during promotional campaign spikes.
The FCC enforces STIR/SHAKEN caller ID authentication standards that extend into messaging origin verification, tightening access for unregistered A2P aggregators. EMA and GDPR frameworks in Europe mandate explicit opt-in documentation and granular consent withdrawal mechanisms, elevating compliance costs for promotional message streams. Stakeholders must monitor regulatory divergence between privacy-first jurisdictions and markets prioritizing digital inclusion, as this tension will determine which technology standards achieve cross-border interoperability.
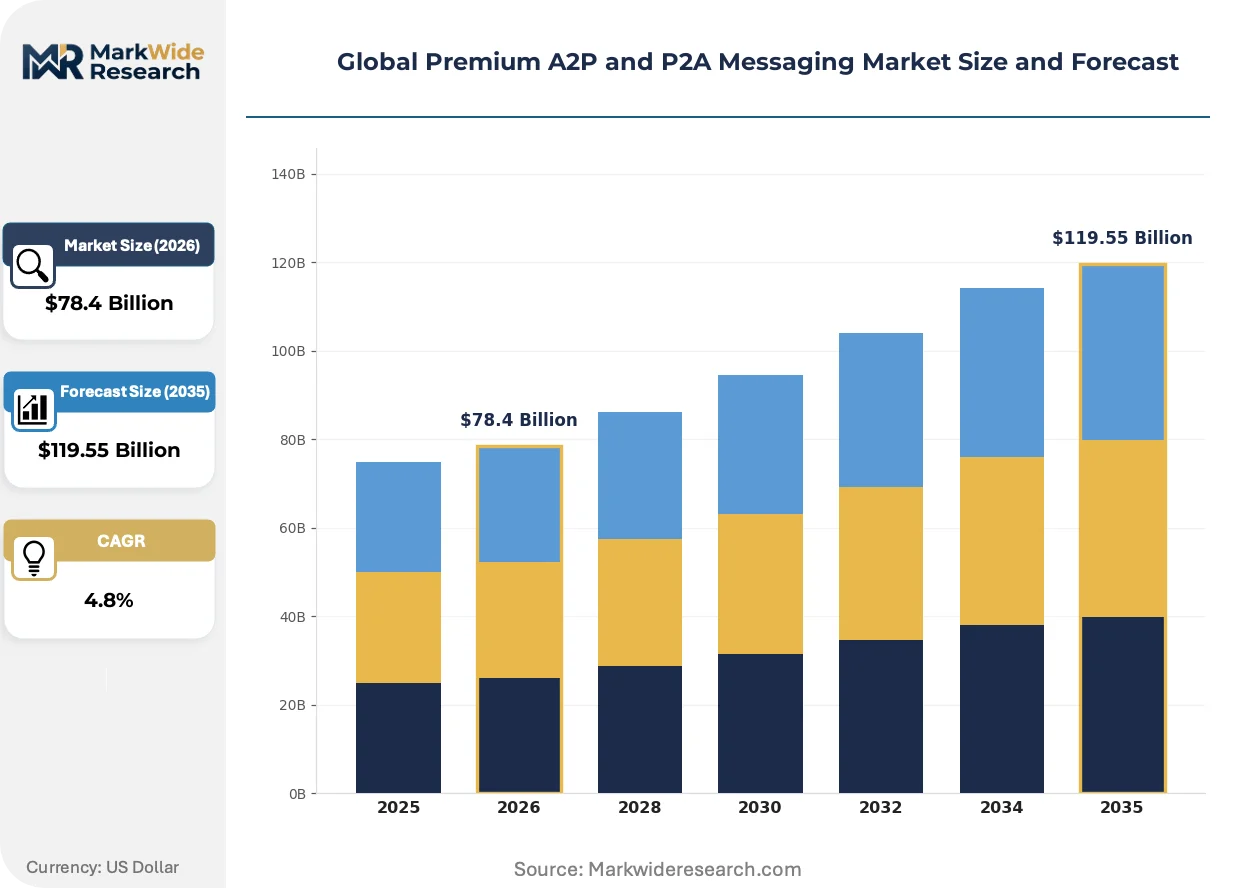
Market Dynamics
Carrier-grade RCS infrastructure is supplanting SMS fallback protocols as the default transport layer for transactional messaging, compressing margins for legacy aggregators while elevating authentication requirements across banking and retail deployments.
Growth Catalysts
- TRAI mandate:India's telecommunications regulator enforces strict sender ID registration and scrubbing requirements, legitimizing premium A2P channels and filtering gray-route traffic from unregistered aggregators.
- Real-time payment confirmation:E-commerce platforms and digital wallet providers in Southeast Asia embed rich media receipts and one-tap support flows directly within messaging threads, converting notification pipes into commerce surfaces.
- EU AI Act compliance layers:Automated decision-making disclosures and consent audit trails for AI-powered chatbot interactions create demand for verified messaging infrastructure with embedded documentation capabilities.
Market Restraints
- Input cost volatility:Carrier termination fees in emerging markets fluctuate with currency instability and interconnection disputes, squeezing aggregator margins on international routes.
- Supply concentration risk:Apple and Google control RCS client distribution and interoperability standards, creating gatekeeper dependency for rich media message rendering.
- Regulatory friction:GDPR's granular consent withdrawal mechanisms and documentation retention requirements impose operational overhead on promotional message streams that SMS-era infrastructure cannot automate.
Strategic Opportunities
- Underpenetrated LATAM corridors:Brazil and Mexico exhibit smartphone penetration above 75 percent but RCS carrier enablement below 40 percent, creating upgrade runway for verified messaging infrastructure.
- Conversational commerce convergence:Integration of payment APIs, identity verification, and LLM-powered natural language understanding within single messaging threads enables end-to-end transaction completion without app switching.
- India's PLI scheme:Production-linked incentives for telecom equipment manufacturing reduce hardware costs for edge messaging infrastructure deployment in tier-2 and tier-3 urban clusters.
Industry Challenges
- Certification timeline compression:STIR/SHAKEN extension into messaging origin verification and GDPR consent audit requirements demand parallel compliance tracks that strain mid-market aggregator operational bandwidth.
- Legacy system integration friction:Enterprise IT departments confront protocol translation complexity when grafting RCS rich media capabilities onto core banking systems architected for 160-character SMS payloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Premium A2P and P2A Messaging Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Message Type: Transactional, Promotional, Two-Factor Authentication, Customer Support, Alerts Technology: SMS, RCS, USSD, Email-to-SMS, OTT Messaging End User: Banks, E-Commerce Platforms, Telecommunications Providers, Government Agencies, Travel Operators Deployment Mode: Cloud-Based, On-Premise, Hybrid, Managed Services |
| Companies Covered | Twilio Inc., AT&T, Sinch, Deutsche Telekom AG, Vodafone Limited, Infobip, CLX Communications, Dialogue Communications Ltd., Beepsend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Premium A2P and P2A Messaging Market Shifts & Advancements
Authentication-first infrastructure deployment is reshaping competitive positioning across the messaging stack. Three distinct vectors are compressing legacy operating models while opening premium service tiers.
RCS Business Messaging is supplanting SMS as the transport protocol for high-value transactional flows. Banking applications in Germany and the Netherlands are migrating fraud alerts and payment confirmations to verified rich channels at accelerated pace. This technology shift is enabling margin expansion for carriers and platform providers while compressing volume-based aggregator economics.
The EU AI Act's transparency requirements for automated decision systems are mandating auditable consent chains within conversational interfaces. Financial services deployments across France and Spain must now embed machine-readable disclosure records directly within message metadata. Promotional message streams face elevated compliance costs as granular withdrawal mechanisms replace batch unsubscribe processing.
Enterprise procurement of messaging infrastructure is consolidating around API-first platform contracts with embedded compliance tooling. Retail and logistics buyers in India are displacing point-solution SMS aggregators with orchestration layers that unify RCS, WhatsApp Business, and native app push notifications. This vendor consolidation pattern is most visible among Series C and public e-commerce platforms seeking unified analytics across customer touchpoints.
Global Premium A2P and P2A Messaging Market Segmentation
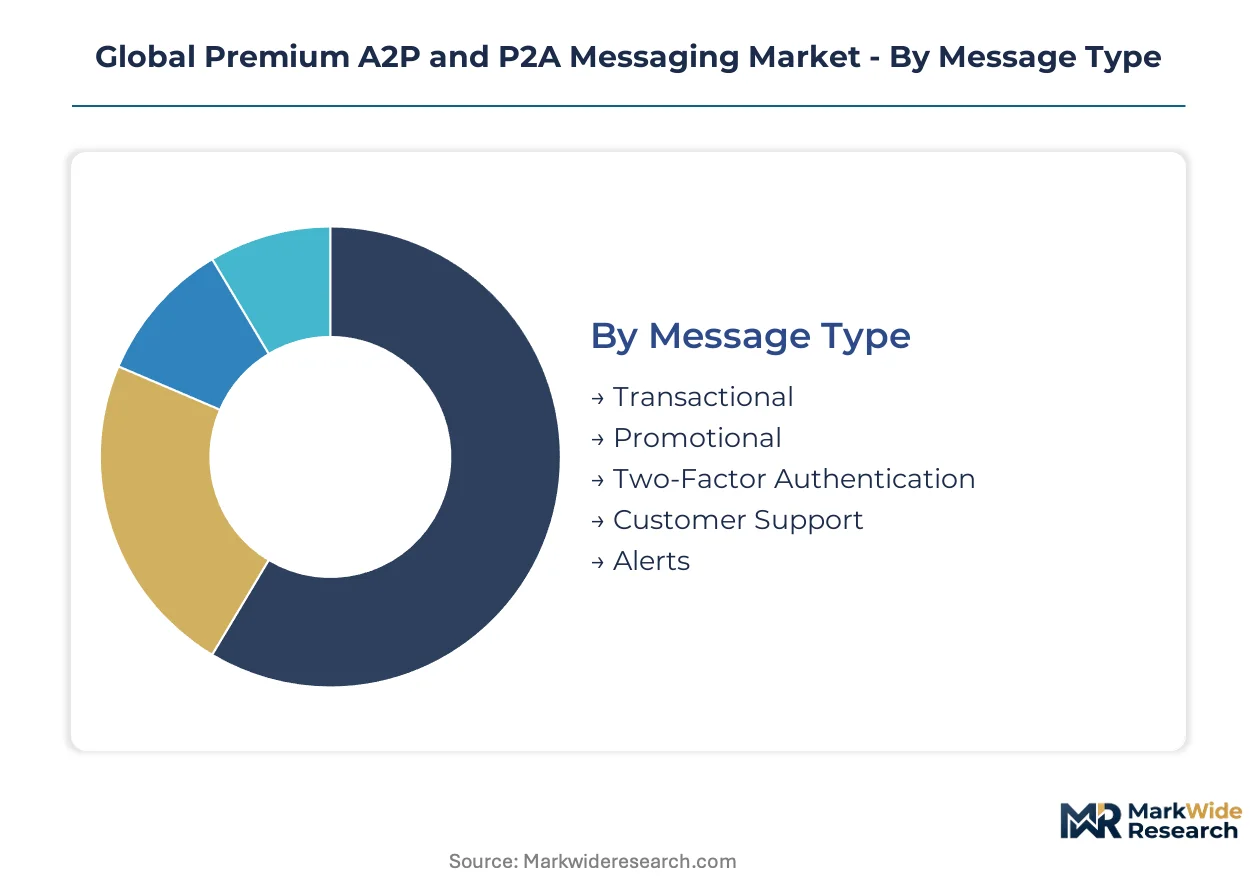
Segmentation in the Premium A2P and P2A Messaging Market reveals how carrier infrastructure investments, regulatory frameworks, and enterprise IT modernization priorities reshape procurement patterns across message types and deployment architectures.
Message Type:
Domestic demand concentrates on compliance-heavy transactional flows in banking hubs like Frankfurt and Mumbai, while promotional segments face cross-border friction under GDPR and emerging AI Act documentation requirements.
- Transactional:Payment confirmations, delivery notifications, and account updates route through carrier-grade SLAs with guaranteed delivery timestamps. Indian digital wallet providers and German retail banks drive volume concentration as real-time receipt expectations harden into standard customer experience benchmarks.
- Two-Factor Authentication:One-time password delivery commands the highest per-message pricing tier due to latency sensitivity and fraud liability exposure. Southeast Asian e-commerce platforms and Nigerian fintech deployments represent the steepest volume expansion as mobile-first authentication displaces hardware token alternatives.
- Promotional:Marketing broadcasts face escalating consent documentation burdens under EU frameworks and TRAI scrubbing mandates in India.
- Customer Support:Conversational threads integrate LLM-powered escalation pathways for Brazilian and Mexican retail deployments.
- Alerts:Critical notifications for utilities and healthcare systems prioritize SMS fallback reliability over rich media rendering.
Transactional commands the established base. The steepest expansion runs through Two-Factor Authentication.
Technology:
Cost tier separation widens between legacy SMS aggregators competing on volume and RCS platform providers capturing premium authentication-verified contracts from European financial services buyers.
- RCS:Rich Communication Services enables verified sender branding, interactive carousels, and read receipts within native messaging clients. German and Dutch banking applications migrate fraud alerts and payment confirmations to these channels, compressing legacy SMS aggregator margins while elevating carrier revenue participation.
- SMS:Short Message Service retains dominance as universal fallback transport with 160-character payload constraints and store-and-forward reliability. Emerging market corridors in Indonesia and Egypt depend on SMS for feature phone penetration and intermittent connectivity environments.
- USSD:Unstructured Supplementary Service Data serves balance inquiry and menu-driven interactions for pre-smartphone device bases in rural India and sub-Saharan Africa.
- Email-to-SMS:Protocol translation gateways enable legacy enterprise systems to inject messages without API modernization.
- OTT Messaging:WhatsApp Business and similar platforms capture conversational commerce flows for Brazilian retail and UAE hospitality sectors.
SMS retains volume leadership across price-sensitive segments. RCS gains share fastest among authentication-verified deployments.
End User:
Application maturity varies sharply: banks demand sub-second latency with full audit trails, while government agencies prioritize cost efficiency over rich media capabilities.
- Banks:Tier-1 institutions in Singapore, Switzerland, and the United States mandate carrier-direct connections with STIR/SHAKEN-compliant origin verification. Fraud alert latency requirements below three seconds drive premium pricing acceptance for verified channel access.
- E-Commerce Platforms:Indian and Indonesian marketplace operators orchestrate omnichannel notification layers spanning RCS, WhatsApp, and app push to reduce cart abandonment. Real-time delivery tracking and one-tap support escalation convert messaging pipes into retention surfaces.
- Telecommunications Providers:Carrier self-use for billing and service notifications generates internal demand for infrastructure optimization.
- Government Agencies:Public health and emergency alert systems in Turkey and South Africa prioritize broadcast reach over interactivity.
- Travel Operators:Airlines and hospitality groups in Thailand and Spain deploy boarding pass delivery and concierge chatbot integration.
Banks anchor the premium tier. E-Commerce Platforms climb the fastest as conversational commerce adoption accelerates.
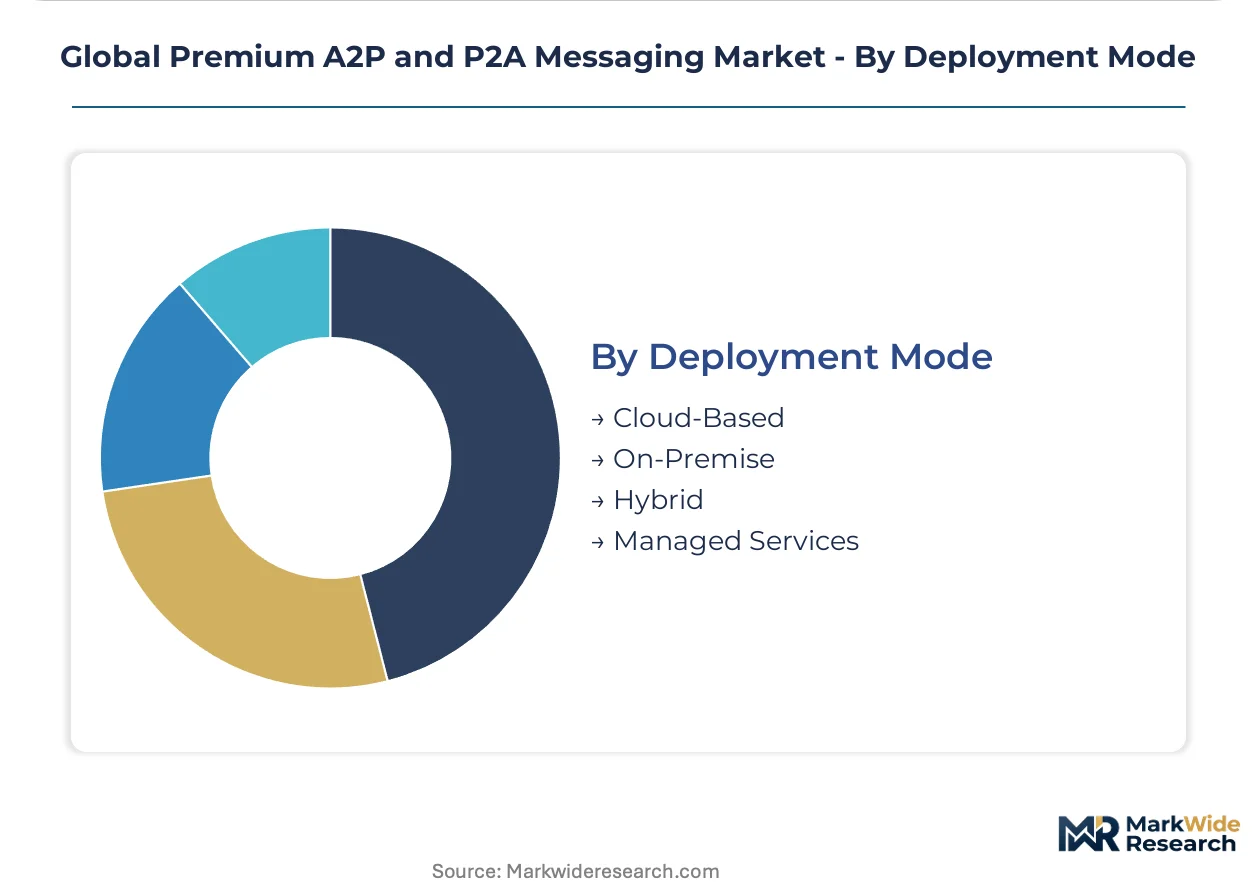
Deployment Mode:
Customer procurement patterns split between mid-market enterprises seeking elastic cloud capacity for campaign spikes and regulated institutions requiring data residency controls.
- Cloud-Based:API-first platforms with auto-scaling infrastructure capture Series C e-commerce and logistics operators in India and Brazil. Unified analytics across RCS, OTT, and push channels displaces point-solution SMS aggregators.
- On-Premise:Dedicated hardware installations persist among Saudi and Swiss banking regulators with strict data localization mandates. Core system integration complexity and legacy protocol translation requirements extend deployment timelines.
- Hybrid:Split architectures route sensitive authentication through private infrastructure while offloading promotional bursts to public cloud.
- Managed Services:Outsourced operations with embedded compliance tooling address GDPR and EU AI Act documentation burdens for French and Spanish financial services deployments.
On-Premise retains regulated institution loyalty. Cloud-Based expands most quickly as mid-market procurement consolidates around orchestration layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement in banking and e-commerce concentrates messaging infrastructure investment in five countries spanning regulatory sophistication and digital payment expansion. Each market exhibits distinct carrier dynamics and compliance frameworks that reshape aggregator competitive positioning.
United States
North American fintech platforms and retail banks drive demand for STIR/SHAKEN-compliant origin verification. The FCC mandates caller ID authentication extensions into messaging channels, tightening access requirements for unregistered traffic. Silicon Valley and New York City clusters anchor developer-centric platform adoption among Series C e-commerce operators.
Germany
Tier-1 financial institutions in Frankfurt mandate carrier-direct connections with sub-three-second latency guarantees for fraud alerts. GDPR and the EU AI Act impose granular consent documentation and automated decision-making disclosure requirements. The Rhine-Main banking cluster migrates payment confirmations to RCS verified channels at accelerated pace.
India
Digital wallet providers and marketplace operators in Mumbai and Bengaluru generate massive A2P volume through real-time payment confirmation workflows. TRAI enforces strict sender ID registration and message scrubbing mandates that filter gray-route traffic. Tier-2 and tier-3 urban clusters benefit from PLI scheme incentives for edge messaging infrastructure deployment.
Brazil
Smartphone penetration exceeds 75 percent yet RCS carrier enablement remains below 40 percent, creating upgrade runway for verified messaging infrastructure. ANVISA and central bank regulations shape authentication requirements for financial services deployments. São Paulo retail operators orchestrate conversational commerce threads integrating payment APIs and LLM-powered support escalation.
United Kingdom
London-based fintechs and e-commerce platforms consolidate procurement around API-first orchestration layers unifying RCS, WhatsApp Business, and native app push. GDPR consent withdrawal mechanisms and documentation retention requirements elevate compliance tooling demand. The Southeast England technology corridor anchors mid-market enterprise adoption of cloud-based deployment architectures.
Global Premium A2P and P2A Messaging Market Competitive Landscape
Player mix skews toward cloud-native platform providers and carrier-integrated aggregators with divergent geographic anchoring. Market structure exhibits tiered concentration: a handful of scaled platforms capture premium enterprise contracts while regional aggregators compete on price-sensitive volume routes. Two strategic archetypes dominate—developer-centric API-first platforms and carrier-direct infrastructure operators. Competitive moves center on M&A for compliance tooling capabilities and strategic partnerships for RCS interoperability certification.
Within the cloud-native platform tier, Twilio Inc. and Infobip exemplify divergent geographic positioning strategies. Twilio Inc. anchors North American fintech adoption through developer-centric platform architecture. Infobip occupies a position emphasizing emerging market density across Southeast Asia and Latin America. Among carrier-integrated operators, Sinch represents the European archetype through direct Deutsche Telekom AG and Vodafone Limited infrastructure relationships. Each company sits within a distinct competitive vector shaped by regional regulatory frameworks and enterprise procurement consolidation patterns.
| Leading Market Players |
|---|
| Twilio Inc. |
| AT&T |
| Sinch |
| Deutsche Telekom AG |
| Vodafone Limited |
| Infobip |
| CLX Communications |
| Dialogue Communications Ltd. |
| Beepsend |
| Others |
Supply & Pricing Matrix
RCS carrier infrastructure substitution for legacy SMS aggregators simultaneously concentrates supply geography among Deutsche Telekom AG and Vodafone Limited direct partnerships while compressing per-message economics for unverified channel operators.
Pricing Analysis
Cost-plus contracts with carrier termination fee indexation dominate enterprise procurement for international routes. Price differentiation hinges on STIR/SHAKEN certification tier and guaranteed delivery SLA thresholds. Cost compression in promotional messaging intensifies as TRAI scrubbing mandates in India and GDPR consent documentation requirements elevate operational overhead. Mid-market e-commerce platforms exhibit acute price sensitivity, while tier-1 Frankfurt banks accept premium pricing for sub-three-second latency guarantees.
Supply Chain Analysis
Germany and India anchor carrier-grade infrastructure deployment, with Frankfurt hosting tier-1 financial institution direct connections and Mumbai supporting massive digital wallet volume flows. Raw material dependencies center on licensed spectrum allocations, interconnection agreements, and cloud compute capacity at edge nodes. Single-source vulnerability concentrates around Apple and Google RCS client distribution control. Distribution runs through API-first platform aggregators displacing point-solution SMS providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium A2P messaging sits in early-cycle expansion as RCS carrier enablement crosses critical mass thresholds in European banking corridors and Indian digital payment ecosystems.
For Market Incumbents: Consolidate around compliance-automation capabilities before EU AI Act audit trail mandates harden into procurement requirements. Acquire GDPR documentation tooling specialists to defend margin position against cloud-native platform erosion. Deepen carrier-direct relationships in underpenetrated Brazil and Mexico corridors where RCS enablement lags smartphone penetration. For New Entrants and Emerging Players: Anchor in conversational commerce integration layers that unify payment APIs, identity verification, and LLM-powered support within single messaging threads. Target LATAM retail operators in São Paulo and Mexico City where verified messaging infrastructure upgrade demand outstrips carrier deployment timelines. Lead with WhatsApp Business API orchestration as a bridge solution during RCS interoperability gaps. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional SMS aggregators facing margin compression from RCS migration and regulatory compliance cost escalation. Five-to-ten year viability favors platforms with embedded AI Act documentation capabilities and emerging market density. Watch TRAI enforcement intensity in India as volume legitimacy inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| RCS Interoperability Certification | Apple-Google standard convergence unlocks verified channel access for European banking deployments. |
| Compliance Tooling Acquisition | GDPR consent audit automation addresses operational overhead crushing promotional message margins. |
| Carrier-Direct Partnership Expansion | Deutsche Telekom and Vodafone relationships secure latency-guaranteed fraud alert routing. |
| Conversational Commerce Platform Integration | Payment API embedding converts notification pipes into transaction completion surfaces for Indian e-commerce. |
| Edge Infrastructure Deployment | PLI scheme incentives reduce hardware costs for tier-2 and tier-3 urban cluster messaging nodes. |
Research Methodology
Cross-validation between primary interviews with carrier network engineers, enterprise IT procurement officers, regulatory compliance leads, and platform product managers anchors the qualitative findings. Secondary sources include TRAI enforcement circulars, FCC STIR/SHAKEN implementation orders, EMA GDPR guidance documents, and carrier interconnection tariff filings. Bottom-up volume modeling triangulates against top-down enterprise messaging spend surveys.
Sensitivity analysis around carrier termination fee volatility and RCS adoption pace shapes the projection framework across message type, technology, and deployment mode segmentation dimensions. CAGRs derive from elasticity-adjusted volume trajectories and pricing tier migration assumptions. Industry-specific inputs include digital wallet transaction growth curves and EU AI Act implementation timelines.
Material uncertainties — regulatory enforcement intensity divergence, currency instability in emerging market routes, and Apple-Google interoperability standard negotiations — sit outside the modeled envelope. Forecasts reflect documented assumptions about carrier infrastructure investment continuity and enterprise procurement consolidation patterns. Recalibration cycles align with material shifts in TRAI mandate enforcement and RCS carrier enablement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Belgium Telecom Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
5G Technology Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Oman Telecommunication Market
Telecommunications
China ICT Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Mobile Voice Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Australia Telecom Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Voip Phone Market