
 Mobile Value-Added Services (MVAS) Market | 2026-2036
Mobile Value-Added Services (MVAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Value-Added Services (MVAS) Market Analysis
GDPR is recalibrating the cost-of-entry calculus for MVAS providers operating across European data corridors. Vodafone Group Plc anchors its competitive position through deep carrier infrastructure integration across multiple continents. Google LLC leverages its advertising technology stack to dominate mobile advertising segments with programmatic precision. Comviva Technologies specializes in subscriber lifecycle management platforms that sustain recurring revenue relationships with tier-one operators.
Mobile Value-Added Services encompass revenue-generating telecommunication offerings beyond standard voice and data connectivity, typically delivered through SMS gateways, USSD protocols, mobile application frameworks, and carrier-grade billing integration. These services monetize subscriber engagement through transactional, subscription, and advertising models while enabling enterprises to reach consumers via device-native channels. SMS-based authentication and mobile banking services retain structural dominance in emerging markets where smartphone penetration remains uneven, while mobile advertising captures expanding margin pools through programmatic targeting and rich media formats. Enterprise end users represent the fastest-growing demand segment as corporations deploy mobile workforce solutions and customer engagement platforms at scale.
The EU AI Act and GDPR impose algorithmic transparency requirements on automated content recommendation engines, directly affecting mobile advertising personalization and mobile gaming loot-box mechanics. India's TRAI mandates strict unsolicited commercial communication regulations that shape SMS marketing compliance costs and operational frameworks for broadcast services. Stakeholders must monitor evolving data localization mandates and spectrum allocation policies as these regulatory instruments determine market access economics and infrastructure investment priorities across jurisdictions.
Market Dynamics
Enterprise adoption of mobile banking and payment platforms is accelerating across emerging economies, compressing service delivery timelines and forcing infrastructure investments into carrier-grade billing systems that can handle transaction volumes at scale.
Growth Catalysts
- India's PLI scheme:The production-linked incentive framework for telecom equipment manufacturing is reducing hardware procurement costs for MVAS providers deploying SMS gateways and USSD infrastructure across South Asian markets.
- Sub-Saharan mobile money ecosystems:Kenya's M-Pesa model and similar platforms in Nigeria and Ghana are displacing traditional banking infrastructure, creating first-mover advantages for carriers integrating financial services into subscriber lifecycle management.
- Rich media advertising formats:Programmatic targeting technologies are expanding margin pools in mobile advertising segments as advertisers shift budget from static display to interactive video and augmented reality placements.
Market Restraints
- GDPR compliance architecture:The European Union's data protection framework imposes algorithmic transparency requirements that recalibrate cost-of-entry calculus for MVAS providers operating across European data corridors.
- Spectrum allocation bottlenecks:National regulatory delays in releasing sub-6 GHz bands constrain carrier capacity expansion in high-density urban markets where MVAS traffic concentrates.
- Feature phone persistence:Uneven smartphone penetration in rural India and parts of Southeast Asia limits addressable market for application-based services, locking providers into legacy SMS and USSD protocols with thinner margins.
Strategic Opportunities
- EU AI Act alignment:Early compliance with algorithmic transparency mandates creates competitive moats for mobile advertising platforms targeting European enterprise clients.
- Enterprise workforce solutions:Mobile customer engagement platforms and field force automation tools represent underpenetrated white space as corporations digitize operations in Brazil and Mexico.
- 5G network slicing:Convergence of carrier infrastructure virtualization and edge computing enables guaranteed quality-of-service tiers for latency-sensitive mobile gaming and live streaming applications.
Industry Challenges
- TRAI compliance complexity:India's unsolicited commercial communication regulations impose granular consent management requirements that increase operational overhead for SMS marketing broadcast services.
- Legacy billing integration:MVAS platforms must maintain interoperability with decades-old carrier charging systems while modernizing to real-time digital wallet settlements, creating technical debt and talent scarcity in mainframe-to-cloud migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Value-Added Services (MVAS) Market |
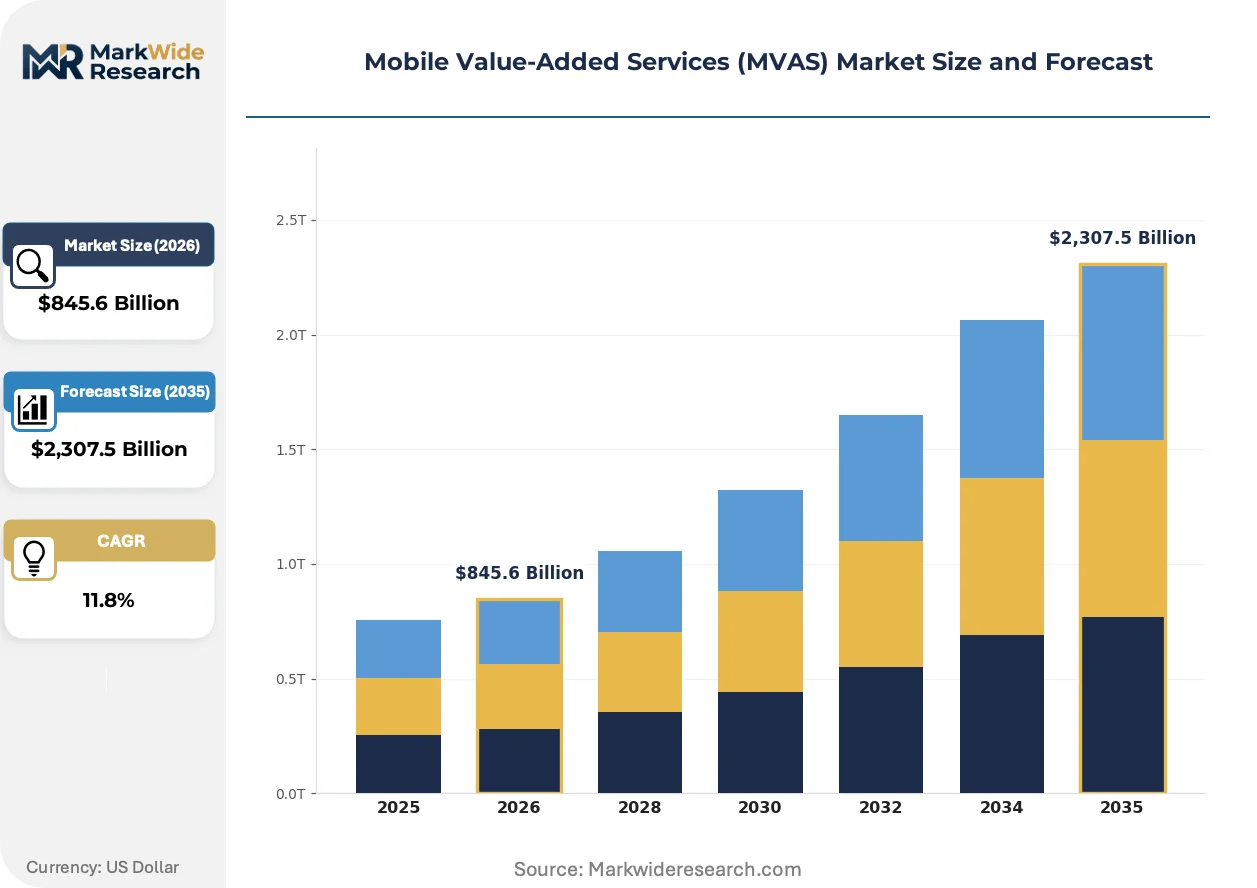
| Market Size in 2026 | $845.6 Billion |
| Market Size in 2035 | $2,307.5 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: SMS, Mobile Banking, Mobile Gaming, Mobile Advertising End User: Enterprises, Consumers, Government, Educational Institutions Delivery Mode: Online, Offline, Subscription-Based, Pay-Per-Use Content Type: Text, Video, Audio, Rich Media |
| Companies Covered | Comviva Technologies, OnMobile Global, Vodafone Group Plc, AT&T Inc., Apple Inc., Google LLC, Huawei Technologies Co. Ltd., Samsung Electronics Co. Ltd., InMobi Pte. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Value-Added Services (MVAS) Market Emerging Trajectories
Artificial intelligence and edge computing architectures are compressing the latency window for real-time service delivery, while regulatory frameworks on both sides of the Atlantic impose new transparency obligations on automated systems.
Rich media messaging protocols built on RCS standards are electrifying customer engagement channels by enabling branded interactive experiences within native messaging applications. Retail banks and e-commerce platforms in Southeast Asia are deploying these capabilities at scale to reduce app download friction. The technology is compressing conversion funnels and displacing standalone mobile applications for transactional services.
The EU AI Act imposes mandatory documentation requirements on automated content recommendation engines used in mobile advertising personalization. Industrial consequence includes forced disclosure of training data provenance and decision logic for algorithmic targeting systems. Mobile gaming operators deploying loot-box mechanics face immediate compliance pressure, with several platforms already restructuring reward distribution algorithms to meet transparency thresholds.
Buyer concentration among enterprise clients is shifting procurement leverage toward outcome-based engagement metrics rather than volume-based messaging commitments. Telecommunications carriers serving Fortune 500 accounts are unbundling platform fees from per-message rates, replacing them with performance guarantees tied to customer acquisition costs. This pattern is most visible in North American and Western European markets where enterprise marketing budgets have centralized under procurement functions with advanced analytics capabilities.
Mobile Value-Added Services (MVAS) Market Segmentation
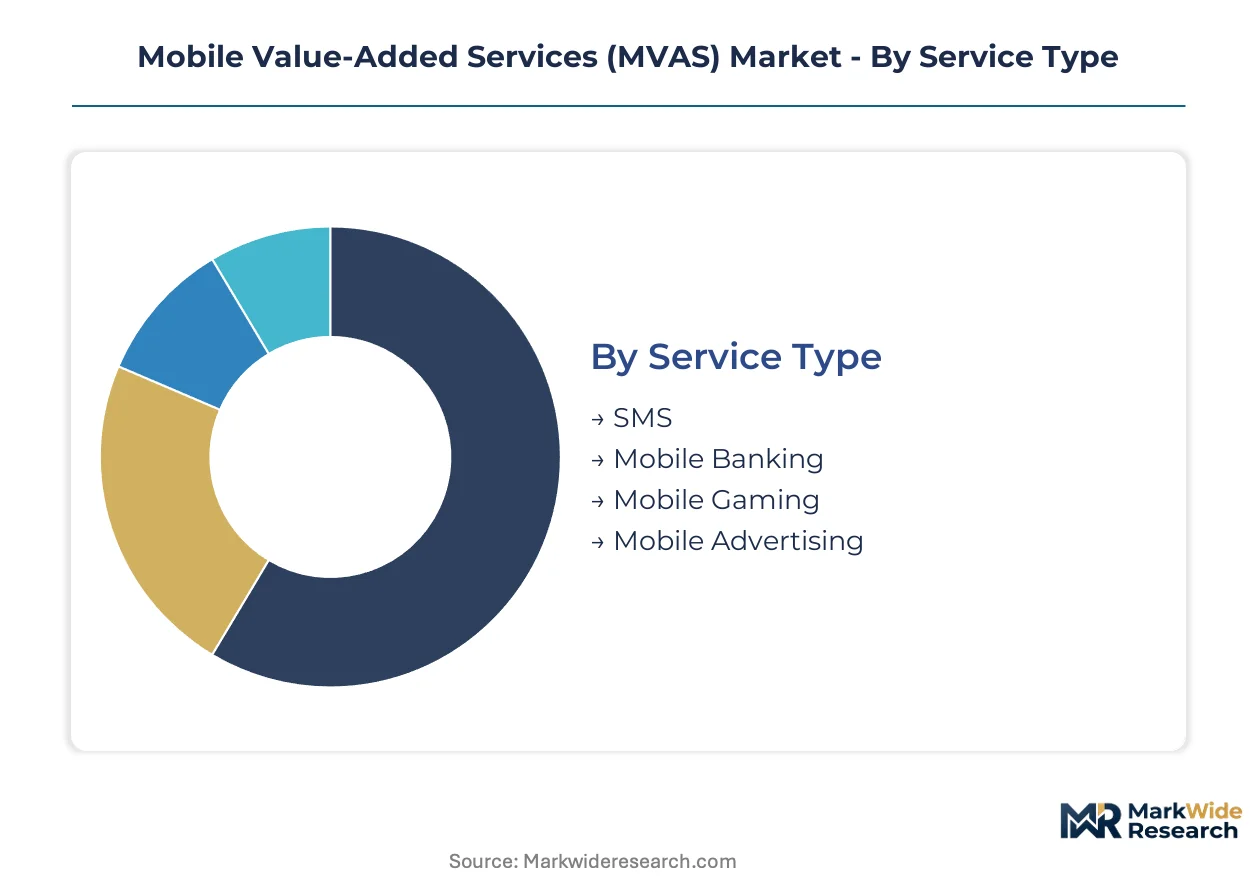
MVAS segmentation reveals divergent margin structures across delivery modes and content formats. Enterprise procurement patterns differ sharply from consumer engagement models, forcing providers to architect separate platform stacks for each buyer category.
Service Type:
Buyer investment thresholds vary most dramatically across this dimension, with carrier-grade infrastructure requirements separating high-barrier from low-barrier entry segments.
- SMS:Legacy protocol infrastructure delivers authentication, alerts, and marketing broadcasts through carrier SS7 networks and gateway aggregators. Demand concentrates in India's financial services sector where TRAI-mandated consent frameworks and feature phone persistence sustain volume despite thinner margins.
- Mobile Banking:Carrier-integrated financial platforms combine USSD menus, SIM toolkit applications, and encrypted SMS for balance inquiries, transfers, and merchant payments. Sub-Saharan Africa anchors volume as Kenya's M-Pesa model and Nigeria's banking agents displace branch infrastructure.
- Mobile Gaming:Freemium monetization through in-app purchases and rewarded video advertising leverages device GPU capabilities and low-latency connectivity.
- Mobile Advertising:Programmatic buying platforms and rich media formats target users via carrier data segments and application inventory.
Volume sits with SMS; growth tilts toward mobile banking.
End User:
Contract structures and procurement sophistication divide this category sharply between centralized enterprise purchasing and fragmented individual transactions.
- Enterprises:Workforce automation platforms, customer engagement tools, and mobile payment acceptance systems require SLA-backed carrier integration. Brazil and Mexico drive expansion as corporations digitize field operations and supply chain interactions.
- Consumers:Individual subscribers purchase entertainment, financial, and informational services through carrier billing or digital wallets.
- Government:Citizen service delivery, emergency alerting, and mobile identity verification demand sovereign data handling and certified security architectures.
- Educational Institutions:Learning management system access, examination result distribution, and fee payment platforms serve distributed student populations.
Procurement concentration favors enterprises; activation velocity favors consumers.
Delivery Mode:
Revenue recognition timing and customer acquisition economics split this category between recurring subscription relationships and transactional event billing.
- Online:Real-time service delivery through mobile applications and browser-based interfaces enables instant provisioning and usage-based metering.
- Offline:Store-and-forward messaging, downloadable content packages, and SIM-based services function without continuous connectivity.
- Subscription-Based:Recurring revenue models bundle content libraries, financial service tiers, or gaming privileges into monthly carrier-billed commitments.
- Pay-Per-Use:Event-driven transactions for single content downloads, authentication requests, or advertising impressions minimize entry cost.
Retention economics favor subscription; penetration depth favors pay-per-use.
Content Type:
Bandwidth requirements and production cost structures create distinct margin profiles across this dimension, with compression efficiency determining addressable device base.
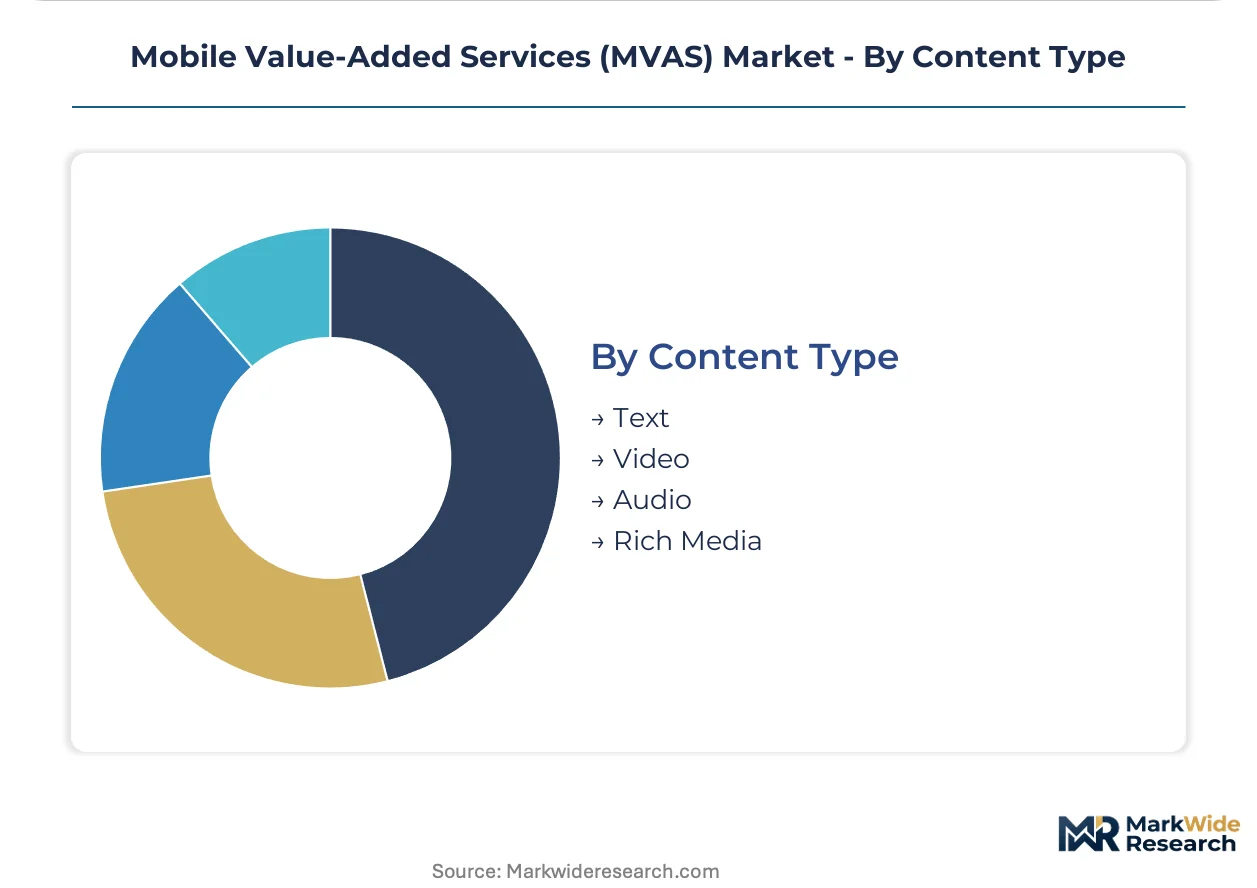
- Text:Low-bandwidth messaging, alerts, and USSD menus function across 2G networks and legacy feature phones with minimal delivery cost.
- Video:Streaming entertainment, advertising placements, and live gaming content consume carrier data allocations and require CDN edge distribution.
- Audio:Music streaming, voice-based services, and podcast distribution balance engagement duration against compression efficiency.
- Rich Media:RCS-based interactive messaging combines branded imagery, carousels, and action buttons within native messaging applications.
Reach extends through text; engagement depth extends through rich media.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's telecom production-linked incentive zones concentrate MVAS infrastructure investment through hardware cost reductions and carrier-grade deployment acceleration.
India
TRAI-mandated consent frameworks and feature phone persistence sustain SMS authentication volumes for financial services. The PLI scheme for telecom equipment manufacturing reduces gateway hardware procurement costs for providers deploying across South Asian markets. Mumbai and Bangalore anchor carrier infrastructure integration hubs where tier-one operators consolidate billing system modernization.
Kenya
M-Pesa's mobile money ecosystem displaces traditional branch banking while creating template replication across East African markets. The central bank's tiered licensing framework for digital financial services shapes compliance architectures for carrier-integrated platforms. Nairobi concentrates fintech-carrier partnerships where subscriber lifecycle management platforms embed payment rails directly into USSD menus.
Germany
GDPR algorithmic transparency requirements recalibrate cost structures for mobile advertising personalization engines operating across European data corridors. The EU AI Act imposes mandatory documentation thresholds on automated content recommendation systems. Berlin hosts compliance architecture specialists serving carriers and advertising platforms navigating dual regulatory frameworks.
Brazil
Enterprise workforce digitization and field force automation tools drive mobile customer engagement platform procurement. ANVISA and central bank regulations govern mobile health service delivery and payment system integration respectively. São Paulo anchors Latin American MVAS provider headquarters where carriers unbundle platform fees from per-message rates for Fortune 500 accounts.
United States
Programmatic advertising budget shifts toward interactive video and augmented reality formats expand margin pools in rich media segments. FCC spectrum allocation timelines and state-level privacy patchworks fragment regulatory compliance requirements. Seattle and San Francisco Bay Area clusters concentrate advertising technology stacks and edge computing infrastructure for latency-sensitive service delivery.
Mobile Value-Added Services (MVAS) Market Vendor Landscape
European carrier groups anchor one tier; Asian infrastructure specialists hold equipment integration capabilities. The vendor base stratifies between consolidated telecommunications operators with captive MVAS platforms and fragmented independent software providers serving multiple carriers. Three archetypes dominate: vertically integrated carriers, subscriber lifecycle management specialists, and advertising technology platforms. Competitive moves concentrate on carrier billing system modernization partnerships and rich media messaging protocol adoption.
Within the carrier-integrated tier, Vodafone Group Plc and AT&T Inc. occupy positions exemplifying infrastructure depth across multiple continents. Comviva Technologies sits within the subscriber lifecycle management specialist archetype, sustaining recurring revenue relationships with tier-one operators. Google LLC anchors the advertising technology platform category, leveraging programmatic precision to capture mobile advertising segments.
| Leading Market Players |
|---|
| Comviva Technologies |
| OnMobile Global |
| Vodafone Group Plc |
| AT&T Inc. |
| Apple Inc. |
| Google LLC |
| Huawei Technologies Co. Ltd. |
| Samsung Electronics Co. Ltd. |
| InMobi Pte. Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive carrier billing integration anchors both supply positioning and pricing power for MVAS providers, with tier-one operators leveraging in-house SS7 gateway infrastructure to command premium rates for guaranteed delivery tiers while independent aggregators compete on spot-market messaging volumes.
Pricing Analysis
Short lead-time provisioning commands 15-25% premiums over standard deployment cycles in carrier-grade billing integration projects. The dominant structure runs on three-tier pricing across premium SLA-backed, standard committed-volume, and economy spot-message tiers. Price differentiation rests on certification grade (ISO 27001 for financial services) and geographic delivery cost (sub-Saharan Africa versus Western Europe). Cost compression in the economy tier is intensifying because India's PLI scheme has flooded South Asian markets with low-cost gateway hardware. Enterprise procurement functions show lowest price sensitivity due to outcome-based contracting, while SMS marketing agencies in fragmented Asian markets exhibit highest sensitivity.
Supply Chain Analysis
India's domestic-content mandates under the PLI scheme are reshaping sourcing patterns for telecom equipment manufacturing. Hardware supply concentrates in India, China, and South Korea for SMS gateways and USSD infrastructure components. Raw material dependencies center on semiconductor chipsets for billing systems, rare earth elements for antenna arrays, and specialized polymers for device casings. Single-source vulnerability runs through advanced node semiconductor fabrication concentrated in Taiwan. Distribution runs through carrier-direct procurement for tier-one operators and specialized systems integrators serving mid-market providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier-grade billing infrastructure capacity constraints prop pricing power for integrated operators, as legacy mainframe-to-cloud migration timelines stretch 18-36 months and talent scarcity in SS7 protocol engineering limits rapid expansion.
For Market Incumbents: Cement defensive positioning through backward integration into edge computing infrastructure and exclusive 5G network slicing partnerships with national carriers. The threat of Google's advertising technology stack capturing enterprise mobile marketing budgets demands immediate response through certification investment in GDPR and EU AI Act compliance architectures. For New Entrants and Emerging Players: Rich media messaging protocols built on RCS standards offer the most penetrable wedge into enterprise customer engagement segments. White-space targets include field force automation tools for Brazilian and Mexican corporations and subscriber lifecycle management platforms for tier-two African carriers. A channel-first go-to-market angle through systems integrators already embedded in carrier procurement cycles accelerates traction. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by telecommunications operators seeking captive billing capabilities. Long-term viability favors providers with demonstrated carrier integration depth and recurring revenue concentration above 70%. The signal to watch is TRAI enforcement intensity on unsolicited commercial communication violations, which could trigger consolidation among non-compliant SMS aggregators.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Billing System Modernization | SS7-to-IP migration enables real-time digital wallet settlements and reduces technical debt. |
| RCS Protocol Adoption | Rich media messaging displaces standalone applications for Southeast Asian retail banks. |
| GDPR Compliance Architecture Investment | Algorithmic transparency certification opens European enterprise procurement channels. |
| Edge Computing Infrastructure Partnership | 5G network slicing guarantees quality-of-service for latency-sensitive gaming applications. |
| Sub-Saharan Mobile Money Platform Integration | USSD menu embedding captures subscriber lifecycle management in Kenya and Nigeria. |
Methodological Framework
Multi-period observation of carrier capex cycles, SMS gateway deployment rates, and mobile money transaction volumes anchored the trend analysis, supplemented by interviews with MVAS platform executives, carrier procurement directors, telecom equipment manufacturing specialists, and regulatory compliance officers. Secondary validation drew from TRAI enforcement disclosures, EU AI Act implementation guidance, GSMA industry statistics, and carrier financial filings. Bottom-up service-type modeling and top-down regional macroeconomic triangulation cross-checked volume and value estimates.
Input-output matrices mapped segmentation dimensions including service type, end-user category, delivery mode, and content format across the projection horizon. CAGRs derived from trend extrapolation of historical deployment patterns and elasticity-adjusted demand curves. Industry-specific forecast inputs incorporated spectrum allocation timelines and mobile money penetration curves in priority markets.
Several conditions sit outside the modeled scope, including sovereign data localization mandates not yet enacted, carrier merger outcomes pending regulatory approval, and quantum-resistant encryption standards still in draft. Forecasts reflect documented assumptions about technology substitution rates and regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G System Integration Market
Telecommunications
5G in Defense Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Myanmar Telecom Market
Telecommunications
Thailand Telecom Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
Global Telecommunication Market
Telecommunications
Romania Telecom Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Norway Telecom Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
A2P Messaging Market
Telecommunications
Esim Subscription Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Global 4G LTE Market
Telecommunications
Super High Frequency Communication Market