
 US Voice-Over LTE (Volte) Market | 2026-2036
US Voice-Over LTE (Volte) Market Size, Share, and Industry Trends Forecast 2026-2036
US Voice-Over LTE (Volte) Market Insights
3GPP Release 15 certification is rotating the competitive field by requiring IMS core compliance for VoLTE interoperability, raising barriers for smaller operators. Verizon Communications Inc. anchors its position through deep fiber backhaul integration that sustains low-latency voice delivery nationwide. T-Mobile US Inc differentiates via aggressive 5G SA core deployment that positions VoNR as a natural migration path from VoLTE. AT&T Corporation leverages its FirstNet contract to dominate public-safety-grade voice services with hardened QoS parameters.
Voice-Over LTE transmits packetized voice traffic over dedicated bearers within LTE radio networks using the IMS architecture, with AMR-WB codecs enabling 50 Hz to 7 kHz audio bandwidth for HD Voice quality. Its primary commercial purpose is replacing circuit-switched fallback with all-IP voice that reduces spectrum overhead and enables simultaneous voice-data sessions. HD Voice deployment among tier-one carriers has matured, while VoWiFi adoption accelerates in enterprise segments where indoor cellular coverage gaps persist. Cloud-based IMS deployments represent the fastest-growing structural category as managed service models shift operational burden from carrier capex to opex budgets.
FCC rules on robocall mitigation via STIR/SHAKEN authentication and NIST cybersecurity frameworks shape VoLTE gateway requirements and intercarrier signaling standards. The Federal Communications Commission also enforces rural voice service quality metrics that pressure United States Cellular Corp and regional operators to upgrade legacy TDM interconnects. Stakeholders must monitor spectrum reallocation proceedings and 3GPP Release 18 timelines to time VoLTE-to-VoNR transition investments without stranding IMS infrastructure commitments.
Market Dynamics
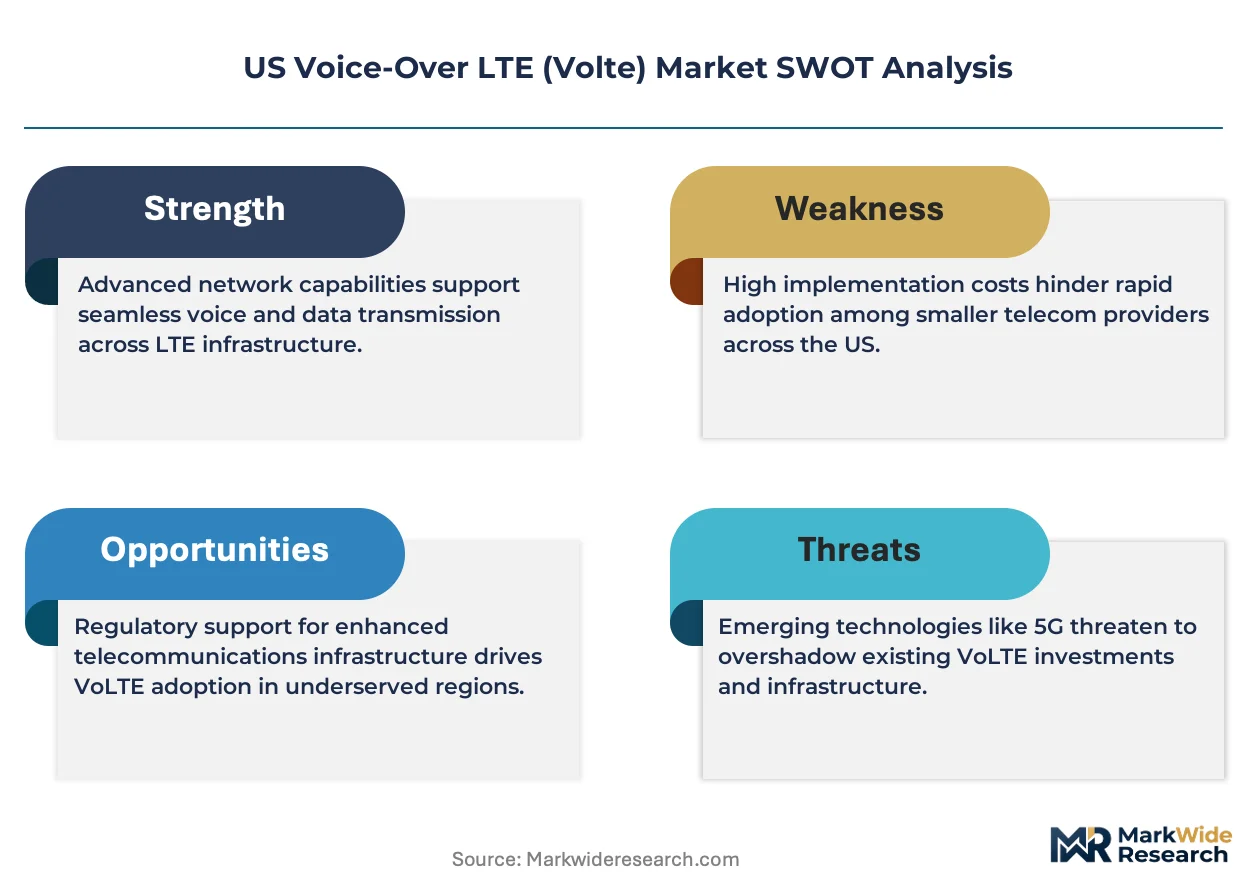
Carrier decommissioning of 3G circuit-switched cores is forcing accelerated VoLTE migrations as spectrum reallocation deadlines compress modernization timelines. FCC mandates for next-generation 911 and rural broadband deployment under BEAD are redirecting capex toward IP-native infrastructure.
Growth Catalysts
- FCC Next-Gen 911 Mandates:Federal requirements for location-accurate emergency calling are compelling carriers to deploy IMS-based voice cores that support geolocation tagging. Public safety agencies drive procurement specifications.
- Enterprise UCaaS Migration:Cloud-based unified communications platforms require VoLTE-enabled mobile endpoints for seamless fixed-mobile convergence. Large employers in healthcare and logistics are standardizing on HD Voice handsets.
- Spectrum Refarming Pressure:AWS-3 and C-band auction winners must clear legacy 3G channels for 5G NR deployment. VoLTE becomes the sole voice bearer as CDMA and GSM networks sunset.
Market Restraints
- IMS Core Capital Intensity:Virtualized IP Multimedia Subsystem deployments require substantial upfront investment in session border controllers and diameter routing agents. Regional carriers face financing constraints.
- Interoperability Certification Bottlenecks:3GPP Release 15 compliance testing delays device approvals. Handset OEMs struggle with carrier-specific IMS profile validation.
- VoNR Substitution Timeline:Standalone 5G voice services threaten to strand VoLTE infrastructure commitments before depreciation cycles complete. T-Mobile's 5G SA core accelerates this risk.
Strategic Opportunities
- VoWiFi Enterprise Penetration:Indoor cellular dead zones in manufacturing facilities and hospitals drive demand for Wi-Fi-calling integration. Managed service providers bundle VoWiFi with private 5G networks.
- Rural BEAD Program Funding:The Broadband Equity, Access, and Deployment program allocates capital for voice-capable fiber-to-the-home builds. Tier-3 carriers in Montana and Alaska qualify for construction subsidies.
- Cloud-Native IMS Outsourcing:Network-as-a-service models shift operational burden to Ericsson and Nokia managed platforms. Capex-constrained operators convert fixed costs to usage-based opex.
Industry Challenges
- Legacy TDM Interconnect Sunsetting:Regional operators must replace time-division multiplexing trunks with SIP-based peering while maintaining service continuity. United States Cellular Corp faces compressed migration windows.
- STIR/SHAKEN Implementation Complexity:Robocall mitigation frameworks require certificate authority integration and real-time attestation verification. Smaller carriers lack in-house cybersecurity expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Voice-Over LTE (Volte) Market |
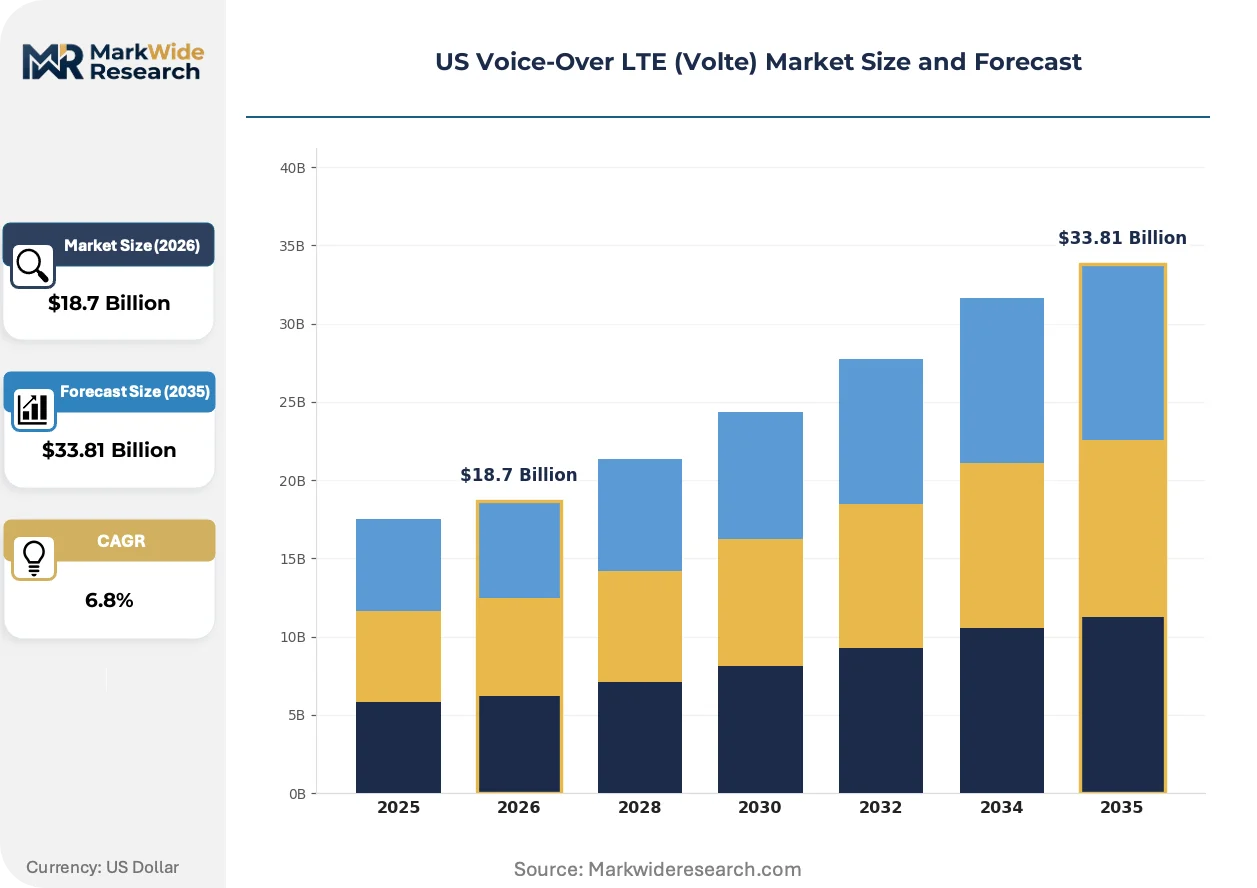
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: HD Voice, VoLTE, VoWiFi, IMS Deployment: On-Premises, Hybrid, Cloud, Managed Service End User: Telecom Providers, Enterprises, Consumers, Government Agencies Application: Mobile Communication, Video Calling, Conferencing, Messaging |
| Companies Covered | AT&T Corporation, Verizon Communications Inc., T-Mobile US Inc, United States Cellular Corp, Appalachian Wireless, Viaero Wireless, Inland Cellular, FTC Wireless, Evolve Cellular Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Voice-Over LTE (Volte) Market Trends and Innovations
VoLTE infrastructure decisions are increasingly subordinate to 5G standalone core roadmaps, compressing technology refresh cycles and reshaping vendor procurement criteria toward cloud-native architectures.
Cloud-native IMS cores are bifurcating deployment models between hyperscale-managed instances and carrier-retained virtualized stacks. Tier-one operators favor AWS Outposts and Azure private edge zones for rapid scaling. This architecture is bifurcating competitive positioning between asset-light challengers and vertically integrated incumbents.
FCC STIR/SHAKEN authentication mandates are hardening gateway security requirements for all originating voice providers. Intercarrier signaling now requires digital certificate validation at session initiation. Rural LECs in the Southeast are consolidating to share compliance infrastructure costs.
Enterprise mobility managers are consolidating device procurement around VoLTE-capable ruggedized handsets for field service workforces. Industrial distributors are displacing carrier-direct channels with vertical-specialized resellers. Oil and gas operations in the Permian Basin represent the most concentrated demand for this procurement shift.
US Voice-Over LTE (Volte) Market Segmentation
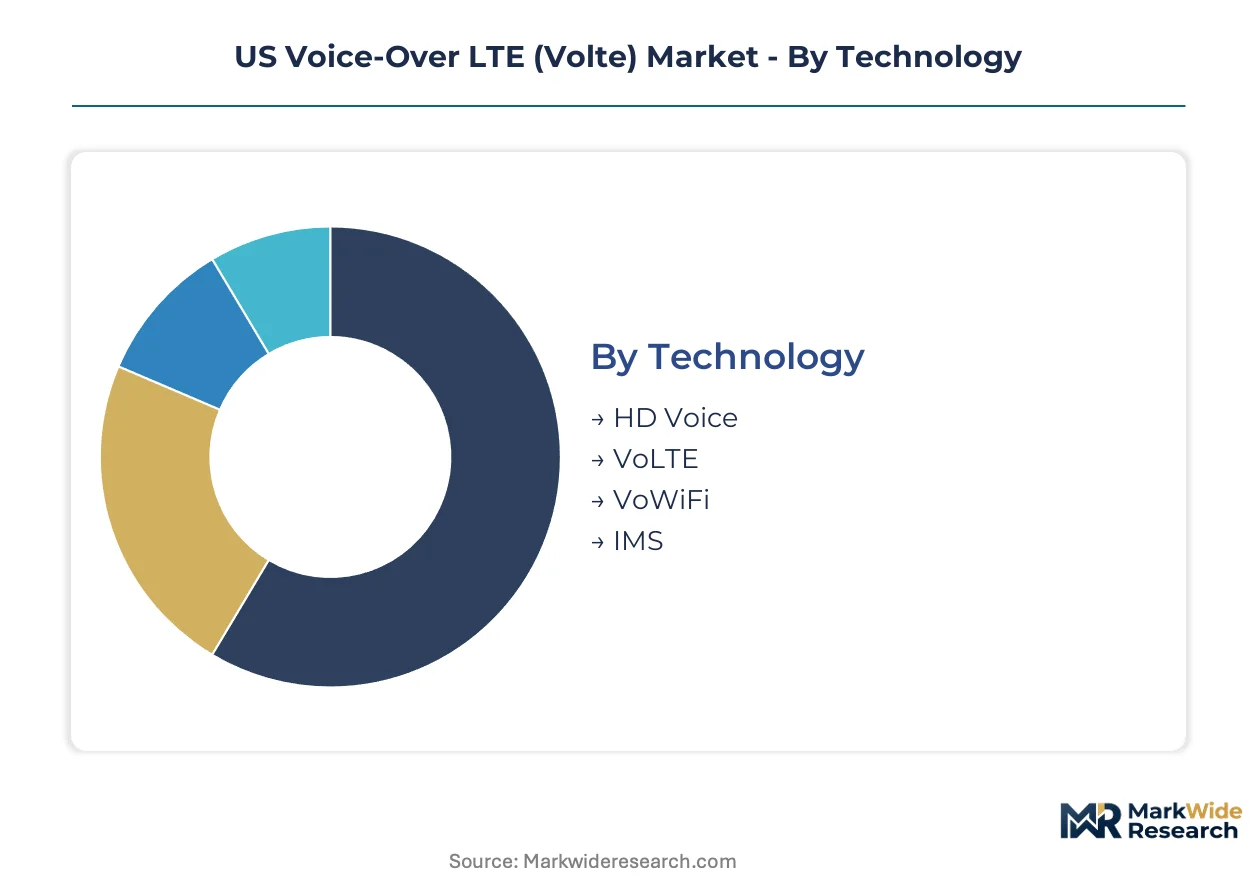
VoLTE market segmentation reveals how carrier infrastructure investments, enterprise procurement patterns, and regulatory mandates distribute demand across distinct technology and deployment categories. Understanding these splits clarifies where IMS core spending concentrates versus where cloud migration accelerates.
Technology:
Carrier-direct channels dominate HD Voice and VoLTE hardware procurement, while systems integrators handle IMS core deployments for regional operators lacking in-house engineering depth.
- HD Voice:AMR-WB codec implementation enables 50 Hz to 7 kHz audio bandwidth for public safety and healthcare communications. Texas and Southeast corridor carriers drive procurement as they modernize ahead of BEAD program deadlines.
- VoLTE:Packetized voice over dedicated LTE bearers replaces circuit-switched fallback, reducing spectrum overhead. Enterprise UCaaS platforms in logistics and healthcare standardize on VoLTE-enabled mobile endpoints for fixed-mobile convergence.
- VoWiFi:Wi-Fi calling integration addresses indoor coverage gaps in manufacturing facilities and hospitals. Managed service providers bundle VoWiFi with private 5G network deployments.
- IMS:IP Multimedia Subsystem cores provide session control and service authentication for all-IP voice architectures.
VoLTE dominates installed base. IMS represents where expansion concentrates as carriers virtualize core infrastructure.
Deployment:
Cost tier stratification separates capital-intensive on-premises builds from opex-optimized cloud and managed service models.
- On-Premises:Carrier-retained IMS infrastructure requires substantial upfront investment in session border controllers and diameter routing agents. Tier-one operators maintain on-premises stacks for hardened QoS control in public safety applications.
- Hybrid:Split architectures preserve sensitive authentication functions on-premises while offloading media processing to cloud instances. Regional carriers in spectrum-refarming windows favor hybrid models to balance control with speed-to-market.
- Cloud:Native IMS deployments on AWS Outposts and Azure private edge zones enable rapid scaling without data center expansion. Asset-light challengers leverage cloud to compete with vertically integrated incumbents.
- Managed Service:Ericsson and Nokia operate network-as-a-service platforms that shift operational burden from carrier capex to usage-based opex. Capex-constrained tier-3 operators in Montana and Alaska qualify for BEAD construction subsidies under this model.
On-premises deployments retain the largest installed footprint. Managed service is climbing the fastest as regional carriers seek financing alternatives.
End User:
Application-specific procurement patterns separate mass-market consumer devices from hardened enterprise and government-grade voice systems.
- Telecom Providers:Tier-one and regional carriers account for core infrastructure demand, with FCC next-generation 911 mandates and rural voice quality metrics driving IMS replacement cycles.
- Enterprises:Healthcare systems and logistics operators standardize on HD Voice handsets for field service workforces. Oil and gas operations in the Permian Basin represent concentrated demand for ruggedized VoLTE devices through vertical-specialized resellers.
- Consumers:Mass-market smartphone adoption of VoLTE capability follows carrier network modernization rather than leading it.
- Government Agencies:Public safety agencies drive procurement specifications for location-accurate emergency calling with geolocation tagging requirements.
Telecom providers dominate infrastructure spending. Government agencies anchor premium-tier demand for hardened QoS parameters.
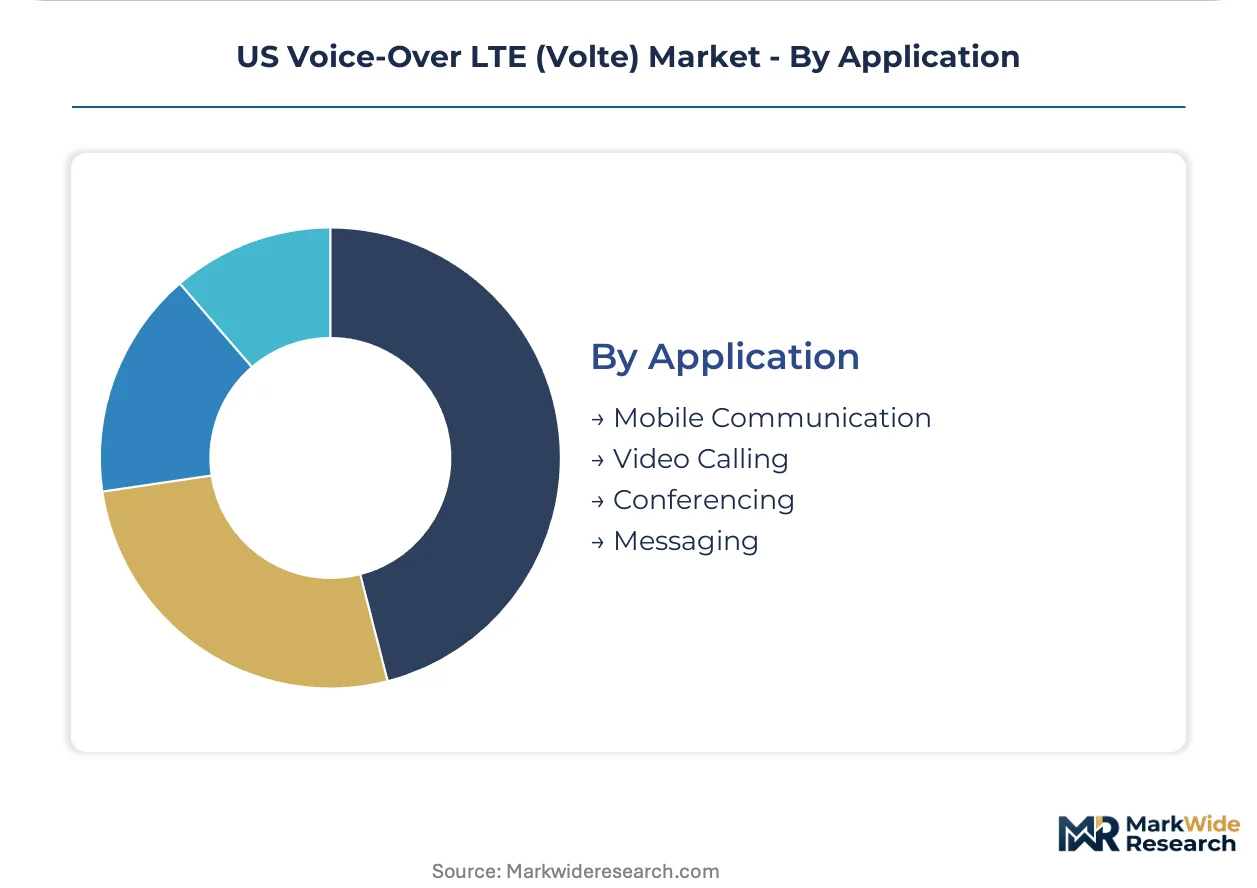
Application:
Maturity differentiation separates commoditized mobile voice from emerging video and conferencing integrations requiring synchronized media processing.
- Mobile Communication:Standard VoLTE voice services represent the baseline use case, with simultaneous voice-data sessions now table stakes for carrier competitiveness.
- Video Calling:Integrated video over LTE bearers requires enhanced session border controller capacity for media transcoding. Enterprise deployments in healthcare telemedicine drive specialized gateway requirements.
- Conferencing:Multi-party voice and video bridging demands scalable IMS application servers. Cloud-native architectures expand most quickly for this use case as distributed workforces persist.
- Messaging:Rich Communication Services over IMS enables enhanced messaging with read receipts and file transfer, though adoption lags behind OTT alternatives.
Mobile communication holds the deepest installed base. Conferencing is gaining share fastest as enterprise collaboration platforms integrate carrier-grade voice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier procurement concentrates in federal connectivity corridors where BEAD program deadlines intersect with legacy network sunset obligations. Texas and the Southeast corridor anchor infrastructure modernization demand. Mountain West and rural Midwest regions present concentrated upgrade windows for tier-3 operators.
Southeast Corridor
Regional carriers in Florida, Georgia, and the Carolinas accelerate IMS core replacements ahead of FCC rural voice quality enforcement. Appalachian Wireless exemplifies tier-3 consolidation pressure in this zone. Federal 911 geolocation mandates drive session border controller procurement in Atlanta and Charlotte metro clusters.
Texas
Oil and gas operations in the Permian Basin generate concentrated demand for ruggedized VoLTE handsets through vertical-specialized resellers. FTC Wireless and Viaero Wireless operate in adjacent rural markets requiring BEAD-funded fiber backhaul. Dallas-Fort Worth anchors hyperscale cloud IMS deployment for enterprise UCaaS integration.
Mountain West
Montana and Alaska tier-3 carriers qualify for BEAD construction subsidies under managed service models. Inland Cellular faces compressed migration windows for TDM interconnect replacement. FCC spectrum reallocation deadlines force accelerated 3G sunset timelines in sparse-coverage zones.
Midwest
United States Cellular Corp maintains significant regional presence across Illinois, Iowa, and Wisconsin with legacy infrastructure upgrade obligations. Manufacturing facilities in Michigan and Ohio drive VoWiFi adoption for indoor coverage gaps. Chicago anchors intercarrier peering infrastructure for SIP-based voice interconnect.
Pacific Northwest
Seattle and Portland metro areas concentrate cloud-native IMS development talent for vendor-managed platforms. Evolve Cellular Inc. operates in adjacent rural Washington markets. FCC cybersecurity frameworks for STIR/SHAKEN compliance drive gateway procurement specifications in this zone.
US Voice-Over LTE (Volte) Market Competitive Landscape
Player mix skews toward vertically integrated national carriers with substantial fiber backhaul assets and regional wireless operators dependent on managed service partnerships. The market structure consolidates around three national anchors with tier-2 and tier-3 carriers occupying fragmented rural footprints. Strategic archetypes include spectrum-heavy infrastructure owners, cloud-native challengers, and federally subsidized rural specialists. Dominant competitive moves center on 5G SA core migration timing and IMS outsourcing to managed network-as-a-service platforms.
Among the national carrier tier, AT&T Corporation, Verizon Communications Inc., and T-Mobile US Inc represent distinct strategic positioning archetypes. AT&T occupies a position anchored by public-safety-grade contract infrastructure with hardened QoS parameters. Verizon exemplifies deep fiber backhaul integration for latency-sensitive voice delivery. T-Mobile sits within the cloud-native challenger category with aggressive standalone 5G deployment that positions voice-over-NR as a migration pathway. United States Cellular Corp anchors the regional specialist tier with significant rural footprint exposure to BEAD program funding cycles.
| Leading Market Players |
|---|
| AT&T Corporation |
| Verizon Communications Inc. |
| T-Mobile US Inc |
| United States Cellular Corp |
| Appalachian Wireless |
| Viaero Wireless |
| Inland Cellular |
| FTC Wireless |
| Evolve Cellular Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term managed service contracts with usage-based indexation lock in supply access to Ericsson and Nokia cloud-native IMS platforms while fixing opex visibility for tier-3 carriers. This structure binds BEAD-funded rural operators to multi-year commitments that shelter infrastructure costs from spot volatility in session border controller procurement.
Pricing Analysis
Cost-plus contracts with equipment indexation dominate IMS core deployments, tying carrier payments to Cisco and Mavenir hardware benchmarks. Price differentiation rests on certification grade—3GPP Release 15 compliance commands premiums over legacy profiles—and volume scale from multi-carrier consortium purchasing. Cost compression in rural tier-3 segments is intensifying because BEAD subsidy deadlines compress negotiation windows. Enterprise healthcare buyers exhibit lowest price sensitivity due to hardened QoS requirements, while logistics fleet operators drive hardest bargain on ruggedized handset volumes.
Supply Chain Analysis
Finland and Sweden anchor virtualized IMS software development through Nokia and Ericsson headquarters engineering. Taiwan and South Korea produce baseband chipsets and radio units that feed into LTE bearer hardware. The chain draws from specialized semiconductor foundries and submarine fiber cable manufacturers. Single-source vulnerability concentrates in cloud hyperscaler edge zones where AWS Outposts and Azure private edge deployments lack geographic redundancy. Distribution runs through carrier-direct procurement for tier-one operators and vertical-specialized resellers for Permian Basin oilfield deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VoLTE infrastructure spending sits within early-cycle expansion as 3G sunset deadlines force accelerated IMS migrations before spectrum reallocation penalties activate. FCC next-generation 911 mandates provide regulatory tailwind embedding voice core replacement into compliance budgets.
For Market Incumbents: Shield core revenue streams by accelerating fiber backhaul densification in Southeast corridor metros where regional carriers face compressed TDM migration windows. Prioritize STIR/SHAKEN certificate authority integration to lock in intercarrier signaling relationships before smaller competitors consolidate compliance infrastructure. Vertical integration into session border controller manufacturing reduces exposure to Mavenir and Cisco supply bottlenecks. For New Entrants and Emerging Players: Differentiate on cloud-native IMS deployment velocity targeting tier-3 carriers in Montana and Alaska that qualify for BEAD construction subsidies but lack in-house engineering depth. White-space concentrates in managed service partnerships where Ericsson and Nokia platforms convert carrier capex to usage-based opex. VoWiFi enterprise bundling with private 5G networks offers the most penetrable go-to-market angle for manufacturing facility indoor coverage gaps. For Investors and Strategic Acquirers: Capital is best deployed toward regional wireless operators with BEAD-funded fiber backhaul commitments and legacy 3G spectrum holdings facing imminent reallocation. Long-term viability hinges on timing VoLTE-to-VoNR transition investments without stranding IMS infrastructure before depreciation cycles complete. Watch T-Mobile's 5G SA core expansion pace as the signal indicating VoNR substitution risk acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native IMS Migration | Shifts tier-3 carrier cost structure from capex to opex under BEAD program timelines. |
| STIR/SHAKEN Gateway Deployment | FCC mandates harden security requirements for all originating voice providers nationwide. |
| VoWiFi Enterprise Bundling | Addresses indoor coverage gaps in hospitals and manufacturing through managed service models. |
| 5G SA Core Transition | T-Mobile's deployment pace signals VoNR substitution risk for VoLTE infrastructure commitments. |
| Regional Carrier Consolidation | Appalachian Wireless exemplifies tier-3 pressure to share compliance and infrastructure costs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with network engineering executives at tier-one carriers, IMS platform product managers at Ericsson and Nokia, and FCC policy specialists; and secondary validation through carrier 10-K filings, BEAD program disbursement records, and 3GPP release documentation. Triangulation across bottom-up infrastructure spend estimates and top-down market sizing anchored volume and value outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions including deployment architecture, end-user category, and application maturity. CAGRs were derived from carrier capex disclosure patterns and spectrum reallocation deadline impacts. Forecast inputs incorporated FCC next-generation 911 mandate enforcement schedules and rural voice quality metric compliance windows.
The analysis sits within stated boundaries; outcomes outside sustained federal broadband subsidy flows or accelerated 3G sunset timelines would require recalibration. Forecasts reflect assumptions around 3GPP Release 18 standardization progress and intercarrier interoperability certification throughput. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Remote Radio Head Market
Telecommunications
Finland Telecom Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Global Esim Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Vietnam ICT Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Denmark Telecom Market
Telecommunications
5G Core Market
Telecommunications
Austria ICT Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
United Arab Emirates Telecom Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market