
 Explosion Proof Mobile Communication Devices Market | 2026-2036
Explosion Proof Mobile Communication Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Proof Mobile Communication Devices Market Intelligence
Market Context
East Asian electronics manufacturing is expanding its certified hazardous-area production lines to serve energy and chemical sectors. Aegex Technologies leverages specialized ATEX and IECEx certification protocols to anchor its position in North American oilfield services. Kyocera Corporation sustains component-level dominance through in-house semiconductor fabrication for thermally stable chipsets. i.safe MOBILE GmbH specializes in German-engineered intrinsically safe smartphones that compete on ergonomic design against bulkier industrial alternatives.
Technical Definition and Segment Structure
Explosion proof mobile communication devices are ruggedized electronic terminals engineered with encapsulated circuitry, flameproof enclosures, and restricted energy parameters to prevent ignition in explosive atmospheres containing flammable gases or combustible dusts. These instruments serve critical voice, data, and video transmission functions in Zone 1 and Zone 2 hazardous locations where standard consumer electronics pose catastrophic ignition risks. Rugged phones command the largest installed base among product types, while smart devices represent the fastest-expanding category as Android-based platforms displace legacy proprietary systems. Oil and gas end users generate the deepest margin pools due to stringent safety mandates and high device turnover in corrosive operating environments, though chemical processing accounts for the most rapid procurement growth as European refineries retrofit under CSRD-linked safety audits.
Regulatory Framework and Outlook
IECEx certification schemes, ATEX Directive 2014/34/EU, and China's GB 3836 standards collectively define the tripartite compliance architecture governing market access and product liability. OSHA Process Safety Management requirements in the United States mandate documented communication redundancy in refineries, directly stimulating replacement demand for certified LTE and satellite-enabled devices. Stakeholders must monitor evolving EU AI Act provisions for automated hazard detection integration, as regulatory convergence between functional safety and artificial intelligence disclosure obligations will reshape R&D allocation across device portfolios.
Market Dynamics
Refinery operators on the United States Gulf Coast are compressing replacement cycles for hazardous-area communication hardware, driven by OSHA Process Safety Management mandates for documented redundancy and the operational strain of LNG export terminal construction.
Growth Catalysts
- IECEx certification harmonization:Unified testing protocols reduce duplicate compliance costs for manufacturers serving multiple export markets, accelerating product launches across energy corridors.
- CSRD-linked safety audits:European refineries face mandatory disclosure of process safety infrastructure, forcing fleet upgrades to certified LTE and satellite-enabled devices before disclosure deadlines.
- Zone 2 smart device migration:Android-based platforms are displacing legacy proprietary systems in chemical processing plants, opening retrofit demand for intrinsically safe smartphones with modern application ecosystems.
Market Restraints
- Specialized semiconductor sourcing:Thermally stable chipsets require captive fabrication or long-lead foundry contracts, constraining production scaling for mid-tier device manufacturers.
- ATEX Directive compliance friction:Notified body bottlenecks in Germany and Italy extend certification timelines by 8-14 months, freezing working capital in pre-market inventory.
- Corrosion-resistant enclosure costs:Encapsulated circuitry and flameproof housings add 40-60% material cost premiums versus standard ruggedized electronics, compressing margin pools for price-sensitive chemical processors.
Strategic Opportunities
- China's GB 3836 alignment:Domestic certification convergence with IECEx standards enables foreign manufacturers to access Sinopec and PetroChina procurement tenders without redundant testing regimes.
- 5G private network integration:Convergence of hazardous-area hardware with localized millimeter-wave infrastructure creates first-mover advantage in refinery digital twin deployments.
- Indian chemical corridor expansion:Gujarat and Maharashtra state industrial zones lack certified device penetration, presenting whitespace for ATEX-certified suppliers establishing local distribution partnerships.
Industry Challenges
- Intrinsic safety engineering talent scarcity:Design of restricted energy parameters and encapsulation protocols requires specialized expertise concentrated in German and Japanese engineering consultancies.
- Legacy system integration complexity:Proprietary radio protocols in aging refinery communication networks resist seamless handoff to IP-based certified devices, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Proof Mobile Communication Devices Market |
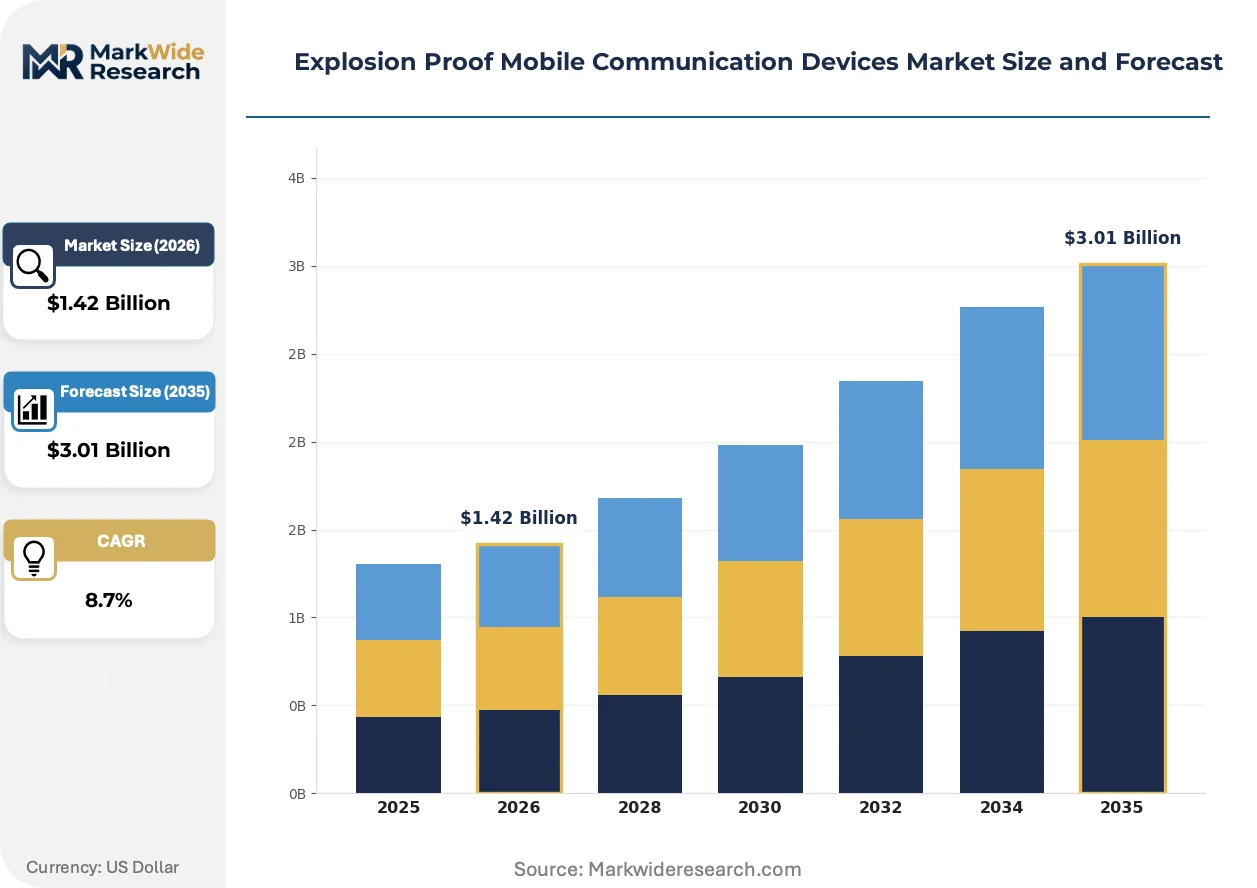
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rugged Phones, Two-Way Radios, Tablets, Smart Devices End User: Oil & Gas, Mining, Chemical Processing, Construction Technology: LTE, Wi-Fi, Bluetooth, Satellite Installation: Portable, Fixed, Vehicle-Mounted, Custom Solutions |
| Companies Covered | Aegex Technologies, LLC, Kyocera Corporation, i.safe MOBILE GmbH, Zebra Technologies Corporation, RugGear, BARTEC GmbH, Getac Technology Corporation, Panasonic Corporation, Sonim Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Proof Mobile Communication Devices Market Strategic Shifts & Innovations
Device architecture is pivoting from isolated hardware toward integrated safety systems, with regulatory pressure and operational digitization converging to redefine procurement criteria across hazardous-area industries.
Edge computing modules embedded directly in intrinsically safe smartphones are decentralizing hazard detection processing from centralized control rooms to field personnel. Oil and gas operators in the Permian Basin and North Sea are piloting these units for real-time gas concentration analysis. This architecture is decentralizing response latency from minutes to seconds, compressing the competitive advantage of legacy distributed control system vendors.
The EU AI Act's automated hazard detection disclosure obligations are forcing manufacturers to document algorithmic decision pathways in safety-critical firmware. Industrial consequence includes mandatory third-party auditing of machine-learning models embedded in smart devices. Zone 1 deployment applications face the steepest compliance burden, with German chemical processors demanding pre-certified AI transparency documentation before contract award.
Refinery procurement departments are unbundling after-sales service from hardware acquisition, selecting specialist third-party maintainers for certified device fleets. Channel disruption concentrates in the United States Gulf Coast, where independent service contractors displace manufacturer-direct support agreements. This pattern is most visible in Texas and Louisiana petrochemical complexes, where turnarounds demand rapid device exchange programs that original equipment manufacturers struggle to match.
Explosion Proof Mobile Communication Devices Market Segmentation
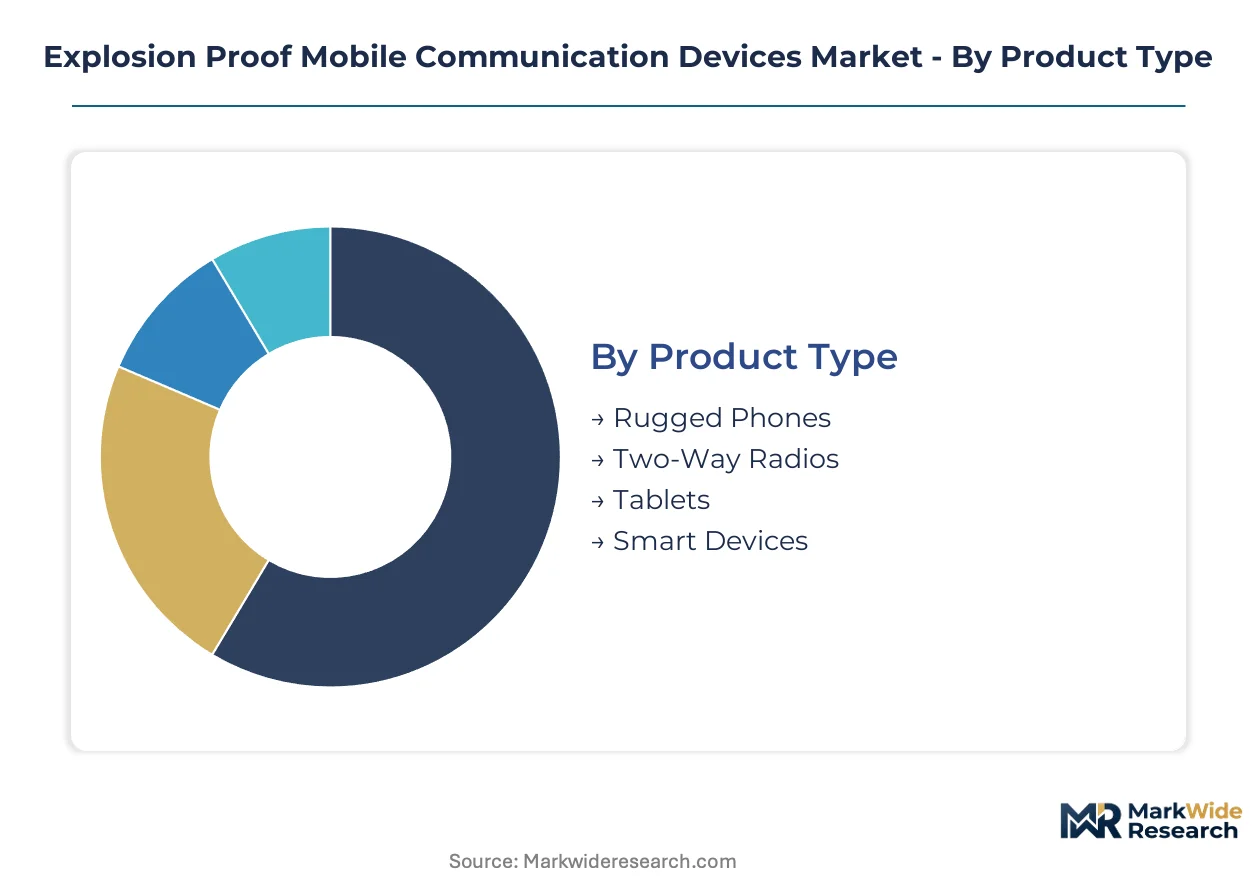
Segmentation in explosion proof mobile communication devices reveals how procurement priorities diverge across hazardous operating environments. Certification requirements, connectivity infrastructure, and workforce mobility patterns create distinct buying behaviors that reshape vendor positioning strategies.
Product Type:
Buyers differentiate primarily by field durability versus computational capability trade-offs.
- Rugged Phones:Encapsulated circuitry and flameproof housings deliver voice-centric communication for Zone 1 refinery walkdowns. United States Gulf Coast petrochemical operators compress replacement cycles here due to OSHA-mandated redundancy and corrosive atmospheric exposure.
- Smart Devices:Android-based platforms with modern application ecosystems displace legacy proprietary systems in chemical processing plants. European refineries retrofitting under CSRD-linked safety audits drive procurement for LTE-enabled units with edge computing modules.
- Two-Way Radios:Legacy proprietary radio protocols persist in aging refinery networks, forcing middleware development for IP migration.
- Tablets:Larger form factors suit maintenance documentation and digital twin visualization in LNG export terminal construction.
Rugged phones lead volumes today; smart devices are gaining share fastest.
End User:
Margin pools concentrate where safety mandates intersect with high device turnover rates.
- Oil & Gas:Stringent IECEx and ATEX certification requirements combine with corrosive operating environments to generate the deepest margin pools. Permian Basin and North Sea operators pilot edge-embedded smartphones for real-time gas concentration analysis.
- Chemical Processing:European refineries face mandatory CSRD disclosure deadlines, forcing fleet upgrades to certified LTE devices before audit cycles. German processors demand pre-certified AI transparency documentation for Zone 1 applications.
- Mining:Underground operations require satellite backup connectivity where terrestrial infrastructure fails.
- Construction:Project-based procurement favors rental and rapid exchange programs over capital acquisition.
Oil and gas dominates revenue concentration; chemical processing shows the steepest expansion trajectory.
Technology:
Connectivity selection hinges on infrastructure maturity and mission-critical redundancy requirements.
- LTE:Private network integration with localized millimeter-wave infrastructure creates first-mover advantage in refinery digital twin deployments. 5G convergence drives R&D allocation toward hazardous-area hardware with deterministic latency.
- Satellite:Essential backup for offshore platforms and remote pipeline segments where terrestrial coverage gaps persist. Indian chemical corridor expansion in Gujarat and Maharashtra presents whitespace for satellite-enabled device distribution.
- Wi-Fi:Confined to Zone 2 environments with controlled access point density.
- Bluetooth:Peripheral pairing for wearable sensors in personal gas monitoring systems.
LTE anchors current installed base; satellite connectivity climbs fastest in greenfield energy corridors.
Installation:
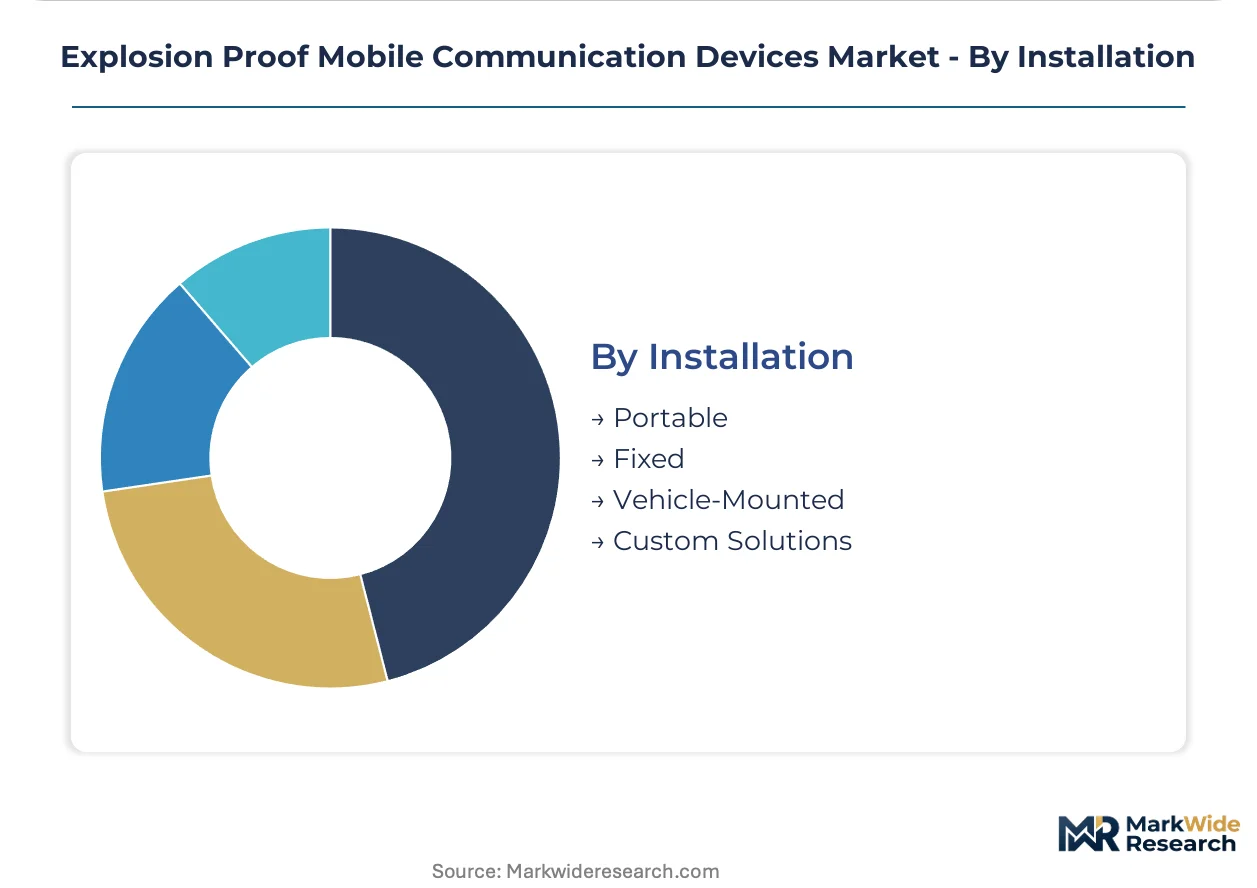
Deployment mode selection reflects workforce mobility patterns and control room centralization trends.
- Portable:Handheld units dominate field personnel communication in Zone 1 and Zone 2 hazardous locations. Texas and Louisiana petrochemical complexes drive independent service contractor penetration for rapid device exchange programs.
- Vehicle-Mounted:Integrated systems support mobile command coordination across sprawling LNG terminal construction sites.
- Fixed:Control room redundancy installations satisfy OSHA Process Safety Management documentation requirements.
- Custom Solutions:Proprietary radio protocol integration for aging refinery networks resists seamless handoff to IP-based standards.
Portable installation leads unit shipments; vehicle-mounted configurations expand most quickly in infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certification cost disparities are driving production migration toward jurisdictions with streamlined hazardous-area approval pathways. Manufacturers seek regulatory arbitrage between ATEX Directive complexity in Europe and faster IECEx harmonization in Asia-Pacific export hubs.
United States
OSHA Process Safety Management mandates compress replacement cycles for refinery communication hardware along the Gulf Coast petrochemical corridor. The Department of Labor enforces documented redundancy requirements that directly stimulate procurement of certified LTE and satellite-enabled devices. Texas and Louisiana complexes drive independent service contractor penetration for rapid device exchange programs during turnaround seasons.
Germany
Notified body bottlenecks extend ATEX certification timelines by 8-14 months, freezing working capital in pre-market inventory for device manufacturers. The EU AI Act imposes automated hazard detection disclosure obligations that force documentation of algorithmic decision pathways in safety-critical firmware. Chemical processors in the Rhine-Ruhr industrial zone demand pre-certified AI transparency documentation before contract award for Zone 1 applications.
China
GB 3836 standards alignment with IECEx protocols enables foreign manufacturers to access Sinopec and PetroChina procurement tenders without redundant testing regimes. The Ministry of Industry and Information Technology oversees domestic certification convergence that reduces market entry friction. Yangtze River Delta electronics manufacturing clusters are expanding certified hazardous-area production lines to serve domestic energy and chemical sectors.
India
Gujarat and Maharashtra state industrial zones present whitespace for ATEX-certified suppliers establishing local distribution partnerships in underpenetrated chemical corridors. The Bureau of Indian Standards regulates product safety compliance while state industrial development corporations offer land and tax incentives for hazardous-area equipment manufacturing. Mumbai-Pune chemical belt expansion drives satellite-enabled device demand where terrestrial infrastructure coverage gaps persist.
Saudi Arabia
Aramco procurement standards mandate IECEx certification for all hazardous-area communication equipment deployed in upstream and downstream operations. The Saudi Standards, Metrology and Quality Organization enforces technical regulations aligned with international explosion protection protocols. Eastern Province industrial cities including Jubail and Yanbu concentrate petrochemical complex construction that generates fleet-scale device procurement for greenfield LNG and refining projects.
Explosion Proof Mobile Communication Devices Market Key Industry Players
German engineering specialists anchor one tier; East Asian electronics fabricators hold scale-driven manufacturing positions. The vendor base stratifies across certification-heavy European boutiques and volume-oriented Asia-Pacific producers. Three archetypes dominate: ATEX/IECEx certification specialists, in-house semiconductor integrators, and ruggedized hardware platform licensors. Competitive moves concentrate on strategic partnerships for 5G private network integration and geographic expansion into underpenetrated chemical corridors.
Within the certification-specialist tier, i.safe MOBILE GmbH and BARTEC GmbH represent German-engineered intrinsically safe device expertise. Kyocera Corporation occupies a position among East Asian producers with captive component fabrication capabilities. Aegex Technologies, LLC exemplifies North American market focus through specialized ATEX and IECEx protocol alignment. These three anchors illustrate how regulatory proximity, semiconductor integration depth, and regional market anchoring define competitive positioning.
| Leading Market Players |
|---|
| Aegex Technologies, LLC |
| Kyocera Corporation |
| i.safe MOBILE GmbH |
| Zebra Technologies Corporation |
| RugGear |
| BARTEC GmbH |
| Getac Technology Corporation |
| Panasonic Corporation |
| Sonim Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned German engineering boutiques anchor the certification-intensive tier of this market, preserving pricing discipline through captive ATEX expertise while East Asian contract manufacturers compete on scale. Sovereign-backed Chinese electronics clusters now absorb component fabrication for mid-tier ruggedized devices, compressing margin pools for Western assemblers dependent on outsourced foundry capacity.
Pricing Analysis
Distributor margins for certified devices run 18-25% above standard industrial electronics, reflecting notified body documentation burdens and specialized inventory carrying costs. Three-tier pricing structure across IECEx Zone 0, Zone 1, and Zone 2 certification levels separates premium intrinsically safe smartphones from economy-grade two-way radios. Cost compression in the mid-tier is intensifying because Sinopec and PetroChina procurement tenders favor GB 3836-aligned suppliers with domestic assembly footprints. Chemical processors in Gujarat and Maharashtra exhibit highest price sensitivity due to project-based capital constraints, while Permian Basin oilfield operators absorb premiums for satellite-enabled redundancy.
Supply Chain Analysis
Thermally stable chipset fabrication rests on Japanese and Taiwanese specialty foundries with captive automotive-grade process nodes. Encapsulation resins and flameproof aluminum alloys draw from German and Chinese specialty materials producers, while final assembly concentrates in Yangtze River Delta electronics clusters and Rhine-Ruhr industrial zones. Single-source vulnerability persists in ATEX-certified battery cell supply, where only two notified body-approved suppliers serve the global installed base. Distribution runs through authorized hazardous-area equipment distributors with certified service technician networks, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as European CSRD disclosure obligations and OSHA redundancy mandates shift procurement toward premium-certified devices with documented AI transparency. Fleet replacement cycles compress where regulatory compliance intersects with operational digitization.
For Market Incumbents: Deepen backward integration into thermally stable semiconductor fabrication to escape foundry queue bottlenecks that freeze working capital. Fortify channel control through certified service technician networks in Texas and Louisiana, where independent contractors now displace manufacturer-direct support agreements during turnaround seasons. ATEX notified body capacity constraints in Germany and Italy present margin defense opportunity through pre-certified platform standardization. For New Entrants and Emerging Players: Launch via satellite-enabled device distribution partnerships targeting Gujarat and Maharashtra chemical corridors, where terrestrial infrastructure gaps and underpenetrated ATEX certification create whitespace. Prioritize Zone 2 Android migration demand in European refineries retrofitting under CSRD-linked safety audits, positioning against legacy proprietary radio protocols with modern application ecosystem compatibility. German-engineered ergonomic design against bulkier industrial alternatives offers differentiation anchor. For Investors and Strategic Acquirers: Industrial electronics conglomerates with hazardous-area equipment portfolios are the most active acquirers in this space, seeking ATEX/IECEx certification specialists to fill regulatory capability gaps. Five-to-ten-year viability hinges on 5G private network integration readiness and AI Act compliance documentation infrastructure. The signal to watch is Sinopec and PetroChina procurement tender participation rates by foreign manufacturers under converged GB 3836-IECEx standards.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Private Network Integration | Convergence with millimeter-wave infrastructure creates first-mover positioning in refinery digital twin deployments. |
| GB 3836 Certification Alignment | Domestic convergence with IECEx standards unlocks Sinopec and PetroChina procurement tender access without redundant testing. |
| Edge Computing Module Embedding | Decentralized hazard detection processing compresses response latency from minutes to seconds in Permian Basin operations. |
| Independent Service Contractor Partnerships | Rapid device exchange programs during turnaround seasons match Texas and Louisiana petrochemical complex procurement patterns. |
| AI Transparency Documentation Pre-Certification | German chemical processors demand pre-certified algorithmic decision pathway disclosure before Zone 1 contract awards. |
Research Approach
Bottom-up oil and gas operator modeling reconciled against top-down electronics manufacturing tracking forms the analytical core of this study. Primary interviews with refinery safety managers, ATEX notified body auditors, hazardous-area equipment procurement officers, and telecommunications infrastructure planners combined with secondary validation from IECEx certification databases, OSHA enforcement records, SEC 10-K filings by industrial electronics manufacturers, and customs trade data for explosion-protected apparatus. Triangulation across stakeholder inputs and documentary sources anchors volume and value estimates.
Historical certification timeline analysis and replacement cycle pattern recognition inform the projection framework across the analysis window. Segmentation dimensions modeled include product type (rugged phones, smart devices, two-way radios, tablets), end-use industry (oil and gas, chemical processing, mining, construction), connectivity technology (LTE, satellite, Wi-Fi, Bluetooth), and installation mode (portable, vehicle-mounted, fixed, custom). CAGRs derive from weighted average of bottom-up demand aggregation and top-down supply capacity assessment, with refinery capital expenditure cycles and LNG terminal construction pipelines as key industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body bottleneck extension or sudden GB 3836 standard revision. Projections reflect assumptions regarding IECEx-ATEX regulatory harmonization pace and 5G private network deployment timelines in hazardous areas. A small set of triggers—CSRD disclosure deadline acceleration, AI Act enforcement severity, and Chinese domestic certification preference shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
United Arab Emirates Telecom Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Video Door Phones Market
Telecommunications
Philippines Telecom Market
Telecommunications
Telecommunication Service Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Voip Phone Market
Telecommunications
Belgium Telecom Market
Telecommunications
China ICT Market
Telecommunications
Underwater Modems Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Rich Communication Services (RCS) Messaging Market