
 Indonesia Telecom Towers Market | 2026-2036
Indonesia Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Telecom Towers Market Insights
BIS certification for steel structural components is unwinding the competitive landscape for new entrants. PT Dayamitra Telekomunikasi Tbk (Mitratel) leverages its relationship with Telkom Group to anchor deployment across Java and Sumatra. PT Profesional Telekomunikasi Indonesia Tbk (Protelindo) sustains the largest independent tower portfolio through aggressive site acquisition. PT Tower Bersama Infrastructure Tbk differentiates via multi-tenant leasing ratios that maximize co-location revenue per structure.
Indonesia telecom towers are steel or reinforced-concrete structures engineered to support multiple antenna arrays, transmission equipment, and power systems at heights typically ranging from 30 to 120 meters, designed to withstand tropical cyclone wind loads and seismic activity across the Pacific Ring of Fire. Their primary purpose is to host radio access network infrastructure for mobile operators while enabling infrastructure sharing that reduces capital duplication. Lattice towers dominate rural and suburban deployments where land availability permits guyed or self-supporting configurations with lower steel cost per meter of elevation. Monopole designs lead urban applications where aesthetic restrictions and footprint constraints limit ground space, with stealth variants gaining traction near heritage sites and residential zones where visual impact triggers local opposition.
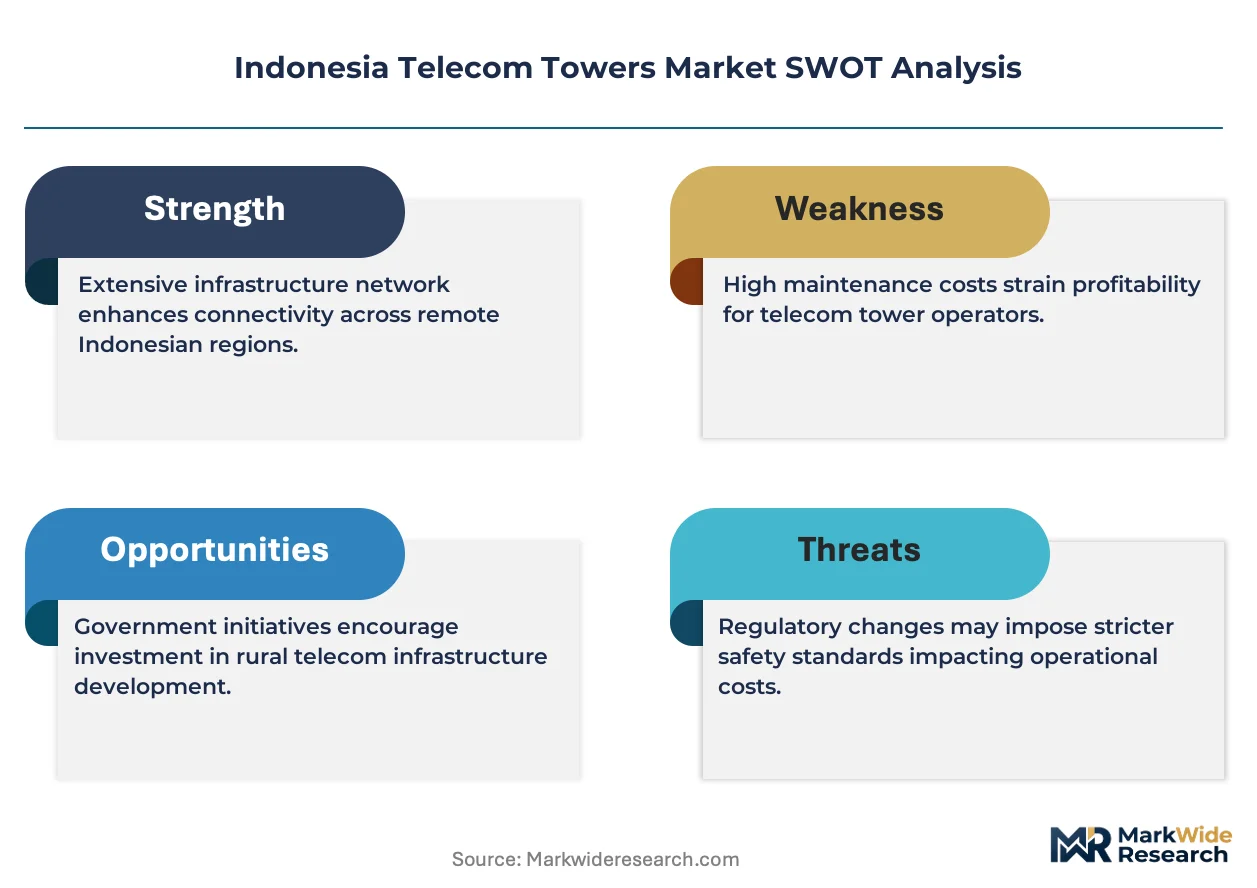
Kominfo infrastructure sharing regulations and BIS structural standards shape who qualifies for government-backed universal service obligation projects, while Ministry of Environment and Forestry permits govern tower placement in protected watersheds and conservation zones. The country's national pharmaceutical regulator has no direct role here, but overlapping jurisdiction between Kominfo, local governments, and military land authorities creates permitting complexity that favors established operators with dedicated regulatory affairs teams. Stakeholders must monitor how Kominfo's revised spectrum auction timelines and 5G rollout obligations reshape tenancy commitments across the tower base, particularly as operators evaluate build-versus-lease decisions for next-generation radio deployments.
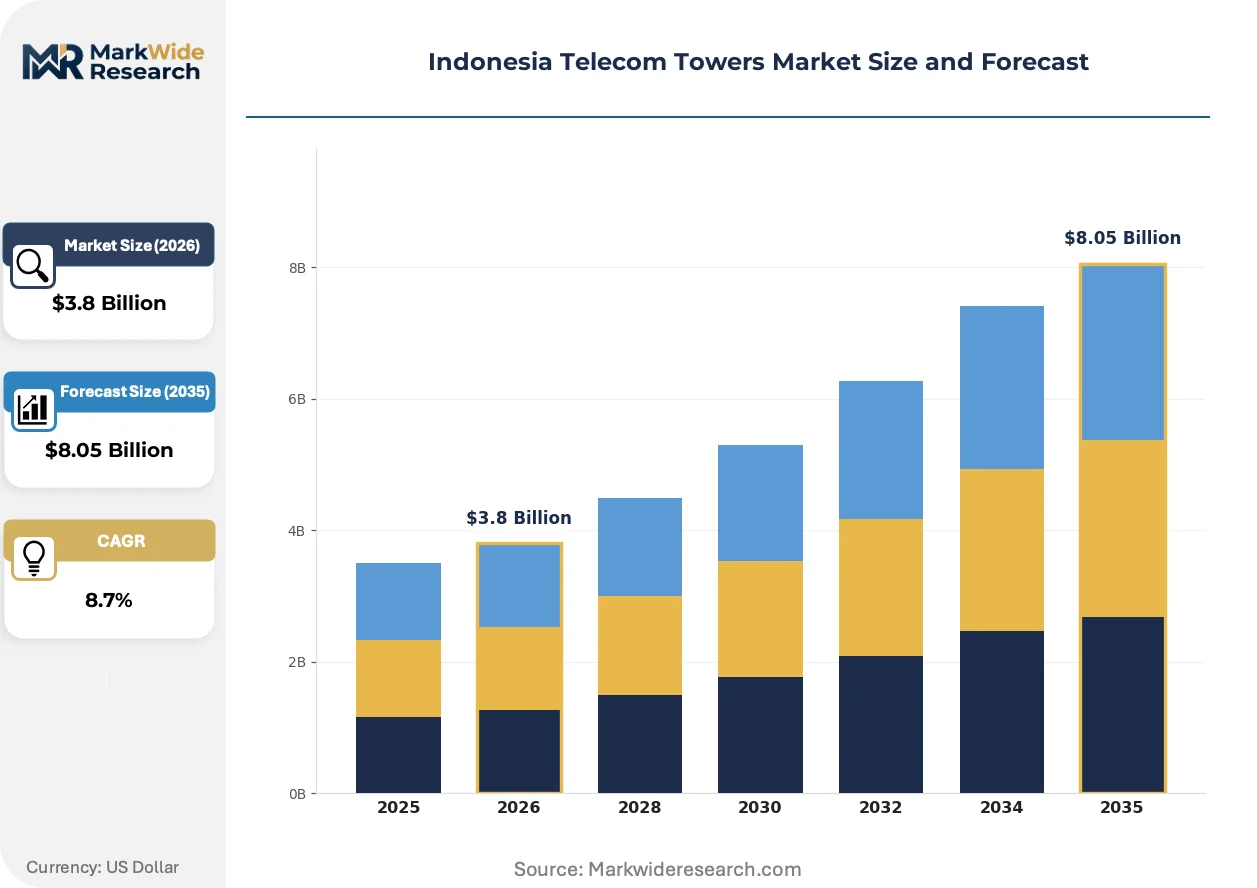
Market Dynamics
Kominfo's infrastructure sharing mandates are compressing the build-versus-lease calculus for mobile operators across the archipelago. Tower densification requirements for 4G and 5G coverage expansion are forcing operators to choose between captive infrastructure and third-party tenancy models.
Growth Catalysts
- Spectrum Auction Obligations:Kominfo's revised 5G rollout timelines mandate minimum coverage thresholds that accelerate tower deployment commitments across Java and Sumatra.
- Multi-Tenant Architecture:Co-location leasing models reduce per-operator capital expenditure while maximizing asset utilization for infrastructure providers.
- Java:Population density and commercial concentration in this island justify premium tower densification investments that attract institutional capital.
Market Restraints
- Steel Price Volatility:Lattice tower fabrication depends on hot-rolled steel coils subject to import duty fluctuations and global commodity cycles.
- Permitting Fragmentation:Overlapping jurisdiction between Kominfo, provincial governments, and military land authorities extends site acquisition timelines by 8-14 months.
- Monopole Cost Premium:Urban aesthetic restrictions force 40-60% higher steel costs per meter compared to guyed lattice configurations in rural zones.
Strategic Opportunities
- Eastern Indonesia:Sulawesi and Papua present underpenetrated coverage gaps where universal service obligation subsidies reduce deployment risk.
- Renewable Power Integration:Solar-hybrid power systems at off-grid tower sites cut diesel logistics costs and align with Ministry of Environment carbon reduction guidelines.
- Edge Computing Convergence:Tower real estate hosts micro data centers that reduce latency for industrial IoT applications in manufacturing zones.
Industry Challenges
- Structural Engineering Talent Scarcity:BIS certification requirements for tower design engineers outpace local university program output.
- Legacy 2G/3G Decommissioning:Tenancy contract renegotiations for upgraded radio equipment create revenue transition gaps during multi-year swap cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Telecom Towers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Monopole, Lattice Tower, Stealth Tower, Rooftop Tower Deployment: Urban, Suburban, Rural, Remote Service Type: 4G, 5G, Microwave, Fiber Optic End User: Telecom Operators, Government, Enterprises, Others |
| Companies Covered | PT Dayamitra Telekomunikasi Tbk (Mitratel), PT Profesional Telekomunikasi Indonesia Tbk (Protelindo), PT Tower Bersama Infrastructure Tbk, PT Centratama Menara Indonesia (EdgePoint), PT Bali Towerindo Sentra Tbk, PT Telkom Infrastruktur Indonesia, PT Indosat Ooredoo Hutchison Tower, PT XL Axiata Towers, PT Smartfren Telecom Infrastructure, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Telecom Towers Market Trends and Innovations
Passive infrastructure is evolving from steel-and-concrete commodity to intelligent platform hosting power, compute, and sensing layers. This transformation is compressing traditional equipment supplier margins while opening adjacent service revenue streams.
Stealth monopole designs with polymer cladding and faux architectural finishes are displacing conventional steel lattice structures in heritage-sensitive urban districts. Municipal governments in Yogyakarta and Surakarta mandate these variants within 500 meters of protected cultural sites. The aesthetic compliance premium is narrowing as local fabricators achieve scale.
Kominfo's revised infrastructure sharing regulations now require operators to disclose tower utilization rates and justify greenfield construction where co-location is technically feasible. This transparency mandate is accelerating tenancy migration toward independent tower companies with excess capacity. Enforcement mechanisms include spectrum license renewal conditions.
Mobile network operators are consolidating vendor relationships and demanding outcome-based tenancy agreements that bundle site acquisition, power uptime guarantees, and maintenance into per-tenant fees. This procurement compression favors tower operators with captive engineering capabilities and regional land-banking positions. The model is most advanced in Jakarta's satellite municipalities where tenancy density justifies dedicated operations centers.
Indonesia Telecom Towers Market Segmentation
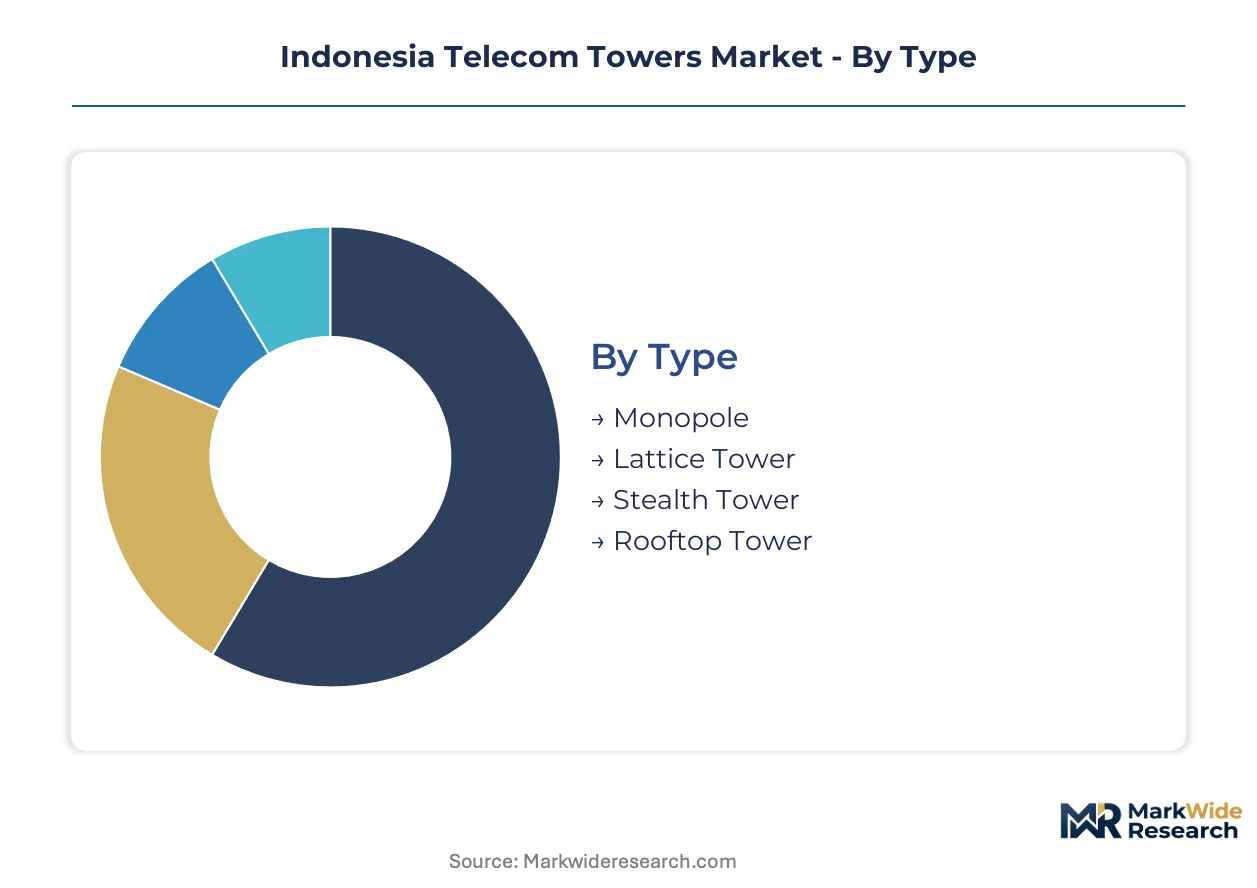
Segmentation reveals how Indonesia's archipelagic geography and regulatory environment fragment tower procurement patterns. Each dimension—structure type, deployment zone, service generation, and customer category—channels capital toward distinct engineering specifications and tenancy models.
Type:
Channel mix varies sharply by structure type, with lattice towers flowing through rural infrastructure contractors while monopoles and stealth variants route through urban specialty fabricators serving municipal permitting offices.
- Monopole:Single-stem steel structures with circular or polygonal cross-sections support antenna arrays up to 50 meters without guy wires. Demand clusters in Jakarta, Surabaya, and Bandung where local zoning boards restrict footprint and visual clutter. Aesthetic compliance premiums compress margins unless fabricators achieve batch production scale.
- Lattice Tower:Triangular or square-section steel truss configurations dominate rural Java and Sumatra where land availability permits larger base footprints. Guyed variants reduce steel tonnage per meter of elevation, lowering material costs for operators building coverage into palm oil plantation zones and trans-Sumatran highway corridors.
- Stealth Tower:Polymer-clad or architectural-facade structures mimic church steeples, flagpoles, or palm trees. Yogyakarta and Surakarta heritage districts mandate these within 500 meters of protected cultural sites.
- Rooftop Tower:Non-penetrating or anchored mast systems mount on commercial and residential buildings. Dense urban cores in Jakarta's Sudirman district favor these where ground leasing is prohibitively expensive.
By volume, lattice towers lead. By growth pace, stealth variants are expanding most quickly as heritage zoning spreads to secondary cities.
Deployment:
Cost tier stratification separates deployment zones, with remote sites commanding diesel logistics premiums that double total cost of ownership against grid-connected urban equivalents.
- Urban:High-tenancy density zones in Jakarta, Surabaya, and Medan justify premium steel specifications and dedicated operations centers. Co-location ratios exceed three tenants per structure, maximizing revenue per site.
- Suburban:Jakarta satellite municipalities and Javanese secondary cities balance coverage extension with capital efficiency. Hybrid power systems bridge grid reliability gaps.
- Rural:Agricultural zones and trans-provincial highways in Central and East Java drive lattice tower deployment with solar-diesel hybrid power. Universal service obligation subsidies reduce operator risk.
- Remote:Sulawesi, Maluku, and Papua present underpenetrated coverage gaps where satellite backhaul and renewable power systems are mandatory. Kominfo subsidies offset low tenancy density.
Urban deployment concentrates revenue. Remote deployment is gaining share fastest as eastern Indonesia universal service obligations accelerate.
Service Type:
Application urgency shapes procurement velocity, with 5G rollout timelines compressing site acquisition cycles against legacy microwave upgrade schedules.
- 4G:Mid-band coverage expansion across Java and Sumatra sustains bulk tenancy demand. Operators prioritize co-location on existing structures over greenfield construction.
- 5G:C-band and millimeter-wave deployments require denser site spacing and higher power budgets. Kominfo spectrum auction obligations mandate minimum coverage thresholds.
- Microwave:Point-to-point backhaul links connect remote towers to fiber nodes. Deployment concentrates in terrain-challenged areas of Sumatra and Sulawesi where trenching is uneconomical.
- Fiber Optic:Tower-mounted fiber termination points enable fronthaul for centralized baseband architectures. Manufacturing zones in Bekasi and Karawang drive demand.
4G services dominate current tenancy. 5G deployment is climbing the fastest as spectrum obligations harden.
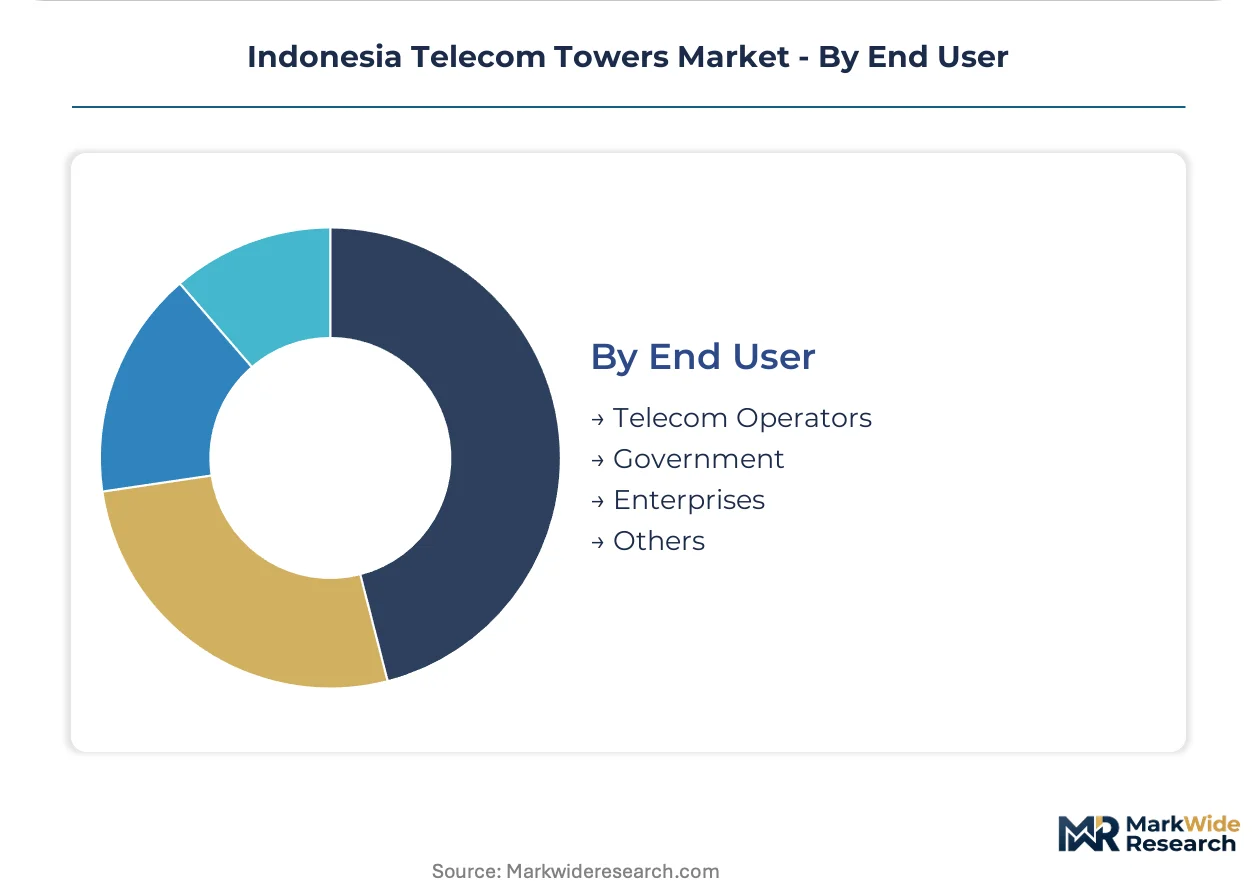
End User:
Customer type determines contract structure, with telecom operators demanding outcome-based tenancy while government and enterprise procure through capital expenditure models.
- Telecom Operators:Telkomsel, Indosat Ooredoo Hutchison, and XL Axiata account for bulk tenancy demand. These mobile network operators are consolidating vendor relationships and demanding bundled site acquisition, power uptime guarantees, and maintenance.
- Government:Kominfo universal service obligation projects and Ministry of Defense communications infrastructure drive direct procurement. BIS structural certification requirements filter qualification.
- Enterprises:Mining concessions in Papua and East Kalimantan, plus plantation estates in Sumatra, procure captive coverage for operational communications and IoT telemetry.
- Others:Broadcasting transmitters and emergency response networks represent niche demand with distinct height and redundancy specifications.
Telecom operators lead by volume. Enterprise deployment is expanding most quickly as industrial digitization penetrates extractive sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile network operators and independent tower companies concentrate procurement decisions in Java's metropolitan corridors, while universal service obligation subsidies redirect capital toward eastern archipelago coverage gaps. Kominfo's infrastructure sharing mandates reshape tenancy patterns across all zones.
Java
Jakarta, Surabaya, and Bandung drive premium tower densification for 5G mid-band deployment. Kominfo spectrum auction obligations mandate minimum coverage thresholds that accelerate site commitments. Manufacturing zones in Bekasi and Karawang host fiber-fed tower clusters serving industrial IoT applications.
Sumatra
Trans-provincial highway corridors and palm oil plantation estates sustain lattice tower demand for 4G coverage extension. BIS structural certification requirements filter qualification for government-backed universal service projects. Medan anchors northern tenancy concentration while Palembang serves southern Sumatra connectivity.
Sulawesi
Underpenetrated coverage gaps in Central and Southeast Sulawesi attract subsidized deployment under eastern Indonesia universal service obligations. Solar-diesel hybrid power systems become mandatory where grid connectivity fails. Makassar functions as the logistics hub for tower component distribution across the island.
Papua
Remote terrain and low population density necessitate satellite backhaul and renewable power configurations at every site. Kominfo subsidies offset the economic burden of single-tenant structures in mining concession zones. Jayapura and Timika clusters serve extractive sector operational communications.
Bali and Nusa Tenggara
Tourism corridor coverage requirements and maritime logistics dependencies shape tower procurement in Denpasar and Mataram. Stealth monopole variants gain preference near heritage districts where aesthetic restrictions apply. Port infrastructure in Benoa supports inter-island equipment mobilization.
Indonesia Telecom Towers Market Competitive Landscape
Player mix skews toward telecom-affiliated tower operators with captive tenancy pipelines from parent mobile network operators. The competitive structure concentrates around three strategic archetypes: independent tower companies maximizing multi-tenant ratios, operator-captive infrastructure units securing internal tenancy, and regional specialists targeting eastern Indonesia subsidy programs. Dominant competitive moves include portfolio consolidation through site acquisitions and tenancy contract renegotiations for upgraded radio equipment.
Among Indonesia-based tower operators, PT Dayamitra Telekomunikasi Tbk (Mitratel), PT Profesional Telekomunikasi Indonesia Tbk (Protelindo), and PT Tower Bersama Infrastructure Tbk occupy distinct positions within the competitive hierarchy. Mitratel represents the operator-captive archetype with structural ties to Telkom Group tenancy pipelines. Protelindo exemplifies the independent tower company model with emphasis on portfolio scale. Tower Bersama anchors the multi-tenant optimization segment where co-location density drives unit economics.
| Leading Market Players |
|---|
| PT Dayamitra Telekomunikasi Tbk (Mitratel) |
| PT Profesional Telekomunikasi Indonesia Tbk (Protelindo) |
| PT Tower Bersama Infrastructure Tbk |
| PT Centratama Menara Indonesia (EdgePoint) |
| PT Bali Towerindo Sentra Tbk |
| PT Telkom Infrastruktur Indonesia |
| PT Indosat Ooredoo Hutchison Tower |
| PT XL Axiata Towers |
| PT Smartfren Telecom Infrastructure |
| Others |
Pricing and Supply Chain Analysis
Batch production scale at Javanese steel fabricators compresses unit costs for lattice tower components while simultaneously anchoring price floors through fixed asset amortization schedules. Kominfo infrastructure sharing mandates intensify tenancy density competition, forcing tower operators to absorb site acquisition premiums rather than pass through to mobile network operators.
Pricing Analysis
Cost-plus contracts with hot-rolled steel coil indexation dominate procurement between tower operators and fabricators. Price differentiation hinges on BIS structural certification grade and volume commitment scale, with certified batches commanding premiums over uncertified alternatives. Pricing pressure intensifies in urban monopole segments where aesthetic compliance specifications inflate engineering costs without commensurate tenancy revenue expansion. Government universal service obligation projects exhibit lowest price sensitivity due to subsidy buffers, while enterprise mining concessions negotiate hardest on per-site economics.
Supply Chain Analysis
Port congestion at Tanjung Priok and container availability fluctuations on the Shanghai-Jakarta lane inflate inbound logistics costs for specialized steel grades. Fabrication capacity concentrates in China, South Korea, and domestic Javanese industrial zones. Raw material dependencies encompass hot-rolled steel coils, zinc-aluminum coating alloys, and polymer cladding resins. Single-source vulnerability persists for seismic-rated structural steel meeting Pacific Ring of Fire specifications. Distribution runs through regional contractor networks with captive installation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia telecom towers represent an early-cycle infrastructure expansion story. 5G spectrum auction obligations from Kominfo compress deployment timelines and accelerate tenancy commitments across Java and Sumatra.
For Market Incumbents: Consolidate portfolio density through targeted site acquisitions in Jakarta satellite municipalities where co-location ratios already exceed three tenants per structure. Deepen captive engineering capabilities to defend against outcome-based procurement compression from mobile network operators. Kominfo's revised transparency mandates on tower utilization rates threaten greenfield construction margins for operators with excess capacity. For New Entrants and Emerging Players: Lead with renewable power integration capabilities in Sulawesi and Papua universal service obligation zones where diesel logistics costs deter established operators. Target remote deployment segments where Kominfo subsidies offset single-tenant economics. Position through solar-hybrid system expertise as a differentiated service layer beyond steel-and-concrete commodity provision. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent tower companies with multi-tenant optimization capabilities over operator-captive infrastructure units facing parent tenancy concentration risk. Long-term viability rests on co-location density execution across Java's manufacturing corridors. Watch Kominfo spectrum auction timeline acceleration as the inflection signal for tenancy commitment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Site Acquisition Consolidation | Portfolio density in Jakarta satellite municipalities maximizes co-location revenue per structure. |
| Renewable Power Integration | Solar-hybrid systems at Sulawesi and Papua sites cut diesel logistics costs and align with Ministry of Environment guidelines. |
| Multi-Tenant Architecture Expansion | Co-location leasing models reduce per-operator capital expenditure while maximizing asset utilization. |
| BIS Certification Investment | Structural certification qualifies operators for government-backed universal service obligation projects. |
| Stealth Monopole Fabrication Scale | Batch production of polymer-clad structures narrows aesthetic compliance premiums in Yogyakarta heritage zones. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Kominfo regulatory filings, BIS structural standards documentation, and mobile operator tenancy disclosures. Primary interviews encompassed tower company engineering directors, mobile network operator procurement leads, provincial permitting officers, and steel fabricator plant managers. Secondary validation drew from customs trade data, infrastructure sharing mandate texts, and universal service obligation subsidy schedules. Bottom-up site-level economics triangulate against top-down market value reconstruction.
Segmentation dimensions modeled span structure type, deployment zone, service generation, and end-user category across the projection horizon. The analytical framework incorporates tenancy density assumptions, steel price index trajectories, and Kominfo spectrum obligation timelines. CAGRs derive from installed base expansion rates and revenue-per-tenure evolution. Industry-specific forecast inputs include BIS certification penetration curves and renewable power adoption thresholds at off-grid sites.
The analysis sits within stated boundaries; outcomes outside Kominfo regulatory enforcement consistency or steel price volatility containment would require recalibration. Forecasts reflect assumptions on infrastructure sharing mandate adherence and universal service obligation subsidy continuity. Specific risk factors encompass permitting fragmentation delays, seismic structural standard revisions, and mobile operator build-versus-lease preference shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Russia Telecom Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Myanmar Telecom Market
Telecommunications
Voip Phone Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Belgium Telecom Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Satcom Terminal Market
Telecommunications
Angola Telecom Market
Telecommunications
Germany Critical Communication Market