
 Europe 5G Infrastructure Market | 2026-2036
Europe 5G Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 5G Infrastructure Market Intelligence
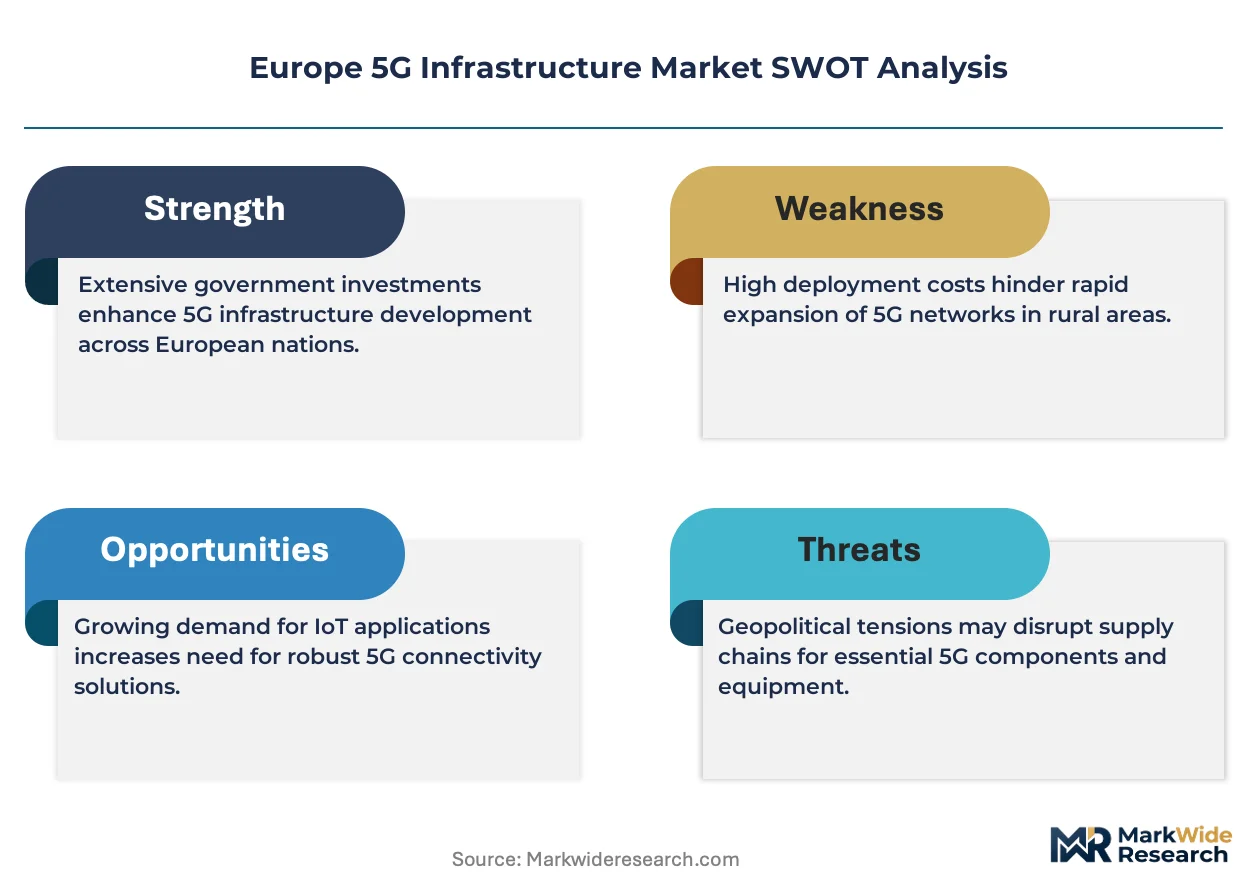
Enterprise buyers are rotating toward private 5G deployments as telecom operators face margin pressure on public network rollouts. Ericsson leverages its Open RAN portfolio to anchor Nordic markets with software-defined baseband solutions. Nokia Corporation competes through in-house silicon development for massive MIMO arrays. Huawei Technologies Co. Ltd. sustains equipment supply relationships with operators in Southern Europe despite trade restrictions elsewhere.
Europe 5G infrastructure encompasses radio access networks, transport layers, and core network elements operating across sub-6 GHz and millimeter wave spectrum bands with latency targets below one millisecond for ultra-reliable low-latency communication. The primary purpose is enabling enhanced mobile broadband, massive machine-type communications, and critical IoT services across industrial and consumer domains. Remote radio units dominate capital expenditure as operators densify urban coverage, while small cell installations accelerate fastest in stadiums, ports, and manufacturing campuses where macro cell signals attenuate. Sub-6 GHz spectrum occupies the near-term deployment majority due to propagation advantages, though millimeter wave capacity layers expand in Germany's dense urban corridors.
The European Telecommunications Standards Institute coordinates technical specifications with EU member states, while the EU Green Deal mandates energy efficiency benchmarks that shape base station power architecture decisions. REACH compliance constrains material selection for printed circuit boards and antenna housings deployed across the continent. National regulators including Germany's Bundesnetzagentur and France's Autorité de Régulation des Communications Électroniques allocate spectrum blocks that determine competitive positioning. Stakeholders must monitor spectrum auction timelines and Open RAN interoperability mandates to align procurement cycles with regulatory milestones.
Market Dynamics
Private network deployments are pulling capital away from public macro densification as German automotive OEMs and French industrial conglomerates prioritize campus-wide control over shared spectrum access.
Growth Catalysts
- EU Gigabit Infrastructure Act:The streamlined permitting framework compresses base station authorization timelines from months to weeks across member states, accelerating urban densification programs.
- Smart manufacturing:Automotive and precision engineering facilities in Germany's Baden-Württemberg and Bavaria regions are sponsoring dedicated 5G campus networks for robotic coordination and predictive maintenance.
- Millimeter wave spectrum:Dense urban corridors in Frankfurt and Paris are layering capacity-rich mmWave small cells atop sub-6 GHz coverage to support stadium and transport hub density.
Market Restraints
- Silicon supply concentration:Massive MIMO array production depends on advanced node semiconductors sourced from a concentrated East Asian foundry base, exposing equipment vendors to geopolitical supply interruptions.
- REACH material constraints:The EU's chemical registration framework restricts substrate and coating chemistries for printed circuit boards, forcing redesign cycles that extend hardware certification timelines.
- Energy cost volatility:Base station power architectures face margin pressure from electricity price swings, complicating total cost of ownership calculations for operator capex committees.
Strategic Opportunities
- Polish industrial corridors:Underpenetrated manufacturing zones in Silesia and Greater Poland present whitespace for private network sponsors seeking lower land and spectrum access costs than Western European alternatives.
- EU Green Deal mandates:Energy efficiency benchmarking for telecommunications infrastructure creates procurement preference for liquid-cooled baseband units and regenerative-powered remote radio heads.
- Open RAN interoperability:The convergence of containerized network functions with standardized fronthaul interfaces enables multi-vendor deployments that reduce single-supplier dependency.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in millimeter wave propagation modeling and beamforming algorithm development concentrates among a narrow cohort of experienced practitioners, constraining deployment velocity.
- Legacy 4G core integration:Non-standalone architectures require seamless handoff orchestration between evolved packet cores and 5G standalone functions, multiplying system test matrices and field validation cycles.
- Site acquisition friction:Municipal zoning disputes and landlord negotiation complexity in historic European city centers delay small cell placement despite streamlined national permitting frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 5G Infrastructure Market |
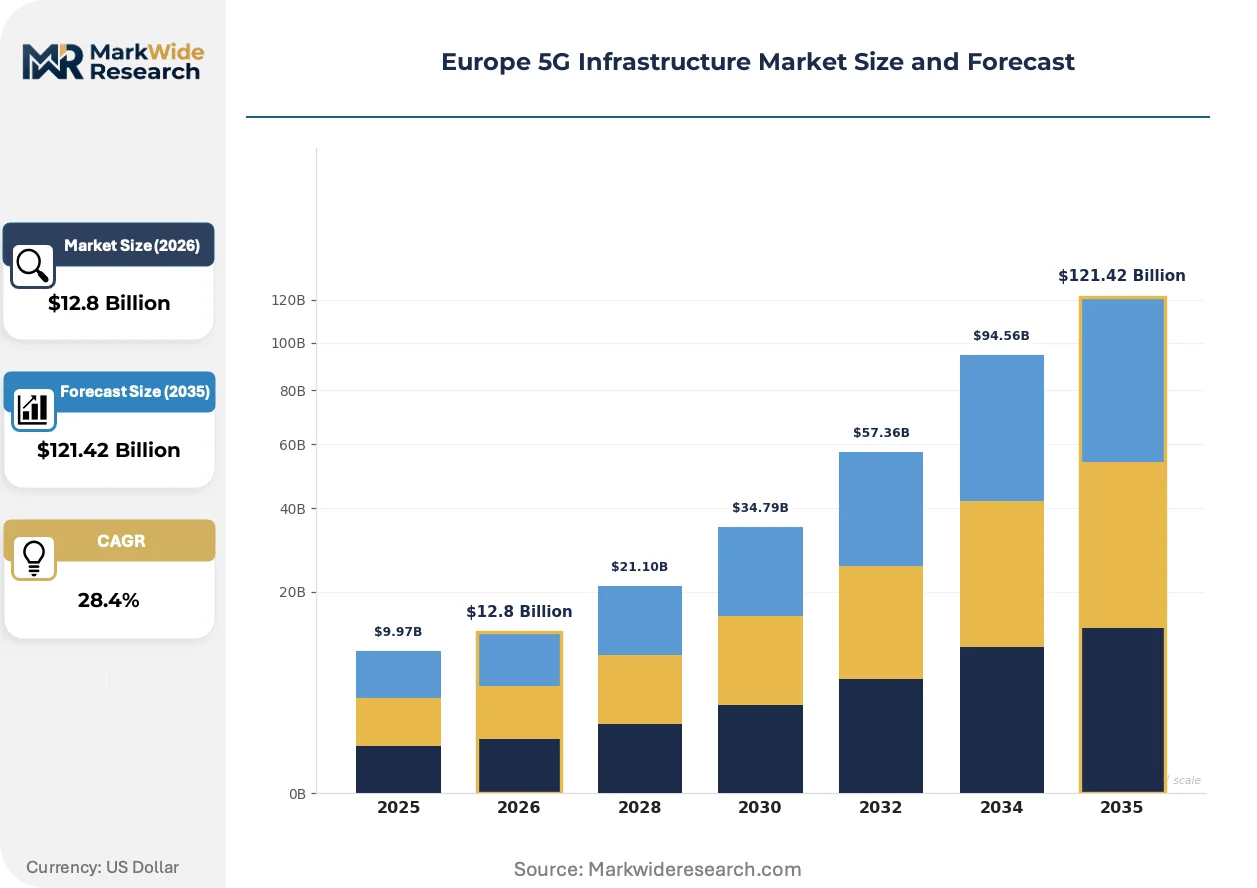
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $121.42 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Radio Units, Small Cell, Macro Cell, Distributed Antenna System Technology: Millimeter Wave, Sub-6 GHz, Network Slicing, Massive MIMO End User: Telecom Operators, Enterprises, Government, Utilities Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Ericsson, Intel Corporation, Qualcomm Technologies Inc., NEC Corporation, Vodafone PLC, Huawei Technologies Co. Ltd., Nokia Corporation, ZTE Corporation, Samsung Electronics Co. Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 5G Infrastructure Market Strategic Shifts & Innovations
Software-defined architectures are fragmenting hardware procurement patterns while regulatory energy mandates and enterprise buying model evolution reshape vendor-customer relationships across the continent.
Open RAN disaggregation is bifurcating the base station supply chain. Radio units, distributed units, and centralized units now source from separate vendors through standardized interfaces. Tier-one operators in Spain and Italy are piloting multi-supplier configurations that compress incumbent pricing power while complicating system integration accountability.
REACH and RoHS compliance deadlines are tightening material specifications for antenna housings and power amplifiers. The European Chemicals Agency's substance restriction roadmap is forcing substrate substitutions that trade thermal performance for environmental certification, particularly affecting outdoor macro deployments in Southern Europe's heat-stressed climates.
Enterprise procurement committees are consolidating vendor relationships around full-stack private network contracts rather than discrete equipment purchases. French automotive suppliers and Dutch port operators now demand guaranteed latency service level agreements bundled with hardware, shifting risk allocation onto infrastructure vendors and compressing pure equipment margins.
Europe 5G Infrastructure Market Segmentation
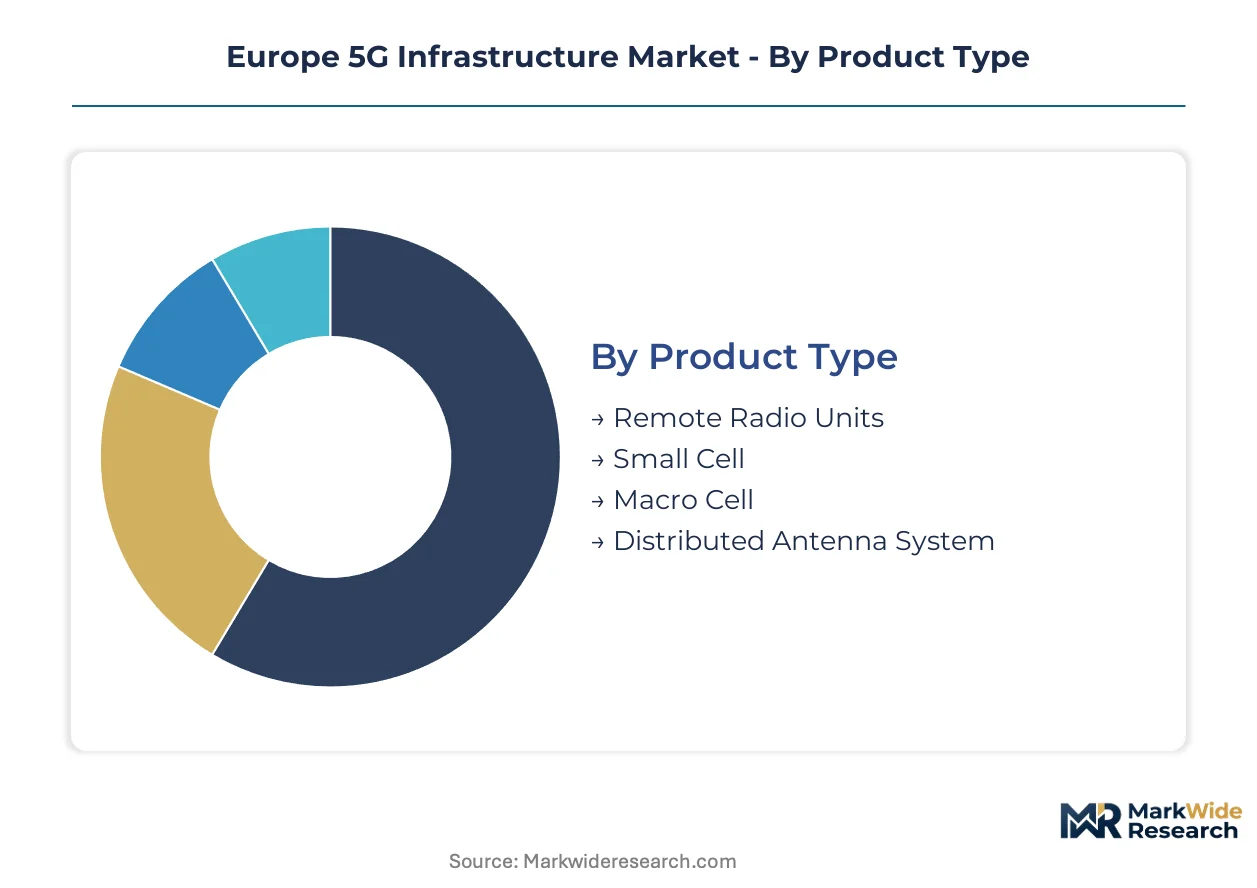
Segmentation in Europe's 5G infrastructure market reveals how capital allocation diverges between public network densification and private campus deployments. Procurement patterns vary sharply across spectrum bands and deployment models, with German industrial buyers driving fundamentally different equipment specifications than French mobile operators.
Product Type:
Domestic manufacturing concentration in Nordic countries shapes supply availability, while export-dependent Southern European operators face longer lead times for specialized hardware.
- Remote Radio Units:These modular transmitters integrate power amplifiers and transceivers for macro cell towers, handling sub-6 GHz and mmWave frequencies. Demand concentrates in Germany's Autobahn corridors and France's TGV rail lines where continuous coverage overrides cost optimization. Bundesnetzagentur spectrum allocations favor high-power configurations.
- Small Cell:Low-power access points fill coverage gaps in dense urban environments and indoor facilities. French automotive OEMs in Hauts-de-France and German precision engineering clusters in Stuttgart sponsor campus-wide deployments. REACH compliance constraints complicate outdoor housing material selection.
- Macro Cell:Full base station assemblies anchor wide-area coverage across rural expanses and suburban rings. Poland's underpenetrated regions and Spain's coastal corridors drive procurement.
- Distributed Antenna System:Networked antenna arrays extend coverage through tunnels, stadiums, and historic city centers. Italian alpine transport infrastructure and London Underground expansion projects specify these systems.
Remote Radio Units hold the largest share; momentum sits with Small Cell as private network sponsors multiply.
Technology:
Cost tiering separates premium beamforming silicon from standard radio configurations, with energy efficiency mandates compressing margins on entry-grade equipment.
- Millimeter Wave:Spectrum above 24 GHz delivers multi-gigabit throughput across short distances with precise beam steering. Frankfurt's financial district and Paris La Défense business cluster layer mmWave capacity for trading floor density. EU Green Deal power benchmarks challenge thermal design.
- Sub-6 GHz:Mid-band spectrum below 6 GHz balances propagation range with capacity, anchoring nationwide coverage layers. Rural deployment economics across Romania and Bulgaria favor this technology. National regulators prioritize sub-6 GHz auction blocks.
- Network Slicing:Virtualized resource partitioning enables guaranteed service levels for critical applications. Dutch port operators and Belgian logistics hubs specify slicing for automated cargo handling.
- Massive MIMO:64+ antenna element arrays boost spectral efficiency through spatial multiplexing. Dense urban corridors in Madrid and Milan drive deployment despite silicon supply concentration risks.
Sub-6 GHz dominates installed base; mmWave climbs fastest as urban capacity layers deepen.
End User:
Customer type determines procurement sophistication, with enterprise committees demanding outcome-based contracts that telecom operators resist.
- Telecom Operators:Deutsche Telekom, Orange, and Telefónica anchor public network rollouts across national footprints. Margin pressure from wholesale access regulation compresses equipment budgets.
- Enterprises:Volkswagen, Siemens, and ASML sponsor private campus networks for robotic coordination and quality assurance. Baden-Württemberg manufacturing zones concentrate demand.
- Government:Defense and emergency services procure hardened infrastructure for secure communications. France's Sécurité Civile and Germany's THW specify disaster-resilient architectures.
- Utilities:Grid operators deploy 5G for substation automation and distributed energy resource management. E.ON and Enel pilot private networks for smart metering density.
Telecom Operators command the largest share; Enterprises gain share fastest as spectrum frameworks liberalize private access.
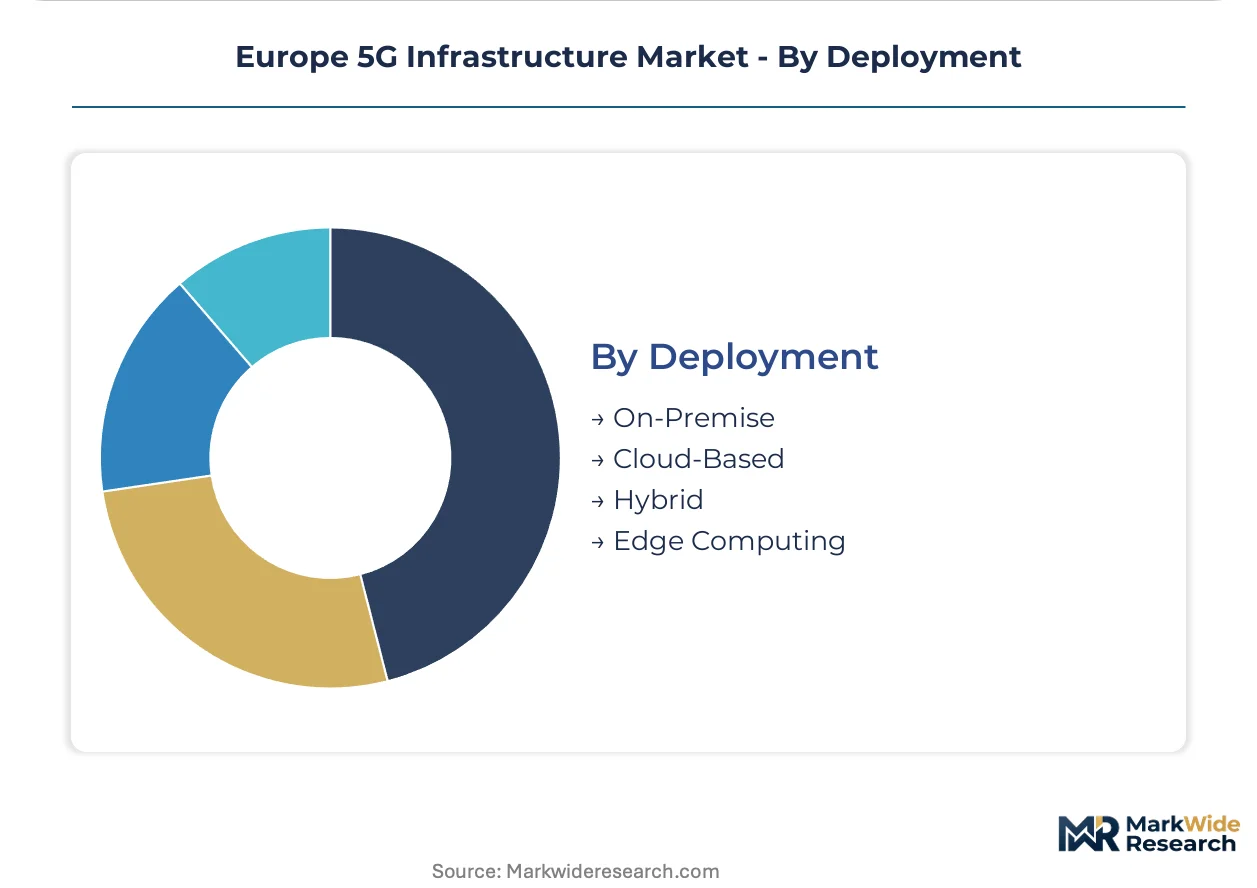
Deployment:
Volume concentration favors cloud-native architectures, though latency-sensitive applications preserve on-premise presence in industrial settings.
- On-Premise:Dedicated hardware installations within facility boundaries deliver deterministic latency for robotic control. German automotive paint shops and semiconductor cleanrooms mandate this model.
- Cloud-Based:Centralized network functions virtualize across hyperscale data centers, enabling rapid scaling. Nordic operators leverage regional cloud infrastructure for cost efficiency.
- Hybrid:Split architectures localize real-time functions while centralizing policy management. French logistics networks adopt this balance for warehouse automation.
- Edge Computing:Micro data centers at base station sites process data within 10 milliseconds. Netherlands' Rotterdam port and Hamburg's container terminals specify edge for autonomous crane coordination.
Hybrid deployments hold the largest share; Edge Computing expands most quickly as industrial latency requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish equipment flows into German industrial corridors anchor the continent's trade pattern, while Finnish vendors serve Baltic and Central European operators seeking alternatives to Asian suppliers. This bilateral exchange shapes procurement timelines and technical standards across the region.
Germany
Automotive OEMs in Stuttgart and Wolfsburg sponsor private 5G campus networks for robotic paint shop coordination. The Bundesnetzagentur's spectrum allocation framework prioritizes industrial license blocks. Bavaria's semiconductor cleanrooms and Baden-Württemberg's precision engineering clusters drive sub-6 GHz densification.
France
Port operators in Le Havre and logistics hubs around Lille demand network slicing for automated cargo handling. The Autorité de Régulation des Communications Électroniques accelerates millimeter wave authorizations for La Défense financial district. Hauts-de-France automotive suppliers specify guaranteed latency service level agreements.
United Kingdom
London Underground expansion and Scottish offshore wind installations drive distributed antenna system procurement. Ofcom's spectrum auction timelines compress equipment delivery windows. Northern England manufacturing zones pilot Open RAN multi-vendor configurations to reduce supplier concentration.
Italy
Alpine tunnel infrastructure and Milan's dense urban corridors require specialized propagation engineering. The Ministry of Economic Development's broadband incentive programs subsidize rural macro cell deployment. Emilia-Romagna's packaging machinery exporters sponsor edge computing installations for quality assurance.
Poland
Underpenetrated manufacturing zones in Silesia attract private network sponsors seeking lower spectrum access costs than Western alternatives. The Office of Electronic Communications streamlines base station permitting for EU-funded connectivity programs. Greater Poland's emerging automotive supplier parks represent whitespace for campus-wide deployments.
Europe 5G Infrastructure Market Key Industry Players
Listed leaders compete with private specialists across capital structure and customer segment, creating a tiered market where scale-driven incumbents anchor public network rollouts while agile challengers capture enterprise private deployments. Equipment vendors fragment across radio access, transport, and core network domains. Three archetypes dominate: integrated stack providers, disaggregated Open RAN specialists, and captive telecom operator procurement arms. Competitive moves concentrate on silicon supply security and energy efficiency certification for EU Green Deal compliance.
Within the integrated stack tier, Ericsson anchors Nordic operator relationships with end-to-end portfolio breadth, while Nokia Corporation occupies a comparable position across Continental European markets. Huawei Technologies Co. Ltd. exemplifies the geopolitically constrained supplier archetype, sustaining equipment flows to Southern European operators despite trade restriction pressures elsewhere. These three entities collectively represent the spectrum from Western-listed to Chinese-headquartered competitive positioning.
| Leading Market Players |
|---|
| Ericsson |
| Intel Corporation |
| Qualcomm Technologies Inc. |
| NEC Corporation |
| Vodafone PLC |
| Huawei Technologies Co. Ltd. |
| Nokia Corporation |
| ZTE Corporation |
| Samsung Electronics Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Equipment vendor scale economies in massive MIMO silicon anchor both supply concentration and price floors across the European 5G infrastructure value chain. German automotive OEM procurement committees leverage volume commitments to compress unit economics for private campus deployments, while REACH compliance redesign cycles extend hardware certification timelines and inflate non-recurring engineering costs.
Pricing Analysis
Sub-6 GHz versus millimeter wave versus Open RAN disaggregated configurations stratify across premium, standard, and economy tiers. Price differentiation hinges on certification grade under EU Green Deal energy efficiency benchmarks and volume scale from national operator consolidation. Cost compression in standard-tier remote radio units intensifies because of silicon foundry margin pressure. Telecom operators exhibit highest price sensitivity due to wholesale access regulation, while German industrial conglomerates prioritize deterministic latency guarantees over unit cost optimization.
Supply Chain Analysis
Taiwan and South Korea anchor advanced node semiconductor fabrication for massive MIMO beamforming silicon. European 5G infrastructure draws from concentrated East Asian foundry capacity for 7nm and 5nm baseband processors, with substrate materials and gallium nitride power amplifiers as critical dependencies. Single-source vulnerability in advanced lithography equipment exposes deployment timelines to export control friction. Distribution runs through tier-one operator procurement arms and direct enterprise contracts with campus network sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's 5G infrastructure sector represents a high-growth disruption as private network deployments accelerate faster than public macro densification, catalyzed by the EU Gigabit Infrastructure Act's streamlined permitting timelines.
For Market Incumbents: Compound installed base advantages through captive silicon supply arrangements that insulate against foundry concentration risk. Deepen energy efficiency certification under EU Green Deal mandates to capture procurement preference from sustainability committees. Defend against Open RAN disaggregation by anchoring software-defined baseband portfolios with Nordic operator relationships. For New Entrants and Emerging Players: CE marking fast-track for liquid-cooled baseband units creates procurement entry points with French port operators and Dutch logistics hubs seeking EU Green Deal compliance. Polish industrial corridors in Silesia present whitespace for private network sponsors facing lower spectrum access costs than Western European alternatives. Pursue outcome-based contracting models that bundle guaranteed latency SLAs with hardware deployment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized Open RAN software vendors with containerized network function expertise over integrated stack incumbents facing margin compression. Long-term viability over the next decade rests on silicon supply security and energy efficiency differentiation. Monitor spectrum auction timelines and Open RAN interoperability mandates as inflection indicators for procurement cycle alignment.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | Multi-vendor deployments reduce single-supplier dependency for Spanish and Italian operators. |
| Silicon Supply Security Partnership | Advanced node foundry agreements insulate Nokia and Ericsson against geopolitical interruption. |
| Private Campus Network Expansion | Baden-Württemberg automotive OEMs sponsor dedicated 5G for robotic paint shop coordination. |
| EU Green Deal Compliance Investment | Liquid-cooled baseband units capture procurement preference from sustainability committees. |
| Millimeter Wave Capacity Layering | Frankfurt and Paris financial districts layer mmWave for trading floor density requirements. |
Research Approach
Operator-level perspectives from network planning executives, procurement directors at German automotive OEMs, regulatory affairs specialists at national spectrum authorities, and infrastructure deployment engineers anchored the qualitative base. Secondary validation drew from Bundesnetzagentur spectrum allocation records, ETSI technical specifications, EU Green Deal implementation guidance, and equipment vendor SEC disclosures. Bottom-up unit economics triangulated against top-down capex forecasts across the projection horizon.
Sensitivity analysis tested deployment velocity assumptions against spectrum auction timing and Open RAN adoption curves. The analytical framework modeled segmentation across product type, spectrum band, deployment architecture, and end-user category throughout the forecast period. CAGRs derived from equipment shipment trajectories and private network sponsorship commitments, with silicon supply constraints and REACH compliance timelines as industry-specific forecast inputs.
Underlying assumptions cover spectrum allocation continuity, foundry capacity expansion, and regulatory energy mandate enforcement, with deviation risk concentrated in export control escalation and municipal zoning disputes. Recalibration cycles align with material shifts in spectrum auction outcomes and Open RAN interoperability certification milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Nepal Telecom Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market
Telecommunications Infrastructure
Global Optical Transport Network (OTN) Equipment Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market