
 International Wholesale Voice Carrier Market | 2026-2036
International Wholesale Voice Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
International Wholesale Voice Carrier Market Analysis
EU digital sustainability reporting under CSRD is consolidating compliance burdens across carrier procurement departments. Deutsche Telekom AG leverages its pan-European fiber backbone to sustain margin-efficient voice termination across regulated markets. Tata Communications Limited anchors trans-Asian voice corridors with undersea cable investments that bypass traditional transit hubs. Orange SA competes through direct bilateral agreements with African and Middle Eastern operators, reducing dependency on third-party clearing.
International wholesale voice carriers provide minute-by-minute call routing, signaling conversion, and settlement services between telecommunications operators across national borders, typically operating through SS7 or IP-based interconnection protocols with quality-of-service guarantees measured in post-dial delay and answer-seizure ratios. The primary commercial purpose centers on enabling retail operators to complete calls outside their licensed geographic footprints without building redundant international infrastructure. Voice termination services still generate the largest revenue pool within service type segmentation, though VoIP technology is displacing TDM-based routing as the dominant transport mode across both developed and developing corridors. SIP trunking represents the fastest-expanding technology segment, driven by enterprise migration from legacy PBX systems and mobile operators seeking packet-efficient interconnection.
The US Federal Communications Commission enforces intercarrier compensation rules that shape wholesale pricing floors for international voice traffic terminating on American networks, while the European Union's Electronic Communications Code mandates cost-oriented wholesale access obligations that constrain carrier margin structures. India's TRAI regulates international long-distance licensing terms that determine market entry thresholds for foreign carriers seeking direct bilateral arrangements with domestic operators. Stakeholders must monitor regulatory divergence between cost-based and market-based interconnection regimes as this friction determines arbitrage opportunities and routing optimization strategies.
Market Dynamics
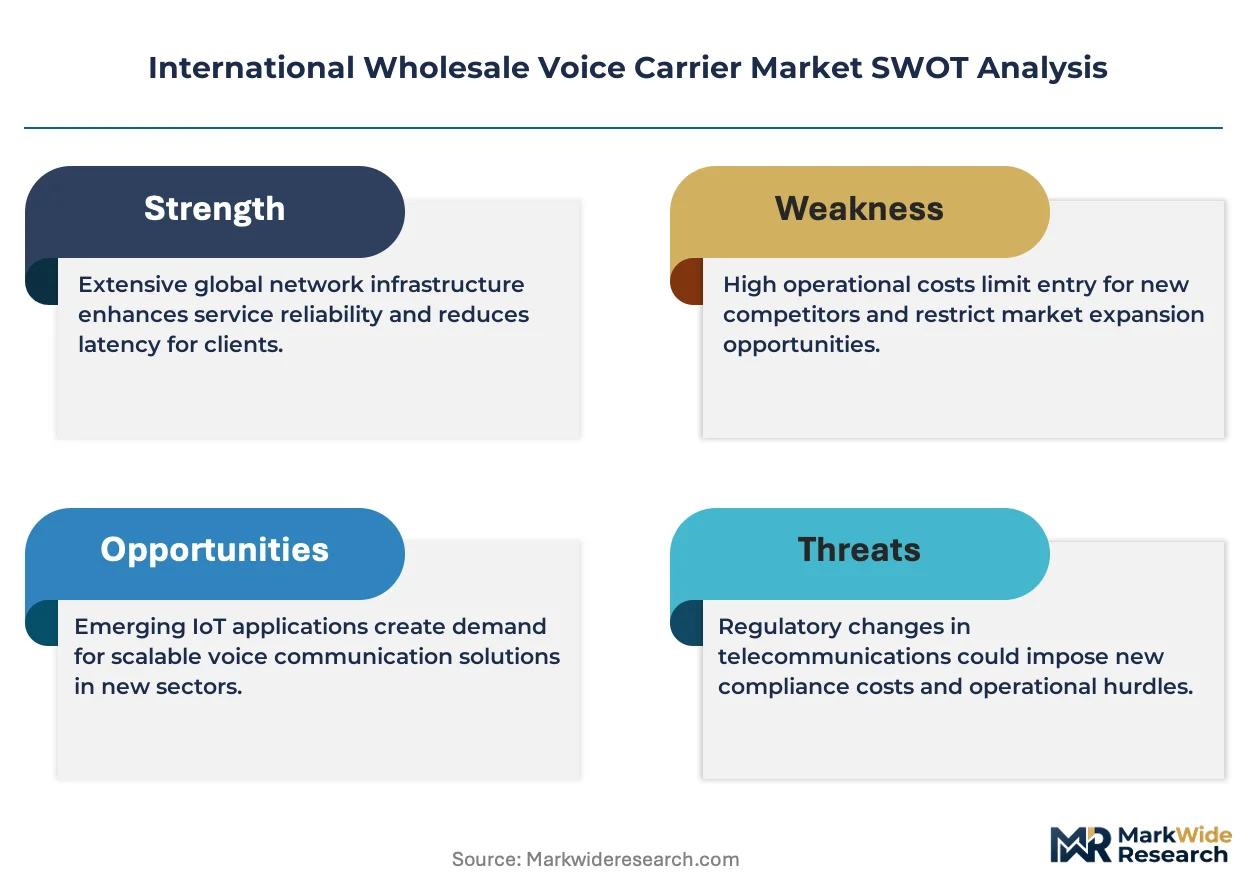
The wholesale voice carrier market faces structural compression as VoIP and SIP trunking protocols displace legacy TDM infrastructure, collapsing per-minute termination rates while forcing carriers to rebuild margin through volume throughput and quality-of-service differentiation.
Growth Catalysts
- Submarine cable expansion:New fiber deployments across Southeast Asian corridors including Indonesia, Vietnam, and the Philippines are expanding international voice capacity and reducing transit dependency on traditional hub markets.
- EU CSRD compliance:Digital sustainability reporting mandates are consolidating procurement decisions around carriers with verifiable carbon accounting, favoring infrastructure-heavy operators with measured Scope 3 emissions data.
- Mobile operator interconnect:Network operators in emerging markets are accelerating bilateral voice agreements as legacy circuit-switched infrastructure reaches end-of-life, creating replacement demand for packet-based termination.
Market Restraints
- Per-minute rate compression:VoIP protocol adoption has eliminated the pricing power once held by TDM-based carriers, squeezing gross margins on international termination services to low single-digit percentages.
- Regulatory arbitrage friction:Divergence between cost-based interconnection regimes in the European Union and market-based compensation rules enforced by the US Federal Communications Commission complicates routing optimization across trans-Atlantic corridors.
- Over-the-top substitution:Messaging applications and app-based voice services are capturing international call volume that previously flowed through carrier networks, particularly on mobile-to-mobile routes.
Strategic Opportunities
- Enterprise SIP trunking:Corporate migration from legacy PBX systems to cloud-based unified communications is expanding demand for managed voice interconnect services with guaranteed quality metrics.
- African corridor development:Direct bilateral agreements with operators in Nigeria, Kenya, and South Africa offer margin-efficient alternatives to traditional European transit hubs for voice traffic originating in the Middle East and South Asia.
- India TRAI licensing reform:Proposed adjustments to international long-distance licensing terms may lower entry thresholds for foreign carriers seeking direct interconnect arrangements with domestic Indian operators.
Industry Challenges
- SS7-to-IP signaling conversion:Maintaining interoperability between legacy signaling systems and modern packet networks requires specialized engineering talent that carriers struggle to retain as the workforce ages.
- Quality metric enforcement:Post-dial delay and answer-seizure ratio guarantees demand continuous network monitoring infrastructure that strains operational budgets at compressed price points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | International Wholesale Voice Carrier Market |
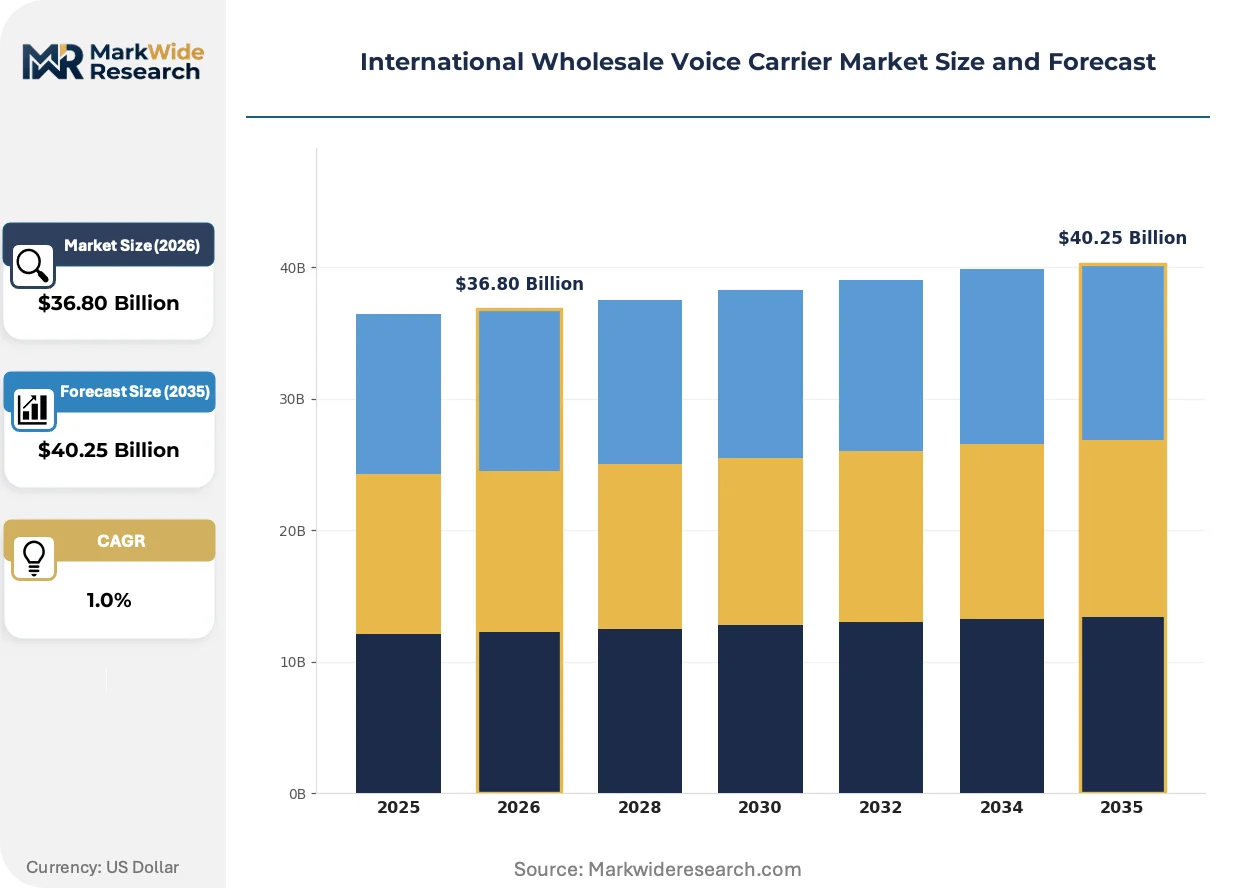
| Market Size in 2026 | $36.80 Billion |
| Market Size in 2035 | $40.25 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Termination, Voice Origination, Private Line, Toll-Free Services Technology: VoIP, TDM, SIP, MPLS End User: Telecom Operators, Resellers, Enterprises, Call Centers Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | BT Group Plc, Orange SA, Verizon Communications, Lumen Technologies, NTT Group, AT&T Corporation, Tata Communications Limited, China Mobile International Limited, Deutsche Telekom AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
International Wholesale Voice Carrier Market Emerging Trajectories
Protocol migration and regulatory fragmentation are actively reshaping competitive positioning in wholesale voice, with carriers differentiating through infrastructure ownership rather than arbitrage routing.
WebRTC technology is expanding into browser-based voice communications, eliminating client software requirements for enterprise users. Contact center operators and unified communications providers are adopting this standard for agent-facing applications. The technology is expanding into wholesale carrier portfolios as a low-friction onboarding mechanism for enterprise SIP trunking customers.
CSRD mandates from the European Union now require large carriers to report Scope 3 emissions from network equipment suppliers and data center partners. This disclosure obligation is filtering procurement decisions toward vertically integrated operators with captive renewable energy contracts. German and French carriers are responding by consolidating supplier panels and demanding power-usage effectiveness certifications from interconnect partners.
Outcome-based routing contracts are displacing traditional per-minute settlement models in enterprise voice procurement. Buyers now specify maximum acceptable post-dial delay thresholds rather than selecting routes based on price alone. This behavioral shift is most visible in financial services and healthcare verticals in the United Kingdom and the Netherlands, where regulatory latency requirements for emergency and trading communications override cost minimization.
International Wholesale Voice Carrier Market Segmentation
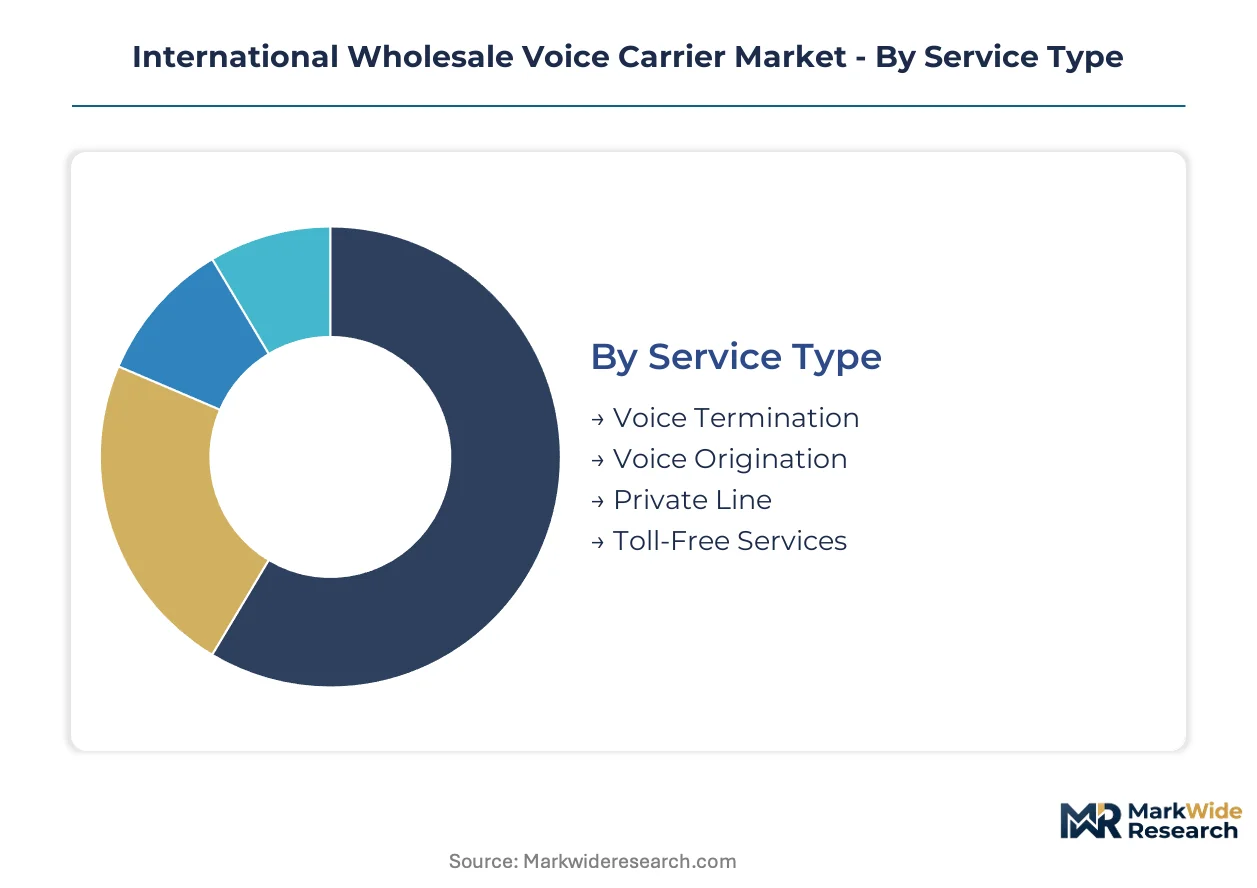
Wholesale voice carriers structure service portfolios around termination economics, protocol migration timelines, and customer technical maturity. Segment boundaries determine pricing power, infrastructure investment requirements, and regulatory exposure across carrier business models.
Service Type:
Volume throughput dominates revenue concentration in legacy termination, while premium origination and managed services capture margin expansion opportunities.
- Voice Termination:Call completion services routing international traffic to destination networks through bilateral agreements or clearinghouse arrangements. Demand concentrates in Southeast Asian corridors including Indonesia and Vietnam, where submarine cable expansion is displacing traditional transit hubs. Per-minute rate compression from VoIP adoption squeezes margins to low single-digit percentages.
- Voice Origination:Inbound call collection from foreign networks enabling retail operators to offer local presence numbers across multiple countries. Enterprise demand in financial services and healthcare verticals across the United Kingdom and Netherlands drives quality-of-service premiums above commodity termination rates.
- Private Line:Dedicated circuit capacity for carriers requiring guaranteed bandwidth and latency isolation.
- Toll-Free Services:Inbound toll-free number provisioning with international accessibility and carrier settlement.
Mature deployment sits with Voice Termination. Newer deployment is concentrated in Toll-Free Services.
Technology:
Protocol selection tracks infrastructure replacement cycles and interoperability requirements between legacy and packet networks.
- VoIP:Packet-switched voice transport compressing bandwidth requirements and collapsing per-minute costs versus circuit-switched alternatives. Mobile operators in emerging markets accelerate bilateral agreements as TDM infrastructure reaches end-of-life, creating replacement demand.
- SIP:Session Initiation Protocol enabling session management and signaling for enterprise unified communications and trunking applications. Corporate migration from legacy PBX systems in North America and Western Europe expands managed interconnect demand with guaranteed post-dial delay metrics.
- TDM:Time-division multiplexing circuit-switched infrastructure maintaining interoperability with legacy network elements.
- MPLS:Multi-Protocol Label Switching providing traffic-engineered paths with quality-of-service guarantees for carrier backbones.
Established infrastructure relies on TDM. Steepest expansion trajectory belongs to SIP.
End User:
Customer type determines technical support intensity, contract structure, and route optimization complexity.
- Telecom Operators:Mobile network operators and fixed-line carriers sourcing international capacity through bilateral or wholesale arrangements. Expansion of interconnect agreements in Nigeria, Kenya, and South Africa offers margin-efficient alternatives to European transit hubs.
- Enterprises:Corporate entities procuring SIP trunking and managed voice services for unified communications platforms. Contact center operators and financial services firms in the United Kingdom adopt WebRTC-based browser communications for agent-facing applications.
- Resellers:Intermediary entities arbitraging routes and aggregating demand from smaller retail operators.
- Call Centers:Business process outsourcing operations requiring high-volume termination with answer-seizure ratio guarantees.
Traditional volume concentration rests with Telecom Operators. Emerging deployment clusters with Enterprises.
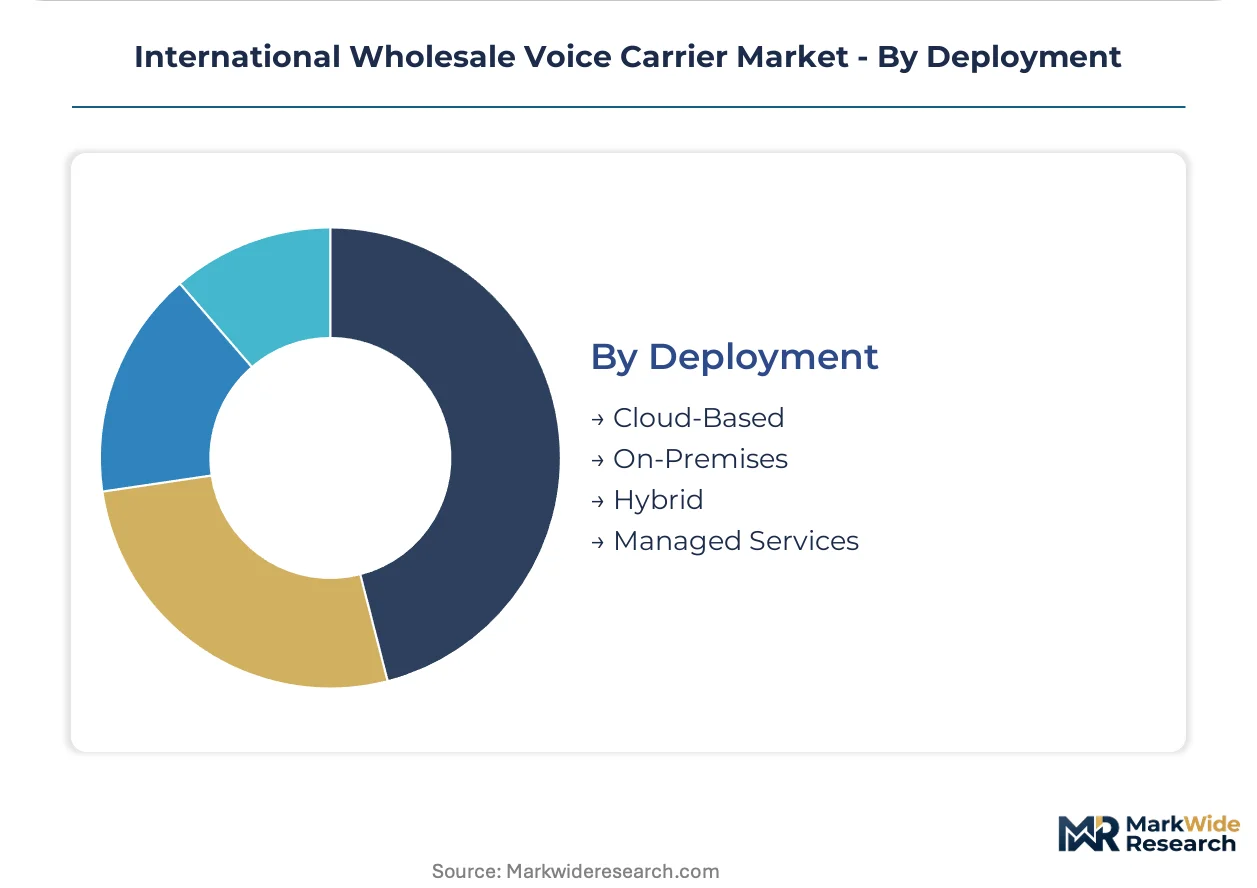
Deployment:
Infrastructure control preferences split between operational sovereignty and capital efficiency objectives.
- Cloud-Based:Fully managed voice infrastructure eliminating customer premises equipment and shifting operational burden to carrier operations. EU CSRD compliance mandates are consolidating procurement toward vertically integrated operators with verifiable Scope 3 emissions data and captive renewable energy contracts.
- Managed Services:Outsourced network operations with carrier-maintained infrastructure and performance guarantees. Quality metric enforcement demands continuous monitoring infrastructure that strains operational budgets at compressed price points.
- On-Premises:Customer-operated switching and signaling equipment retaining full operational control.
- Hybrid:Mixed architecture combining cloud trunking with retained premises equipment for specific functions.
Legacy architecture persists in On-Premises. Accelerating migration targets Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity concentrates in submarine cable landing stations across Southeast Asia and the Mediterranean, while consumption demand clusters in financial centers and emerging market mobile networks. Infrastructure ownership determines routing economics more than geographic proximity. Regulatory divergence between cost-based and market-based interconnection regimes fragments procurement strategies across corridors.
Indonesia
Mobile network operators accelerate bilateral voice interconnect agreements as legacy TDM infrastructure phases out. TRAI licensing frameworks in neighboring jurisdictions indirectly shape Indonesian carrier entry thresholds through competitive benchmarking. Jakarta and Batam host submarine cable landing stations that expand international voice capacity while reducing transit dependency on Singapore hubs.
Germany
EU CSRD mandates consolidate procurement decisions around carriers with verifiable Scope 3 emissions data and captive renewable energy contracts. The Electronic Communications Code imposes cost-oriented wholesale access obligations that constrain margin structures for voice termination services. Frankfurt anchors pan-European fiber backbones that sustain margin-efficient voice routing across regulated markets.
United States
FCC intercarrier compensation rules shape wholesale pricing floors for international voice traffic terminating on American networks. Financial services and healthcare verticals in New York and Chicago drive demand for outcome-based routing contracts with guaranteed post-dial delay thresholds. Lumen Technologies and AT&T Corporation occupy positions within the infrastructure-heavy carrier tier serving these latency-sensitive segments.
India
TRAI regulates international long-distance licensing terms that determine market entry thresholds for foreign carriers seeking direct bilateral arrangements with domestic operators. Mumbai and Chennai concentrate submarine cable investments that bypass traditional European transit hubs for voice traffic originating in the Middle East and South Asia. Tata Communications Limited anchors trans-Asian voice corridors with undersea cable infrastructure.
United Kingdom
Contact center operators and financial services firms adopt WebRTC-based browser communications for agent-facing applications. Ofcom regulations align with EU cost-oriented frameworks while maintaining distinct interconnection dispute resolution mechanisms. London hosts clearinghouse arrangements that intermediate voice settlement between African and Middle Eastern operators.
International Wholesale Voice Carrier Market Vendor Landscape
The competitive structure tilts toward infrastructure-heavy incumbents with captive submarine cable and fiber backbone assets. Tiered specialization separates premium managed service providers from commodity termination arbitrageurs. Three archetypes dominate: pan-regional integrated carriers with renewable energy contracts, bilateral-focused specialists in emerging market corridors, and cloud-native SIP trunking platforms. Capacity expansion through submarine cable consortium participation and strategic partnerships for African corridor development represent the dominant competitive moves.
Among European integrated carriers, Deutsche Telekom AG and Orange SA exemplify the infrastructure-heavy archetype with pan-regional fiber assets and CSRD-compliant procurement positioning. Tata Communications Limited occupies a position within the trans-Asian specialist tier, leveraging undersea cable investments to bypass traditional transit hubs. BT Group Plc sits within the managed services vector, serving enterprise SIP trunking demand with quality-of-service guarantees. Verizon Communications and AT&T Corporation anchor the North American infrastructure tier, with FCC-regulated termination economics shaping their wholesale voice strategies. China Mobile International Limited represents the scale-driven emerging market archetype, expanding bilateral agreements across Southeast Asian corridors.
| Leading Market Players |
|---|
| BT Group Plc |
| Orange SA |
| Verizon Communications |
| Lumen Technologies |
| NTT Group |
| AT&T Corporation |
| Tata Communications Limited |
| China Mobile International Limited |
| Deutsche Telekom AG |
| Others |
Supply Flow & Price Mechanics
Enterprise SIP trunking procurement in financial services and healthcare verticals anchors the dominant outcome-based pricing model, where post-dial delay guarantees supersede per-minute cost minimization and compress arbitrage margins across commodity termination tiers.
Pricing Analysis
Margin tightening in legacy TDM termination reflects VoIP protocol displacement and submarine cable capacity expansion across Southeast Asian corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies by answer-seizure ratio guarantees and geographic routing complexity. Cost-down pressure on international voice termination accelerates because mobile operators in emerging markets bypass traditional clearinghouses through direct bilateral agreements. Resellers exhibit highest price sensitivity, while enterprise buyers in regulated verticals absorb quality premiums.
Supply Chain Analysis
Refurbishment and redeployment of legacy SS7 signaling equipment flows through specialized engineering services as carriers phase out circuit-switched infrastructure. Submarine cable manufacturing concentrates in Japan, South Korea, and the United States, with fiber deployment projects drawing from Corning, Fujikura, and Prysmian supply bases. Single-source vulnerability sits with specialized signaling protocol engineers nearing retirement age. Distribution runs through carrier consortium arrangements for cable system capacity and bilateral interconnect agreements for termination services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Submarine cable landing station capacity constraints in Southeast Asian corridors prop termination pricing for infrastructure-heavy carriers against arbitrage-dependent competitors.
For Market Incumbents: Deepen captive fiber backbone investments across Indonesia, Vietnam, and the Philippines to defend margin position against cloud-native SIP trunking platforms. Pursue backward integration into renewable energy contracts for EU CSRD compliance advantage. Prioritize SS7-to-IP signaling engineering talent retention through specialized compensation structures. For New Entrants and Emerging Players: Managed service providers in African corridor development present the most penetrable white-space target, with direct bilateral agreements in Nigeria, Kenya, and South Africa offering margin-efficient alternatives to European transit dependency. WebRTC-based browser communications for contact center operators provide a low-friction onboarding mechanism distinct from incumbent SIP trunking portfolios. For Investors and Strategic Acquirers: Distressed-cycle entries favor infrastructure-heavy carriers with submarine cable consortium participation in Southeast Asian corridors. Long-term viability hinges on vertical integration depth and regulatory compliance positioning across cost-based and market-based interconnection regimes. Monitor India TRAI licensing reform announcements for foreign carrier entry threshold adjustments as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Submarine Cable Consortium Participation | Secures dedicated fiber capacity on Indonesia-Vietnam-Philippines routes bypassing Singapore transit hubs. |
| Renewable Energy Contract Captive Supply | Positions EU carriers for CSRD Scope 3 emissions compliance in procurement decisions. |
| Direct Bilateral Agreement Expansion | Reduces clearinghouse dependency for voice termination in African and Middle Eastern corridors. |
| WebRTC Platform Integration | Enables browser-based voice onboarding for enterprise contact centers without client software. |
| SS7-to-IP Signaling Engineering Acquisition | Addresses workforce aging risks in legacy protocol interoperability maintenance. |
Methodological Framework
Multi-period observation of submarine cable deployment timelines, bilateral interconnect agreement filings, and per-minute rate trajectories anchored the trend analysis, supplemented by interviews with carrier network planning officers, wholesale voice procurement managers at mobile operators, submarine cable system developers, and signaling protocol engineering specialists. Secondary validation drew from FCC intercarrier compensation rulemakings, EU Electronic Communications Code implementation reports, TRAI consultation papers, ITU-T traffic statistics, and carrier financial disclosures. Bottom-up route-level volume estimates and top-down market size triangulation cross-checked segmentation outputs.
Input-output matrix modeling structured the analytical framework across service type, technology protocol, end-user category, and deployment architecture dimensions throughout the forecast period. CAGRs derived from trend extrapolation of VoIP displacement rates, SIP trunking adoption curves, and emerging market mobile subscriber growth. Industry-specific forecast inputs incorporated submarine cable capacity commissioning schedules and regulatory licensing reform timelines.
Caveats apply where India TRAI licensing adjustments, EU CSRD enforcement intensity variations, or OTT voice substitution acceleration could materially shift the outlook. Practitioners should monitor bilateral agreement announcement velocity and submarine cable route diversification for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Belgium Telecom Market
Telecommunications
Spain ICT Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Thailand Telecom Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
Brazil Telecom Market
Telecommunications
Germany ICT Market
Telecommunications
Hungary ICT Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
5G in Defense Market
Telecommunications
Germany Critical Communication Market
Telecommunications
5G Transport Networks Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market