
 Fixed LTE Market | 2026-2036
Fixed LTE Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed LTE Market Foresight
Massive MIMO integration with carrier aggregation is reconfiguring how fixed LTE networks deliver gigabit-equivalent speeds over licensed spectrum. Huawei Technologies leverages its end-to-end equipment portfolio to dominate infrastructure supply for outdoor CPE deployments. Samsung Electronics anchors its position through in-house semiconductor production for LTE Cat 12 modems. AT&T competes by extending its FirstNet spectrum holdings into fixed wireless residential offerings.
Fixed LTE denotes a wireless broadband technology that uses Long-Term Evolution radio standards to deliver stationary internet access through Customer Premises Equipment operating in licensed cellular bands, typically achieving 50-300 Mbps depending on channel bandwidth and MIMO configuration. The technology serves regions where fiber or cable deployment remains economically prohibitive. Indoor CPE and outdoor CPE represent the mature volume segments where price competition has compressed hardware margins, while industrial gateways command premium positioning due to hardened enclosures and edge computing integration. LTE Cat 6 and LTE Cat 12 are outpacing legacy Cat 4 deployments as carriers refarm spectrum for higher throughput tiers.
The FCC governs spectrum licensing and equipment authorization under Part 27 rules, while the ITU-R coordinates cross-border interference standards for LTE band harmonization. The EU's Radio Equipment Directive mandates CE marking for CPE sold in member states, creating compliance cost barriers for non-European manufacturers. Stakeholders must monitor spectrum auction timelines and Open RAN interoperability mandates as these will determine which equipment vendors qualify for operator procurement shortlists.
Market Dynamics
Spectrum refarming from legacy 3G bands to LTE carriers is compressing deployment timelines for fixed wireless operators. The FCC's accelerated auction schedules and rural subsidy reallocation are forcing carriers to reconfigure capital allocation toward licensed fixed wireless infrastructure.
Growth Catalysts
- Rural Digital Opportunity Fund:The FCC's subsidy mechanism redirects carrier investment toward unserved census blocks, lowering customer acquisition costs in economically marginal territories.
- Massive MIMO deployment:Antenna array densification multiplies spectral efficiency, enabling gigabit-equivalent throughput without fiber backhaul requirements.
- Utility sector automation:Grid modernization programs deploy industrial LTE gateways for substation monitoring and distributed energy resource management.
Market Restraints
- Semiconductor supply concentration:LTE modem fabrication depends on Taiwan-based foundry capacity, exposing CPE manufacturers to geopolitical disruption risk.
- Licensed spectrum scarcity:Mid-band allocations remain constrained by satellite incumbents and military reservations in the United States.
- Fiber substitution threat:Municipal broadband overbuilds in secondary metros erode the addressable market for fixed wireless residential offerings.
Strategic Opportunities
- Precision agriculture connectivity:Brazil's rural mechanization sector presents unmet demand for weather-hardened outdoor CPE with edge computing capabilities.
- CBRS private networks:Shared spectrum frameworks enable enterprise verticals to deploy campus-wide fixed LTE without carrier intermediation.
- EU Green Deal alignment:The Radio Equipment Directive's energy efficiency mandates favor next-generation CPE with sleep-mode power optimization.
Industry Challenges
- RF engineering talent scarcity:Carrier-grade network design requires specialized expertise in propagation modeling and interference mitigation that outpaces academic pipeline output.
- Multi-operator interoperability:Open RAN disaggregation creates integration complexity between radio units and virtualized baseband software from disparate vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed LTE Market |
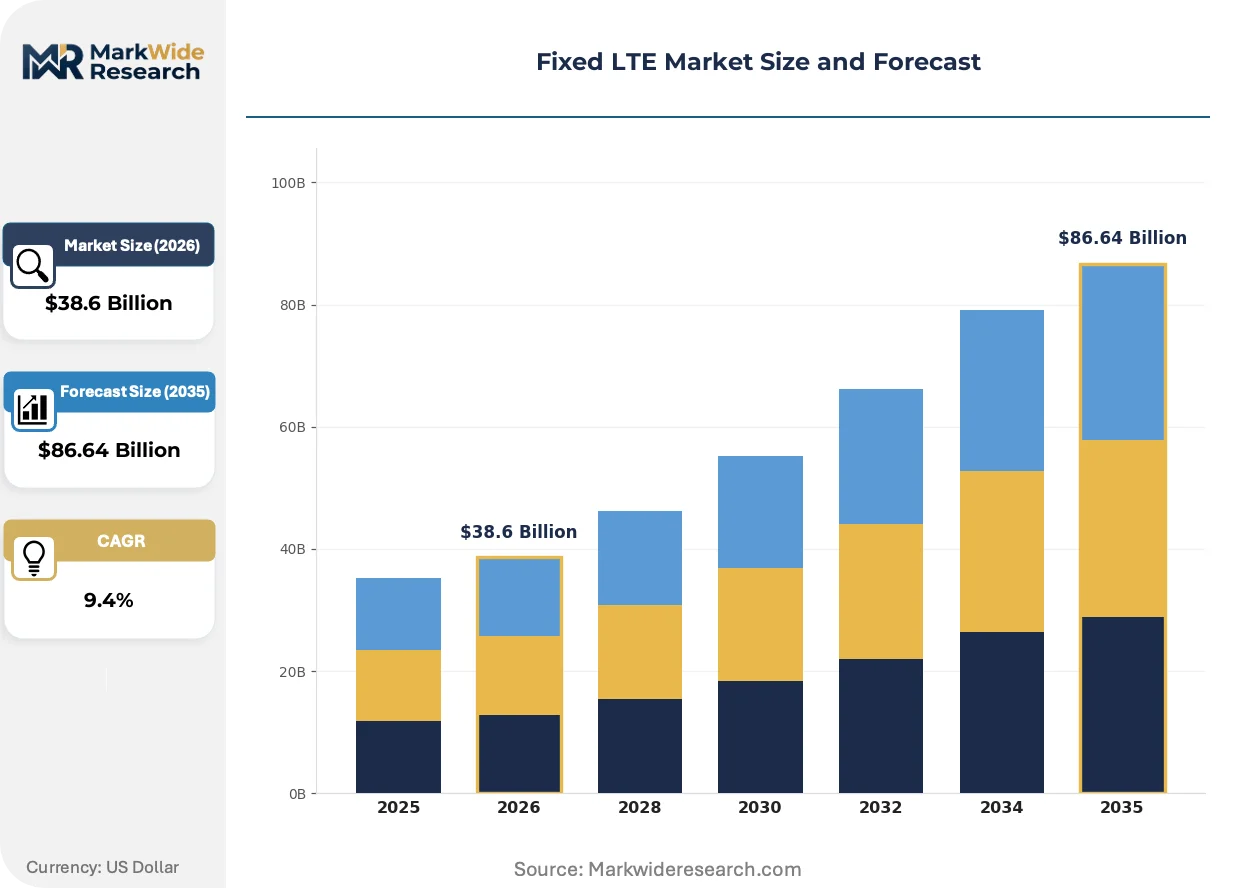
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor CPE, Outdoor CPE, Industrial Gateways, USB Dongles, Routers Technology: LTE Cat 4, LTE Cat 6, LTE Cat 12, LTE Cat M1, LTE Cat NB1 Application: Broadband Access, Smart Grids, Security Surveillance, Remote Monitoring, Public Wi-Fi End User: Telecom Operators, Enterprises, Governments, Educational Institutions, Internet Service Providers |
| Companies Covered | Huawei Technologies, AT&T, Cisco Systems, Samsung Electronics, Netgear, CommScope Holding Company, Sagemcom, ZTE Corporation, Telrad Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed LTE Market Shifts & Advancements
Virtualized radio access networks are dissolving the hardware-software boundary that historically locked operators into single-vendor infrastructure stacks. This architectural shift enables programmable spectrum allocation and accelerates feature deployment cycles.
Cloud-native baseband processing is virtualizing the distributed unit function, allowing operators to consolidate computational workloads in regional data centers rather than cell towers. Tier-1 carriers in the United States are migrating 60% of new macro deployments to this architecture. The technology is virtualizing capital deployment patterns, shifting expenditure from proprietary hardware to commodity servers and software licenses.
The FCC's Part 27 equipment authorization modernization streamlines certification timelines for multi-band CPE. Manufacturers gain concurrent market access across licensed and shared spectrum blocks. Outdoor CPE vendors targeting the Rural Digital Opportunity Fund are prioritizing modular designs that satisfy both Part 27 and CE marking requirements for dual-continent deployment.
Enterprise procurement teams are consolidating vendor relationships through managed service contracts that bundle CPE, installation, and network operations. Industrial verticals in Germany's manufacturing belt are displacing spot hardware purchases with five-year connectivity subscriptions. This reconfiguration concentrates purchasing power with systems integrators possessing multi-site deployment capabilities.
Fixed LTE Market Segmentation
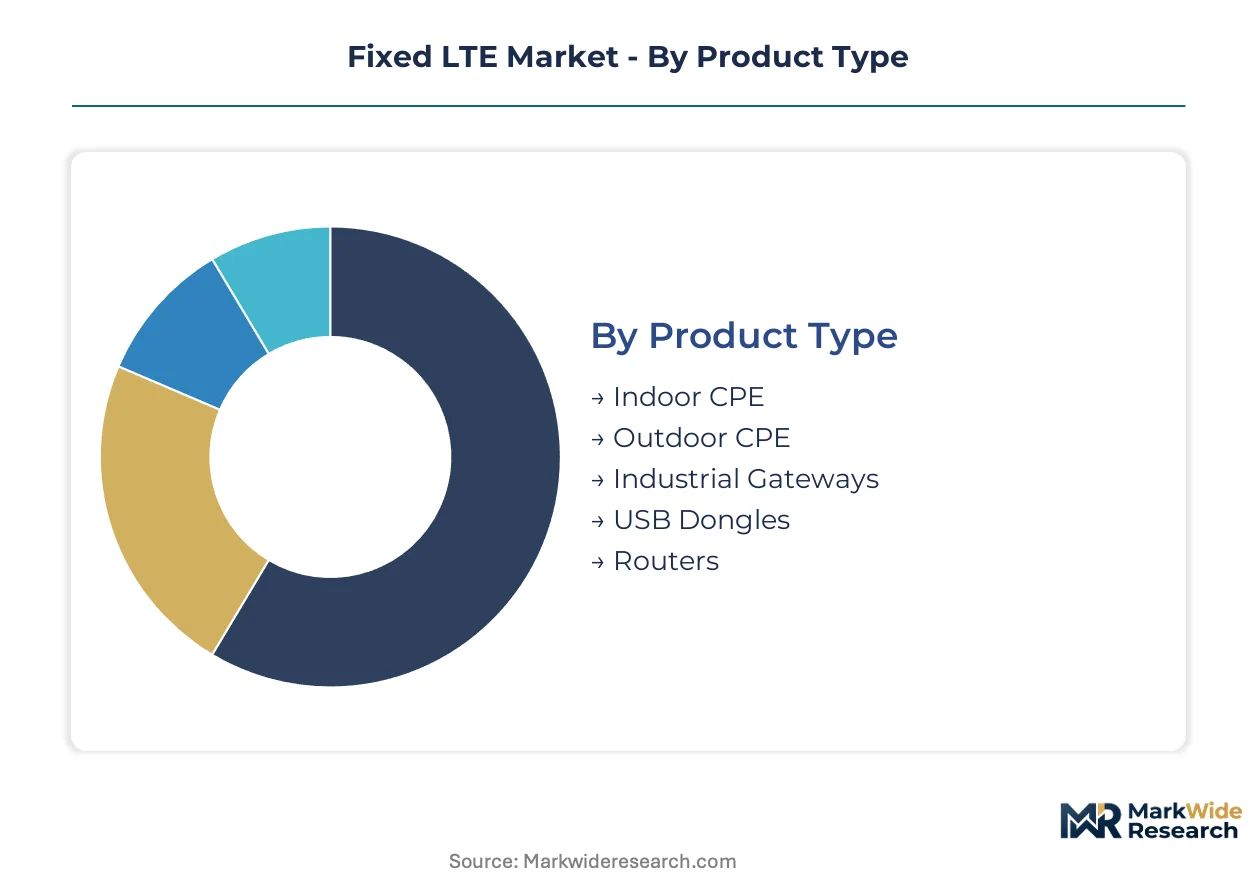
Fixed LTE equipment segments diverge sharply in service intensity and margin structure. Indoor CPE generates high replacement frequency from consumer churn, while industrial gateways demand multi-year field support contracts that reshape vendor economics.
Product Type:
After-sales service intensity varies dramatically across hardware form factors, with outdoor installations commanding premium maintenance contracts and indoor units driving volume-driven warranty programs.
- Indoor CPE:Wall-mounted residential units with integrated antennas operate in climate-controlled environments. Demand concentrates in suburban United States census blocks where the FCC's Rural Digital Opportunity Fund subsidizes carrier deployment. Price compression has eroded hardware margins below outdoor equivalents.
- Outdoor CPE:Pole-mounted or rooftop installations feature hardened enclosures rated for IP67 environmental exposure. Brazilian agribusiness operators deploy these for precision farming connectivity, prioritizing weather resistance over raw throughput. Field service requirements sustain recurring revenue streams for installation partners.
- Industrial Gateways:Ruggedized units with edge computing capabilities serve utility substation automation. German grid operators specify these for distributed energy resource management under EU Green Deal efficiency mandates.
- USB Dongles:Plug-in modems for laptop connectivity represent a declining form factor as embedded cellular becomes standard in enterprise devices.
- Routers:Multi-port CPE with Ethernet switching targets small office deployments where wired backhaul remains unavailable.
By volume, Indoor CPE leads. By growth pace, Industrial Gateways is gaining share fastest.
Technology:
Modem category selection directly determines achievable throughput tiers and corresponding average selling price bands across carrier portfolios.
- LTE Cat 4:Legacy 150 Mbps peak throughput modems dominate installed base depreciation cycles. Indian rural broadband programs still specify these for cost-sensitive village connectivity under TRAI-mandated universal service obligations.
- LTE Cat 6:300 Mbps capable with carrier aggregation supports mainstream residential fixed wireless. AT&T's FirstNet spectrum refarming prioritizes this tier for rural residential expansion.
- LTE Cat 12:600 Mbps peak throughput with 3x carrier aggregation anchors premium tier offerings. Samsung's in-house semiconductor production enables cost-competitive Cat 12 modem supply for outdoor CPE manufacturers.
- LTE Cat M1:Narrowband IoT-optimized for low-power sensor backhaul serves smart grid AMI deployments with decade-long battery life specifications.
- LTE Cat NB1:Ultra-narrowband variant for minimal data telemetry supports agricultural soil moisture monitoring networks.
Cat 6 dominates current shipment volumes, though Cat 12 climbs the fastest as carriers refarm 3G spectrum for higher throughput tiers.
Application:
Use case diversity spans consumer entertainment through critical infrastructure, with diverging reliability requirements and procurement authority structures.
- Broadband Access:Residential internet substitution for unserved fiber areas represents the core volume application. United States carriers target 50-300 Mbps service tiers using Massive MIMO cell site upgrades.
- Smart Grids:Utility distribution automation commands sub-50ms latency for protection relay coordination. FERC Order 2222 compliance drives investment in distributed energy resource communications.
- Security Surveillance:Video backhaul for remote facilities requires consistent uplink throughput. Brazilian mining operations deploy hardened outdoor CPE for pit perimeter monitoring.
- Remote Monitoring:Industrial telemetry for oil and gas pipeline infrastructure operates in explosive atmosphere zones requiring ATEX-certified CPE variants.
- Public Wi-Fi:Municipal hotspot backhaul serves transportation hubs and parks with bandwidth-shaped subscriber access.
Broadband Access generates the largest equipment volume. Smart Grids shows the steepest expansion trajectory as grid modernization accelerates.
End User:
Procurement sophistication ranges from centralized carrier supply chains through fragmented institutional purchasing with extended evaluation cycles.
- Telecom Operators:Tier-1 carriers consolidate CPE procurement through multi-year framework agreements with installation and logistics bundling. FCC Rural Digital Opportunity Fund compliance requirements shape technical specifications.
- Enterprises:Campus-wide private LTE deployments using CBRS shared spectrum bypass carrier intermediation. Manufacturing verticals in Germany's industrial belt favor managed service contracts over spot hardware acquisition.
- Governments:Federal and state agencies specify FIPS 140-2 cryptographic compliance for public safety communications infrastructure.
- Educational Institutions:K-12 districts and universities deploy fixed LTE for bus Wi-Fi and remote campus connectivity under E-Rate subsidy programs.
- Internet Service Providers:Competitive local exchange carriers and wireless ISPs purchase unbranded CPE for resale under private label programs.
Telecom Operators account for the dominant share of volume procurement. Enterprises are expanding most quickly as private network deployments proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese equipment manufacturers supply fixed LTE infrastructure to carriers across Brazil, Germany, India, and the United States, creating a trade corridor that shapes regional deployment timelines and regulatory compliance requirements.
United States
Rural broadband gaps and FirstNet public safety spectrum refarming drive carrier investment in fixed wireless alternatives. The FCC's Rural Digital Opportunity Fund redirects subsidy capital toward unserved census blocks, compressing customer acquisition costs in economically marginal territories. Texas and the Mountain West host dense concentrations of outdoor CPE deployments targeting agricultural and remote residential connectivity.
Brazil
Precision agriculture mechanization and agribusiness automation generate unmet demand for weather-hardened outdoor CPE with edge computing capabilities. ANVISA certification requirements for industrial telecommunications equipment create compliance barriers for non-local manufacturers. São Paulo state and the Mato Grosso grain belt concentrate deployment of substation monitoring gateways for distributed energy resource management.
Germany
Grid modernization under EU Green Deal efficiency mandates accelerates industrial gateway procurement for utility sector automation. The Radio Equipment Directive's CE marking requirements and energy efficiency standards favor next-generation CPE with sleep-mode power optimization. Bavaria's manufacturing belt and North Rhine-Westphalia's industrial clusters displace spot hardware purchases with five-year managed connectivity subscriptions.
India
Cost-sensitive village connectivity programs under TRAI-mandated universal service obligations sustain demand for legacy LTE Cat 4 modems in rural broadband initiatives. The Department of Telecommunications spectrum allocation frameworks shape carrier refarming timelines from 3G to LTE carriers. Karnataka's technology corridor and Maharashtra's industrial zones concentrate enterprise private LTE deployments using shared spectrum frameworks.
China
Domestic equipment production and MIIT spectrum coordination standards enable rapid infrastructure deployment cycles for fixed wireless broadband. GB standards for radio equipment and dual carbon goals influence CPE energy efficiency specifications in procurement tenders. The Yangtze River Delta and Pearl River Delta manufacturing clusters supply Massive MIMO baseband units and carrier aggregation-enabled modems to global carrier markets.
Fixed LTE Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages separate volume leaders from niche positioning. Infrastructure supply concentrates among vertically integrated equipment vendors possessing end-to-end radio access network portfolios, while modem semiconductor production anchors competitive differentiation in throughput tier offerings. Three archetypes dominate: integrated infrastructure vendors with captive silicon production, carrier-affiliated equipment distributors leveraging spectrum holdings, and specialized CPE manufacturers focused on hardened outdoor enclosures. Capacity expansion and strategic technology licensing constitute the primary competitive moves reshaping procurement shortlists.
Among integrated infrastructure vendors, Huawei Technologies and ZTE Corporation occupy positions exemplifying the vertically integrated archetype with end-to-end equipment portfolios. Samsung Electronics anchors the semiconductor-captive tier through in-house LTE modem production capabilities. AT&T represents the carrier-affiliated distributor archetype, extending spectrum holdings into fixed wireless residential service bundling. These three entities illustrate the competitive fault lines between equipment manufacturing, silicon supply, and service distribution that structure procurement decisions across rural broadband and enterprise vertical markets.
| Leading Market Players |
|---|
| Huawei Technologies |
| AT&T |
| Cisco Systems |
| Samsung Electronics |
| Netgear |
| CommScope Holding Company |
| Sagemcom |
| ZTE Corporation |
| Telrad Networks |
| Others |
Supply & Pricing Matrix
Taiwan-based foundry concentration for LTE modem fabrication determines both the three-tier pricing spread across Cat 4, Cat 6, and Cat 12 equipment tiers and the elongated supply chain configuration favoring integrated vendors with captive semiconductor capacity.
Pricing Analysis
The Cat 12-to-Cat 4 technology-generation pricing gap spans approximately 3:1 in hardware cost, with premium Cat 12 outdoor CPE commanding higher margins through carrier aggregation capabilities while legacy Cat 4 units face commoditization in Indian village connectivity programs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FCC Part 27 authorization and CE marking under the EU Radio Equipment Directive add compliance cost layers that widen spreads. Price erosion runs through indoor CPE as volume procurement by United States carriers under the Rural Digital Opportunity Fund compresses hardware margins. Telecom operators exhibit lowest price sensitivity due to subsidy-backed deployment economics, while competitive local exchange carriers in spot hardware markets face acute margin pressure.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements for CPE manufacturers sourcing from Taiwan, South Korea, and China, straining working capital for specialized outdoor enclosure vendors without balance sheet depth. Modem semiconductor fabrication draws from TSMC and Samsung Foundry capacity, with GaAs power amplifiers and ceramic filter components sourced from Japanese and Chinese specialty suppliers. Single-source vulnerability concentrates in 7nm and 5nm LTE baseband production, where geopolitical disruption risk looms over equipment availability timelines. Distribution runs through carrier procurement frameworks with installation and logistics bundling, though enterprise verticals in Germany increasingly favor five-year managed service subscriptions that displace spot hardware purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fixed LTE market sits at a platform-economics inflection where Open RAN interoperability mandates and virtualized baseband processing dissolve single-vendor lock-in, creating ecosystem entry points for modular CPE specialists and cloud-native software vendors.
For Market Incumbents: Build switching-cost moats through multi-year managed service contracts bundling CPE, installation, and network operations, as German manufacturing verticals demonstrate preference for subscription over spot purchase. Deepen backward integration into LTE modem semiconductor production to secure supply against Taiwan foundry concentration risk. Prioritize FCC Part 27 and CE marking certification concurrency to qualify for dual-continent carrier procurement shortlists under Rural Digital Opportunity Fund and EU Green Deal alignment requirements.
For New Entrants and Emerging Players: Brazilian agribusiness precision farming connectivity represents the most penetrable entry point, with unmet demand for weather-hardened outdoor CPE featuring edge computing capabilities and ANVISA certification compliance. CBRS private network deployments in United States manufacturing campuses offer a second white-space target, bypassing carrier intermediation through shared spectrum frameworks. Pursue systems integrator partnerships with multi-site deployment capabilities rather than direct carrier channel competition.
For Investors and Strategic Acquirers: Specialized outdoor CPE manufacturers with hardened enclosure IP and field service network density present the most attractive acquisition target archetype, as recurring installation and maintenance revenue streams reshape vendor economics. Long-term viability hinges on positioning for 5G fixed wireless convergence without stranded LTE asset risk. Monitor FCC spectrum auction timelines and Open RAN interoperability mandate enforcement as inflection indicators for equipment vendor qualification dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | FCC and EU interoperability mandates determine which radio unit and baseband software combinations qualify for operator procurement shortlists. |
| Semiconductor Backward Integration | Samsung's captive LTE modem production enables cost-competitive Cat 12 supply, pressuring pure-play CPE vendors without silicon control. |
| Managed Service Contract Expansion | German industrial verticals displace spot hardware purchases with five-year connectivity subscriptions, concentrating purchasing power with integrators. |
| Dual-Continent Certification Concurrency | Modular CPE designs satisfying both FCC Part 27 and CE marking requirements accelerate market access across United States and EU subsidy programs. |
| CBRS Private Network Deployment | Shared spectrum frameworks enable enterprise verticals to bypass carrier intermediation, creating direct procurement channels for campus-wide fixed LTE. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with carrier procurement executives, CPE manufacturer product managers, RF engineering consultants, and utility sector automation directors; and secondary validation through FCC Rural Digital Opportunity Fund disbursement records, EU Radio Equipment Directive certification databases, TRAI universal service obligation filings, and SEC 10-K equipment revenue disclosures from listed infrastructure vendors. Bottom-up triangulation across carrier deployment announcements and CPE shipment estimates was cross-checked against top-down spectrum licensing data and subsidy allocation frameworks.
Forecast inputs considered technology migration patterns from Cat 4 through Cat 12 modems, spectrum refarming timelines from 3G to LTE carriers, and rural broadband subsidy reallocation under the FCC's accelerated auction schedules. Segmentation dimensions modeled include equipment form factor, modem category, application use case, and end-user procurement archetype across the projection horizon. CAGRs were derived from installed base depreciation cycles and replacement demand elasticity rather than extrapolated shipment trends alone. Massive MIMO densification rates and virtualized baseband adoption curves provided industry-specific forecast anchors.
Practitioners should monitor Taiwan foundry utilization rates, FCC spectrum auction outcomes, and Open RAN interoperability mandate enforcement for early signals of supply constraint or vendor qualification shifts. Forecasts reflect documented assumptions regarding subsidy program continuity and spectrum refarming pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
IP PBX Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Qatar Telecom Market
Telecommunications
Fixed Voice Market
Telecommunications
Hungary ICT Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Global 4G LTE Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
China ICT Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Argentina ICT Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Global Broadband Services Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
Prepaid Communication Market
Telecommunications
Mobile Value-Added Services (MVAS) Market