
 Belgium Telecom Market | 2026-2036
Belgium Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Telecom Market Insights
Belgian fiber infrastructure deployment is rebalancing as regional operators and national incumbents scale gigabit-capable networks across Wallonia and Flanders. Proximus sustains dominant wholesale access through its fiber backbone investments and vectoring technology leadership. Orange Belgium S.A. competes aggressively on converged mobile-fixed bundles, leveraging its 5G standalone network to capture enterprise subscribers. Telenet Group Holding NV anchors cable-based gigabit delivery in Flanders while navigating wholesale regulatory obligations.
Belgium Telecom encompasses wired and wireless communication services delivering voice, data, and video transmission across fixed and mobile infrastructures, operating through technologies ranging from GPON fiber with symmetrical 1 Gbps throughput to 5G NR in sub-6 GHz and mmWave bands for ultra-reliable low-latency applications. Mobile Services generate the largest revenue pool through postpaid ARPU stability, while Fiber Optic infrastructure represents the fastest-expanding technology segment as operators replace copper DSL plant. Business Customers command premium pricing for SLA-guaranteed connectivity, whereas Bundled Offers concentrate residential churn reduction through quadruple-play packaging.
BIPT, the Belgian postal and telecommunications regulator, enforces wholesale access pricing and net neutrality compliance that shapes retail margin structures for all operators. EU Green Deal connectivity targets and national digital sovereignty frameworks mandate open fiber access and energy-efficient network equipment standards. Stakeholders must monitor spectrum refarming decisions and BIPT's fiber co-investment rulings to calibrate capital allocation between 5G densification and FTTP overbuild strategies.
Market Dynamics
Belgian telecom infrastructure faces structural pressure from BIPT-mandated wholesale fiber access rules that compel dominant operators to open their networks to retail competitors, compressing margins while accelerating nationwide gigabit coverage targets.
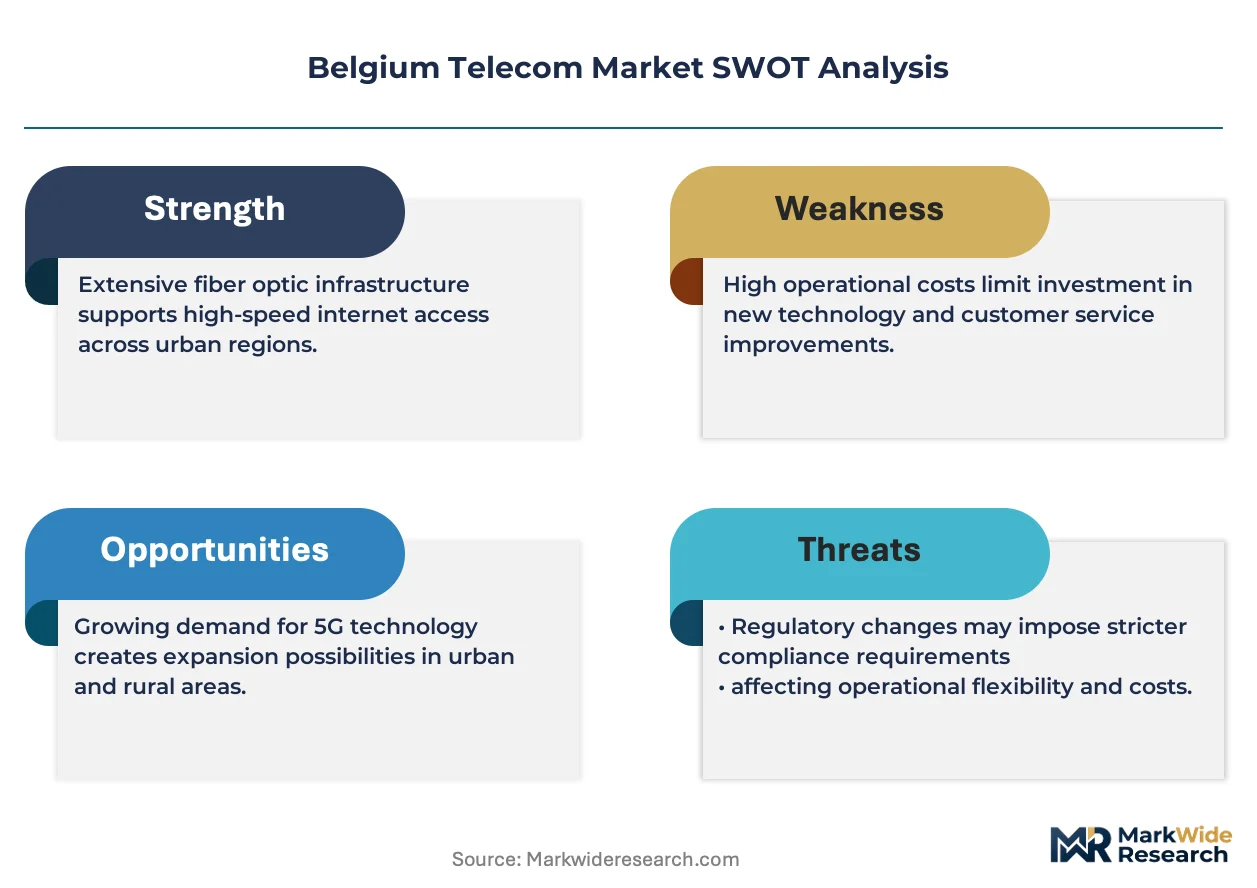
Growth Catalysts
- EU Gigabit Infrastructure Act:Binding connectivity deadlines force operators to prioritize fiber-to-the-premises over legacy copper, unlocking state co-investment funds for rural Wallonia deployments.
- Enterprise cloud migration:Belgian financial services and logistics clusters demand symmetrical gigabit connectivity, driving premium ARPU growth in Brussels-Capital corridor data centers.
- 5G standalone architecture:Sub-6 GHz and mmWave network slicing enables ultra-reliable low-latency services for industrial automation in Flanders manufacturing zones.
Market Restraints
- Copper retirement cost burden:Legacy DSL infrastructure decommissioning requires substantial labor and disposal expenditure before fiber revenue materializes.
- Wholesale access price compression:BIPT-regulated fiber unbundling rates limit retail pricing power for vertically integrated operators.
- Permitting fragmentation:Municipal-level civil engineering authorizations across three regional governments delay trenching timelines.
Strategic Opportunities
- Wallonia fiber gap:Lower penetration rates in southern provinces create first-mover advantage for alternative network builders with municipal partnership models.
- Converged fixed-mobile bundles:Quadruple-play packaging combining 5G mobile, fiber broadband, television, and fixed voice reduces residential churn.
- EU Green Deal network standards:Energy-efficient equipment mandates favor operators with modern GPON and XGS-PON architectures over legacy DSL power consumption.
Industry Challenges
- Fiber splicing technician scarcity:Specialized workforce shortages delay activation timelines for new premises passed.
- Legacy billing system integration:Migration from copper-centric OSS/BSS platforms to fiber-native provisioning creates customer service friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Telecom Market |
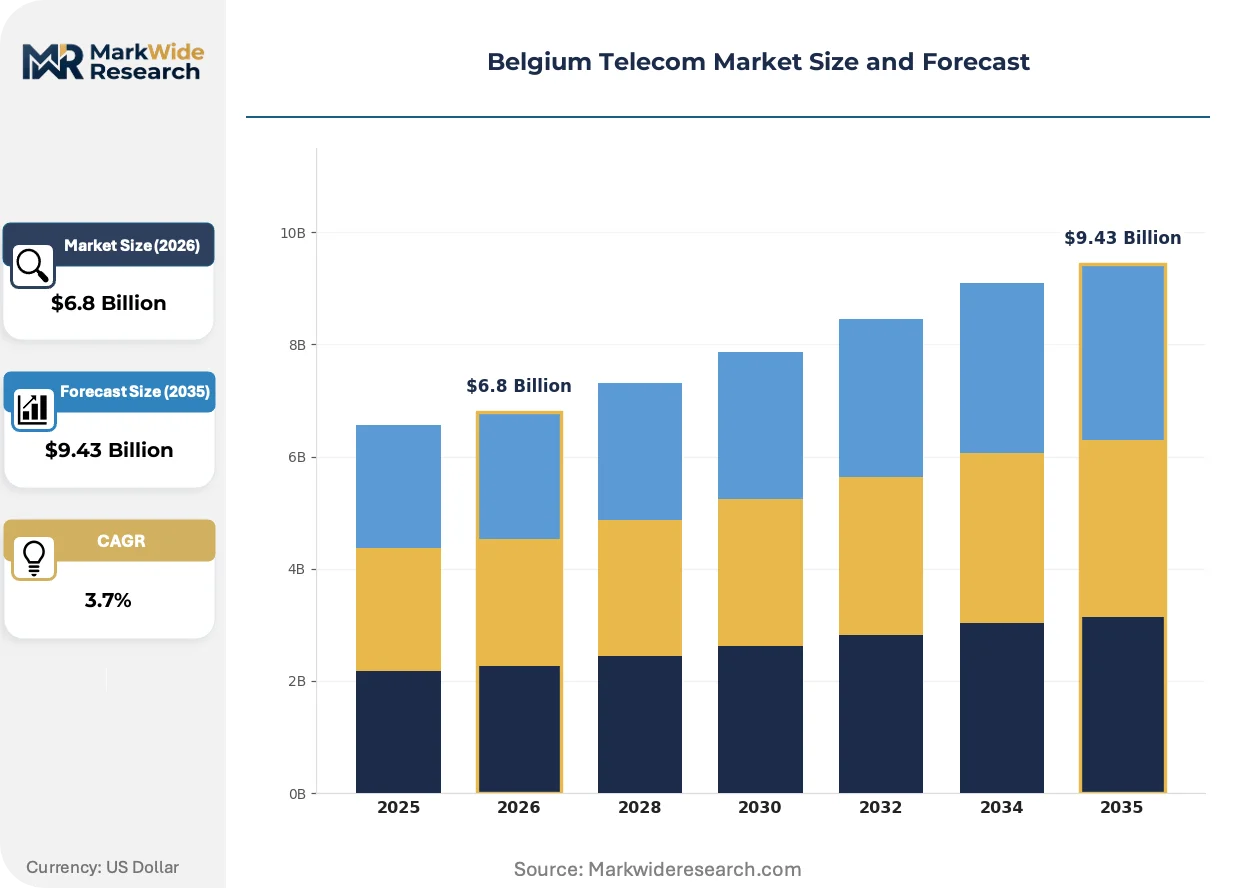
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Internet Services, TV Services, VoIP Services End User: Residential Customers, Business Customers, Government Agencies, Educational Institutions Technology: 5G, Fiber Optic, DSL, Cable Pricing Model: Prepaid Plans, Postpaid Plans, Bundled Offers, Unlimited Data Plans |
| Companies Covered | Proximus, Orange Belgium S.A., Telenet Group Holding NV, Digi Communications N.V, VOO, Base, Scarlet, EDPnet, Destiny, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Telecom Market Trends and Innovations
Belgian operator strategies pivot toward infrastructure sharing and software-defined automation as regulatory pressure and capital efficiency demands reshape deployment economics.
XGS-PON fiber technology is rewriting access network economics by delivering symmetrical 10 Gbps throughput over existing optical distribution infrastructure. Proximus and regional alt-nets are accelerating XGS-PON overlays in Flanders urban cores to capture enterprise premium pricing. The technology is compressing the viable lifespan of vectoring-enhanced VDSL2 and forcing wholesale access renegotiations.
BIPT's fiber co-investment rulings under EU electronic communications framework mandate risk-sharing mechanisms for rural deployments. Operators must publish transparent reference offers for dark fiber and duct access, enabling retail competitors to enter without parallel infrastructure builds. Wallonia municipalities are leveraging these rules to attract infrastructure funds from European Investment Bank facilities.
Enterprise procurement now favors multi-year connectivity contracts with guaranteed SLA tiers over transactional broadband subscriptions. System integrators and managed service providers are displacing direct operator relationships in mid-market manufacturing and healthcare verticals. This pattern concentrates in Brussels-Capital and Antwerp port logistics clusters where uptime penalties justify premium pricing.
Belgium Telecom Market Segmentation
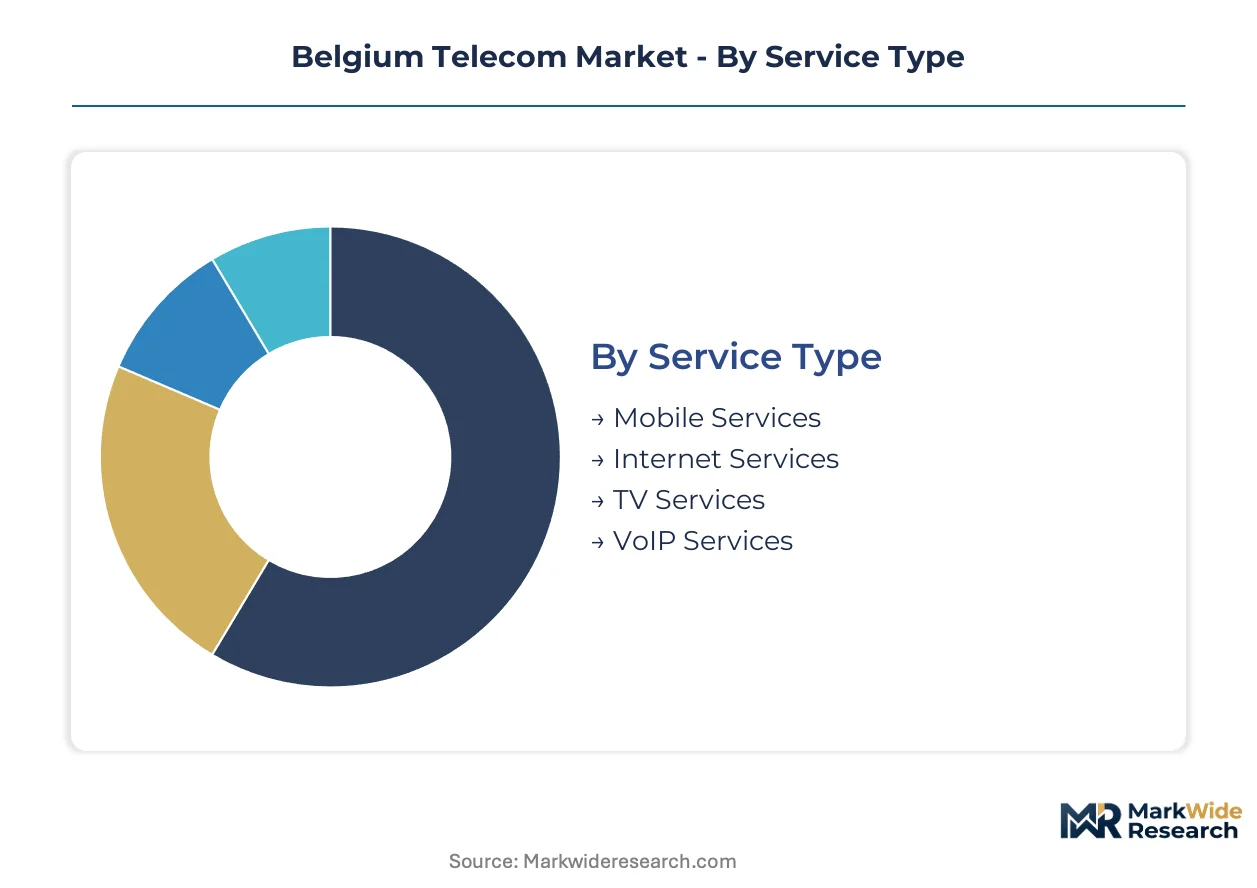
Belgian telecom segmentation reveals how BIPT regulatory categories and EU electronic communications framework obligations shape operator investment priorities across service tiers. Distinct compliance burdens apply to wholesale versus retail offerings, while technology migrations trigger asymmetric capital allocation between legacy copper retirement and fiber overbuild strategies.
Service Type:
Mobile Services and Internet Services carry heavier BIPT net neutrality documentation requirements than broadcast-oriented TV Services, with VoIP Services falling under overlapping electronic communications and data protection frameworks.
- Mobile Services:Postpaid subscriptions with guaranteed SLA tiers dominate enterprise procurement in Brussels-Capital financial districts. Proximus and Orange Belgium compete for ARPU stability through 5G standalone network slicing contracts with logistics clusters.
- Internet Services:Symmetrical gigabit fiber connectivity commands premium positioning in Flanders data center corridors. XGS-PON overlays are displacing vectoring-enhanced VDSL2 as operators accelerate copper retirement timelines.
- TV Services:IPTV delivery over GPON infrastructure integrates with quadruple-play bundling strategies.
- VoIP Services:Cloud-based unified communications face GDPR call recording compliance obligations.
Leading the category by volume: Mobile Services. Growing fastest: Internet Services.
End User:
Business Customers and Government Agencies impose stringent procurement certification requirements, while Residential and Educational segments operate under lighter transactional frameworks.
- Residential Customers:Quadruple-play packaging concentrates churn reduction investments from Telenet and Orange Belgium. Converged fixed-mobile bundles with television and fixed voice anchor retention in Flanders urban cores.
- Business Customers:SLA-guaranteed connectivity with uptime penalties justifies premium pricing in Antwerp port logistics and Brussels-Capital manufacturing zones. Multi-year contracts displace transactional subscriptions as system integrators capture mid-market relationships.
- Government Agencies:Public procurement mandates favor operators with BIPT-certified wholesale access offers.
- Educational Institutions:Bulk connectivity tenders prioritize cost efficiency over latency-sensitive specifications.
Residential Customers generate the largest revenue pool. Business Customers deliver the steepest expansion trajectory as cloud migration accelerates.
Technology:
Fiber Optic deployments trigger EU Green Deal equipment efficiency standards, while 5G infrastructure faces BIPT spectrum utilization audits and DSL confronts mandatory retirement timelines.
- Fiber Optic:GPON and XGS-PON architectures deliver symmetrical 1-10 Gbps throughput with energy consumption profiles that satisfy EU Green Deal mandates. Wallonia municipalities leverage BIPT co-investment rulings to attract European Investment Bank rural deployment funds.
- 5G:Sub-6 GHz and mmWave network slicing enables ultra-reliable low-latency services for Flanders industrial automation. BIPT spectrum refarming decisions shape densification economics.
- DSL:Legacy copper plant faces decommissioning cost burdens before fiber revenue materializes.
- Cable:DOCSIS 3.1 gigabit delivery anchors Telenet's Flanders positioning amid wholesale regulatory obligations.
Fiber Optic claims the fastest volume growth. 5G shows the most rapid value expansion through enterprise slicing contracts.
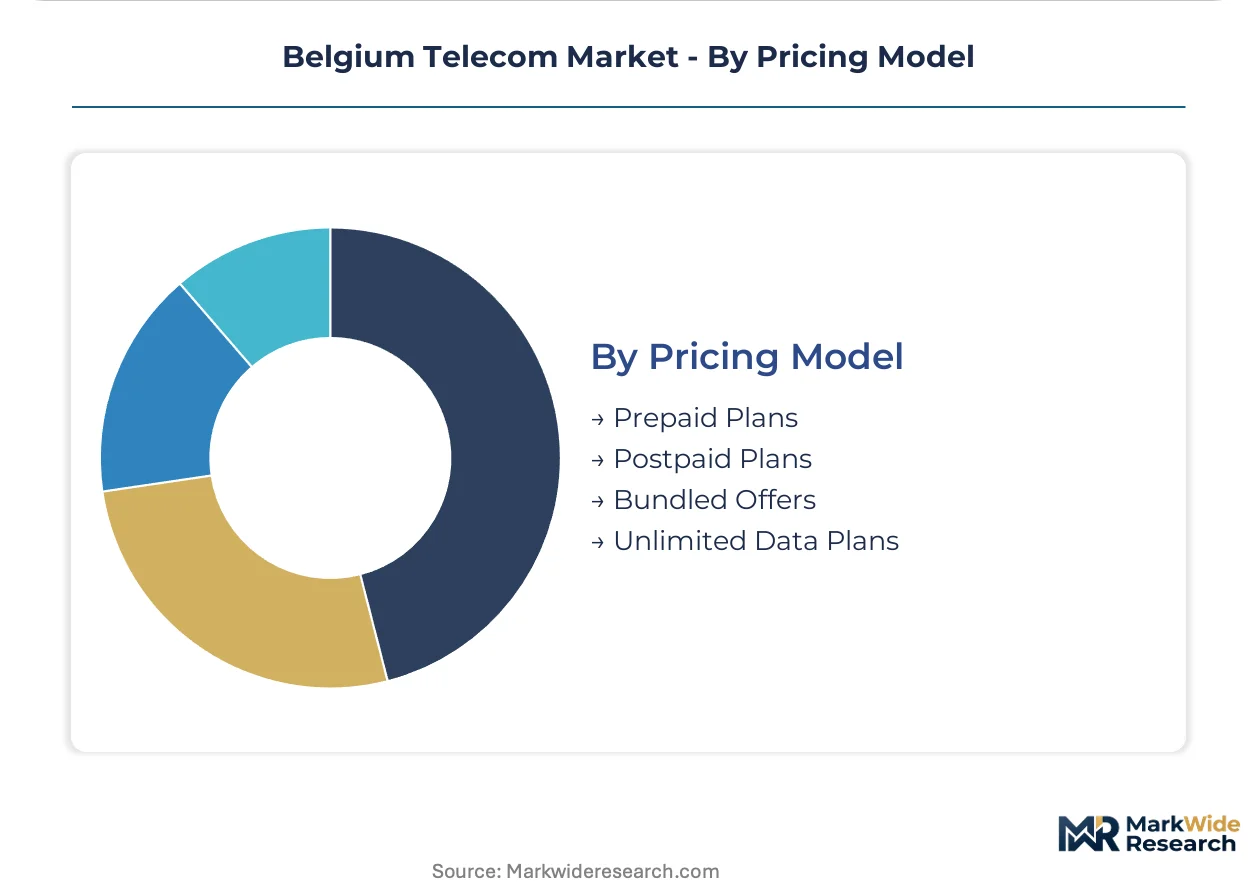
Pricing Model:
Postpaid Plans and Bundled Offers require complex BIPT wholesale cost allocation transparency, while Prepaid and Unlimited Data Plans operate under simpler retail margin structures.
- Postpaid Plans:Subscription stability underpins operator cash flow predictability across mobile and fixed segments. ARPU defense depends on device financing integration and loyalty program mechanics.
- Bundled Offers:Quadruple-play packaging reduces residential churn through service consolidation. Proximus leverages fiber backbone dominance to anchor converged pricing.
- Prepaid Plans:Low-margin acquisition tool for price-sensitive demographic entry.
- Unlimited Data Plans:Traffic management disclosures face BIPT net neutrality scrutiny.
Postpaid Plans dominate revenue contribution. Bundled Offers are climbing the fastest as convergence strategies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in the Campine region anchor Belgium's fiber cable manufacturing supply chain, connecting raw material availability to infrastructure deployment economics across the country's three linguistic regions.
Brussels-Capital Region
Financial services clusters and EU institutional headquarters drive enterprise connectivity demand with stringent SLA requirements. BIPT enforces wholesale access pricing transparency that shapes retail competition dynamics. The European Quarter and Zaventem airport logistics corridor concentrate premium fiber subscriptions for data center interconnection.
Flanders
Port of Antwerp manufacturing zones and Ghent-Leuven technology corridors generate industrial automation demand for 5G network slicing. EU Gigabit Infrastructure Act timelines accelerate municipal co-investment frameworks for rural fiber extensions. Eindhoven-Antwerp axis data centers anchor cross-border low-latency connectivity contracts.
Wallonia
Lower fiber penetration rates create first-mover opportunities for alternative network builders with municipal partnership structures. BIPT fiber co-investment rulings unlock European Investment Bank facilities for rural deployment gaps. Liège logistics platforms and Charleroi aerospace clusters demand symmetrical gigabit connectivity for cloud migration.
German-speaking Community
Small population base limits standalone infrastructure economics, favoring cross-border service integration with Luxembourg and German networks. Regional development agencies leverage EU structural funds for broadband universal service obligations. Eupen manufacturing SMEs access fiber through wholesale arrangements with neighboring operators.
Belgium Telecom Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue infrastructure-light wholesale resale models and municipal partnership structures. The market exhibits moderate concentration with three vertically integrated operators controlling fixed and mobile access infrastructure. Strategic archetypes include fiber backbone incumbents leveraging vectoring technology, cable operators navigating wholesale regulatory obligations, and mobile-first challengers converging into fixed-line bundles. Dominant competitive moves center on XGS-PON capacity overlays and quadruple-play packaging to reduce residential churn.
Within the incumbent tier, Proximus anchors wholesale fiber access through backbone investments, while Orange Belgium S.A. exemplifies mobile-first convergence into fixed-line enterprise contracts. Telenet Group Holding NV occupies the cable-delivery position in Flanders with DOCSIS 3.1 gigabit infrastructure. These three entities represent the primary competitive anchors shaping BIPT-regulated market dynamics.
| Leading Market Players |
|---|
| Proximus |
| Orange Belgium S.A. |
| Telenet Group Holding NV |
| Digi Communications N.V |
| VOO |
| Base |
| Scarlet |
| EDPnet |
| Destiny |
| Others |
Pricing and Supply Chain Analysis
XGS-PON fiber technology migration is compressing legacy copper economics while concentrating supply power among operators with modernized optical distribution networks. Belgian wholesale access rules simultaneously constrain retail pricing freedom and redirect capital toward fiber-native infrastructure investments.
Pricing Analysis
SLA-backed service bundling separates premium enterprise connectivity from unbundled residential broadband tiers in Belgian operator portfolios. Three-tier pricing structure across premium SLA-guaranteed, standard best-effort, and economy wholesale-resale levels reflects BIPT-regulated fiber unbundling rates and vectoring technology depreciation schedules. Pricing pressure stems from municipal co-investment frameworks diluting first-mover returns in rural Wallonia. Residential quadruple-play subscribers show highest price sensitivity; financial services clusters in Brussels-Capital demonstrate lowest elasticity due to uptime penalty structures.
Supply Chain Analysis
EU Green Deal local-content mandates for energy-efficient network equipment are reshaping Belgian operator sourcing toward GPON and XGS-PON vendors with CE-marked sustainability certifications. Optical fiber draws from Corning and Prysmian manufacturing footprints in Germany and France; active electronics rest on semiconductor supply from Taiwan and South Korea. Single-source vulnerability in specialized fiber splicing technician labor pools creates activation bottlenecks. Distribution runs through vertically integrated operator procurement teams and wholesale dark fiber exchanges regulated by BIPT reference offers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgian telecom infrastructure is consolidating around fiber backbone scale as BIPT wholesale obligations and EU Gigabit Infrastructure Act deadlines force sub-scale operators toward acquisition or exit.
For Market Incumbents: Hedge copper retirement cost exposure through accelerated XGS-PON overlays in Flanders urban cores before legacy DSL decommissioning liabilities peak. Secure fiber co-investment partnerships with Wallonia municipalities to preempt alt-net first-mover claims in underserved provinces. Vertical integration into specialized splicing workforce training reduces activation timeline risk. For New Entrants and Emerging Players: Digital wholesale resale platforms offer lowest-capital entry into Belgian enterprise connectivity without parallel infrastructure builds. Target mid-market manufacturing clusters in Liège and Charleroi with managed service wrapper models displacing direct operator relationships. Municipal partnership structures in southern provinces unlock European Investment Bank facility access. For Investors and Strategic Acquirers: Re-rating potential sits with regional alt-nets possessing Wallonia fiber co-investment rulings and municipal anchor tenancy agreements given EU rural connectivity fund flows. Long-term viability centers on symmetrical gigabit penetration rates exceeding copper replacement thresholds. Watch BIPT spectrum refarming announcements as 5G standalone densification capex inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| XGS-PON Network Overlay | Proximus and regional operators capture enterprise premium pricing with symmetrical 10 Gbps throughput. |
| Wallonia Municipal Partnership | Alternative network builders secure European Investment Bank facilities for rural fiber deployment gaps. |
| 5G Standalone Network Slicing | Orange Belgium and Proximus enable ultra-reliable low-latency contracts with Flanders manufacturing zones. |
| Quadruple-Play Bundle Convergence | Telenet and Orange Belgium reduce residential churn through consolidated mobile-fixed-television-voice packaging. |
| Specialized Workforce Development | Operators mitigate fiber splicing technician scarcity delaying new premises activation timelines. |
Research Methodology
Regulatory filings from BIPT, European Commission electronic communications directives, and operator wholesale reference offers formed the secondary backbone for market sizing. Primary interviews with network infrastructure planners, enterprise procurement managers at Brussels-Capital financial services clusters, and municipal digital officers in Wallonia complemented documentary sources. Bottom-up premises-passed estimates and top-down revenue aggregation were triangulated against EU Gigabit Infrastructure Act coverage targets.
Historical fiber deployment curves and mobile ARPU trendlines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end-user category, access technology, and regional regulatory cluster. CAGRs were derived from infrastructure investment schedules and subscriber migration assumptions. Enterprise cloud connectivity demand curves and BIPT co-investment ruling implementation timelines served as industry-specific forecast inputs.
The model holds under stable BIPT wholesale pricing enforcement and EU structural fund disbursement continuity; deviation in spectrum refarming timelines or municipal permitting fragmentation would shift fiber penetration trajectories. Forecasts reflect documented assumptions about copper retirement cost curves and enterprise SLA premium sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Hosted PBX Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
Global Relay Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Mexico Telecom Market
Telecommunications
Algeria Telecom Market
Telecommunications
Tetra Terminals Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
5G Monetization Market
Telecommunications
Finland Telecom Market
Telecommunications
Russia ICT Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market