
 Germany Critical Communication Market | 2026-2036
Germany Critical Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Critical Communication Market Foresight
A shift from single-source government contracts to multi-vendor framework agreements is pivoting procurement dynamics across German critical communication infrastructure. Motorola Solutions leverages its installed base in BDBOS terrestrial trunked radio networks to sustain long-term service revenue. Thales Group competes through cybersecurity-hardened dispatch architectures. Multitone Elektronik International GmbH anchors niche healthcare alerting segments where compliance requirements favor specialized domestic suppliers.
Critical communication encompasses mission-voice and narrowband data systems engineered to 99.999% availability standards with sub-300-millisecond call setup latency, serving first responders and industrial control rooms where commercial cellular fallback fails. Terrestrial trunked radio retains dominant installed value across German public safety, though long-term evolution broadband push-to-talk represents the fastest-expanding technology layer as BDBOS evaluates hybrid migration paths. Radio systems command the deepest replacement cycle visibility, while accessories generate recurring margin pools through battery and handset refresh programs tied to fleet standardization mandates.
KBA type-approval requirements shape automotive emergency call device specifications, while BDBOS federal procurement rules and EU Cybersecurity Act certification constrain vendor eligibility for next-generation public safety networks. The Federal Network Agency spectrum reallocation timeline will determine whether terrestrial trunked radio coexistence or full broadband migration prevails. Stakeholders must monitor BDBOS technology board procurement decisions and BSI critical infrastructure classification updates to align R&D roadmaps with enforceable compliance windows.
Market Dynamics
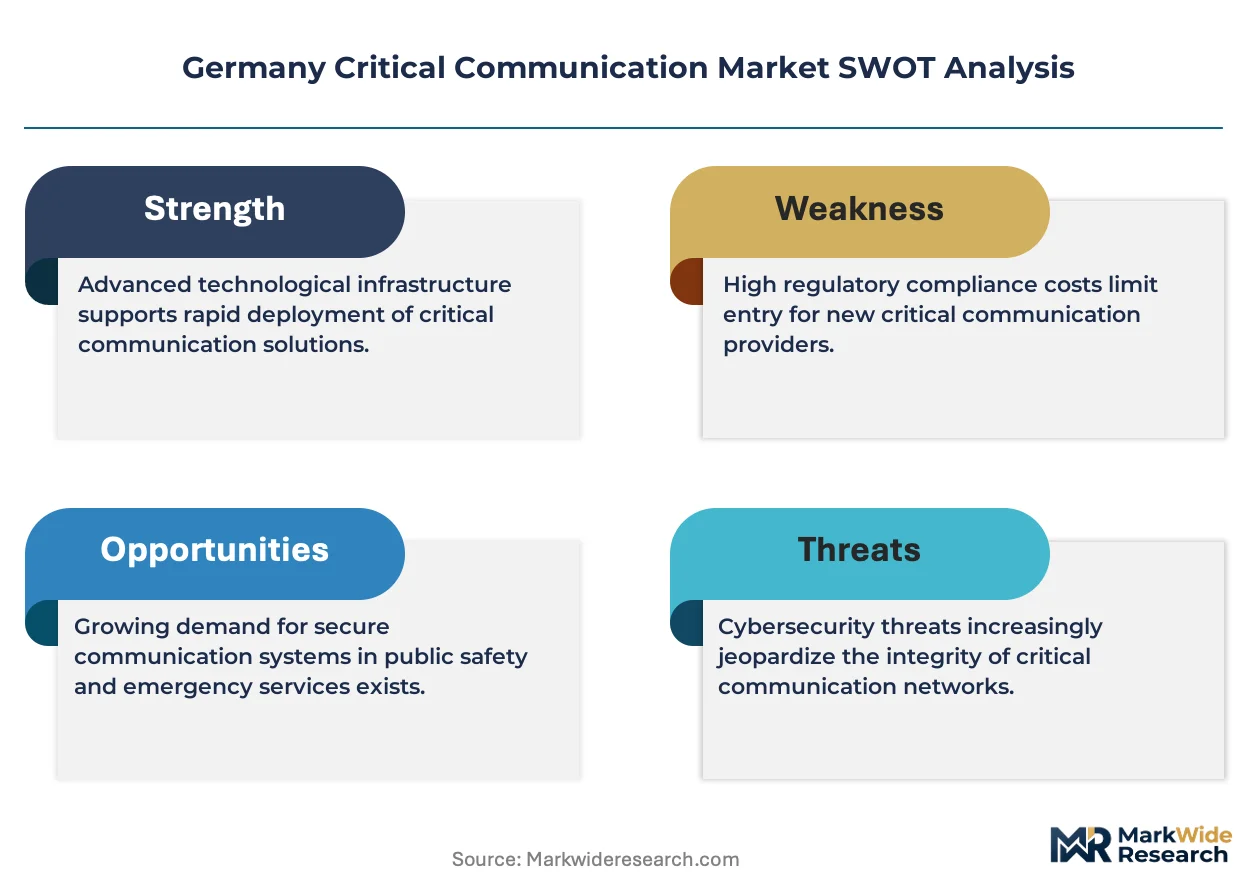
BDBOS federal network modernization mandates are forcing a wholesale migration from narrowband terrestrial trunked radio toward broadband-enabled hybrid architectures, compressing vendor qualification timelines and rewiring procurement authority from state-level agencies to centralized federal frameworks.
Growth Catalysts
- Broadband spectrum reallocation:Federal Network Agency timelines for 700 MHz band release are accelerating infrastructure replacement cycles across Bavarian and North Rhine-Westphalian industrial corridors.
- First-responder consolidation programs:Municipal mergers in Baden-Württemberg and Lower Saxony are consolidating fragmented radio fleets into unified procurement pools requiring interoperable equipment.
- Cybersecurity certification mandates:EU Cybersecurity Act baseline requirements for critical infrastructure are disqualifying uncertified vendors from BDBOS framework eligibility.
Market Restraints
- Semiconductor supply concentration:RF component fabrication dependency on Asian foundries creates 18-24 month lead time volatility for base station chipsets.
- Terrestrial trunked radio sunk costs:Existing BDBOS network investments carry 15-year depreciation schedules that clash with accelerated broadband migration timelines.
- Specialized technician scarcity:TETRA and LTE hybrid maintenance requires dual-certification skill sets concentrated among retiring workforce cohorts.
Strategic Opportunities
- Healthcare alerting vertical expansion:Klinikum Stuttgart and Charité Berlin are mandating nurse-call-to-dispatch integration that exceeds commercial cellular reliability.
- Industrial control room convergence:Chemical processing facilities in Ludwigshafen are merging SCADA alerting with mission-voice systems under BSI critical infrastructure classification.
- Framework agreement aggregation:Multi-vendor BDBOS procurement pools allow specialized accessory suppliers to bypass direct federal qualification barriers.
Industry Challenges
- Dual-mode interoperability testing:Simultaneous TETRA and LTE push-to-talk certification extends product validation cycles by 8-12 months.
- Legacy dispatch console migration:Proprietary CAD system interfaces in Hamburg and Munich emergency control centers resist standardized API adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Critical Communication Market |
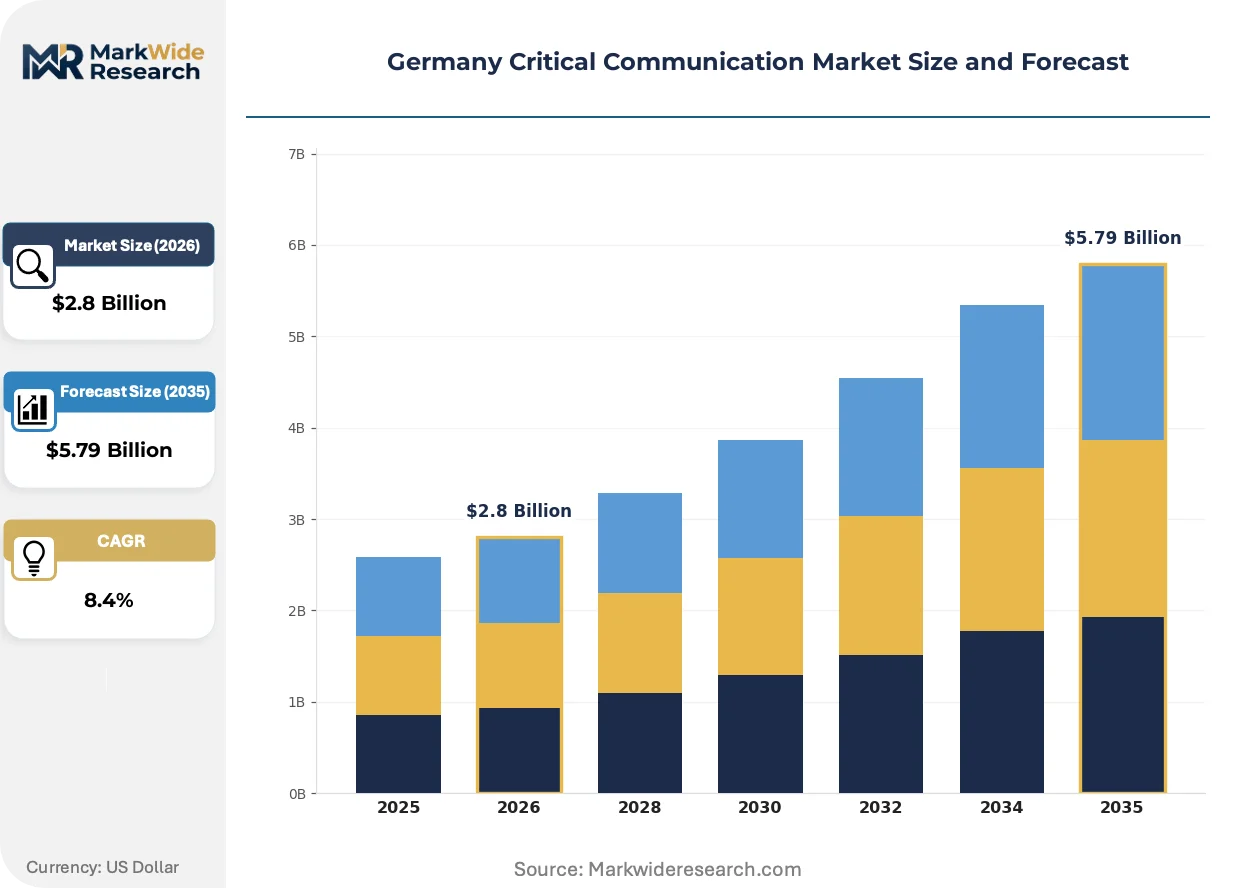
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radio Systems, Network Equipment, Dispatch Consoles, Accessories Technology: Terrestrial Trunked Radio, Digital Mobile Radio, Long-Term Evolution, Broadband Push-to-Talk Application: Public Safety, Transportation, Utilities Management, Manufacturing Plants End User: Emergency Services, Transit Operators, Energy Providers, Industrial Facilities |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Hytera Communications, Multitone Elektronik International GmbH, Thales Group, Ascom Holding, Motorola Solutions, Huawei Technologies, Airbus, Nokia Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Critical Communication Market Shifts & Advancements
Broadband migration is fragmenting the vendor base while compressing equipment refresh cycles. Three concurrent developments are reshaping how mission-critical networks are architected, procured, and maintained across German federal states.
Edge-computing-enabled dispatch nodes are decentralizing call processing from centralized control rooms to localized base station clusters. Bavarian rural police districts are piloting these architectures to maintain sub-300-millisecond latency during fiber backhaul outages. The shift is decentralizing vendor lock-in patterns that historically concentrated maintenance contracts with single-source integrators.
BSI technical guidelines for critical infrastructure cybersecurity are mandating supply chain attestation down to firmware component origins. Industrial control room operators in North Rhine-Westphalia must now document hardware provenance for EU Cybersecurity Act compliance. Chemical processing facilities are responding by pre-qualifying European-manufactured radio terminals ahead of formal mandate deadlines.
Service unbundling is separating hardware procurement from maintenance and software licensing. Municipal purchasers in Baden-Württemberg are negotiating multi-year framework agreements that split terminal acquisition from dispatch software subscriptions. This restructuring is most visible among mid-sized fire departments consolidating across district boundaries where legacy bundled contracts previously locked in single vendors.
Germany Critical Communication Market Segmentation
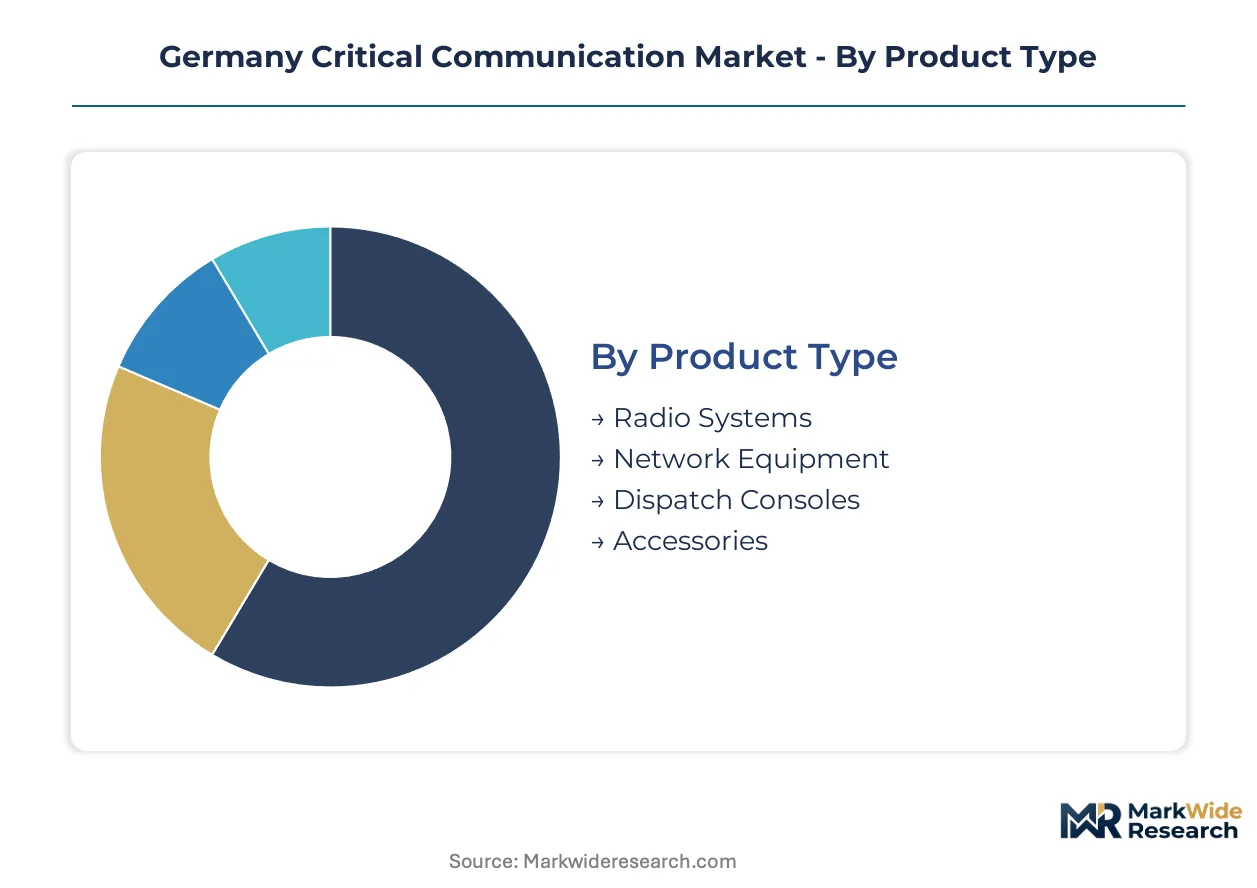
German critical communication procurement follows divergent technical standards across federal states, making segment-level customization essential for vendor positioning. BDBOS framework eligibility varies by product certification depth, while industrial buyers prioritize interoperability over feature breadth.
Product Type:
Customization intensity spans from fully bespoke dispatch consoles to standardized battery accessories, with federal procurement rules favoring modular architectures that permit component-level competitive bidding.
- Radio Systems:Mission-voice terminals engineered to 99.999% availability standards with sub-300-millisecond call setup latency. Bavarian state police and North Rhine-Westphalian fire departments concentrate demand as first-responder consolidation programs mandate fleet standardization across merged districts.
- Network Equipment:Base stations, repeaters, and core network infrastructure forming the physical layer of BDBOS terrestrial trunked radio and hybrid broadband architectures. Demand clusters in industrial corridors where chemical processing facilities under BSI critical infrastructure classification require hardened redundancy.
- Dispatch Consoles:Integrated command-and-control workstations with proprietary CAD system interfaces. Hamburg and Munich emergency control centers drive specifications that resist standardized API adoption.
- Accessories:Batteries, chargers, and handset peripherals generating recurring revenue through refresh programs tied to fleet standardization mandates.
Leading the category by volume: Radio Systems. Growing fastest: Network Equipment as broadband migration accelerates base station replacement cycles.
Technology:
Migration timelines separate mature installed bases from emerging certification pipelines, with vendor qualification costs determining competitive entry barriers across each layer.
- Terrestrial Trunked Radio:TETRA-based narrowband systems retaining dominant installed value across German public safety. Existing BDBOS network investments carry depreciation schedules that constrain accelerated replacement.
- Digital Mobile Radio:Cost-optimized narrowband alternative for non-mission-critical industrial applications. Manufacturing plants in Baden-Württemberg deploy DMR where TETRA certification costs prove prohibitive.
- Long-Term Evolution:Commercial cellular technology adapted for critical infrastructure through hardened core networks and priority access mechanisms. Federal Network Agency 700 MHz band reallocation timelines determine deployment velocity.
- Broadband Push-to-Talk:LTE-based mission-voice service representing the steepest expansion trajectory as BDBOS evaluates hybrid migration paths combining TETRA reliability with broadband data capacity.
Dominant installed base: Terrestrial Trunked Radio. Expanding most quickly: Broadband Push-to-Talk as federal spectrum policy enables hybrid architectures.
Application:
Reliability tiering separates life-safety applications from operational efficiency use cases, with BSI classification determining cybersecurity hardening requirements.
- Public Safety:Police, fire, and emergency medical services requiring guaranteed availability during mass-casualty incidents. Municipal mergers in Lower Saxony consolidate fragmented radio fleets into unified procurement pools.
- Transportation:Rail, aviation, and maritime coordination systems where KBA type-approval shapes automotive emergency call device specifications. Deutsche Bahn regional networks drive interoperability standards.
- Utilities Management:Grid control and pipeline monitoring for electricity, gas, and water distribution. Energy providers face EU Cybersecurity Act baseline requirements for critical infrastructure certification.
- Manufacturing Plants:Process control and worker safety alerting in chemical and automotive production. Ludwigshafen chemical processing facilities merge SCADA alerting with mission-voice systems under BSI classification.
Highest certification barrier: Public Safety. Gaining share fastest: Utilities Management as grid digitization accelerates control system replacement.
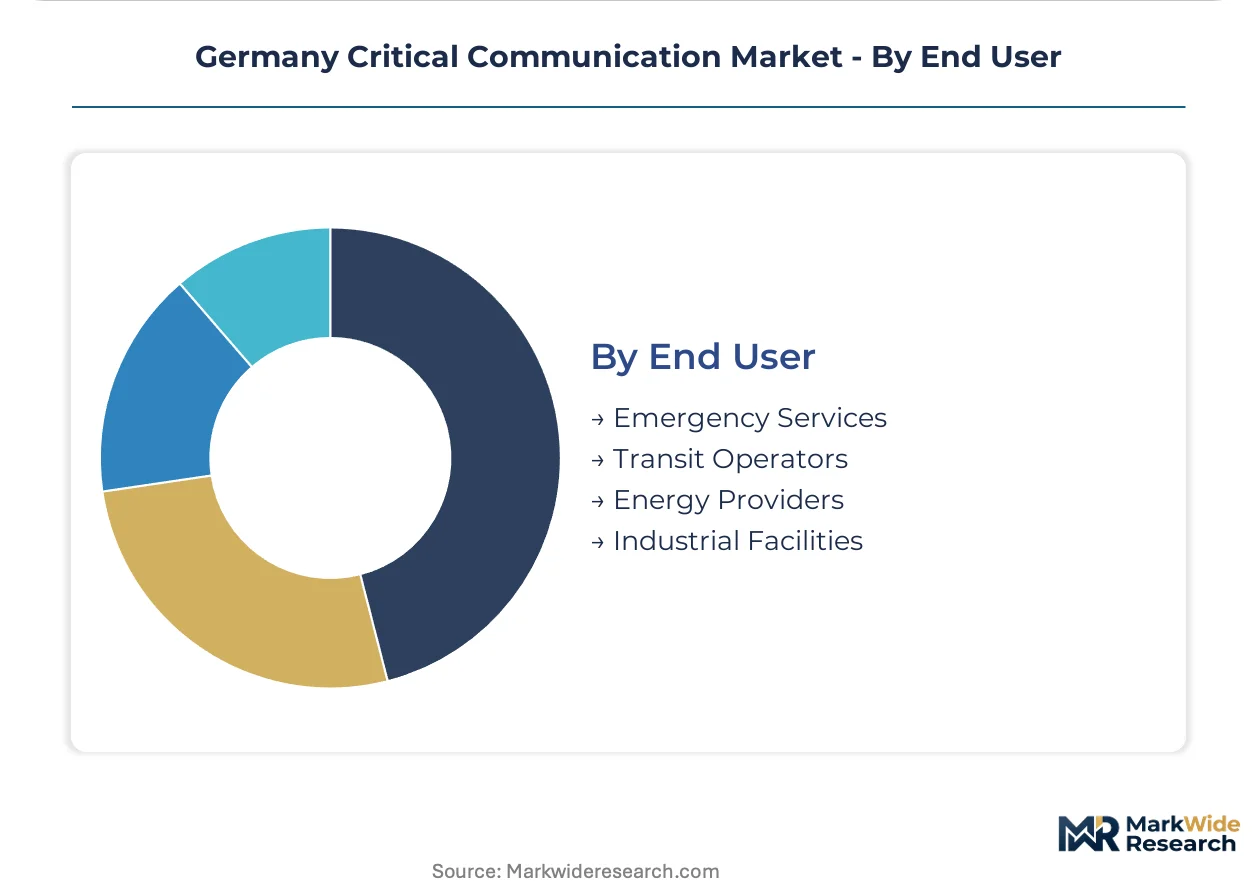
End User:
Procurement authority concentration varies from centralized federal frameworks to fragmented municipal purchasing, rewiring vendor go-to-market requirements.
- Emergency Services:Police, fire, and ambulance operators under BDBOS federal network modernization mandates. State-level agencies cede procurement authority to centralized federal frameworks.
- Transit Operators:Regional rail and urban transport authorities requiring interoperability with public safety networks. S-Bahn systems in Berlin and Munich coordinate dispatch integration.
- Energy Providers:Transmission and distribution operators subject to BSI critical infrastructure classification. Pre-qualification of European-manufactured radio terminals precedes formal mandate deadlines.
- Industrial Facilities:Chemical, automotive, and pharmaceutical plants with site-specific safety systems. Nurse-call-to-dispatch integration at Klinikum Stuttgart and Charité Berlin exceeds commercial cellular reliability.
Most centralized procurement: Emergency Services. Climbing the fastest: Industrial Facilities as healthcare alerting mandates expand addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication in Saxony anchors component supply for base station chipsets serving BDBOS network modernization across German federal states.
Bavaria
State police fleet standardization and Munich emergency control center upgrades drive procurement concentration. KBA type-approval requirements shape automotive emergency call device specifications for Bavarian automotive suppliers. Industrial corridors around Ingolstadt and Regensburg merge SCADA alerting with mission-voice systems under BSI critical infrastructure classification.
North Rhine-Westphalia
Chemical processing facilities in Ludwigshafen and Düsseldorf police district consolidations create dual demand streams. EU Cybersecurity Act baseline requirements disqualify uncertified vendors from framework eligibility. The Ruhr industrial belt concentrates hybrid TETRA-LTE base station deployment as BDBOS evaluates broadband migration paths.
Baden-Württemberg
Municipal fire department mergers across Stuttgart and Karlsruhe districts consolidate fragmented radio fleets. BDBOS federal procurement rules constrain vendor eligibility for next-generation networks. Manufacturing plants in the Black Forest region deploy cost-optimized narrowband alternatives where TETRA certification costs prove prohibitive.
Lower Saxony
Rural police districts and Hanover regional transport authorities require interoperability with public safety networks. Federal Network Agency spectrum reallocation timelines determine whether terrestrial trunked radio coexistence or full broadband migration prevails. The Volkswagen industrial complex in Wolfsburg mandates nurse-call-to-dispatch integration exceeding commercial cellular reliability.
Berlin-Brandenburg
Charité Berlin healthcare alerting mandates and S-Bahn dispatch integration create specialized demand. BSI technical guidelines for critical infrastructure cybersecurity mandate supply chain attestation down to firmware component origins. The capital region pilots edge-computing-enabled dispatch nodes to maintain sub-300-millisecond latency during fiber backhaul outages.
Germany Critical Communication Market Competitive Landscape
Global majors compete with regional champions across technology certification depth and federal framework eligibility. The vendor base separates into three tiers: integrated system architects with BDBOS terrestrial trunked radio installed bases, cybersecurity-hardened dispatch specialists, and niche healthcare alerting providers. Dominant competitive moves include multi-vendor framework agreement aggregation and service unbundling that separates hardware procurement from maintenance subscriptions.
Within the integrated system tier, Motorola Solutions and Telefonaktiebolaget LM Ericsson exemplify archetypes leveraging long-term service revenue from legacy network maintenance. Thales Group occupies a position among cybersecurity-focused specialists competing through hardened dispatch architectures. Multitone Elektronik International GmbH anchors the domestic specialist segment where compliance requirements favor localized suppliers in healthcare verticals.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Hytera Communications |
| Multitone Elektronik International GmbH |
| Thales Group |
| Ascom Holding |
| Motorola Solutions |
| Huawei Technologies |
| Airbus |
| Nokia Corporation |
| Others |
Supply & Pricing Matrix
BDBOS federal framework procurement pools concentrate buyer power among centralized purchasing authorities, anchoring contract-based long-term offtake as the dominant pricing model across German critical communication infrastructure.
Pricing Analysis
Warranty and maintenance unbundling from hardware acquisition is compressing upfront terminal pricing while expanding recurring service revenue streams. Three-tier pricing structure across mission-critical, industrial-grade, and standard commercial certification levels differentiates vendor positioning. Cost compression in mid-tier network equipment is intensifying because municipal purchasers negotiate multi-vendor framework splits. Industrial facilities in chemical processing corridors exhibit lowest price sensitivity due to BSI cybersecurity hardening mandates.
Supply Chain Analysis
EU Cybersecurity Act certification requirements gate vendor eligibility, forcing supply chain restructuring toward European-manufactured radio terminals. RF component fabrication draws from Taiwan, South Korea, and Malaysia for base station chipsets. Gallium nitride power amplifiers, ceramic filters, and hardened enclosures constitute critical input dependencies. Single-source vulnerability in Asian foundry capacity creates procurement risk. Distribution runs through BDBOS-qualified system integrators serving federal and state procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Cybersecurity Act baseline requirements are forcing consolidation by disqualifying uncertified vendors from framework eligibility, eliminating marginal competitors.
For Market Incumbents: Extend service revenue capture through multi-year maintenance subscriptions unbundled from hardware sales. Motorola Solutions and Ericsson archetypes should deepen backward integration into European radio terminal manufacturing to preempt BSI supply chain attestation mandates. Threat substitution from LTE broadband push-to-talk entrants demands accelerated TETRA-LTE hybrid certification pipelines. For New Entrants and Emerging Players: Mid-sized municipal fire departments in Baden-Württemberg district merger zones represent the most penetrable buyer archetype bypassing direct federal qualification barriers. Healthcare alerting verticals at Charité Berlin and Klinikum Stuttgart offer white-space expansion where compliance complexity favors specialized domestic suppliers. Framework agreement aggregation through established integrator partnerships provides the essential go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors cybersecurity-hardened dispatch specialists with BSI pre-qualification status ahead of formal mandate deadlines. Long-term viability centers on vendors controlling hybrid TETRA-LTE certification pipelines across the analysis window. Acquisition targets should demonstrate proven interoperability testing capabilities. The signal to monitor is Federal Network Agency 700 MHz band reallocation timeline announcements as inflection triggers for broadband migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid TETRA-LTE Certification Pipeline | BDBOS technology board procurement decisions favor vendors with simultaneous dual-mode interoperability validation. |
| European Manufacturing Footprint | BSI technical guidelines mandate supply chain attestation down to firmware component origins for critical infrastructure classification. |
| Framework Agreement Aggregation | Multi-vendor BDBOS procurement pools allow specialized accessory suppliers to bypass direct federal qualification barriers. |
| Edge-Computing Dispatch Node Deployment | Bavarian rural police districts pilot localized base station clusters to maintain sub-300-millisecond latency during fiber outages. |
| Healthcare Alerting Vertical Expansion | Klinikum Stuttgart and Charité Berlin nurse-call-to-dispatch integration mandates exceed commercial cellular reliability standards. |
Research Methodology
Independent corroboration across BDBOS procurement documentation, Federal Network Agency spectrum allocation filings, and BSI technical guideline releases underwrites the qualitative findings. Primary interviews with BDBOS technology board members, state police procurement officers, industrial control room operators, and healthcare facility safety directors combined with secondary validation from EU Cybersecurity Act certification databases, customs trade records for RF component imports, and federal budget appropriation documents. Bottom-up terminal shipment estimates and top-down infrastructure investment allocations were triangulated.
Rate-of-change decomposition across technology migration timelines, procurement cycle phasing, and certification pipeline throughput anchored the analytical framework. Segmentation dimensions modeled include product type, technology layer, application reliability tier, and end-user procurement authority concentration. CAGRs were derived from replacement cycle visibility and broadband migration policy velocity. Industry-specific forecast inputs incorporated BDBOS framework award patterns and BSI critical infrastructure classification expansion schedules.
Revisions become necessary when Federal Network Agency spectrum reallocation timelines accelerate or BDBOS technology board procurement decisions favor alternative migration paths. Forecasts reflect assumptions regarding semiconductor supply normalization and dual-certification technician availability. A model refresh is warranted upon material change in EU Cybersecurity Act enforcement thresholds or BSI supply chain attestation mandate deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Underwater Modems Market
Telecommunications
France Telecom Market
Telecommunications
Ghana Telecom Market
Telecommunications
Global SS7 Market
Telecommunications
Romania Telecom Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
Dialer Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Esim Subscription Market
Telecommunications
Managed M2M Services Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
5G Core Market
Telecommunications
Free Space Optics (FSO) Communication Market