
 North America Telecom Expense Management Market | 2026-2036
North America Telecom Expense Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Telecom Expense Management Market Analytics
Subscription-based managed services financing is reconfiguring capital deployment for mid-market buyers who previously lacked upfront IT budgets. Tangoe leverages cloud-native architecture to sustain recurring revenue from enterprise clients. Calero-MDSL anchors its position through invoice automation specialization. WidePoint Corporation competes on federal compliance credentials, distinguishing its channel control in government verticals.
Telecom expense management encompasses the systematic audit, allocation, and optimization of enterprise voice, data, and mobile spending through software platforms that integrate carrier invoices with internal accounting systems. These platforms apply machine-learning algorithms to detect billing anomalies and enforce usage policies across distributed workforces. Cloud-based deployment models now capture the fastest expansion as enterprises abandon on-premises infrastructure maintenance, while managed services bundles concentrate margin pools by combining software access with ongoing analyst support. Healthcare and BFSI verticals lead segment penetration due to stringent cost-allocation requirements and multi-location complexity.
FCC regulations govern carrier billing transparency and dispute resolution timelines, directly shaping platform feature requirements for North American vendors. The Sarbanes-Oxley Act and HIPAA compliance frameworks compel enterprises in regulated sectors to maintain auditable telecom expenditure trails, elevating demand for policy management modules. Stakeholders must monitor evolving state-level data privacy legislation and carrier consolidation patterns to anticipate invoice complexity shifts.
Market Dynamics
Carrier consolidation across the United States and Canada is compressing vendor diversity, forcing enterprise buyers to adopt automated dispute-resolution platforms as invoice complexity escalates.
Growth Catalysts
- HIPAA compliance mandates:Healthcare systems require auditable telecom expenditure trails, accelerating deployment of policy management modules.
- Cloud-native architecture migration:Mid-market enterprises abandon on-premises infrastructure for subscription-based managed services financing.
- Remote workforce expansion:Distributed employee bases generate mobile usage policy enforcement demand across multi-location organizations.
Market Restraints
- Carrier billing opacity:FCC dispute-resolution timelines create friction for platform feature standardization.
- Legacy ERP integration costs:SAP and Oracle system connectivity requires substantial professional services expenditure.
- Consolidated vendor landscape:Three dominant carriers control pricing data access, limiting third-party platform accuracy.
Strategic Opportunities
- Canadian financial services:Toronto and Vancouver banking clusters generate secondary adoption momentum for expense allocation platforms.
- AI-driven anomaly detection:Machine-learning algorithms converge with robotic process automation to reduce analyst headcount requirements.
- State-level privacy legislation:California and New York data protection frameworks create compliance-driven upgrade cycles.
Industry Challenges
- Telecom tariff complexity:Analyst teams require specialized training in carrier-specific rate structures and surcharge methodologies.
- API standardization gaps:Inconsistent data formats between carrier billing systems and enterprise platforms delay implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Telecom Expense Management Market |
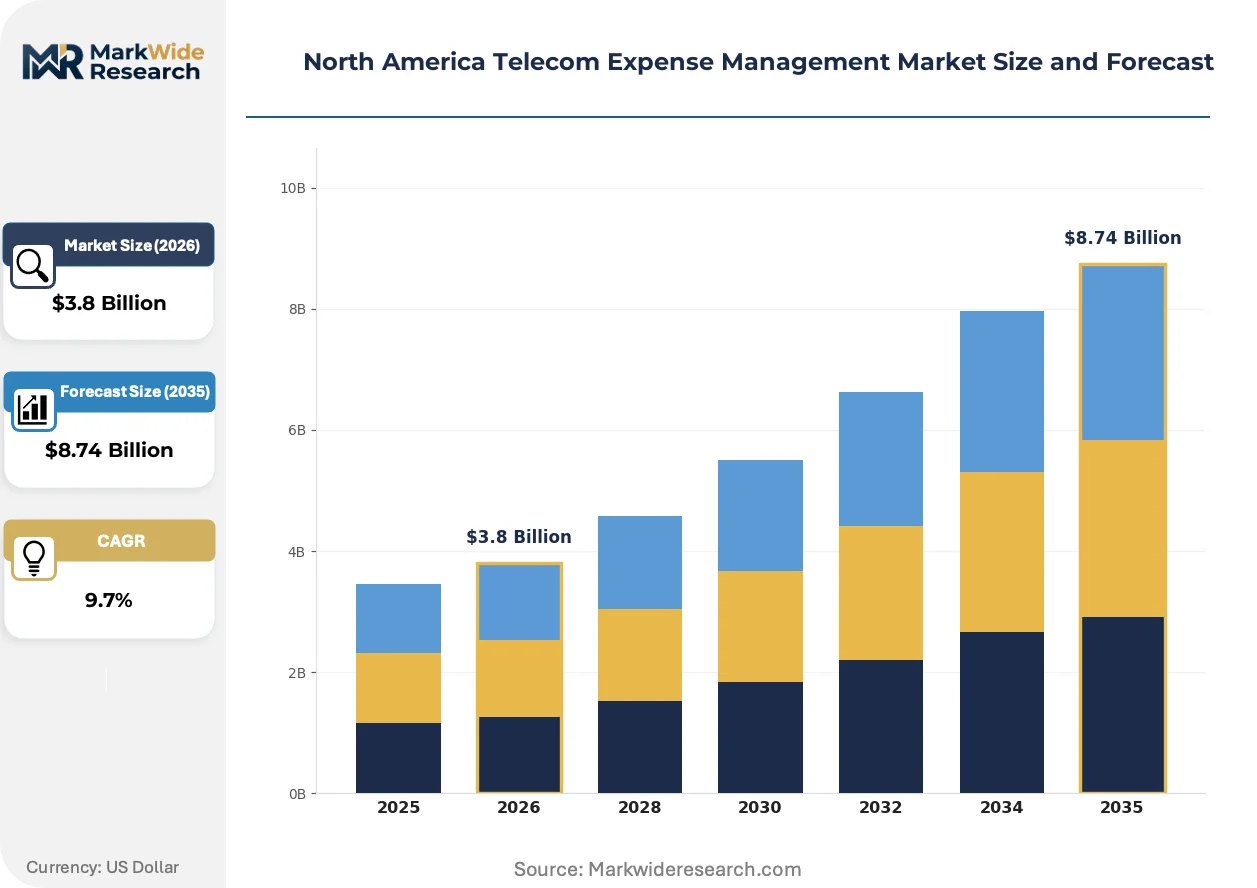
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Audit Services, Invoice Management, Policy Management, Reporting Tools Deployment Model: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services Customer Type: Enterprises, SMBs, Government, Non-Profit Organizations Industry Vertical: Healthcare, BFSI, Retail, Manufacturing |
| Companies Covered | Tangoe, Calero-MDSL, Verizon, AT&T, Cimpl, Avotus Corporation, WidePoint Corporation, TeleManagement Technologies, Tellennium, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Telecom Expense Management Market Evolving Landscape
Automation architectures are restructuring how enterprises consume telecom expense capabilities, shifting value capture from software licenses to continuous optimization services.
Machine-learning invoice validation is collapsing the traditional audit cycle from quarterly reviews to real-time anomaly flagging. Healthcare and BFSI verticals adopt these platforms fastest due to stringent cost-allocation requirements. The compression of detection latency is eliminating manual spreadsheet reconciliation and reducing analyst staffing ratios.
FCC net neutrality rulings reshape carrier transparency obligations, compelling vendors to build automated dispute-filing modules directly into platform workflows. Billing transparency mandates affect enterprise selection criteria more than feature breadth. United States buyers now prioritize platforms with pre-built carrier API connectors over customizable configurations.
Subscription financing models displace perpetual license purchases across mid-market segments previously excluded from advanced expense management. Managed services bundles combine software access with dedicated analyst support, capturing margin pools that pure-play vendors cannot access. This shift concentrates most visible in United States healthcare and financial services verticals with constrained upfront IT capital.
North America Telecom Expense Management Market Segmentation
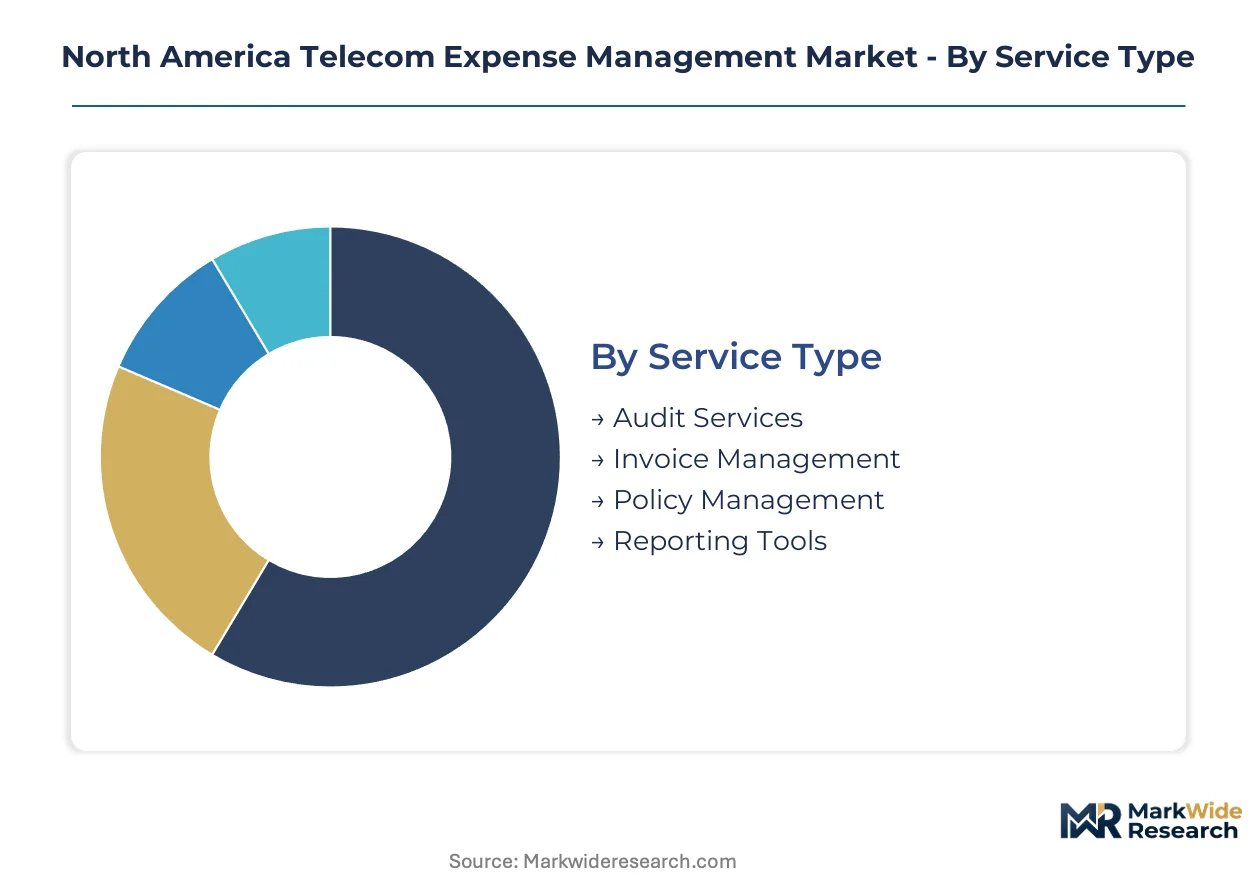
Telecom expense management platforms segment across service delivery, technical architecture, buyer scale, and sector-specific compliance requirements. Each dimension carries distinct procurement cycles and margin structures that reshape vendor positioning across the United States and Canada.
Service Type:
Invoice Management and Policy Management command the shortest renewal cycles as enterprises demand continuous optimization rather than periodic audits. Audit Services and Reporting Tools operate on longer engagement horizons with lower recurring revenue attachment.
- Invoice Management:Automated ingestion and validation of carrier bills through machine-learning algorithms that flag billing anomalies against contracted rates. Healthcare systems in the United States deploy these capabilities to satisfy HIPAA audit trail requirements while reducing analyst headcount.
- Policy Management:Usage governance frameworks that enforce spending limits and roaming restrictions across distributed mobile workforces. Canadian financial services clusters in Toronto leverage these modules to allocate telecom costs precisely across business units and regulatory entities.
- Audit Services:Periodic manual review engagements for historical billing recovery.
- Reporting Tools:Dashboard and analytics outputs for executive visibility into telecom expenditure patterns.
Established volume favors Invoice Management; emerging adoption favors Policy Management.
Deployment Model:
Cloud-Based and Managed Services bundles capture mid-market buyers previously excluded by upfront capital requirements. On-Premises and Hybrid Solutions retain footholds in government and regulated sectors with data sovereignty constraints.
- Cloud-Based:Multi-tenant SaaS architectures with automatic feature updates and API connectivity to carrier billing systems. United States healthcare enterprises abandon on-premises infrastructure maintenance for subscription financing models that preserve IT capital.
- Managed Services:Combined software access with dedicated analyst support for dispute resolution and contract negotiation. SMB segments across the United States purchase these bundles to access enterprise-grade capabilities without internal telecom expertise.
- On-Premises:Single-tenant installations behind enterprise firewalls for maximum data control.
- Hybrid Solutions:Split configurations retaining sensitive processing on-premises while leveraging cloud analytics.
Cloud-Based deployment is climbing the fastest; Hybrid Solutions retain niche positioning in federal and provincial government accounts.
Customer Type:
Enterprises and Government buyers anchor revenue concentration with multi-year contracts and complex integration requirements. SMBs and Non-Profit Organizations represent expansion frontiers as subscription pricing democratizes access.
- Enterprises:Multi-location organizations with carrier diversity exceeding fifty contracts and annual telecom spend above five million dollars. These buyers demand API standardization across SAP and Oracle ERP environments, driving professional services attachment.
- SMBs:Organizations with constrained IT budgets and limited internal telecom expertise. Subscription-based managed services financing enables these buyers to deploy expense management platforms previously accessible only to Fortune 500 accounts.
- Government:Federal, state, and provincial agencies with Federal Risk and Authorization Management Program (FedRAMP) or comparable compliance mandates.
- Non-Profit Organizations:Mission-driven entities prioritizing cost transparency for donor reporting and grant compliance.
Enterprises dominate current revenue; SMBs represent the steepest expansion trajectory as pricing accessibility improves.
Industry Vertical:
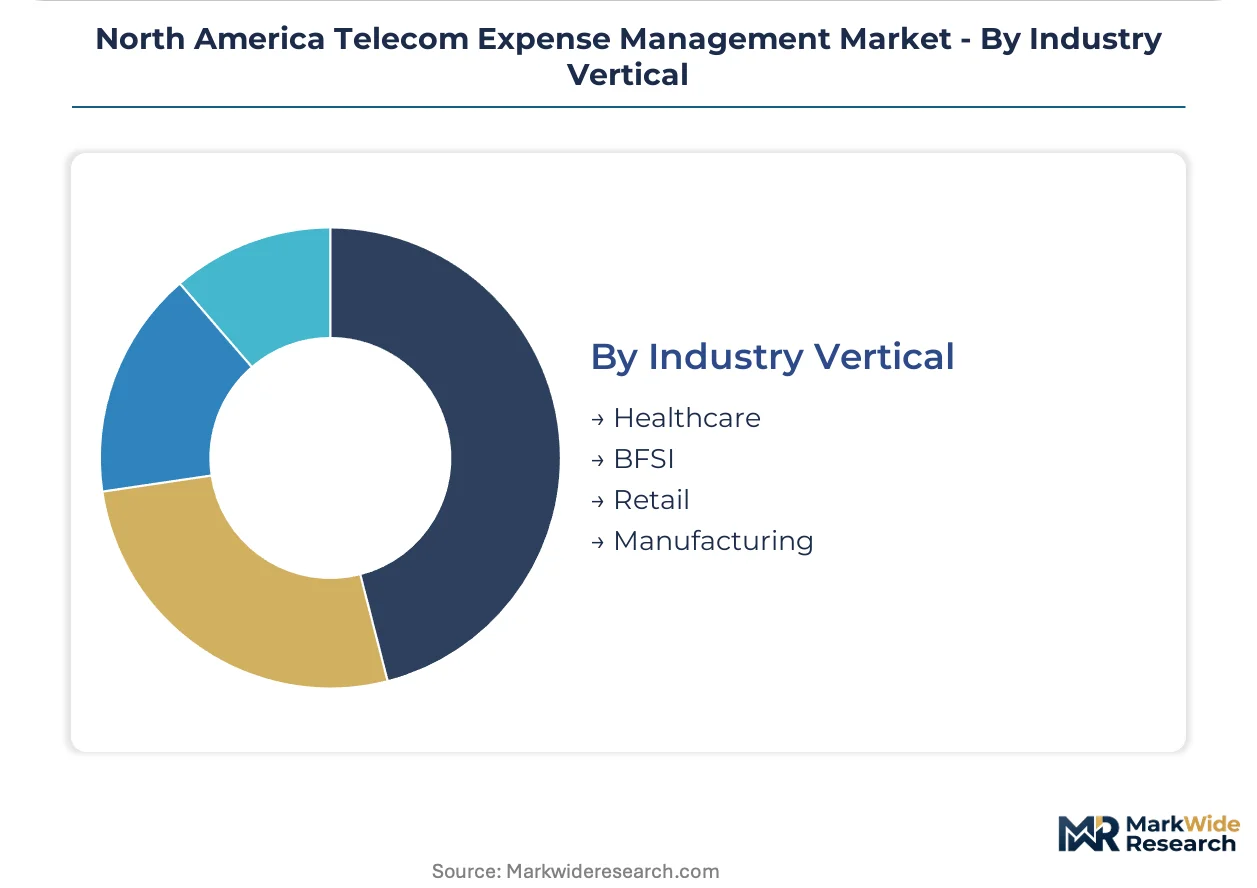
Healthcare and BFSI verticals lead penetration due to stringent cost-allocation mandates and multi-location operational complexity. Retail and Manufacturing segments follow with distinct compliance and supply-chain integration requirements.
- Healthcare:Hospital systems and payer organizations requiring auditable expenditure trails for HIPAA compliance and Medicare cost reporting. United States health networks deploy policy management modules to govern mobile device usage across clinical and administrative workforces.
- BFSI:Banking, financial services, and insurance entities with Sarbanes-Oxley audit requirements and branch-level cost allocation needs. Canadian banking clusters in Vancouver and Toronto generate concentrated demand for automated invoice validation.
- Retail:Multi-store operators with seasonal workforce fluctuations and distributed point-of-sale connectivity.
- Manufacturing:Industrial enterprises integrating telecom expense data with supply-chain and logistics platforms.
Healthcare anchors current platform deployment; BFSI is gaining share fastest as Canadian financial services accelerate adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC billing transparency mandates and carrier consolidation patterns are redrawing procurement priorities across North American enterprise buyers. Subscription financing models now penetrate mid-market segments previously excluded by upfront capital barriers.
United States
Healthcare systems and federal agencies drive platform deployment through HIPAA and FedRAMP compliance requirements. FCC dispute-resolution timelines compel vendors to embed automated filing modules directly into workflows. Hospital networks in Texas and California abandon on-premises infrastructure for cloud-native subscription models.
Canada
Toronto and Vancouver banking clusters generate concentrated demand for automated invoice validation and cost allocation precision. Health Canada data sovereignty frameworks sustain hybrid deployment preferences among provincial health authorities. Canadian financial services accelerate adoption faster than any adjacent vertical.
Mexico
Nearshoring manufacturing investments expand multi-location enterprise footprints requiring mobile policy governance. Federal telecommunications reform initiatives press for billing standardization across dominant carriers. Mexico City metro enterprises pilot managed services bundles to access analyst support without internal telecom expertise.
Northeast Corridor
Philadelphia-to-Boston pharmaceutical and insurance headquarters anchor complex ERP integration demand. State-level data privacy legislation in New York creates compliance-driven upgrade cycles for policy management modules. Regional carrier diversity exceeds fifty contracts per enterprise, forcing automated dispute-resolution adoption.
Pacific Northwest
Seattle and Vancouver technology clusters pioneer API-first platform architectures for real-time invoice validation. Cross-border data flow requirements between Washington State and British Columbia sustain hybrid cloud preferences. Regional SaaS vendors compete on pre-built carrier connectors rather than customization depth.
North America Telecom Expense Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around three functional archetypes. Tangoe and Calero-MDSL anchor the cloud-native platform tier with recurring revenue engines. WidePoint Corporation occupies the federal compliance niche with FedRAMP credentials. Verizon and AT&T leverage carrier ownership to bundle expense management with connectivity contracts. Dominant competitive moves include invoice automation specialization and analyst-staffed managed services bundling.
Within the cloud-native platform tier, Tangoe exemplifies subscription-based recurring revenue capture from enterprise healthcare and financial services accounts. Calero-MDSL occupies a position anchored through machine-learning invoice validation specialization. WidePoint Corporation represents the compliance-driven archetype, distinguishing its channel control through federal and provincial government verticals. These three named entities collectively illustrate how vendor positioning stratifies across technical architecture, regulatory credentialing, and service bundling depth rather than feature breadth alone.
| Leading Market Players |
|---|
| Tangoe |
| Calero-MDSL |
| Verizon |
| AT&T |
| Cimpl |
| Avotus Corporation |
| WidePoint Corporation |
| TeleManagement Technologies |
| Tellennium |
| Others |
Value Network & Pricing Analysis
The I-95 corridor freight network carries cloud infrastructure components from East Coast ports to Midwest data centers, with logistics cost volatility feeding directly into subscription pricing tiers and compressing margins for vendors lacking carrier API pre-certification.
Pricing Analysis
Certification level (FedRAMP/StateRAMP-grade) creates the primary spread between premium and standard SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with HIPAA-compliant policy management modules commanding substantial premiums over basic invoice ingestion. Cost compression in the mid-market tier is intensifying because carrier API standardization reduces differentiation headroom. SMB buyers exhibit highest price sensitivity, while federal agencies prioritize compliance credentials over cost.
Supply Chain Analysis
Export-control restrictions on machine-learning training hardware limit flows of advanced GPUs into Canadian and Mexican deployment environments, constraining real-time anomaly detection capabilities for regional vendors. Software development concentrates in the United States, India, and Ireland, with cloud infrastructure sourcing from domestic hyperscaler regions. The supply chain rests on semiconductor availability, carrier billing data feeds, and cybersecurity certification processing. Single-source vulnerability in carrier API access poses structural risk. Distribution runs through direct enterprise sales teams and channel partners serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
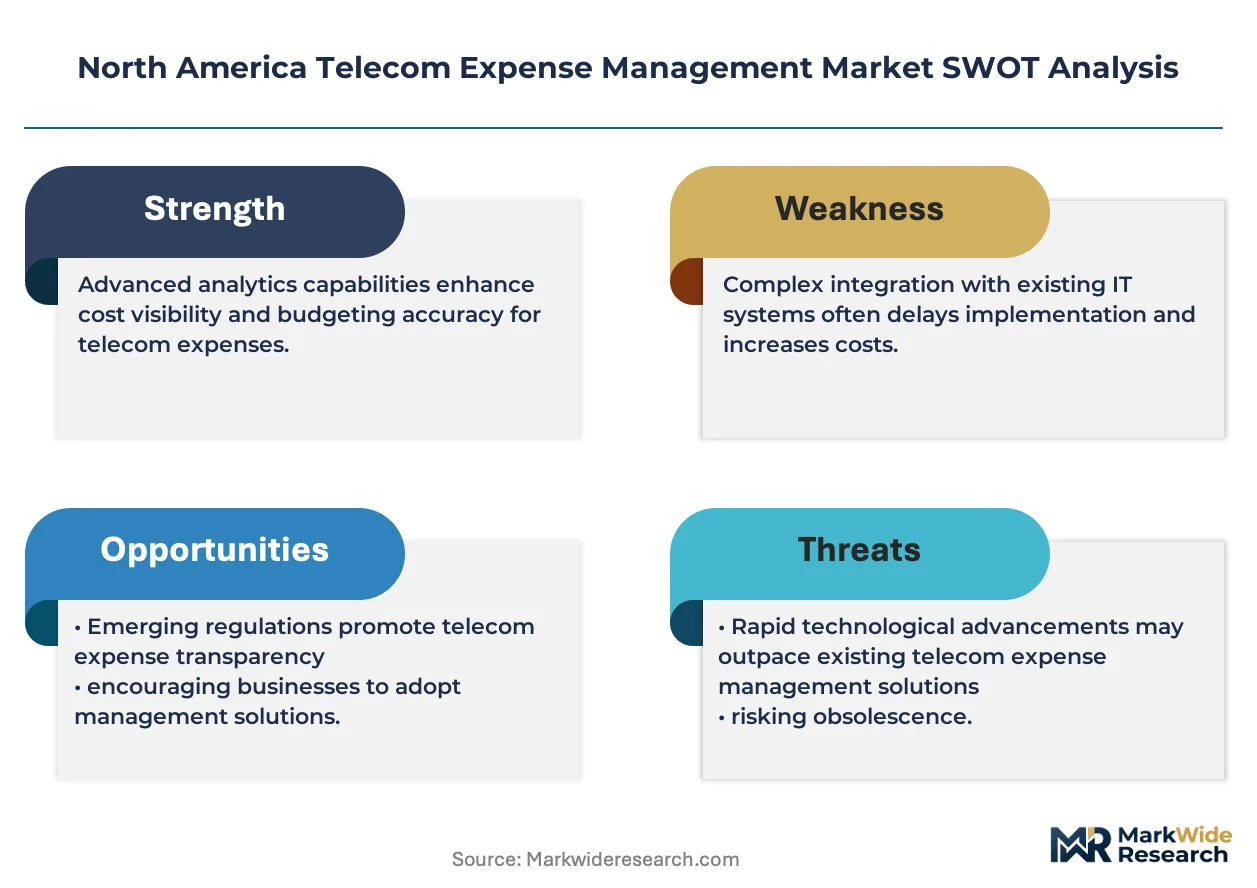
North American telecom expense management sits in early-cycle expansion as HIPAA-mandated audit trails force healthcare systems toward automated platforms previously accessible only to Fortune 500 accounts.
For Market Incumbents: Harden recurring revenue streams by embedding robotic process automation deeper into dispute-resolution workflows before pure-play AI entrants capture analyst-staffing cost advantages. Prioritize FedRAMP certification investment to defend government vertical share against carrier-owned bundling threats from Verizon and AT&T.
For New Entrants and Emerging Players: Canadian provincial health authorities outside Ontario and Quebec represent the most penetrable geography, with hybrid deployment preferences creating white-space for compliance-specialist vendors. Target Mexico City manufacturing clusters expanding through nearshoring investments with Spanish-language managed services bundles as the specific go-to-market angle.
For Investors and Strategic Acquirers: FCC net neutrality rulings reshape the acquisition landscape by elevating automated dispute-filing capabilities above feature breadth in enterprise selection criteria. Long-term viability favors platforms with pre-built carrier API connectors and analyst-staffed service layers over pure software plays. Watch carrier consolidation patterns as the signal indicating invoice complexity inflection and platform switching momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Carrier API Pre-Certification Program | Eliminates implementation delays for United States healthcare systems facing HIPAA audit deadlines. |
| Managed Services Bundle Expansion | Captures SMB segments previously excluded by upfront IT capital requirements. |
| FedRAMP Authorization Pathway | Unlocks federal and state agency procurement channels with multi-year contract visibility. |
| AI-Driven Anomaly Detection Platform | Reduces analyst headcount ratios while collapsing detection latency from quarterly to real-time. |
| Canadian Banking Cluster Partnership | Secures reference architecture for BFSI cost allocation requirements in Toronto and Vancouver. |
Research Methodology
A spread of perspectives from telecom expense management platform executives, healthcare IT procurement officers, carrier billing operations directors, and federal compliance consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC rulings, HIPAA audit guidelines, carrier tariff filings, and enterprise software procurement databases. Bottom-up sizing of deployment volumes across cloud, managed services, and on-premises segments was triangulated against top-down expenditure estimates from healthcare and BFSI verticals.
Demand-supply balance across the projection horizon anchored the analytical framework, with segmentation modeling covering service delivery mode, technical architecture, buyer scale tier, and vertical compliance requirements. CAGRs were derived from fitted growth curves calibrated to adoption velocity in healthcare systems and Canadian financial services clusters. Forecast inputs included carrier consolidation timelines, state-level privacy legislation enactment patterns, and remote workforce mobile policy enforcement penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed entrants or carrier-owned platform bundling would shift outcomes beyond modeled ranges. Material shifts in FCC dispute-resolution mandates or carrier API standardization enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Indonesia Volte Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Cloud RAN Market
Telecommunications
Myanmar Telecom Market
Telecommunications
Global Telecommunication Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Europe Managed SD-WAN Services Market
Telecommunications
LTE Base Station System Market
Telecommunications
5G Core Market
Telecommunications
Prepaid Communication Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
Global International Calling Apps Market
Telecommunications
Managed M2M Services Market
Telecommunications
Belgium ICT Market
Telecommunications
Spain ICT Market
Telecommunications
MVNO Market