
 NOR Flash Market | 2026-2036
NOR Flash Market Size, Share, and Industry Trends Forecast 2026-2036
NOR Flash Market Outlook
Asset-light foundry partnerships are tilting capital requirements downward for fabless NOR flash competitors. Winbond Electronics Corp. leverages captive 300mm fabrication to sustain cost leadership in low-density serial NOR. GigaDevice Semiconductor Inc. anchors its position through backward integration into 12-inch wafer supply. Infineon Technologies AG differentiates via automotive-qualified embedded NOR with extended temperature ratings.
NOR flash constitutes a non-volatile memory architecture utilizing floating-gate transistors organized in a parallel addressable matrix, enabling random access read speeds below 70 nanoseconds for code execution in place. Its primary commercial purpose centers on storing boot firmware, BIOS images, and executable code in systems requiring instantaneous startup without DRAM shadowing. Serial NOR commands the largest revenue pool due to SPI interface standardization across consumer and industrial controllers. High-density configurations represent the fastest-expanding technology tier as automotive domain controllers consolidate multiple discrete chips. Embedded NOR captures premium margin pools by eliminating external memory packaging in space-constrained modules.
The US FCC and FDA impose electromagnetic compatibility and safety validation on NOR flash within wireless medical devices and avionics systems. China's MIIT enforces GB standards for domestic semiconductor procurement in telecommunication infrastructure. REACH and RoHS compliance across Europe restricts hazardous substances in memory packaging substrates. Stakeholders must monitor how automotive functional safety certifications reshape supplier qualification timelines and foundry allocation priorities.
Market Dynamics
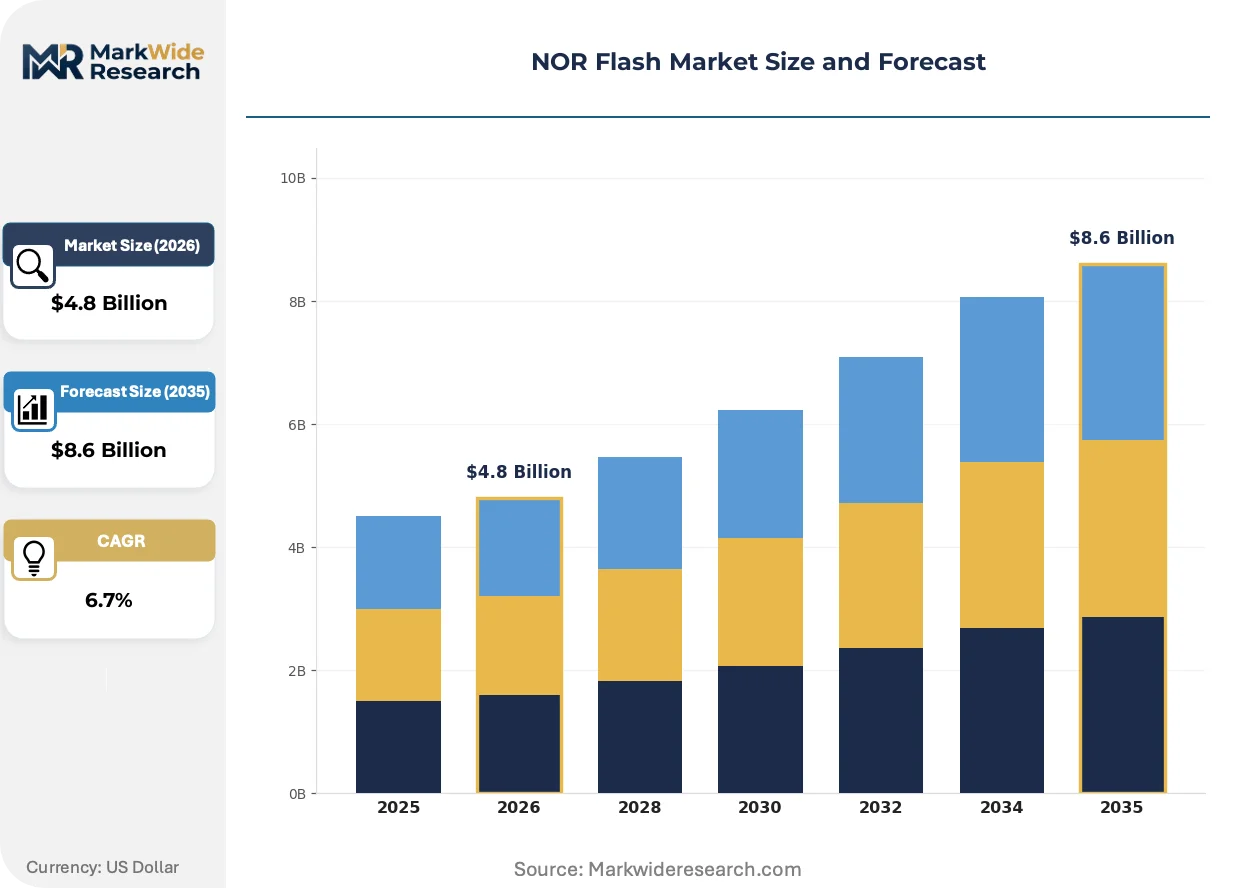
Automotive domain controller consolidation is collapsing discrete memory chip counts into single high-density NOR packages, rewiring supplier qualification timelines and foundry allocation priorities across the memory value chain.
Growth Catalysts
- Automotive ECU expansion:China's MIIT mandates domestic semiconductor sourcing for critical infrastructure, accelerating local NOR flash procurement for vehicle firmware storage.
- SPI interface standardization:Serial NOR commands the largest revenue pool due to universal controller compatibility across consumer and industrial endpoints.
- Industrial IoT gateway density:Taiwan anchors demand concentration for high-density serial NOR in factory automation and edge computing deployments.
Market Restraints
- 300mm wafer supply concentration:Captive fabrication at select foundries creates allocation bottlenecks during demand spikes.
- NAND flash substitution pressure:Execute-in-place alternatives threaten low-density NOR sockets in cost-sensitive consumer devices.
- REACH and RoHS compliance friction:Europe's hazardous substance restrictions constrain packaging substrate sourcing and extend qualification cycles.
Strategic Opportunities
- Space-constrained embedded modules:Embedded NOR eliminates external memory packaging in medical wearables and aerospace avionics.
- Extended temperature automotive ratings:Functional safety certifications open premium margin pools in powertrain and chassis controllers.
- China's dual carbon goals:Energy efficiency mandates favor low-power serial NOR in smart grid and renewable energy monitoring systems.
Industry Challenges
- Automotive functional safety certification timelines:ISO 26262 qualification extends product development cycles by 18-24 months.
- Legacy parallel NOR integration complexity:Random access architectures require specialized controller IP that fragments design resources.
- Foundry allocation reconfiguration:Mixed-signal process migration demands capital-intensive equipment retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NOR Flash Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parallel NOR, Serial NOR, OTP NOR, Embedded NOR End User: Consumer Electronics, Automotive, Telecommunication, Industrial Technology: Synchronous, Asynchronous, Low-Density, High-Density Application: Firmware, BIOS, Code Storage, Data Retention |
| Companies Covered | Infineon Technologies AG, Microchip Technology Inc., Micron Technology Inc., Integrated Silicon Solution, Renesas Electronics Corp., Winbond Electronics Corp., GigaDevice Semiconductor Inc, Cypress Semiconductor Corp, Macronix International Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NOR Flash Market Strategic Shifts
Memory architecture convergence around serial interfaces is compressing legacy parallel NOR volumes while opening new density tiers for code-storage consolidation.
High-density serial NOR is collapsing multiple discrete boot memory chips into single-package solutions. Automotive tier-one suppliers are adopting 512Mb-1Gb configurations for consolidated domain controller firmware. This density migration is collapsing bill-of-material line items and simplifying PCB layouts across vehicle electronic architectures.
China's GB standards for domestic semiconductor procurement are reshaping supplier qualification pathways. MIIT enforcement of local content requirements in telecommunication infrastructure is redirecting foundry output toward certified domestic vendors. NOR flash suppliers are responding with dedicated China-qualified product lines and localized test flows.
Buyer consolidation among automotive OEMs is compressing supplier approval cycles and hardening volume commitment terms. Long-term supply agreements now dominate procurement for qualified NOR flash in safety-critical ECUs. This contract shift is most visible in Germany and Japan, where KBA and METI oversight intensifies traceability requirements.
NOR Flash Market Segmentation
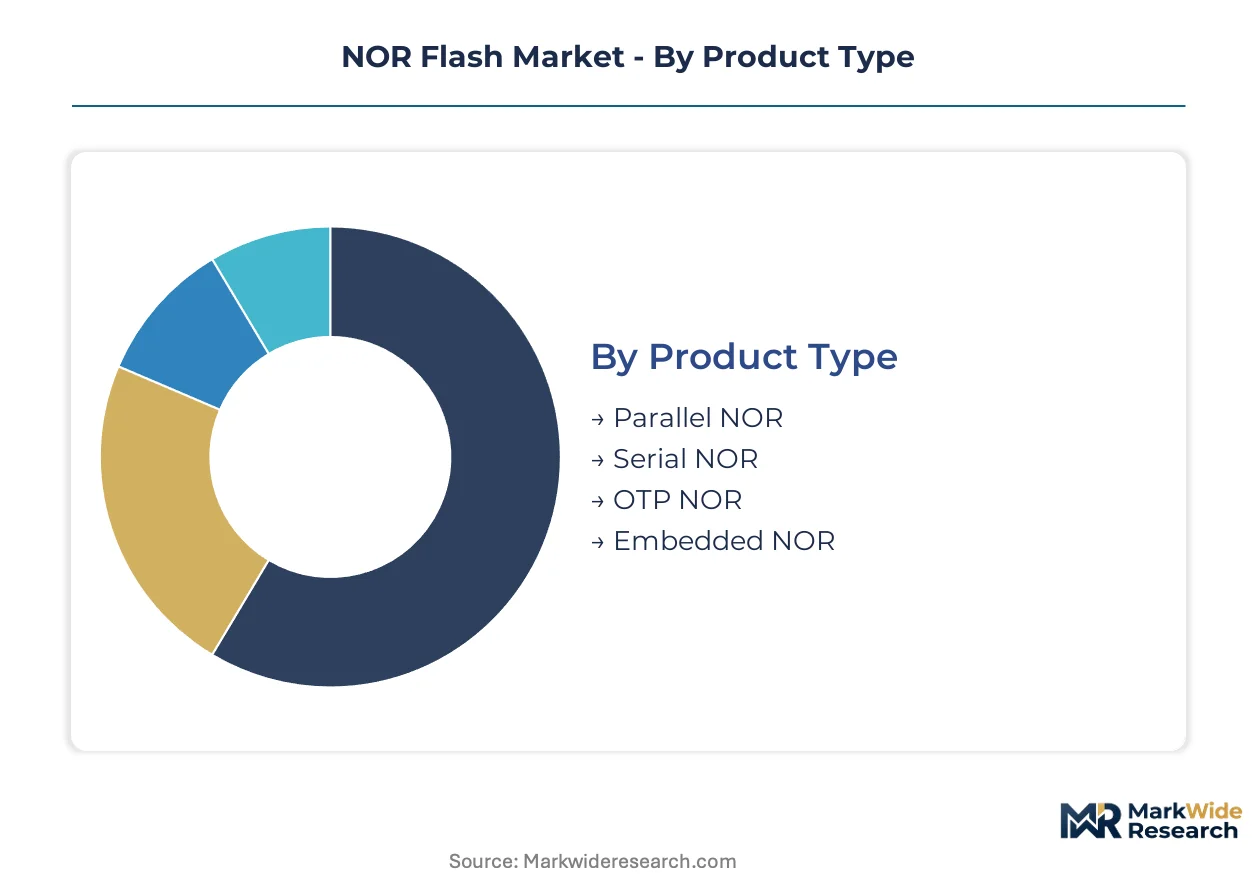
NOR flash segmentation reveals how interface architectures, density tiers, and qualification requirements fragment procurement strategies across end-use verticals. Product type and technology choices determine foundry process selection, while end-user specifications dictate certification timelines and margin structures.
Product Type:
After-sales service intensity varies sharply across product categories, with automotive-qualified embedded NOR requiring field failure analysis and traceability support that parallel NOR in consumer devices never demands.
- Serial NOR:SPI interface standardization enables universal controller compatibility across consumer and industrial endpoints. Taiwan anchors demand concentration for high-density serial NOR in factory automation gateways, driven by domain controller consolidation collapsing multiple discrete chips into single packages.
- Embedded NOR:Monolithic integration eliminates external memory packaging in space-constrained medical wearables and aerospace avionics. Powertrain and chassis controllers in Germany and Japan drive premium-margin procurement through ISO 26262 functional safety certifications with extended temperature ratings.
- Parallel NOR:Random access architectures below 70 nanoseconds serve legacy BIOS storage in server motherboards requiring instantaneous startup without DRAM shadowing.
- OTP NOR:One-time programmable cells provide immutable boot code storage for security-sensitive payment terminals and cryptographic hardware modules.
Serial NOR holds the largest share; momentum sits with embedded NOR.
End User:
Cost tier stratification separates automotive safety-critical procurement with 18-24 month qualification cycles from consumer electronics sourcing governed by spot pricing and rapid product refresh.
- Automotive:Domain controller architectures consolidate ECU firmware into high-density NOR packages with AEC-Q100 automotive qualification. China's MIIT mandates domestic semiconductor sourcing for vehicle infrastructure, accelerating local procurement for firmware storage.
- Industrial:Factory automation and edge computing deployments in Taiwan drive high-density serial NOR demand for IoT gateway consolidation. Extended temperature ratings and long-term supply agreements dominate procurement patterns.
- Telecommunication:Base station controllers and network infrastructure utilize serial NOR for boot firmware under China's GB standards for domestic procurement.
- Consumer Electronics:Cost-sensitive devices face NAND flash substitution pressure in execute-in-place applications, compressing low-density NOR sockets.
Automotive commands premium pricing tiers; industrial applications are expanding most quickly.
Technology:
Volume concentration favors high-density synchronous architectures in automotive domain controllers, while asynchronous low-density production serves fragmented consumer and legacy industrial sockets.
- High-Density:512Mb-1Gb configurations collapse multiple boot memory chips into single-package solutions for automotive domain controllers. PCB layout simplification and bill-of-material reduction drive tier-one supplier adoption.
- Synchronous:Clock-aligned data transfer supports high-speed code execution in automotive powertrain controllers requiring deterministic read latency.
- Low-Density:Legacy 32Mb-128Mb configurations persist in cost-constrained consumer devices and industrial sensors with minimal firmware footprints.
- Asynchronous:Eliminated clock dependency reduces power consumption in battery-operated medical wearables and remote monitoring equipment.
High-Density captures the steepest expansion trajectory; Low-Density retains volume concentration in legacy sockets.
Application:
Margin structure correlates with certification burden, where BIOS storage for avionics systems under FAA oversight commands multiples over commodity firmware in consumer devices.
- Firmware:Boot code storage for microcontrollers and SoCs requires instantaneous read access without DRAM initialization. Automotive ECU architectures in Germany and Japan specify long-term supply agreements with full traceability.
- BIOS:Motherboard initialization code demands sub-70 nanosecond random access for server and workstation platforms. FCC electromagnetic compatibility validation applies to wireless-enabled systems.
- Code Storage:Execute-in-place architectures enable direct processor execution from NOR without shadowing to RAM, critical for fast-boot industrial controllers.
- Data Retention:Non-volatile archival applications leverage NOR's 20-year retention specifications for configuration parameters and calibration constants in smart grid infrastructure.
Firmware dominates revenue contribution; BIOS applications face NAND substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement offices and industrial gateway manufacturers concentrate NOR flash demand across manufacturing clusters in Germany, China, Taiwan, Japan, and the United States. Each geography imposes distinct regulatory qualification pathways that reshape supplier access and foundry allocation priorities.
Germany
Automotive powertrain and chassis controller manufacturers drive premium-tier NOR flash procurement through KBA-mandated traceability requirements. The country's national automotive regulator enforces ISO 26262 functional safety certifications that extend supplier qualification timelines by 18-24 months. Stuttgart and Munich anchor tier-one supplier engineering centers where high-density serial NOR consolidates discrete boot memory chips into single-package domain controller solutions.
China
MIIT mandates domestic semiconductor sourcing for vehicle firmware storage and telecommunication infrastructure under GB standards enforcement. The ministry's procurement rules redirect foundry output toward certified local vendors for base station controllers and smart grid monitoring systems. Shanghai and Shenzhen industrial zones host the fastest-growing concentration of NOR flash test flows dedicated to China-qualified product lines.
Taiwan
Industrial IoT gateway manufacturers in Hsinchu Science Park drive high-density serial NOR demand for factory automation and edge computing deployments. The island's national industrial regulator maintains extended temperature rating specifications that govern procurement patterns for long-term supply agreements. Taipei anchors captive 300mm fabrication capacity that sustains cost leadership in low-density serial NOR production.
Japan
METI oversight intensifies traceability requirements for safety-critical ECU firmware storage in vehicle electronic architectures. The ministry's automotive division coordinates with OEM procurement offices to compress supplier approval cycles through hardened volume commitment terms. Nagoya and Osaka industrial corridors concentrate domain controller consolidation projects collapsing multiple discrete memory chips into single high-density packages.
United States
FCC electromagnetic compatibility validation applies to wireless-enabled BIOS storage in server motherboards and medical devices. The commission's safety requirements intersect with FDA oversight on NOR flash within avionics systems and wireless medical equipment. Silicon Valley and Austin engineering centers focus on execute-in-place architectures enabling direct processor execution without DRAM shadowing.
NOR Flash Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply relationships governed by automotive qualification timelines and foundry allocation priorities. The vendor base organizes around captive fabrication capacity, fabless design houses, and memory subsystem integrators serving distinct end-use verticals. Three archetypes dominate: integrated device manufacturers with in-house wafer supply, fabless competitors leveraging asset-light foundry partnerships, and automotive-qualified specialists commanding premium margins through extended temperature ratings. Competitive moves concentrate on backward integration into 12-inch wafer supply and strategic partnerships for mixed-signal process migration.
Among integrated device manufacturers with captive fabrication, Winbond Electronics Corp. and Infineon Technologies AG exemplify archetypes occupying positions at opposite ends of the density spectrum. Winbond anchors cost leadership in low-density serial NOR through 300mm fabrication control. Infineon represents the automotive-qualified embedded NOR specialist tier where functional safety certifications open premium margin pools. GigaDevice Semiconductor Inc. sits within the fabless competitor archetype leveraging asset-light foundry partnerships to tilt capital requirements downward.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Microchip Technology Inc. |
| Micron Technology Inc. |
| Integrated Silicon Solution |
| Renesas Electronics Corp. |
| Winbond Electronics Corp. |
| GigaDevice Semiconductor Inc |
| Cypress Semiconductor Corp |
| Macronix International Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive 300mm fabrication in Taiwan and China anchors cost leadership positions for low-density serial NOR, while automotive qualification requirements in Germany and Japan concentrate premium margin pools at the high-density embedded tier. Foundry allocation bottlenecks during demand spikes translate directly into pricing volatility for fabless competitors without backward-integrated wafer supply.
Pricing Analysis
Certification level creates the primary spread, with ISO 26262-qualified automotive NOR commanding substantial premiums over consumer-grade serial variants. Three-tier pricing structure across premium, standard, and economy levels reflects AEC-Q100 qualification status, volume commitment scale, and after-sales traceability bundling. Cost compression in low-density consumer tiers intensifies because NAND flash execute-in-place alternatives threaten socket viability. Consumer electronics OEMs exhibit highest price sensitivity, while German and Japanese automotive tier-one suppliers prioritize supply assurance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard for automotive OEM procurement offices qualifying NOR flash vendors for long-term agreements. Wafer supply concentrates in Taiwan, China, and South Korea, with raw silicon, specialty gases, and photoresist materials drawing from concentrated chemical supplier bases. Single-source vulnerability around 300mm mixed-signal process capacity represents the dominant structural risk. Distribution runs through authorized distributors serving industrial and automotive verticals, with direct OEM relationships dominating high-volume safety-critical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated automotive OEM procurement offices, where hardened volume commitment terms and compressed supplier approval cycles now dominate safety-critical NOR flash sourcing. Tier-one supplier consolidation across Germany, Japan, and China has fragmented vendor access and intensified qualification burden.
For Market Incumbents: Entrench automotive qualification positions by deepening captive 300mm fabrication control and accelerating ISO 26262 certification pipelines for emerging domain controller densities. NAND flash substitution in consumer execute-in-place sockets threatens low-density revenue streams; counter through backward integration into 12-inch wafer supply and exclusive long-term supply agreements with China-qualified product lines. For New Entrants and Emerging Players: Pursue white-space opportunities in industrial IoT gateway applications across Taiwan's Hsinchu Science Park corridor, where high-density serial NOR demand outpaces qualified domestic supplier capacity. China's MIIT-mandated domestic semiconductor procurement for telecommunication infrastructure offers the most penetrable regulatory pathway; establish localized test flows and GB standards compliance as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward automotive-qualified embedded NOR specialists with existing AEC-Q100 certifications and extended temperature rating portfolios. Long-term viability hinges on functional safety certification moats and foundry allocation priority through the projection horizon. Watch for inflection signals in China-qualified product line revenue mix and automotive domain controller consolidation project wins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 300mm Wafer Supply | Captive fabrication secures allocation priority during demand spikes and insulates margin from foundry pricing volatility. |
| ISO 26262 Functional Safety Certification | Automotive powertrain and chassis controller qualification opens premium pricing tiers in Germany and Japan procurement. |
| China-Qualified Product Line Localization | MIIT GB standards compliance enables access to mandated domestic semiconductor procurement for vehicle firmware storage. |
| High-Density Serial NOR Platform Expansion | 512Mb-1Gb configurations collapse multiple discrete chips into single-package domain controller solutions for tier-one suppliers. |
| Long-Term Supply Agreement Structuring | Hardened volume commitments with automotive OEMs secure foundry allocation and compress competitor access to safety-critical sockets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive ECU procurement managers, foundry process engineers, industrial IoT gateway manufacturers, and memory subsystem integrators. Secondary validation drew from MIIT GB standards documentation, KBA traceability requirements, SEMI wafer capacity reports, and SEC filings of publicly traded memory suppliers. Bottom-up unit demand estimates across density tiers and end-use verticals were triangulated against top-down foundry capacity and revenue aggregation.
Calibration against historical automotive qualification timelines and foundry allocation patterns anchored the analytical framework across the analysis window. Segmentation dimensions modeled include interface architecture, density tier, qualification requirement, and regional regulatory cluster. CAGRs were derived from supply-demand balance projections incorporating automotive domain controller consolidation rates and China domestic procurement mandate enforcement intensity. Wafer supply concentration indices and certification pipeline backlogs served as industry-specific forecast inputs.
Sensitivities concentrate around MIIT enforcement intensity for domestic semiconductor procurement, ISO 26262 qualification timeline extensions, and NAND flash substitution acceleration in consumer execute-in-place applications. Forecasts reflect assumptions regarding foundry capacity expansion, automotive OEM consolidation trajectories, and regulatory pathway stability. Macroeconomic contraction, trade restriction escalation, or disruptive memory architecture substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Data Storage Market
Data Storage
North America SSD Caching Market
Data Storage
Japan Data Center Storage Market
Data Storage
Global Portable Data Storage Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Storage Virtualization Market
Data Storage
Zoned Flash Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Germany Data Center Storage Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
North America AMH and Storage Systems Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
NAND Flash Memory Market
Data Storage
Optical Disk Market