
 NAND Flash Memory Market | 2026-2036
NAND Flash Memory Market Size, Share, and Industry Trends Forecast 2026-2036
NAND Flash Memory Market Outlook
Korean semiconductor foundries is pivoting toward advanced 3D NAND stacking architectures to meet enterprise storage requirements. Samsung Electronics leverages vertical integration across wafer fabrication and controller design to sustain cost leadership in high-density modules. SK hynix anchors its competitive position through advanced packaging investments that reduce latency in data center deployments. Micron Technology competes primarily on technology leadership in QLC and PLC cell architectures for read-intensive workloads.
NAND flash memory constitutes a non-volatile storage technology employing floating-gate or charge-trap transistors organized in cell arrays, with current manufacturing achieving 200+ layer vertical stacks and interface speeds exceeding 2,400 MT/s through ONFI 5.0 protocols. The technology retains data without power and serves as the dominant medium for solid-state storage across consumer devices and enterprise infrastructure. 3D NAND product categories command the largest revenue share due to bit-density economics, while TLC configurations balance cost and endurance for mainstream data center adoption. Automotive applications within the application dimension represent the fastest-expanding demand pool as SDVs require localized storage for sensor fusion and over-the-air update buffering.
EPA energy efficiency standards and South Korea's K-REACH chemical disclosure framework shape manufacturing compliance costs and material sourcing protocols for NAND producers operating across multiple geographies. China's SAMR enforces domestic cybersecurity review standards for storage components deployed in critical information infrastructure, creating market access conditions distinct from other regulatory regimes. Stakeholders must monitor how divergent chemical handling and data localization requirements affect cross-border supply chain configuration and capital allocation for new fab capacity.
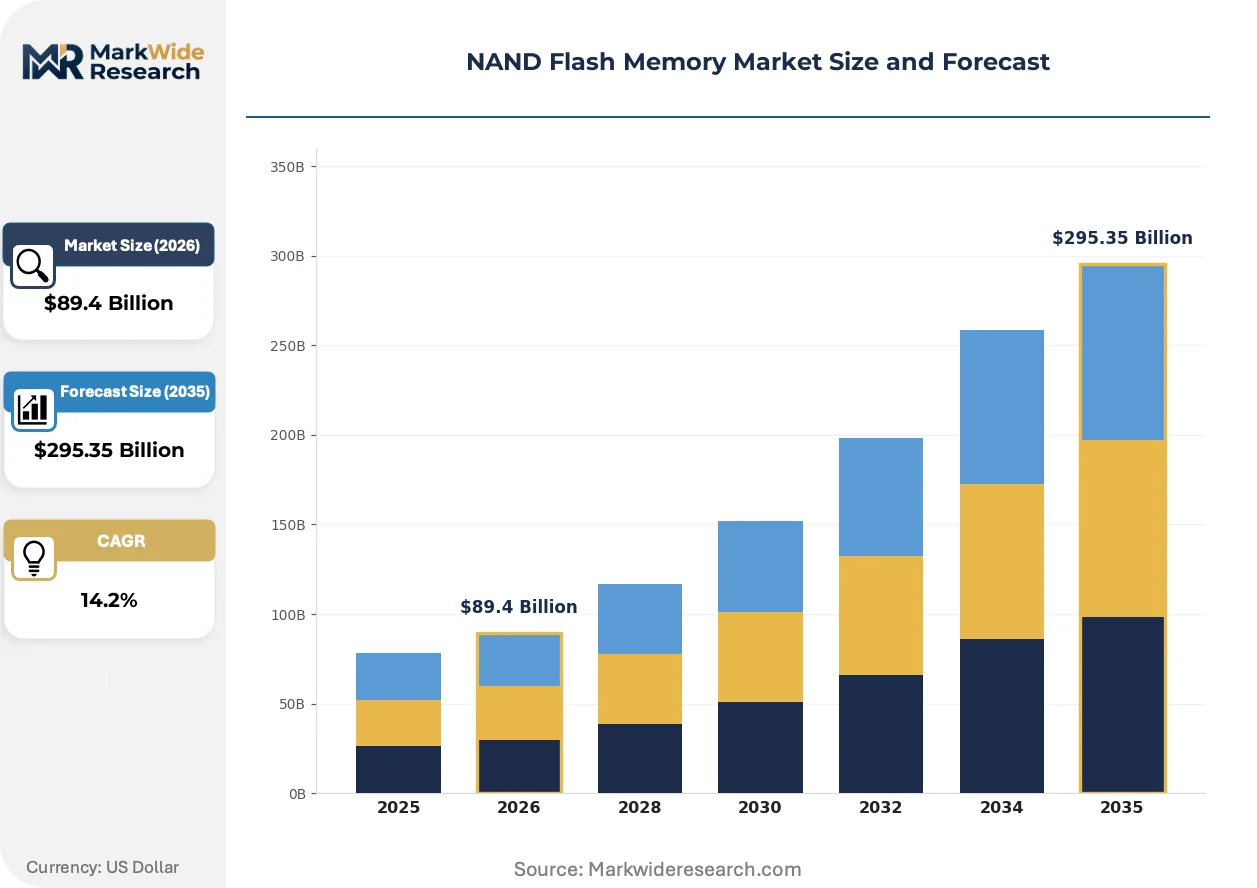
Market Dynamics
Data center operators are expanding storage procurement for AI training workloads, creating a structural pull toward higher-density 3D NAND configurations while China's dual carbon goals reshape fab energy sourcing requirements.
Growth Catalysts
- AI Training Infrastructure:Hyperscale data centers in the United States and South Korea are deploying petabyte-scale solid-state storage arrays to support generative model training pipelines.
- EPA Energy Efficiency Standards:Compliance with tightening power consumption benchmarks is accelerating fab modernization and process node transitions toward lower-energy-per-bit architectures.
- Software-Defined Vehicles:Automotive OEMs are integrating localized NAND storage for sensor fusion, over-the-air update buffering, and autonomous driving log retention.
Market Restraints
- Polysilicon and Rare Gas Volatility:Input cost swings for high-purity silicon and neon, krypton, and xenon gases constrain margin stability at the wafer fabrication stage.
- Korean and US Supply Concentration:Advanced 3D NAND manufacturing clusters heavily in South Korea and the United States, creating geographic risk exposure for downstream module assemblers.
- QLC Endurance Ceiling:Quad-level cell architectures face inherent program-erase cycle limitations that restrict deployment in write-intensive enterprise workloads.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives and tariff structures are attracting module assembly and testing investments to serve domestic and export demand.
- PLC Cell Commercialization:Penta-level cell technology convergence with advanced error correction codes promises further bit-density gains for read-heavy cold storage tiers.
- China Dual Carbon Procurement Mandates:State-backed renewable energy requirements for new fab capacity are creating first-mover advantages for producers with secured clean power offtake.
Industry Challenges
- EUV Lithography Talent Scarcity:The specialized workforce for extreme ultraviolet patterning remains concentrated among a handful of equipment vendors and foundry operators.
- SAMR Cybersecurity Certification Timelines:China's domestic review standards for storage components in critical infrastructure extend product qualification cycles and complicate launch synchronization.
- Legacy SAS Interface Integration:Enterprise storage vendors face friction bridging ONFI 5.0 native speeds with installed-base SAS/SATA backplane requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NAND Flash Memory Market |
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $295.35 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D NAND, SLC, MLC, TLC Application: Consumer Electronics, Data Centers, Industrial, Automotive Technology: Flash Translation Layer, Controller Technology, Packaging Technology, Memory Management End User: OEMs, Retailers, System Integrators, Distributors |
| Companies Covered | Samsung Electronics, SK hynix, Micron Technology, KIOXIA, Western Digital, YMTC, SanDisk, Toshiba Memory, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NAND Flash Memory Market Strategic Shifts
Process automation and layer-stacking advances are compressing cost-per-gigabyte trajectories while regulatory energy mandates and shifting procurement patterns restructure competitive priorities.
Charge-trap flash architecture is automating the transition from floating-gate designs by simplifying vertical scaling and reducing inter-cell interference. Samsung Electronics and SK hynix are deploying this technology across 200+ layer generations. The shift is automating yield improvement and accelerating bit-density roadmaps for data center SSD deployments.
South Korea's K-REACH chemical disclosure framework is expanding reporting obligations for perfluorinated compounds used in etching and cleaning processes. NAND producers are reformulating wet chemistry protocols and qualifying alternative chemistries. Module manufacturers serving Korean and European markets are prioritizing suppliers with verified K-REACH and REACH compliance documentation.
Hyperscale buyers are consolidating procurement around direct-to-fab contracts for raw NAND die, bypassing traditional module vendor channels. Cloud service providers in the United States are negotiating multi-year supply agreements with Samsung, SK hynix, and Micron. This disintermediation is most visible in Virginia and Oregon data center clusters where storage procurement teams now maintain direct foundry relationships.
NAND Flash Memory Market Segmentation
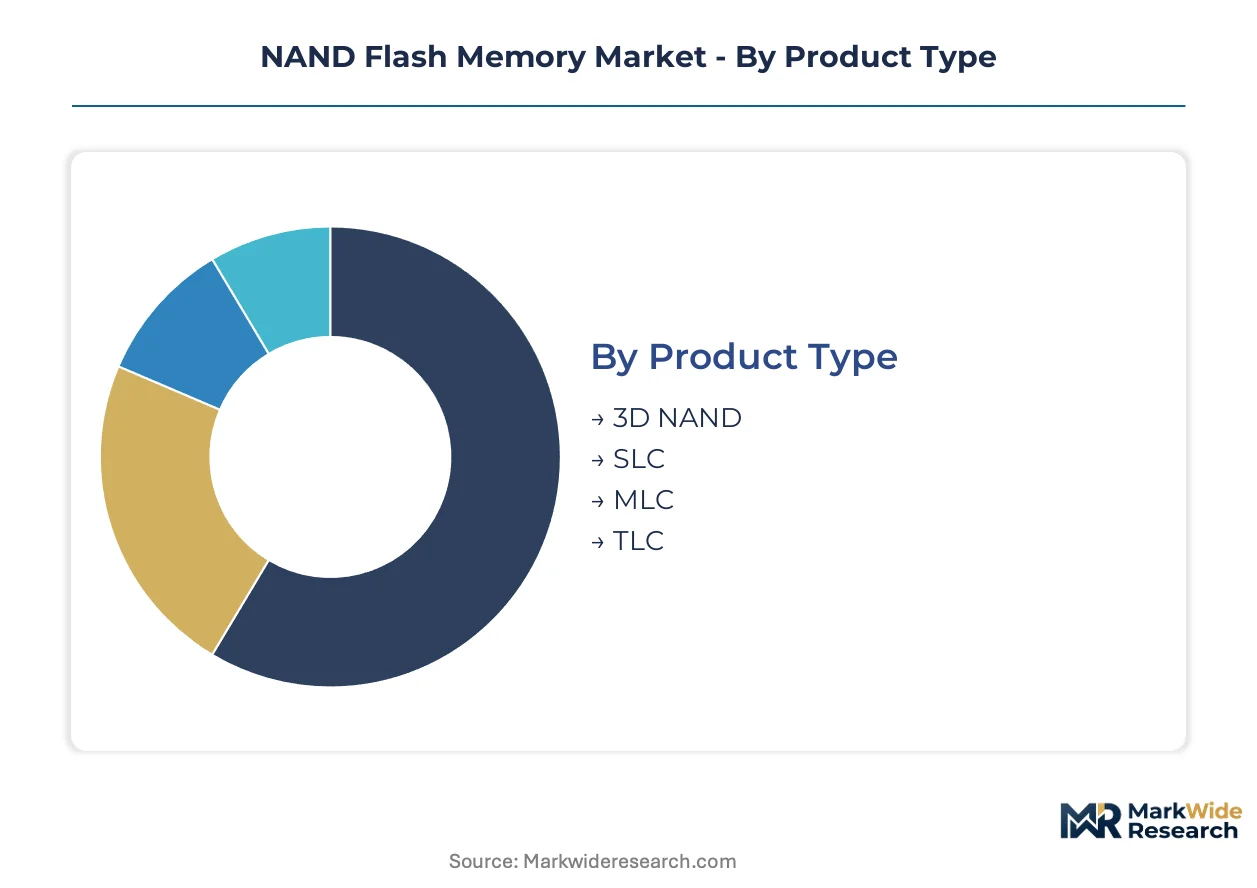
NAND flash memory segmentation reveals how architectural choices, deployment contexts, and supply chain positioning create distinct competitive arenas. Product density tiers, application workloads, and technology integration levels each command differentiated margin profiles and procurement patterns.
Product Type:
Supply concentration in advanced 3D NAND production creates tiered availability across legacy planar architectures and vertical-stacking generations.
- 3D NAND:Vertical charge-trap or floating-gate transistors stacked in 200+ layer configurations achieve bit-density economics that planar technologies cannot match. Data center operators in the United States and South Korea are consolidating procurement around 3D NAND-based SSDs for AI training infrastructure, though EUV lithography bottlenecks constrain supply elasticity for the densest configurations.
- TLC:Triple-level cell architectures store three bits per cell, balancing cost-per-gigabyte against endurance specifications for mainstream enterprise adoption. Hyperscale cloud deployments in Virginia and Oregon data center clusters favor TLC-based drives for read-intensive workloads where write amplification remains manageable.
- MLC:Multi-level cell designs retain two bits per cell, offering superior program-erase cycle durability for industrial and embedded applications.
- SLC:Single-level cell configurations maximize endurance and write performance for mission-critical caching layers and automotive control systems.
Today's leader: 3D NAND. Tomorrow's challenger: TLC as QLC and PLC densities mature.
Application:
End-use diversification across consumer, enterprise, and emerging mobility platforms reshapes capacity allocation and interface requirements.
- Data Centers:Petabyte-scale storage arrays supporting generative AI training pipelines demand high-throughput NVMe interfaces and QLC densities for cold tier economics. Supply agreements now bypass module vendors as hyperscalers negotiate directly with Samsung, SK hynix, and Micron for raw die procurement.
- Automotive:Software-defined vehicles integrate localized NAND for sensor fusion buffering, over-the-air update staging, and autonomous driving log retention. China's SAMR cybersecurity certification requirements extend qualification timelines for storage components deployed in critical information infrastructure.
- Consumer Electronics:Smartphones, tablets, and portable gaming devices drive volume absorption for mainstream density tiers.
- Industrial:Extended temperature ranges and shock resistance specifications differentiate ruggedized NAND modules for manufacturing automation and edge computing.
Data Centers absorb the highest absolute bit volumes. Automotive applications are expanding most quickly as SDV architectures proliferate.
Technology:
Controller and packaging integration capabilities determine performance ceilings and power efficiency in finished storage products.
- Controller Technology:Sophisticated error correction, wear leveling, and garbage collection algorithms manage cell degradation in high-density configurations. Samsung Electronics leverages in-house controller design to sustain cost leadership across high-density module portfolios.
- Packaging Technology:Advanced multi-chip packaging and through-silicon via integration reduce latency and footprint for data center SSD form factors. SK hynix anchors competitive positioning through packaging investments that accelerate signal integrity in enterprise deployments.
- Flash Translation Layer:Firmware abstraction layers map logical to physical addresses, isolating host systems from cell-level wear characteristics.
- Memory Management:Intelligent caching and prefetching algorithms optimize throughput for mixed read-write workloads.
Controller integration separates premium from commodity tiers. Packaging innovation is concentrating competitive advantage fastest among Korean suppliers.
End User:
Channel structure and procurement scale create divergent pricing power and technical support requirements across the value chain.
- OEMs:Original equipment manufacturers specify custom form factors and firmware for integrated device production. Direct foundry relationships are displacing traditional module vendor channels as procurement teams at major OEMs negotiate multi-year supply agreements.
- System Integrators:Enterprise IT infrastructure builders configure storage subsystems for specific workload profiles, requiring technical validation support and qualification documentation.
- Distributors:Inventory aggregation and logistics services bridge geographic and volume gaps between producers and fragmented downstream demand.
- Retailers:Consumer-facing channels prioritize brand recognition and price positioning for upgrade and replacement markets.
OEMs command the deepest technical engagement. System integrators are gaining procurement leverage fastest as enterprise SSD adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing NAND flash manufacturing capacity as producers seek jurisdictions with favorable energy costs, chemical handling protocols, and semiconductor incentive structures. South Korea and the United States currently anchor advanced 3D NAND fabrication, while China and India pursue module assembly and testing investments under divergent compliance regimes.
United States
Hyperscale data center operators in Virginia and Oregon are consolidating petabyte-scale storage procurement for AI training infrastructure, driving direct-to-fab contracting with Korean and domestic producers. EPA energy efficiency standards tighten power consumption benchmarks for fab equipment and module integration facilities. Idaho and Arizona host expanding wafer fabrication clusters where Samsung Electronics and Micron Technology operate captive cleanroom capacity.
South Korea
Domestic foundries anchor global supply for 200+ layer vertical charge-trap architectures serving enterprise SSD deployments. K-REACH chemical disclosure frameworks expand reporting obligations for perfluorinated etching compounds, elevating compliance costs for wet chemistry protocols. The Seoul Capital Area concentration of packaging and testing facilities supports SK hynix's advanced multi-chip integration for data center latency reduction.
China
State-backed renewable energy mandates under dual carbon goals are reshaping fab energy sourcing requirements for new wafer fabrication capacity. SAMR cybersecurity certification extends qualification timelines for storage components in critical information infrastructure, creating distinct market access conditions. Yangtze Memory Technologies Corporation operates domestic 3D NAND production serving local server and smartphone OEMs under GB standards compliance.
India
PLI scheme incentives and tariff structures are attracting module assembly and testing investments to serve domestic electronics manufacturing and export demand. Central Electricity Authority grid reliability standards shape power backup requirements for cleanroom operations. Gujarat and Tamil Nadu host emerging packaging facilities where system integrators configure storage subsystems for industrial automation and telecom infrastructure.
Japan
KIOXIA maintains advanced fabrication presence for enterprise and consumer NAND die production, with METI industrial policy supporting materials science R&D in Yokohama and Kitakami clusters. JIS standards govern reliability testing protocols for automotive-grade storage modules. The Nagoya-Tokyo corridor concentrates controller design and firmware development capabilities for industrial and automotive applications.
NAND Flash Memory Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent packaging and regional module assembly opportunities. The vendor base concentrates around vertically integrated foundry operators with captive wafer fabrication, controller design, and advanced packaging capabilities. Three archetypes dominate: Korean conglomerates with full-stack integration, US technology specialists with QLC/PLC cell leadership, and Chinese state-supported challengers building domestic supply security. Competitive dynamics center on EUV lithography capacity expansion and strategic partnerships for controller IP access.
Among Korean fabricators, Samsung Electronics and SK hynix exemplify the vertically integrated archetype, combining wafer fabrication with in-house controller design and multi-chip packaging investments. Micron Technology occupies a position representing US-based technology leadership in high-density cell architectures. These three anchors illustrate how geographic concentration in South Korea and the United States creates tiered supply security for hyperscale data center procurement.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK hynix |
| Micron Technology |
| KIOXIA |
| Western Digital |
| YMTC |
| SanDisk |
| Toshiba Memory |
| Intel |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals gate qualified supply and premium-tier pricing access for NAND flash memory producers, as state-backed renewable energy mandates for new fab capacity create first-mover advantages for producers with secured clean power offtake while excluding carbon-intensive suppliers from high-margin data center procurement channels.
Pricing Analysis
Distributor margins compress most severely in standard-density modules where hyperscale buyers negotiate direct-to-fab contracts for raw NAND die, bypassing traditional module vendor channels entirely. Three-tier pricing structure across premium, standard, and economy levels separates enterprise NVMe SSDs with in-house controller integration from mainstream SATA replacements and consumer-grade USB flash drives. Cost compression in QLC tiers is intensifying because bit-density economics attract hyperscale cold storage procurement, though endurance limitations prevent full substitution for TLC in write-intensive workloads. System integrators serving industrial automation exhibit highest price sensitivity, while cloud service providers in Virginia and Oregon data center clusters prioritize performance density over unit cost.
Supply Chain Analysis
High-purity polysilicon supply rests on German and US specialty chemical producers, while rare gas refining for neon, krypton, and xenon concentrates in Ukraine and Russian facilities before final purification in South Korea and Japan. Advanced 3D NAND wafer fabrication draws from photoresist formulations, EUV pellicles, and atomic layer deposition precursors as critical input categories. Single-source vulnerability for EUV lithography equipment creates chokepoint exposure for 200+ layer generation ramps. Distribution runs through module assemblers in Taiwan and Malaysia, with testing and firmware integration increasingly migrating to India under PLI scheme incentives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAND flash memory investment allocates capital across a geographic-arbitrage play where South Korea's K-REACH compliance costs exceed India's PLI-scheme supported module assembly economics by a factor that reshapes margin capture location decisions.
For Market Incumbents: Extend captive controller design capabilities to defend against emerging fabless controller vendors targeting mid-tier enterprise SSD sockets through licensing partnerships. Anchor capacity addition in Arizona and Idaho clusters where EPA energy efficiency standards align with hyperscale buyer procurement criteria, while deepening backward integration into advanced packaging to offset margin pressure from direct-to-fab die sales. For New Entrants and Emerging Players: Controller firmware optimization for automotive SDV workloads offers a technology-first wedge into a segment where China's SAMR cybersecurity certification extends qualification timelines and creates incumbent vulnerability. Target India's module assembly and testing segment as the most penetrable geography, leveraging PLI scheme incentives and Central Electricity Authority grid reliability standards as qualification collateral. Pursue system integrator partnerships for industrial automation storage subsystems as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional module assembly specialists because hyperscale procurement consolidation has disintermediated traditional brand distributors and fragmented downstream margin capture. Five-to-ten year viability hinges on securing qualified clean power offtake for captive fab capacity or locked-in controller IP access. Watch EUV lithography equipment delivery timelines as the inflection indicator for supply elasticity in 300+ layer generations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controller Design | Samsung Electronics sustains cost leadership through in-house production of flash management silicon. |
| Advanced Packaging Investment | SK hynix reduces signal latency in enterprise NVMe deployments through multi-chip integration capabilities. |
| Direct-to-Fab Supply Agreement | Hyperscale buyers in Virginia and Oregon bypass module vendors to negotiate raw die procurement with Korean producers. |
| Automotive Certification Pathway | Storage vendors navigate China's SAMR extended qualification timelines for SDV sensor fusion applications. |
| Clean Power offtake Securement | Producers with renewable energy contracts under China's dual carbon goals access premium-tier data center procurement. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with NAND flash engineering directors, hyperscale data center procurement officers, semiconductor equipment vendor sales leads, and automotive Tier 1 supplier quality managers with secondary validation against SEC 10-K filings, SEMI equipment shipment databases, customs trade records for silicon wafer imports, and EPA energy consumption disclosures. Bottom-up die shipment estimates and top-down storage system revenue analysis provided cross-verification.
Historical reference periods anchored the projection horizon through observed layer-transition timelines and interface protocol adoption curves, with segmentation modeling across product density tiers, application workloads, controller integration levels, and regional procurement clusters. CAGRs derived from bit-demand elasticity coefficients and fab capacity expansion schedules, incorporating EUV lithography throughput constraints and K-REACH chemical reformulation timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polysilicon and rare gas input cost volatility, SAMR certification timeline extensions, and hyperscale buyer consolidation patterns. A small set of named triggers warrants ongoing watch: EUV equipment delivery schedules, China's dual carbon procurement mandate enforcement intensity, and automotive SDV storage content per vehicle trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Global Portable Data Storage Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
APAC Next Generation Storage Market
Data Storage
Europe Flash Memory Market
Data Storage
Japan Data Center Storage Market
Data Storage
SSD Controller Market
Data Storage
Flash Memory Market
Data Storage
Enterprise Flash Storage Market
Data Storage
NAND Flash Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Storage Virtualization Market
Data Storage
All Flash Storage Market
Data Storage
Serial EEPROM Market
Data Storage
Transparent Caching Market