
 Data Center Storage Solutions Market | 2026-2036
Data Center Storage Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Storage Solutions Market Outlook
The gap between premium all-flash arrays and commodity hard-disk deployments is rebalancing as enterprise buyers split budgets between latency-critical workloads and archival cold storage. Dell Technologies leverages its vertical integration across controllers and media to sustain margin discipline at both tiers. Huawei Technologies anchors its position through aggressive pricing in Asia-Pacific and Africa, while Pure Storage specializes in NVMe-native architectures that dominate high-performance computing contracts.
Data center storage solutions encompass electromechanical and solid-state systems engineered to retain digital information with specified IOPS, latency, and durability parameters, serving as the persistent layer for enterprise applications, analytics engines, and cloud services. HDD remains the cost-per-gigabyte leader for exabyte-scale archives, though SSD and NVMe configurations capture the majority of new spending on primary workloads where response time determines application performance. Hybrid deployment models now outpace pure on-premises installations as enterprises distribute data across owned facilities and colocation sites to optimize resilience and geographic compliance.
FERC grid-interconnection rules in the United States, the EU Energy Efficiency Directive, and China's MIIT data center power-usage standards collectively shape facility design and equipment procurement across major markets. These frameworks force storage vendors to certify power consumption metrics and thermal profiles before qualifying for enterprise and government tenders. Stakeholders must weigh media transition timelines against stranded-asset risk as flash economics continue eroding disk's total-cost-of-ownership advantage.
Market Dynamics
Hyperscale cloud providers are compressing refresh cycles from five years to three, forcing enterprise storage vendors to rearchitect controller firmware for seamless multi-tenant density without forklift upgrades.
Growth Catalysts
- AI training clusters:Large language model deployments require petabyte-scale NVMe fabrics with sub-100 microsecond latency, pulling flash array spending into hyperscale budgets previously reserved for disk archives.
- EU Energy Efficiency Directive:Mandatory power-usage effectiveness disclosures are disqualifying legacy spinning-disk installations from public-sector tenders across Germany, France, and the Netherlands.
- Edge computing proliferation:Factory automation and autonomous vehicle development in Michigan, Bavaria, and Guangdong province are spawning distributed storage nodes that replicate data to central facilities.
Market Restraints
- NAND flash supply concentration:Three Korean and Taiwanese foundry operators control wafer output, exposing array pricing to memory cycle volatility and geopolitical export restrictions.
- Stranded HDD assets:Seven-year depreciation schedules on enterprise disk systems clash with three-year flash TCO breakeven points, freezing capital release for midmarket buyers.
- China MIIT power standards:New data center PUE ceilings in Beijing and Shanghai are blocking certifications for non-all-flash primary storage configurations above 1.3 efficiency ratios.
Strategic Opportunities
- India data center buildout:Mumbai and Chennai hyperscale campuses lack indigenous storage assembly capacity, creating import substitution openings for modular NVMe chassis with local SKD assembly.
- Computational storage convergence:Processing-in-memory controllers from Samsung and Kioxia are collapsing analytics pipeline latency, enabling new appliance categories that fuse compute and persistent tiers.
- US IRA clean energy credits:Storage vendors qualifying renewable-powered manufacturing facilities gain preference in federal cloud procurement scoring matrices.
Industry Challenges
- Firmware engineering scarcity:Controller software talent concentrates in Silicon Valley and Tel Aviv, forcing vendors to acquire teams at premium multiples or outsource to Taiwanese ODMs with weaker IP protection.
- Interoperability certification backlog:VMware vSAN, Kubernetes CSI, and S3 API compliance testing queues stretch 14-18 months, delaying product launches and ceding early-mover advantage to incumbents with pre-certified platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Storage Solutions Market |
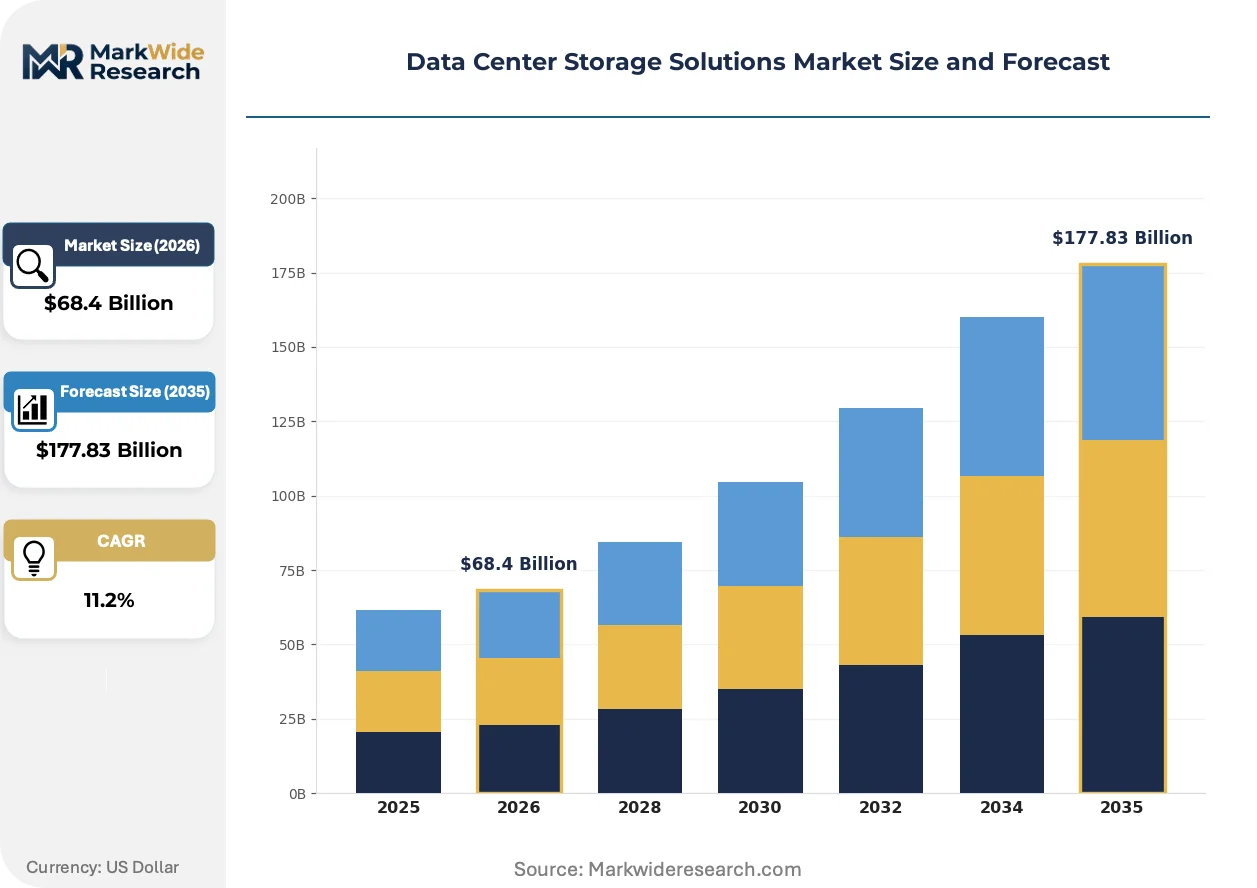
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $177.83 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDD, SSD, Hybrid Drives, Tape Storage Deployment Model: On-premises, Cloud, Hybrid, Colocation End User: Large Enterprises, SMEs, Cloud Providers, Managed Service Providers Technology: NVMe, Fibre Channel, iSCSI, SAS |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, Huawei Technologies, IBM, Pure Storage, Hitachi Vantara, Infinidat, Supermicro Computer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Storage Solutions Market Strategic Shifts
Storage infrastructure is bifurcating into latency-optimized primary tiers and thermally-optimized archival layers, with software-defined placement engines governing data movement between them.
Computational storage drives with embedded ARM processing cores are automating data reduction and encryption at the device level. Hyperscale operators in Northern Virginia and Frankfurt are qualifying these drives for analytics workloads that previously required separate server nodes. The compression of host CPU overhead is automating total cost reductions of 15-20% at rack scale.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are banning specific flame retardants and refrigerants used in storage chassis and cooling systems. Array manufacturers must redesign thermal interfaces and recertify supply chains before 2027 compliance deadlines. European enterprise buyers are now requiring pre-certification documentation in RFPs, favoring vendors with advanced substitution roadmaps.
Consumption-based financing models are displacing capital purchase contracts for primary storage. Colocation providers in Dallas-Fort Worth and Amsterdam are offering storage-as-a-utility with metered IOPS pricing, transferring depreciation risk to vendors. Financial buyers in healthcare and media verticals are consolidating vendor relationships to three-year subscription frameworks with automatic refresh clauses.
Data Center Storage Solutions Market Segmentation
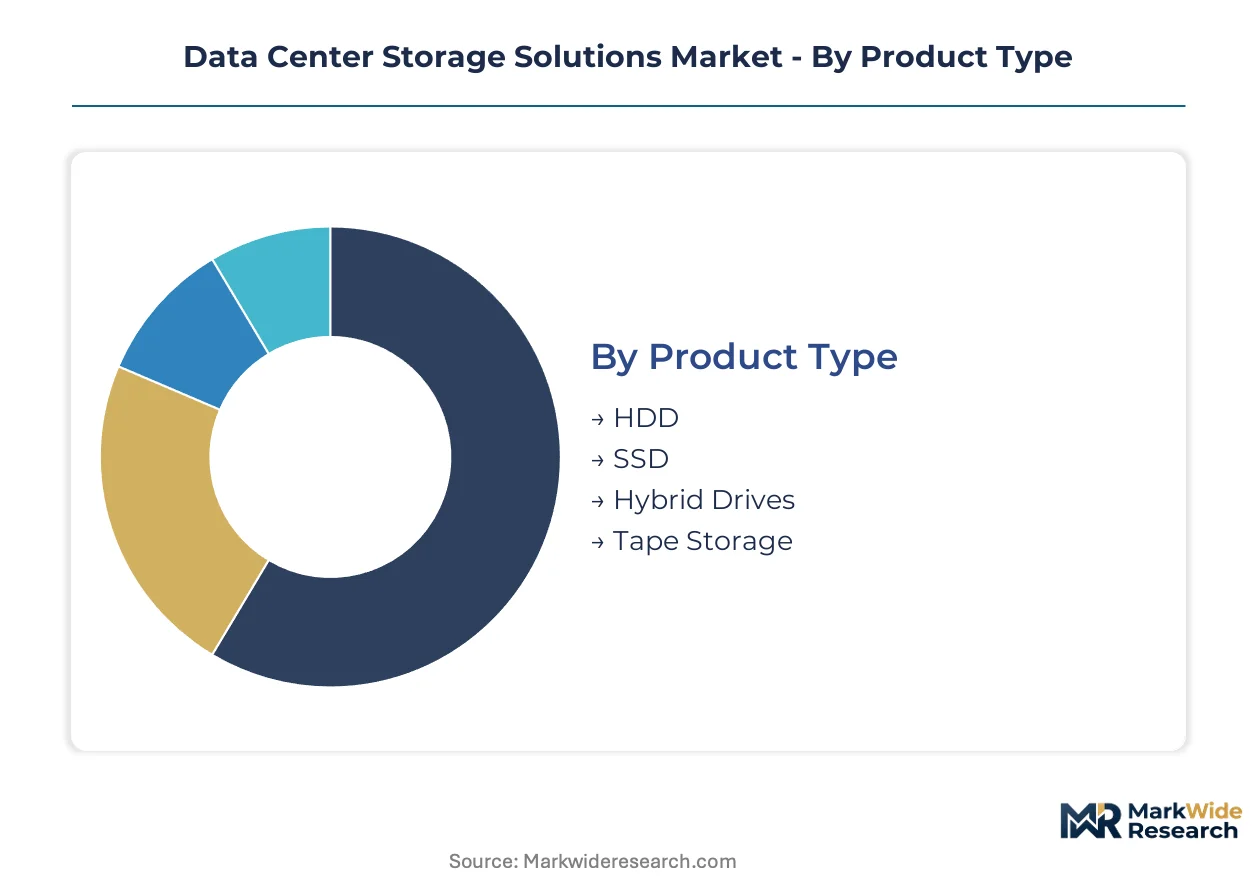
Storage procurement patterns diverge sharply across buyer archetypes, with hyperscale cloud operators prioritizing density-optimized NVMe fabrics while midmarket enterprises stretch depreciation schedules on hybrid configurations. Segment boundaries are blurring as software-defined controllers abstract physical media differences, yet hardware selection still determines total cost curves for latency-sensitive versus archival workloads.
Product Type:
Cost-per-gigabyte thresholds and workload latency requirements separate buyers into distinct hardware tiers with incompatible refresh cycles.
- HDD:Electromechanical platters deliver the lowest acquisition cost per terabyte for exabyte-scale archives. Demand concentrates in hyperscale cold storage facilities across Northern Virginia and Dallas-Fort Worth, where FERC grid-interconnection rules favor power-dense disk enclosures over flash for infrequently accessed datasets.
- SSD:NAND-based solid-state media eliminates rotational latency for primary workloads. Cloud providers in Frankfurt and Amsterdam are displacing disk for analytics pipelines as EU Energy Efficiency Directive disclosures expose spinning-disk power overhead in PUE calculations.
- Hybrid Drives:Tiered cache architectures combine flash front-ends with disk back-ends for midmarket budget constraints.
- Tape Storage:Linear magnetic media serves air-gapped compliance archives with 30-year retention mandates.
HDD leads volumes today; SSD is gaining share fastest.
Deployment Model:
Control over data sovereignty and latency budgets drives facility selection, with regulated industries maintaining on-premises assets while digital-native firms externalize infrastructure.
- On-premises:Owned facilities retain sensitive workloads under direct administrative control. Financial services clusters in New York and London maintain on-premises NVMe arrays for trading systems where microseconds determine profitability.
- Cloud:Hyperscale rental eliminates capital expenditure for variable workloads. SaaS vendors in Bengaluru and São Paulo are migrating primary storage to cloud to redirect engineering talent toward application development.
- Hybrid:Orchestrated data placement spans owned and rented infrastructure.
- Colocation:Wholesale data center leases offer physical control with outsourced facility operations.
On-premises retains the largest installed base; cloud deployments are expanding most quickly.
End User:
Procurement scale and technical staffing depth determine whether buyers prioritize vendor-managed services or in-house platform engineering.
- Large Enterprises:Fortune 500 technology budgets support dedicated storage engineering teams. Automotive manufacturers in Michigan and Bavaria deploy edge-to-core NVMe fabrics for autonomous vehicle development pipelines.
- SMEs:Constrained IT headcount favors converged appliances with embedded management. Regional healthcare networks across Texas and Florida are consolidating onto hyperconverged platforms to reduce specialist hiring requirements.
- Cloud Providers:Hyperscale operators design custom storage servers for multi-tenant density.
- Managed Service Providers:Multi-tenant platforms aggregate demand from sub-scale buyers.
Large enterprises dominate current spending; cloud providers are climbing the fastest.
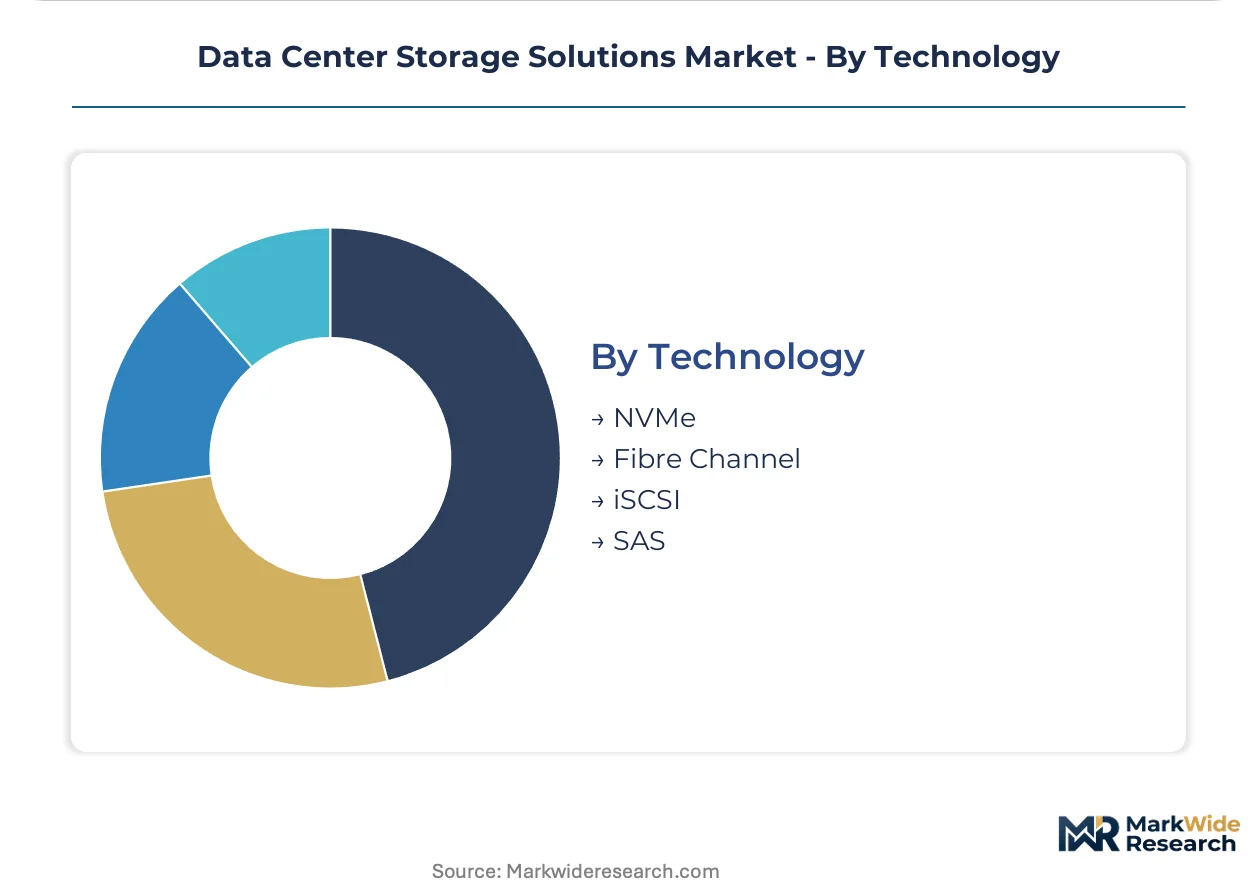
Technology:
Protocol selection locks buyers into specific latency-throughput tradeoffs and ecosystem compatibility constraints.
- NVMe:PCIe-native command sets reduce overhead versus legacy SCSI translations. AI training clusters in Guangdong province and Northern California require NVMe-oF fabrics for parameter server synchronization at scale.
- Fibre Channel:Lossless transport protocol persists in mainframe-attached enterprise storage. German automotive suppliers maintain Fibre Channel SANs for ERP systems where protocol stability outweighs bandwidth efficiency.
- iSCSI:Ethernet-based block transport enables IP-routed storage without dedicated fabrics.
- SAS:Serial-attached SCSI serves midmarket direct-attached configurations.
Fibre Channel retains the largest legacy footprint; NVMe shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Storage engineering talent clusters in Northern Virginia, Frankfurt, and Singapore anchor procurement decisions for hyperscale operators. These concentrations shape regional deployment patterns as facility designers optimize for latency to major cloud campuses.
United States
FERC grid-interconnection rules favor power-dense storage configurations in Northern Virginia and Dallas-Fort Worth metro clusters. The Inflation Reduction Act's clean energy credits reward renewable-powered manufacturing facilities in federal procurement scoring. Hyperscale cloud providers in Ashburn and Loudoun County compress refresh cycles to three years, forcing vendor firmware rearchitecture.
Germany
EU Energy Efficiency Directive mandates disqualify legacy spinning-disk installations from public-sector tenders across Frankfurt and Berlin. REACH substance restrictions and F-Gas Regulation phase-downs ban specific flame retardants in storage chassis by 2027. Automotive suppliers in Bavaria maintain Fibre Channel SANs for ERP systems where protocol stability outweighs bandwidth efficiency.
China
MIIT power-usage standards impose PUE ceilings blocking non-all-flash primary storage certifications above 1.3 efficiency ratios in Beijing and Shanghai. Dual carbon goals accelerate displacement of disk archives in hyperscale facilities. AI training clusters in Guangdong province require NVMe-oF fabrics for parameter server synchronization at scale.
India
Mumbai and Chennai hyperscale campuses lack indigenous storage assembly capacity, creating import substitution openings for modular NVMe chassis. BIS certification requirements and PLI scheme incentives favor local SKD assembly partnerships. Regional healthcare networks across Maharashtra consolidate onto hyperconverged platforms to reduce specialist hiring requirements.
Japan
METI efficiency standards and JIS certification requirements shape enterprise storage procurement in Tokyo and Osaka. Financial services clusters maintain on-premises NVMe arrays for trading systems where microseconds determine profitability. Edge computing nodes in Nagoya and Kyushu replicate factory automation data to central facilities.
Data Center Storage Solutions Market Competitive Environment
Top-tier vendors anchor hyperscale cloud contracts, while mid-tier specialists capture edge computing and regional enterprise deployments. The market structure reflects a bifurcation between scale-driven incumbents with captive controller firmware and nimble challengers with NVMe-native architectures. Strategic archetypes include vertically integrated hardware manufacturers, software-defined storage pure-plays, and Asian challengers with aggressive pricing in emerging markets. Dominant competitive moves encompass multi-year subscription financing frameworks and computational storage convergence through processing-in-memory controllers.
Within the vertically integrated tier, Dell Technologies exemplifies margin discipline across controller and media production. Pure Storage occupies a position as the NVMe-native architecture specialist capturing high-performance computing contracts. Huawei Technologies represents the Asia-Pacific pricing challenger anchoring market share in Africa and emerging Asian markets through aggressive tender positioning.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Huawei Technologies |
| IBM |
| Pure Storage |
| Hitachi Vantara |
| Infinidat |
| Supermicro Computer |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation phase-down schedules gate qualified supply for storage chassis cooling systems, restricting premium-tier pricing access to vendors with certified thermal interface redesigns and compliant refrigerant substitution roadmaps ahead of 2027 deadlines.
Pricing Analysis
Bundled subscription frameworks and unbundled capital purchase splits define buyer-vendor negotiations, with consumption-based financing displacing outright ownership for primary storage tiers. Three-tier pricing structure across all-flash premium, hybrid standard, and disk-based economy levels reflects certification grade and after-sales service bundling. Cost compression in midmarket hybrid configurations is intensifying because hyperscale cloud providers compress refresh cycles and force firmware rearchitecture investments. SME buyers exhibit highest price sensitivity due to constrained IT headcount and depreciation schedule rigidity, while hyperscale operators prioritize density-optimized TCO over unit acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for controller refurbishment and NAND flash module remanufacturing are emerging as margin-recovery mechanisms as hyperscale operators demand three-year refresh guarantees. Wafer output concentrates in South Korea, Taiwan, and Japan, with controller firmware engineering anchored in Silicon Valley and Tel Aviv. Array assembly draws from precision machining in Mexico and Malaysia, with final integration tethered to regional compliance certification hubs. Single-source vulnerability in Korean and Taiwanese foundry operators exposes pricing to memory cycle volatility. Distribution runs through direct hyperscale procurement teams in Northern Virginia and Frankfurt, supplemented by channel partners serving midmarket enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center storage solutions function as a stable compounder, with AI training cluster deployments pulling petabyte-scale NVMe spending into budgets previously reserved for disk archives and sustaining replacement demand across economic cycles.
For Market Incumbents: Anchor hyperscale cloud contracts through multi-year subscription frameworks with automatic refresh clauses that transfer depreciation risk from buyers. Deepen captive supply of controller ASICs to defend margin position against Asian challengers with aggressive tender positioning. Fortify firmware engineering teams in Tel Aviv and Silicon Valley against acquisition premiums driven by talent scarcity.
For New Entrants and Emerging Players: Cloud-native sales channels and developer-centric platform marketplaces offer low-friction entry points for NVMe-native architectures targeting SaaS vendors in Bengaluru and São Paulo. White-space concentrates in India's Mumbai and Chennai hyperscale campuses, where indigenous storage assembly capacity gaps create import substitution openings for modular chassis with local SKD assembly partnerships. Computational storage convergence through processing-in-memory controllers provides differentiated positioning against established array vendors.
For Investors and Strategic Acquirers: Roll-up economics work for regional managed service providers because fragmented midmarket demand favors multi-tenant platforms that aggregate sub-scale buyers under unified infrastructure management. Long-term viability rests on five-to-ten year subscription revenue visibility from healthcare and media verticals consolidating vendor relationships. Monitor FERC grid-interconnection rule amendments and EU Energy Efficiency Directive enforcement intensity as inflection indicators for hardware refresh timing and certified supplier list composition.
| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-oF Fabric Certification | Qualification for AI training clusters in Guangdong and Northern California hyperscale facilities. |
| Computational Storage Convergence | Processing-in-memory controllers from Samsung and Kioxia collapse analytics pipeline latency at rack scale. |
| Local SKD Assembly Partnership | BIS certification and PLI scheme incentives unlock India's Mumbai and Chennai hyperscale procurement. |
| Subscription Financing Framework | Metered IOPS pricing transfers depreciation risk to vendors in Dallas-Fort Worth colocation markets. |
| Thermal Interface Redesign | REACH and F-Gas compliance secures European enterprise RFP participation through 2027 deadlines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center infrastructure executives, storage engineering directors, hyperscale procurement officers, and colocation facility operators with secondary validation against SEC filings, hyperscaler capex disclosures, FERC grid-interconnection dockets, and EU regulatory implementation notices. Bottom-up unit economics and top-down market sizing triangulated across deployment model, technology protocol, and end-user archetype segmentation.
Segment-weighting approaches applied differential growth assumptions across NVMe, Fibre Channel, iSCSI, and SAS protocol tiers, with HDD, SSD, hybrid drive, and tape storage product categories modeled separately across on-premises, cloud, hybrid, and colocation deployment models. CAGRs derived from shipment volume trajectories and average selling price evolution throughout the forecast period, incorporating AI training cluster capacity buildouts, EU Energy Efficiency Directive compliance timelines, and China MIIT PUE ceiling enforcement as industry-specific demand drivers.
The model assumes a particular technology adoption path; alternative pathways for computational storage and processing-in-memory architectures would alter the outlook for traditional controller-based array demand. Practitioners should monitor NAND flash foundry utilization rates, hyperscale refresh cycle compression announcements, and regulatory pre-certification documentation requirements in European RFPs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Ceph Storage Solutions Market
Data Storage
Hardware Storage Market
Data Storage
SSD Controller Market
Data Storage
Next-Generation Storage Market
Data Storage
OTG Pen Drive Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Optical Disk Market
Data Storage
NOR Flash Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
China Solid-State Drive Market
Data Storage
AI Powered Storage Market
Data Storage
Flash Memory Market
Data Storage
Enterprise Flash Storage Market
Data Storage
APAC Next Generation Storage Market