
 Data Storage Market | 2026-2036
Data Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Data Storage Market Intelligence
The adoption of NVMe over Fabrics (NVMe-oF) protocols is narrowing the performance gap between direct-attached storage and networked storage systems. This technological shift creates new opportunities for specialized vendors. Pure Storage, Inc. specializes in all-flash arrays, differentiating through its unified storage platform. Microsoft Corporation leverages its vast cloud footprint to deliver integrated storage services, while Dell Technologies Inc. competes across the full spectrum of enterprise hardware from high-end arrays to hyper-converged infrastructure.
Data storage encompasses the technologies and media used to retain digital information. These systems utilize magnetic, optical, or semiconductor media, with performance often measured by IOPS and throughput. Their primary commercial function is to provide reliable retention for applications from backup to real-time processing. Flash Storage, including Solid State Drives, now commands the primary storage segment for enterprise workloads, while Cloud Storage represents the fastest-growing category for scalable data backup and archiving solutions.
Data governance regulations like the EU's GDPR and the US's HIPAA mandate strict controls on data residency, access, and security. In parallel, data localization laws in countries such as India and Brazil are forcing enterprises to reconsider their cloud and data center deployment strategies. Vendor selection increasingly depends on the ability to provide solutions that support multi-cloud data mobility while ensuring compliance across fragmented regulatory environments.
Market Dynamics
The proliferation of stringent data sovereignty and localization mandates represents the central structural force shaping the data storage market. Regulations like the EU's GDPR and similar frameworks in India and Brazil dictate where data can reside, compelling enterprises to adopt hybrid and multi-cloud architectures.
Growth Catalysts
- Artificial Intelligence Workloads:The expansion of AI and machine learning applications demands high-throughput, low-latency storage systems, driving investment in all-flash arrays and NVMe-based infrastructure to accelerate data processing for training models.
- Healthcare Data Expansion:Growth in the healthcare sector, particularly in managing large-scale medical imaging archives like PACS and electronic health records, necessitates scalable and compliant storage solutions to ensure data integrity and accessibility.
- Regulatory Compliance Mandates:Data protection regulations such as the US's HIPAA require secure, long-term retention and auditable access controls for sensitive information, creating persistent demand for compliant enterprise storage and archiving platforms.
Market Restraints
- High Capital Expenditure:The significant upfront investment required to build, cool, and power modern, high-density data centers acts as a major barrier to entry and expansion, particularly for smaller enterprises.
- Semiconductor Supply Concentration:The geographic concentration of advanced semiconductor fabrication in East Asia creates supply chain vulnerabilities for critical components like NAND flash and DRAM, exposing the market to geopolitical risks and price volatility.
- Power Consumption and Cooling Costs:Increasing storage density and performance leads to higher power consumption and heat generation, driving up operational expenses for data center operators and constraining physical deployment in certain locations.
Strategic Opportunities
- Edge Computing Infrastructure:The rise of edge computing for applications like IoT and autonomous systems creates a new frontier for decentralized storage solutions that offer low-latency data access and processing away from centralized data centers.
- Storage for Quantum Computing:As quantum computing matures, a nascent opportunity is emerging for specialized storage systems capable of managing the unique data input/output requirements and state information associated with quantum workloads.
- Data Sovereignty-as-a-Service:Vendors can develop specialized service offerings that help enterprises navigate complex data residency laws by providing compliant storage zones and data mobility tools across multiple jurisdictions.
Industry Challenges
- Multi-Cloud Management Complexity:Enterprises face significant operational challenges in managing data, security, and costs across disparate public and private cloud storage environments, requiring sophisticated orchestration tools and specialized skills. *Legacy System Integration: Integrating modern storage protocols like NVMe-oF with existing legacy IT infrastructure can be complex and costly, often creating performance bottlenecks and delaying technology adoption cycles.
- Talent Scarcity:A persistent shortage of IT professionals with expertise in modern storage architecture, data governance, and cloud-native technologies hinders the ability of organizations to fully leverage advanced storage capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Storage Market |
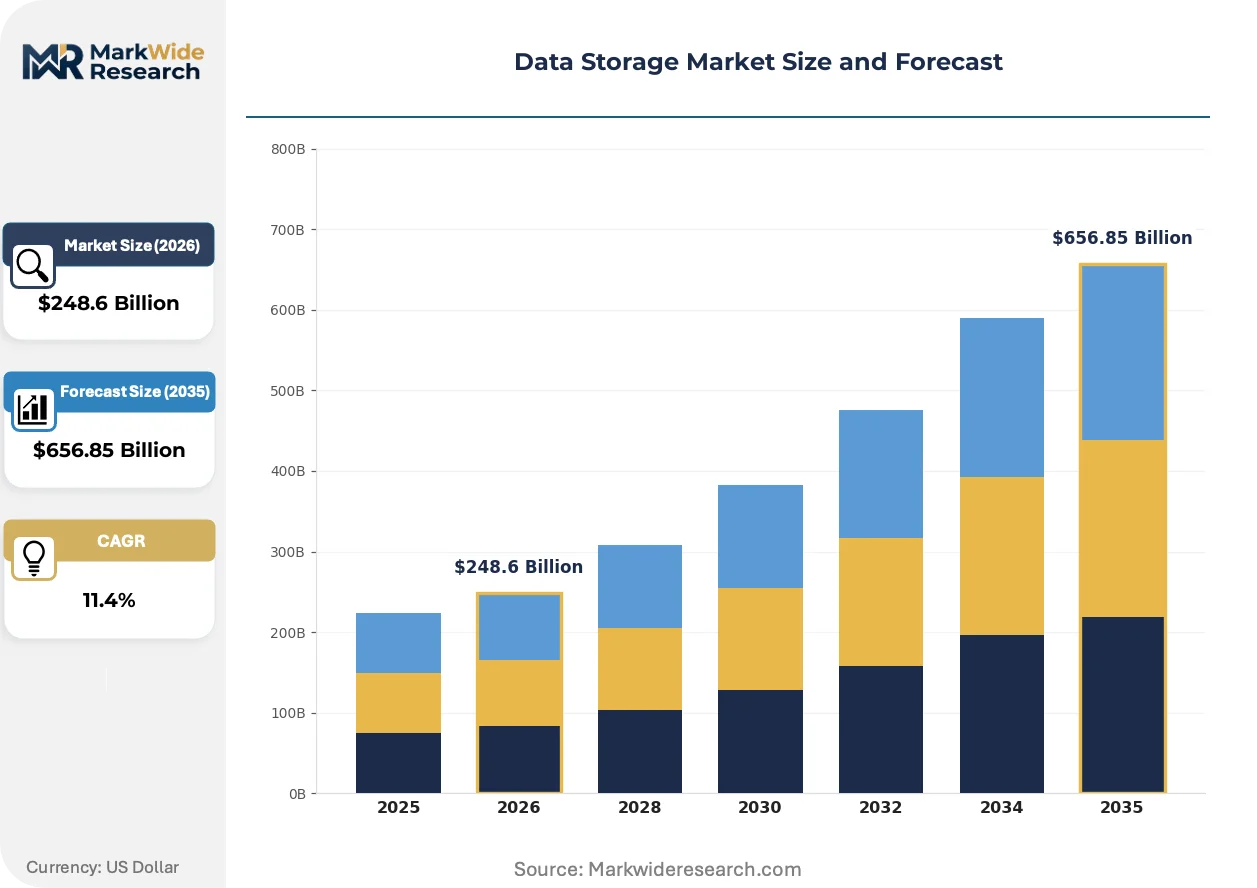
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $656.85 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Storage, Hard Disk Drives, Solid State Drives, Cloud Storage Technology: NVMe, SATA, SAS, SSD, HDD End User: Enterprises, Government, Education, Healthcare Application: Data Backup, Archiving, Disaster Recovery, Primary Storage |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, IBM Corporation, NetApp, Inc., Dell Technologies Inc., Seagate Technology Holdings Public Limited Company, Western Digital Corporation, Pure Storage, Inc., Hewlett Packard Enterprise Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Storage Market Strategic Shifts & Innovations
A fundamental transition toward software-defined and disaggregated architectures is underway. This shift enables greater flexibility in deploying and managing storage resources to meet the demands of both performance-intensive applications and stringent data compliance frameworks across hybrid cloud environments.
Hybrid storage arrays combine different media types, primarily using flash storage for performance-critical data and hard disk drives for high-capacity, less-frequently accessed data. Enterprise IT departments are increasingly adopting these systems to balance performance requirements with budget constraints. This technology is hybridizing the primary storage segment, allowing organizations to achieve flash-like performance for active workloads while leveraging the cost-effectiveness of disk for bulk data.
Data localization laws, such as those implemented in India and Brazil, are directly influencing infrastructure deployment strategies. These regulations mandate that specific categories of citizen data must be stored on servers within national borders, compelling global cloud providers and multinational corporations to invest in local data center capacity. The financial services and e-commerce sectors are most affected, re-architecting their data flows to ensure compliance.
A notable shift in purchasing behavior involves moving from large, upfront capital expenditures to consumption-based acquisition models for on-premises storage. This disrupts traditional reseller channels by enabling vendors to offer Storage-as-a-Service (STaaS), where customers pay a subscription based on usage. This model is gaining traction in North American and European markets where enterprises seek to align infrastructure costs with business demand.
Data Storage Market Segmentation
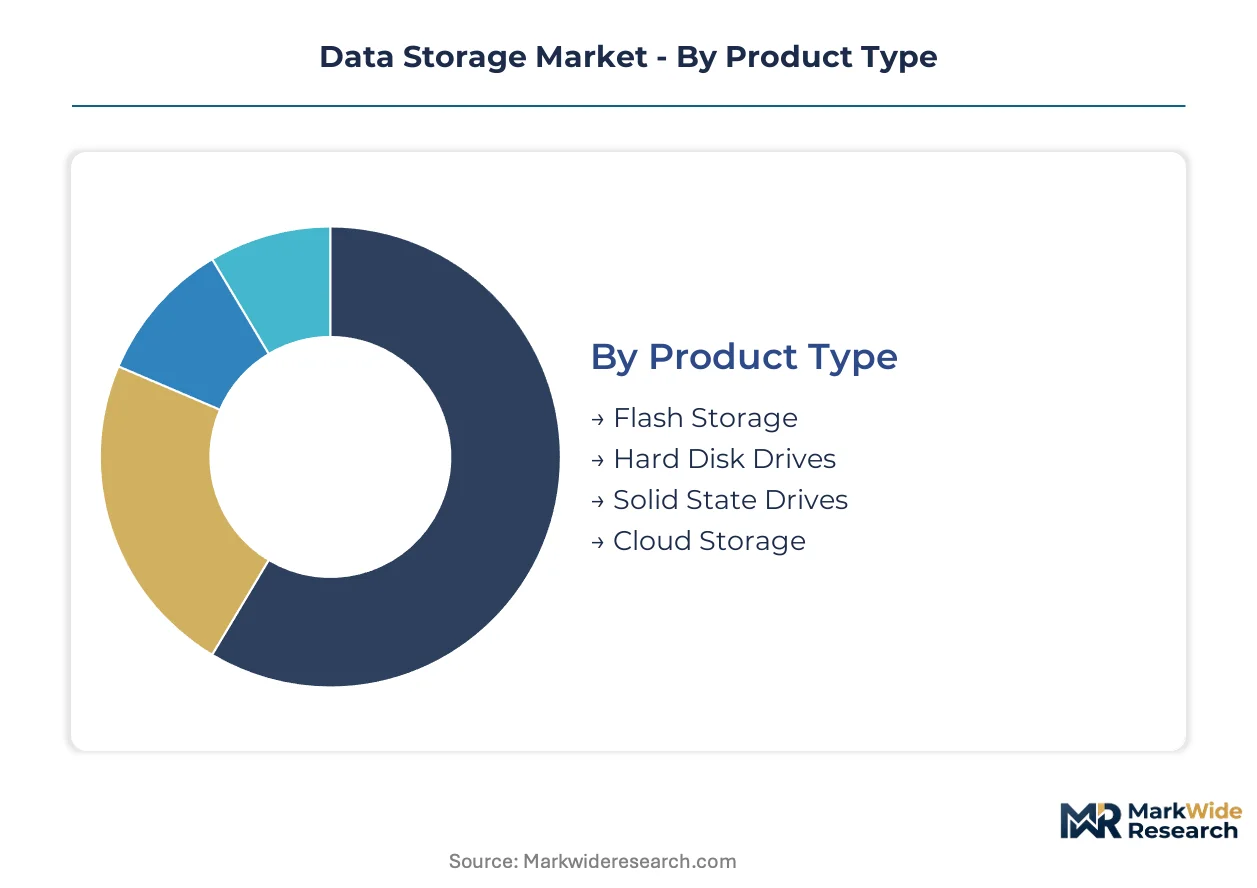
Market segmentation provides a granular view of the data storage landscape, revealing distinct product types, technologies, end-user behaviors, and application demands. Understanding these segments is crucial for identifying areas of concentrated investment and emerging opportunities across the global market. This detailed breakdown helps stakeholders tailor solutions to specific operational and regulatory requirements.
Product Type:
Data storage product types exhibit varying refresh cycles, with some media experiencing rapid obsolescence while others offer long-term retention capabilities.
- Flash Storage:Flash storage utilizes semiconductor-based memory cells for data retention, providing high-speed read/write capabilities and low latency for performance-critical workloads. Enterprise data centers in Germany and Japan demand flash for performance-intensive database and virtualization applications, driven by real-time analytics requirements.
- Cloud Storage:Cloud storage delivers data retention services over a network, abstracting underlying infrastructure from the user through a consumption-based model. Global enterprises increasingly adopt cloud storage for scalable backup and archiving solutions, particularly to meet EU GDPR and US HIPAA compliance needs.
- Hard Disk Drives:These devices store data on rapidly rotating platters coated with magnetic material, offering high capacity at a lower cost per gigabyte.
- Solid State Drives:SSDs are data storage devices that use integrated circuit assemblies as memory, providing faster access times and greater durability than traditional HDDs.
Hard Disk Drives anchors the volume base while Cloud Storage gains share at the steepest rate.
Technology:
Different storage technologies cater to distinct performance and cost profiles, influencing their adoption across various application tiers.
- NVMe:NVMe (Non-Volatile Memory Express) is a host controller interface and storage protocol designed specifically for solid-state drives, leveraging PCIe for high throughput and low latency. AI and machine learning initiatives in the United States require NVMe for accelerating data processing during model training and inference.
- SSD:Solid State Drives (SSDs) are non-volatile storage devices that store data on flash memory, offering significantly faster data access and boot times compared to HDDs. Businesses in the UK utilize SSDs extensively for primary storage in servers and workstations, benefiting from their durability and speed for critical applications.
- SATA:Serial Advanced Technology Attachment (SATA) is a computer bus interface that connects host bus adapters to mass storage devices such as hard disk drives and optical drives.
- SAS:Serial Attached SCSI (SAS) is a point-to-point serial protocol that moves data to and from computer storage devices, offering higher performance and reliability than SATA for enterprise environments.
- HDD:Hard Disk Drives (HDDs) are electro-mechanical data storage devices that store and retrieve digital data using magnetic storage.
SATA remains a cost-effective solution for general-purpose storage, as NVMe technology expands most quickly for high-performance use cases.
End User:
The specific requirements of end-user segments dictate the scale and security features demanded from data storage solutions.
- Enterprises:Enterprises encompass large corporations across various sectors, requiring robust, scalable, and secure storage infrastructure for diverse applications and vast data volumes. Financial institutions in Singapore prioritize enterprise storage for regulatory compliance and high-transaction volume processing.
- Healthcare:The healthcare sector includes hospitals, clinics, and research institutions, handling sensitive patient data and large medical images from PACS systems. Healthcare providers in Canada adopt specialized storage to manage PACS archives and EHRs, ensuring data integrity and accessibility under Health Canada guidelines.
- Government:Government agencies require secure and compliant storage solutions for public records, defense data, and citizen information, often with long-term retention mandates.
- Education:Educational institutions utilize data storage for student records, research data, learning management systems, and administrative functions.
Government organizations maintain a substantial data footprint, while the healthcare sector exhibits the steepest expansion trajectory in storage demand.
Application:
Data storage applications vary significantly in their performance, availability, and retention requirements, influencing technology selection.
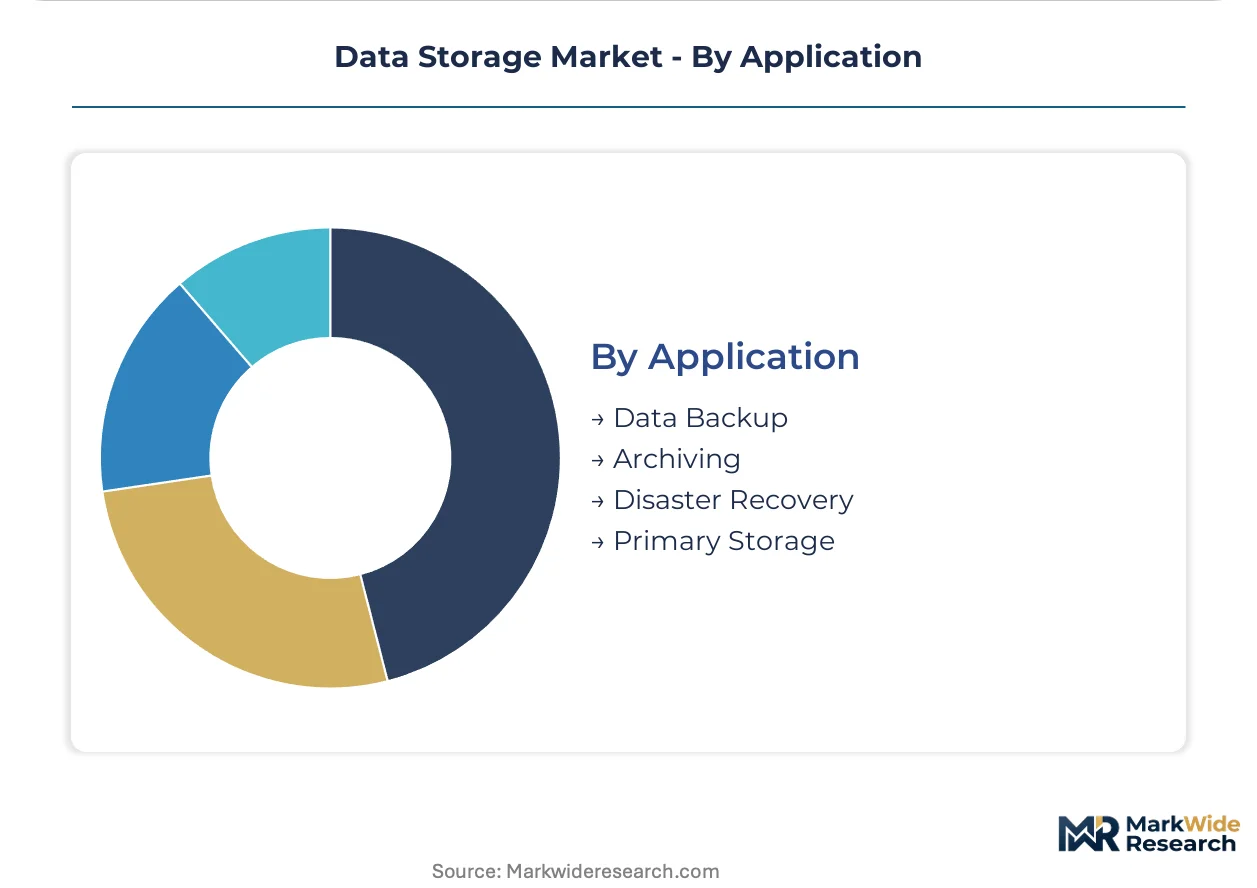
- Primary Storage:Primary storage refers to systems used for active, frequently accessed data that applications require for real-time operations, supporting transactional and analytical workloads. E-commerce platforms in India rely on primary storage for their transactional databases, ensuring rapid customer interactions and order processing.
- Data Backup:Data backup involves creating copies of data to restore in case of data loss or corruption, serving as a fundamental component of disaster recovery and business continuity plans. Organizations across Europe implement data backup solutions to comply with GDPR data protection requirements and maintain business continuity.
- Archiving:Archiving involves moving older, less frequently accessed data to long-term, cost-effective storage solutions for regulatory compliance or historical record-keeping.
- Disaster Recovery:Disaster recovery applications focus on restoring IT infrastructure and data after a catastrophic event, ensuring business continuity and minimal downtime.
Archiving provides long-term, cost-effective data retention, while Primary Storage solutions are climbing the fastest due to real-time processing needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global data storage market exhibits a complex interplay between domestic demand and the strategic positioning of data center infrastructure. Countries with robust digital economies often become net importers of advanced storage solutions, while others focus on building localized data residency capabilities to support national digital sovereignty initiatives.
United States
Demand for high-performance data storage in the United States stems from the rapid expansion of AI workloads and large-scale cloud computing platforms. The US's HIPAA regulations mandate stringent security and retention requirements for healthcare data, driving investment in compliant storage. Northern Virginia continues to concentrate hyperscale data center development, supporting the nation's digital infrastructure.
Germany
German enterprises require flash storage for performance-intensive database and virtualization applications, fueled by advanced manufacturing and automotive sectors. The EU's GDPR significantly influences data storage architecture choices, emphasizing data protection and residency within the European Union. Frankfurt serves as a major internet exchange point and data center hub, attracting significant storage infrastructure investment.
India
India's e-commerce platforms and burgeoning digital services sector drive strong demand for primary storage to handle transactional databases and real-time processing. Data localization laws in India compel global cloud providers to establish local data centers, ensuring citizen data resides within national borders. Major IT hubs like Bangalore and Hyderabad are seeing increased investment in compliant storage solutions.
Japan
Japanese enterprises prioritize high-speed, low-latency storage for mission-critical applications and scientific research, particularly in robotics and advanced analytics. METI guidelines encourage secure data management practices, impacting storage procurement decisions across industries. Tokyo's dense urban infrastructure supports a sophisticated network of data centers, catering to the country's technological demands.
Canada
Healthcare providers in Canada require specialized storage to manage PACS archives and electronic health records, ensuring data integrity and accessibility. Health Canada guidelines dictate secure, long-term retention policies for sensitive patient information, influencing storage solution design. Toronto and Montreal are key data center markets, serving as critical points for data processing and storage within the country.
Data Storage Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established technology giants competing alongside specialized vendors. This market structure allows for both broad-spectrum hardware and integrated service offerings. Strategic archetypes include diversified enterprise hardware providers, cloud infrastructure specialists, and all-flash array innovators. Dominant competitive moves involve portfolio diversification into integrated services and strategic partnerships to address complex hybrid cloud environments.
Among technology giants, Microsoft Corporation exemplifies a cloud-first strategy, leveraging its vast cloud footprint to deliver integrated storage services. Dell Technologies Inc. occupies a position as a comprehensive enterprise hardware provider, offering a full spectrum of solutions from high-end arrays to hyper-converged infrastructure. Pure Storage, Inc. represents a specialized archetype, focusing on all-flash arrays and differentiating through its unified storage platform.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| IBM Corporation |
| NetApp, Inc. |
| Dell Technologies Inc. |
| Seagate Technology Holdings Public Limited Company |
| Western Digital Corporation |
| Pure Storage, Inc. |
| Hewlett Packard Enterprise Company |
| Others |
Cost & Logistics Intelligence
Data center capacity utilization, particularly in hubs like Northern Virginia, directly influences supplier behavior and pricing posture. High utilization rates incentivize infrastructure expansion and premium service offerings from cloud providers, while undercapacity can drive up spot market prices for compute and storage resources.
Pricing Analysis
Enterprise buyers anchor the market's pricing structure, increasingly favoring consumption-based acquisition models for on-premises storage. Price differentiation stems from performance tier, such as flash versus hard disk drives, and the level of data residency compliance offered. Pricing pressure stems from the commoditization of basic storage hardware, yet premium solutions command higher prices for advanced data governance features. Financial institutions and healthcare providers exhibit the lowest price sensitivity due to stringent regulatory demands, while smaller enterprises are more price-sensitive.
Supply Chain Analysis
Export-control regimes impacting advanced semiconductor technology limit the free flow of critical components, affecting the data storage supply chain. Geographic supply concentration for NAND flash and DRAM centers heavily in East Asia, specifically South Korea and Taiwan. The industry relies on specialized controllers and high-purity silicon as key component dependencies. Geopolitical risks and single-source vulnerabilities in semiconductor fabrication represent a significant structural risk. Distribution channels for enterprise storage run through direct sales to hyperscalers and large corporations, supplemented by channel partners for mid-market and smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data storage market presents a significant service-attach opportunity, with Storage-as-a-Service (STaaS) and integrated data management solutions expanding faster than raw hardware sales.
For Market Incumbents:Pre-empt disruption from cloud-native providers by aggressively diversifying into integrated hybrid cloud services and multi-cloud orchestration platforms. Invest heavily in R&D for AI-driven data management and intelligent tiering to enhance existing portfolio capabilities. Control of the channel through strong partner programs remains a crucial lever against emerging specialized vendors. Focus on securing long-term contracts with enterprises facing complex data sovereignty requirements.
For New Entrants and Emerging Players:Build out specialized solutions for underserved niches, such as edge computing infrastructure for IoT applications or compliant data sovereignty-as-a-service offerings. The mid-market segment with complex compliance needs and limited in-house IT expertise represents a penetrable target. Partner with regional system integrators to establish a strong go-to-market presence and provide localized support. Focus on delivering differentiated value through software-defined architectures.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting in an upward direction across the high-performance storage sub-segment, driven by NVMe and all-flash array adoption. The long-term viability of data storage remains robust, as digital transformation continues across all industries. Target acquisition archetypes include specialized software-defined storage providers and data governance platforms with strong intellectual property. Adoption rates of NVMe-oF in specific vertical markets serve as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Data Sovereignty-as-a-Service | Addresses strict regulatory mandates, enabling multi-jurisdictional compliance for global enterprises. |
| Expand Edge Storage Solutions | Captures new demand from IoT and autonomous systems requiring low-latency data processing. |
| Invest in NVMe-oF Integration | Narrows the performance gap between direct-attached and networked storage, boosting application speed. |
| Acquire Multi-Cloud Orchestration Platforms | Simplifies complex data management across disparate cloud environments for enterprise customers. |
| Offer Consumption-Based Storage Models | Aligns infrastructure costs with business demand, appealing to enterprises seeking operational flexibility. |
Research Approach
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, data center architects, and compliance officers, and refined through iterative feedback. This approach combined in-depth primary interviews with rigorous secondary validation from SEC filings, industry association reports, technology journals, and government regulatory documents. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and coherence.
The analytical framework established a demand-supply balance across the analysis window, modeling market dynamics through a comprehensive segmentation. Segmentation dimensions included product type, technology, end user, application, and regional compliance mandates. Compound Annual Growth Rates were derived from historical data trends and projected market drivers, with industry-specific inputs like data generation rates and regulatory changes informing the forecast.
Practitioners should monitor geopolitical instability impacting semiconductor supply and the emergence of new data localization laws for early signals of market shifts. Forecasts reflect assumptions regarding technological advancements and economic stability over the projection horizon. Material shifts in AI adoption rates or critical component availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Flash Memory Market
Data Storage
Tape Storage Market
Data Storage
Hardware Storage Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Americas Flash Memory Market
Data Storage
Multiprotocol Storage Market
Data Storage
South Korea Data Center Storage Market
Data Storage
NAND Flash Memory Market
Data Storage
APAC Next Generation Storage Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
AI Powered Storage Market
Data Storage
Storage Virtualization Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Serial EEPROM Market
Data Storage
Zoned Flash Market