
 Ceph Storage Solutions Market | 2026-2036
Ceph Storage Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Ceph Storage Solutions Market Analysis
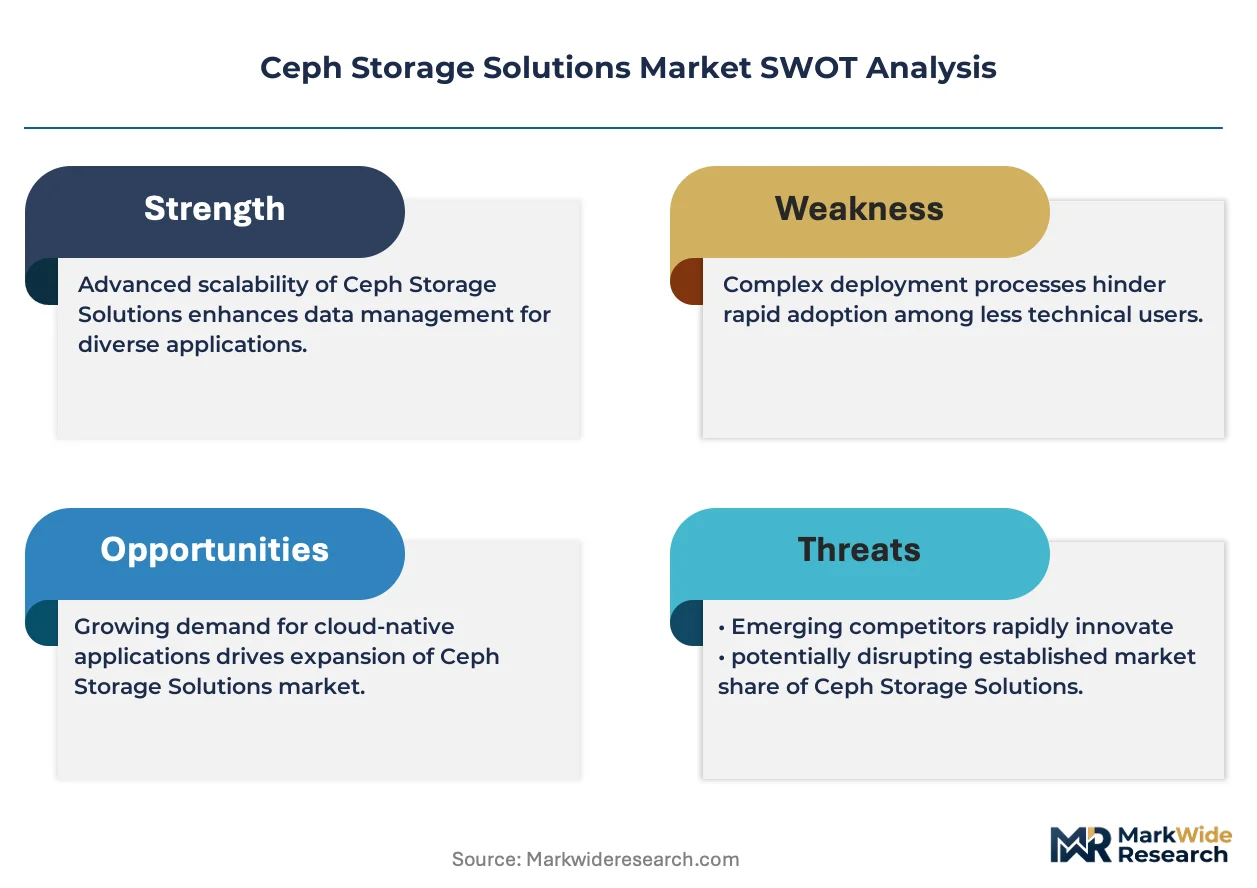
Petabyte-scale object durability is redrawing procurement criteria for enterprise storage buyers. Red Hat sustains technology leadership through upstream RHEL integration and managed OpenShift data services. IBM leverages its hybrid cloud platform to anchor Ceph deployments across financial services and government verticals. Dell competes with tightly bundled PowerEdge and storage networking packages that reduce deployment complexity for large enterprises.
Ceph storage solutions constitute open-source, software-defined object, block, and file storage built on a distributed architecture with automatic replication, self-healing, and CRUSH algorithm-based data placement across commodity hardware nodes. The system eliminates single points of failure through RADOS, tolerates disk, node, or rack-level outages without service interruption, and serves primary use cases in cloud-native application backends, media archives, and scientific data repositories. On-premises deployment retains the largest installed base as regulated industries reject public cloud egress costs and latency variability, though hybrid cloud configurations capture the fastest expansion as edge-to-core pipelines mature. Managed services extract superior margins versus technical support engagements because subscription models embed continuous platform engineering and security patching.
FDA 21 CFR Part 11, HIPAA Security Rule, and GDPR Article 32 shape demand by mandating audit trails, encryption-at-rest, and geographic data residency that Ceph's policy-driven placement groups satisfy. ISO 27001 certification and SOC 2 Type II attestation increasingly gate procurement for healthcare and financial services buyers evaluating vendor shortlists. Stakeholders must weigh upstream community release velocity against vendor-supported long-term stable branches when committing to decade-long capacity planning horizons.
Market Dynamics
Enterprise data retention mandates under GDPR Article 32 and HIPAA Security Rule are forcing storage architects toward software-defined architectures that guarantee geographic data residency without vendor lock-in. Sovereign cloud procurement in defense and financial services verticals is accelerating petabyte-scale cluster deployments.
Growth Catalysts
- GDPR Article 32:European data localization requirements mandate encryption-at-rest and audit trails that Ceph's policy-driven placement groups satisfy natively, pulling financial services and healthcare buyers toward self-hosted object storage.
- Petabyte-scale scientific repositories:Genomics and climate modeling workloads generate exabyte-class datasets that exceed commercial cloud egress economics, driving research institutions toward RADOS-based distributed architectures.
- Edge-to-core pipelines:Industrial IoT sensor networks in German manufacturing and Chinese smart cities require low-latency local storage with centralized aggregation, favoring hybrid Ceph configurations over pure cloud alternatives.
Market Restraints
- Specialized talent scarcity:CRUSH map optimization and RADOS troubleshooting demand distributed systems expertise that commands premium compensation in Frankfurt, Beijing, and Silicon Valley labor markets.
- Memory and NVMe input volatility:Ceph's performance tier depends on flash storage pricing that fluctuates with NAND fab utilization in South Korea and Taiwan, compressing margin predictability for cluster operators.
- Hardware certification friction:FDA 21 CFR Part 11 and ISO 27001 attestation timelines extend sales cycles by months for healthcare and financial services deployments.
Strategic Opportunities
- Indian sovereign cloud expansion:RBI data localization directives and the PLI scheme for data centers create procurement windows for Ceph-based private cloud infrastructure in Mumbai and Bangalore.
- AI training data lakes:Convergence of object storage with GPU-direct networking protocols enables petabyte-scale model training datasets without cloud egress penalties.
- Managed service channel maturation:Subscription-based platform engineering and automated security patching extract superior margins versus traditional technical support engagements.
Industry Challenges
- Integration complexity with legacy SAN/NAS:Enterprise storage teams face skill gaps in migrating block workloads from proprietary arrays to Ceph RBD without application downtime.
- Upstream versus stable branch selection:Capacity planners must weigh community release velocity against decade-long hardware refresh cycles when committing to vendor support models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceph Storage Solutions Market |
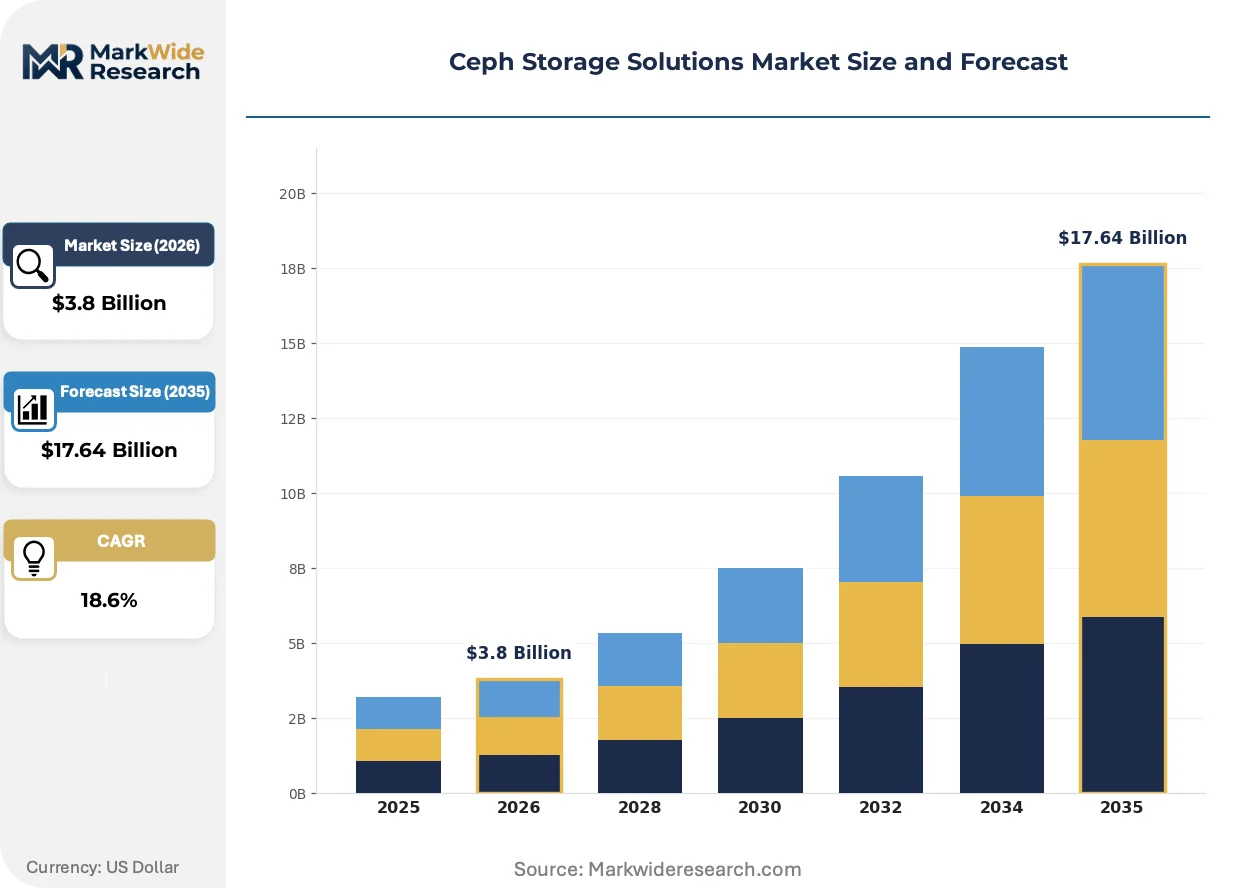
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud End User: SMBs, Enterprises, Government, Education Service Type: Managed Services, Professional Services, Technical Support, Consulting Solution: Backup, Disaster Recovery, Archiving, Data Management |
| Companies Covered | Dell, ZTE Corporation, Red Hat, NetApp, Fujitsu, IBM, SUSE, 45Drives, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceph Storage Solutions Market Emerging Trajectories
Storage architecture is decoupling from proprietary hardware assumptions as software-defined systems absorb functions previously locked in controller firmware. This shift is compressing traditional array margins while expanding design flexibility for cloud-native workloads.
Erasure-coded cold storage tiers are fragmenting the economics of long-term retention. These configurations reduce replication overhead from three copies to fractional redundancy ratios. Media archives and scientific repositories in Germany and the United States are adopting 8+3 and 10+4 encoding schemes. The resulting cost structure is fragmenting demand away from tape libraries and commercial cloud archive tiers toward self-managed object pools.
EU AI Act risk classification rules are reshaping training data governance. High-risk AI system providers must demonstrate data lineage and immutability. Healthcare AI developers in France and the Netherlands are deploying Ceph clusters with WORM-enabled buckets and cryptographic provenance logging. This regulatory pressure is accelerating certified infrastructure procurement ahead of enforcement deadlines.
Buyer concentration among hyperscale-adjacent enterprises is compressing vendor negotiation cycles. Fortune 500 storage procurement teams now benchmark Ceph total cost of ownership against native cloud storage APIs directly. Financial services buyers in New York and London are unbundling professional services from hardware procurement, favoring direct engagement with systems integrators over traditional channel resale. This disintermediation is most visible in capital markets data lake deployments.
Ceph Storage Solutions Market Segmentation
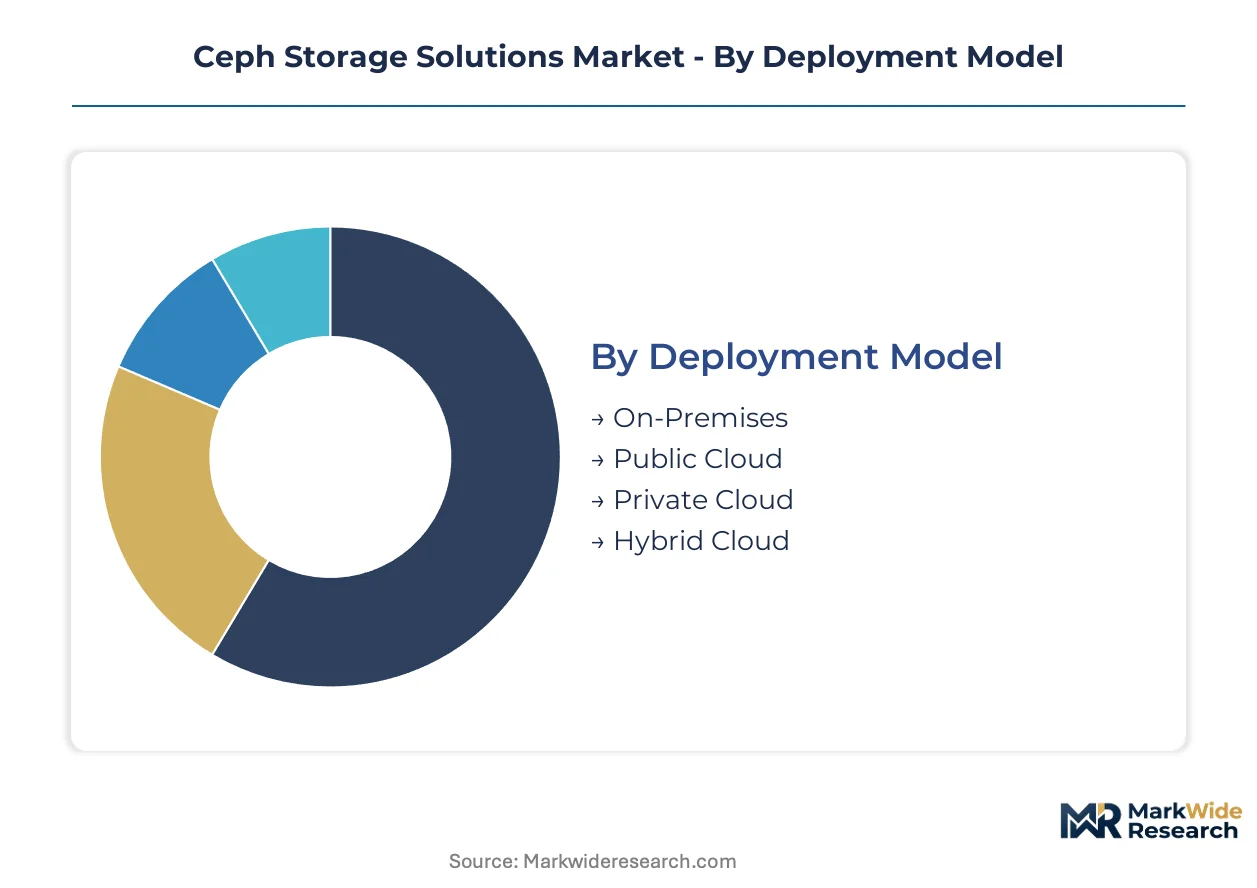
Ceph's modular architecture fragments procurement patterns across deployment topologies, buyer sophistication levels, and service engagement models. Understanding these fault lines exposes where margin pools concentrate and which configuration paths encounter compliance friction.
Deployment Model:
Domestic infrastructure retains the largest footprint across regulated European and North American buyers, while hybrid configurations increasingly serve cross-border data pipelines.
- On-Premises:Fully self-hosted clusters on certified hardware satisfy GDPR Article 32 residency mandates and HIPAA Security Rule audit requirements. Financial services buyers in Frankfurt and healthcare systems in Boston dominate procurement, rejecting cloud egress economics for petabyte-scale retention.
- Hybrid Cloud:Edge-to-core architectures aggregate industrial IoT streams locally before centralizing analytics. German manufacturing networks and Chinese smart city deployments favor this model for latency-sensitive preprocessing with cloud burst capacity.
- Private Cloud:Sovereign cloud configurations serve defense archiving and government intelligence use cases in the United States and Germany.
- Public Cloud:Managed Ceph instances on hyperscaler infrastructure attract cloud-native startups prioritizing OpEx flexibility over capital deployment.
On-Premises commands the established base. The steepest expansion runs through Hybrid Cloud.
End User:
Buyer scale determines support model preferences and hardware certification intensity, with government and enterprise segments driving compliance-heavy procurement.
- Enterprises:Fortune 500 storage teams unbundle professional services from hardware procurement, engaging systems integrators directly for capital markets data lake deployments in New York and London. These buyers benchmark total cost of ownership against native cloud storage APIs.
- Government:Defense and intelligence agencies in the United States, Germany, and China mandate sovereign infrastructure with ISO 27001 certification and SOC 2 Type II attestation gating vendor shortlists.
- SMBs:Mid-market buyers in India and Southeast Asia adopt managed service wrappers to bypass internal distributed systems expertise gaps.
- Education:Research institutions in the United States and Germany deploy petabyte-scale clusters for genomics and climate modeling workloads exceeding commercial cloud egress economics.
Enterprises anchor current revenue concentration. Government buyers are expanding most quickly as sovereign cloud mandates harden.
Service Type:
Engagement depth separates subscription-based platform engineering from transactional support, with margin structure favoring continuous service relationships.
- Managed Services:Subscription models embed automated security patching, CRUSH map optimization, and continuous platform engineering. These contracts extract superior margins versus break-fix arrangements by capturing decade-long capacity planning relationships.
- Professional Services:Migration consulting and cluster architecture design command premium day rates in Frankfurt, Beijing, and Silicon Valley where RADOS troubleshooting expertise concentrates.
- Technical Support:Per-incident or tiered support contracts serve cost-conscious buyers with internal Ceph expertise.
- Consulting:Advisory engagements on upstream versus stable branch selection guide hardware refresh cycles for capacity planners.
Managed Services captures the margin premium. Professional Services is climbing the fastest as migration complexity drives external expertise demand.
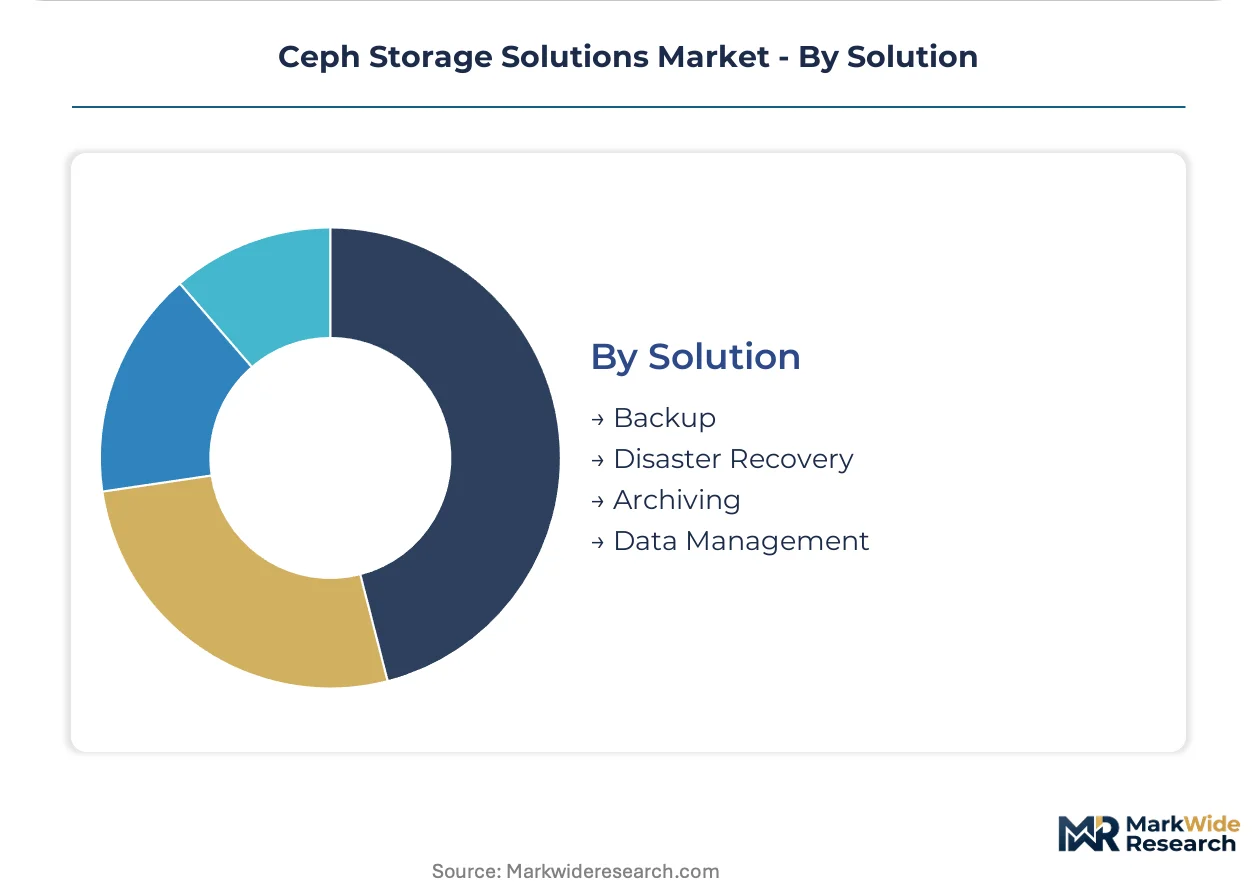
Solution:
Functional use case determines erasure coding ratios, durability requirements, and regulatory attachment points across buyer verticals.
- Archiving:Erasure-coded cold storage tiers with 8+3 and 10+4 encoding schemes displace tape libraries and commercial cloud archive tiers. Media repositories in Germany and scientific datasets in the United States adopt these configurations for fractional redundancy economics.
- Data Management:Policy-driven placement groups enable geographic data residency without vendor lock-in, satisfying GDPR Article 32 and HIPAA Security Rule mandates for financial services and healthcare buyers.
- Backup:RADOS-based distributed architectures replace proprietary backup appliances for enterprises rejecting single points of failure.
- Disaster Recovery:Cross-cluster replication tolerates disk, node, or rack-level outages without service interruption for regulated industries.
Archiving holds the installed base. Data Management is gaining share fastest as EU AI Act risk classification rules reshape training data governance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net storage technology flows tilt toward import-dependent economies building sovereign data infrastructure, while export capacity concentrates in established hardware manufacturing bases. Trade friction in NAND flash and server components is reshaping procurement geography.
United States
Defense and intelligence agencies drive classified archive deployments with ISO 27001 certification requirements. FDA 21 CFR Part 11 mandates shape healthcare storage procurement in Boston and Research Triangle Park clusters. Financial services buyers in New York unbundle professional services from hardware, engaging systems integrators directly for capital markets data lakes.
Germany
Industrial IoT sensor networks in Bavarian manufacturing corridors require low-latency edge storage with centralized aggregation. GDPR Article 32 residency mandates pull Frankfurt financial services toward self-hosted object pools. Baden-Württemberg automotive suppliers deploy hybrid configurations for quality control data retention.
China
Smart city deployments in Shenzhen and Hangzhou generate exabyte-class surveillance and telemetry datasets exceeding commercial cloud economics. MIIT data localization directives accelerate domestic Ceph ecosystem development. Yangtze River Delta research institutions build petabyte-scale clusters for climate modeling workloads.
India
RBI data localization directives and PLI scheme incentives create procurement windows in Mumbai and Bangalore data center corridors. Mid-market buyers adopt managed service wrappers to bypass distributed systems expertise gaps. Karnataka's technology services sector drives hybrid cloud demand for client data residency.
Ceph Storage Solutions Market Vendor Landscape
Listed leaders compete with private specialists across support model differentiation, creating a tiered structure where subscription-based platform engineering extracts superior margins. The vendor base clusters around three strategic archetypes: upstream open-source distributors, systems integrators bundling certified hardware, and managed service operators capturing decade-long capacity relationships. Dominant competitive moves include strategic partnerships with NAND flash suppliers and geographic expansion into sovereign cloud procurement corridors.
Within the enterprise infrastructure tier, Dell and Hewlett Packard Enterprise represent bundled hardware-software offerings that reduce deployment complexity for Fortune 500 storage teams. IBM occupies a position bridging hybrid cloud platforms with regulated vertical expertise. Red Hat exemplifies the upstream distribution archetype through RHEL integration and managed OpenShift data services. ZTE Corporation anchors Chinese domestic supply for smart city and telecommunications deployments.
| Leading Market Players |
|---|
| Dell |
| ZTE Corporation |
| Red Hat |
| NetApp |
| Fujitsu |
| IBM |
| SUSE |
| 45Drives |
| Hewlett Packard Enterprise |
| Others |
Supply Flow & Price Mechanics
ISO 27001 certification and SOC 2 Type II attestation simultaneously gate supplier qualification and stratify contract values across healthcare and financial services procurement, compressing margin pools for uncertified vendors while embedding premium pricing for audit-ready infrastructure. This dual-gating mechanism concentrates buyer power among Fortune 500 storage teams and defense agencies that unbundle services from hardware, forcing tiered commercial structures that reflect compliance depth rather than raw capacity metrics.
Pricing Analysis
Industrial OEM buyers anchor subscription-based managed services as the dominant pricing structure, with three-tier pricing stratification across premium certified, standard supported, and economy self-managed levels. Price differentiation centers on ISO 27001 attestation depth and geographic data residency guarantees, with Frankfurt and New York financial services buyers showing lowest price sensitivity while Indian mid-market adopters drive cost compression through managed service wrappers. Pricing pressure intensifies in the NVMe performance tier as NAND flash pricing fluctuates with South Korean and Taiwanese fab utilization, squeezing margin predictability for cluster operators dependent on flash-accelerated RADOS deployments.
Supply Chain Analysis
Inventory lead times for certified server hardware extend procurement cycles by months as FDA 21 CFR Part 11 and ISO 27001 attestation timelines layer onto manufacturing schedules. Supply concentrates in China, Taiwan, and South Korea for NAND flash components and commodity server chassis, with Germany and the United States anchoring specialized networking equipment for low-latency Ceph deployments. Raw material dependencies center on NAND flash wafers, DDR4/DDR5 memory modules, and RoHS-compliant power supplies, exposing operators to single-source vulnerability in advanced node semiconductor fabrication. Distribution runs through systems integrators in Frankfurt, Beijing, and Silicon Valley who bundle certified hardware with professional services for regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceph storage economics are approaching a platform inflection where Kubernetes-native data services and GPU-direct networking protocols reshape procurement criteria, with OpenShift and S3-compatible API interoperability becoming the decisive ecosystem leverage point for vendor positioning.
For Market Incumbents: Secure long-term NAND flash supply agreements with South Korean and Taiwanese suppliers to dampen input cost volatility in performance-tier deployments. Defend subscription margin pools by embedding automated CRUSH map optimization and security patching into managed service contracts, countering emerging cloud-native entrants who threaten to commoditize the orchestration layer through upstream community distributions.
For New Entrants and Emerging Players: SOC 2 Type II fast-track certification opens procurement doors in healthcare and financial services verticals where attestation timelines currently extend sales cycles. White-space concentrates in Indian sovereign cloud corridors under RBI data localization directives and in AI training data lakes where GPU-direct RDMA protocols enable petabyte-scale model datasets without cloud egress economics. Go-to-market should lead with managed service wrappers that bypass internal distributed systems expertise gaps among mid-market buyers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed systems integrators in Frankfurt and Singapore who have accumulated decade-long capacity planning relationships with defense and financial services buyers. Long-term viability hinges on subscription model conversion rates and embedded platform engineering attach rates rather than transactional hardware margins. Monitor Ceph upstream versus stable branch commitment patterns among Fortune 500 storage teams as an inflection signal for vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OpenShift data services embedding Ceph RBD and object storage accelerates Red Hat's hybrid cloud lock-in among RHEL-dependent enterprises. |
| Strategic Partnership | NAND flash supplier alliances with Samsung or SK Hynix dampen margin volatility for performance-tier cluster operators in Frankfurt and New York. |
| Acquisition of Specialist Firm | CRUSH map optimization boutiques in Silicon Valley and Beijing concentrate scarce distributed systems expertise for healthcare AI deployments. |
| Geographic Expansion | Mumbai and Bangalore data center corridors under RBI localization directives create procurement windows for sovereign cloud infrastructure. |
| Product Launch | WORM-enabled buckets with cryptographic provenance logging address EU AI Act risk classification rules for high-risk training data governance. |
Methodological Framework
A standing panel of storage architects, Ceph platform engineers, healthcare IT procurement directors, and financial services infrastructure leads provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and hospital procurement databases. Bottom-up cluster deployment counts triangulated against top-down enterprise storage spend estimates to anchor market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment topology, buyer sophistication tier, service engagement depth, and functional use case as core segmentation dimensions. CAGRs derived from capacity planning relationships and hardware refresh cycle patterns, with inputs including NAND flash pricing indices, certified server shipment data, and regulatory attestation timeline surveys.
Decision-makers should treat outputs as directional under assumptions of sustained GDPR Article 32 enforcement and stable NAND fab utilization; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Storage Area Network Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
All Flash Storage Market
Data Storage
Zoned Flash Market
Data Storage
Distributed Storage System Market
Data Storage
Data Center Storage Solutions Market
Data Storage
Enterprise Flash Storage Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
Data Storage Devices Market
Data Storage
South Korea Data Center Storage Market
Data Storage
Channel Storage Systems Market
Data Storage
Hardware Storage Market
Data Storage
Powered Storage Devices Market
Data Storage
Blu-Ray Optical Disk Market