
 Storage Virtualization Market | 2026-2036
Storage Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Storage Virtualization Market Analytics
Modular appliance bundling is broadening buyer choice in the storage virtualization landscape. VMware leverages its hypervisor dominance to anchor integrated compute-storage offerings across enterprise accounts. IBM sustains mainframe-era credibility in high-availability block storage virtualization for regulated workloads. Nutanix competes through hyper-converged infrastructure packaging that collapses separate storage, compute, and networking procurement decisions into single-vendor contracts.
Storage virtualization abstracts physical storage resources into logical pools managed independently of underlying hardware, typically employing block-level, file-level, or object-level abstraction protocols with automated tiering and thin provisioning capabilities. Its primary commercial purpose is to decouple capacity planning from hardware refresh cycles while enabling non-disruptive data migration and centralized policy enforcement across heterogeneous storage arrays. Hybrid cloud deployment models command the largest addressable base as enterprises retain sensitive workloads on-premise while bursting analytics to public infrastructure. Object storage technology represents the fastest-expanding architecture as unstructured data volumes from AI training pipelines and media repositories overwhelm traditional file systems. On-premise solutions retain margin concentration in sectors with strict data residency mandates.
FCC guidelines on communications infrastructure resilience and HIPAA data protection requirements shape healthcare provider storage architecture decisions in the United States. The EU AI Act and GDPR cross-border data transfer rules are forcing multinational enterprises to deploy geographically partitioned virtualized storage pools with automated compliance tagging. Stakeholders must monitor how NIST cybersecurity framework updates and emerging SEC climate disclosure rules alter capital allocation between cloud-native and traditional on-premise storage virtualization platforms.
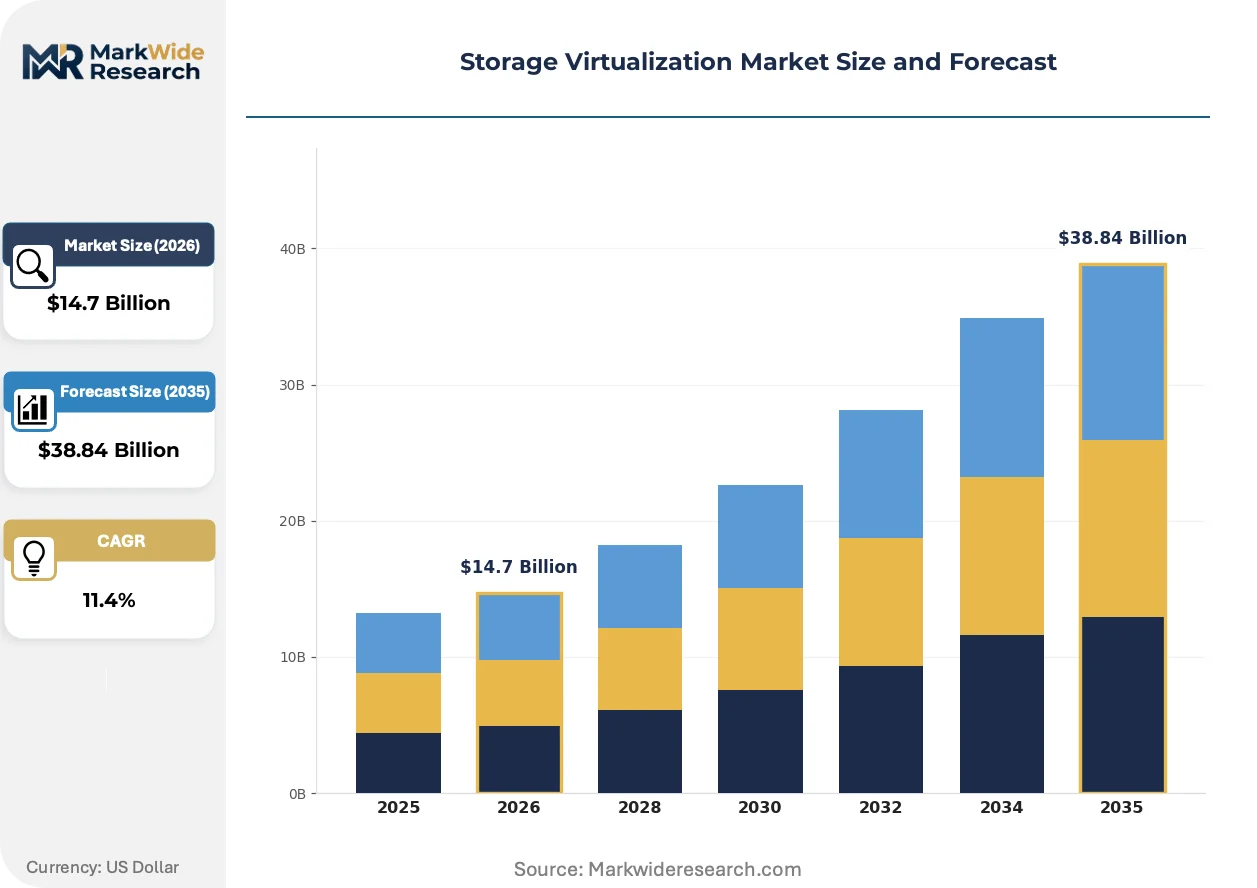
Market Dynamics
Hybrid cloud data gravity is compressing storage procurement cycles as enterprises simultaneously repatriate sensitive workloads and burst analytics to public infrastructure, forcing vendors to engineer seamless data mobility across jurisdictional boundaries.
Growth Catalysts
- HIPAA data protection mandates:United States healthcare providers are virtualizing storage to automate compliance tagging and audit trails across distributed patient record repositories.
- AI training pipeline expansion:Unstructured data volumes from machine learning workloads are overwhelming traditional file systems, pulling object storage virtualization into enterprise core infrastructure.
- Hyperscale data center construction:Concentrated facility investment in Northern Virginia and Dallas-Fort Worth is driving demand for software-defined storage pooling across heterogeneous hardware generations.
Market Restraints
- Flash memory supply concentration:NAND fabrication capacity in South Korea and Taiwan creates input cost volatility that compresses margins for appliance vendors.
- EU AI Act cross-border friction:Automated decision-making data residency rules are forcing redundant storage pool deployment across member states, inflating effective capacity costs.
- Technical debt in block protocols:Legacy Fibre Channel investments in financial services delay NVMe-oF adoption, stretching refresh timelines.
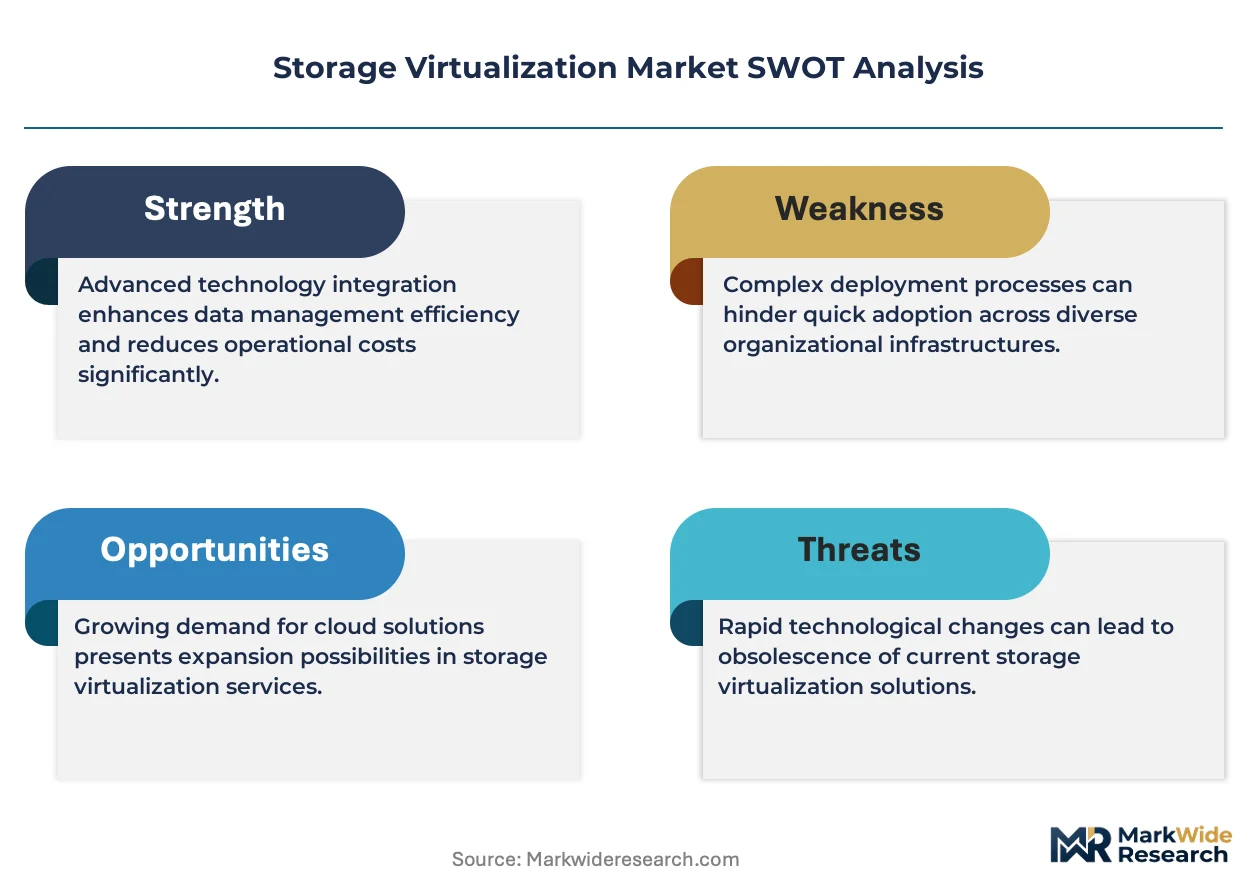
Strategic Opportunities
- Edge computing storage nodes:Manufacturing facilities in Germany and Japan require localized virtualization to process industrial IoT streams without cloud egress penalties.
- Greenfield sovereign cloud deployments:Saudi Arabia and UAE national cloud initiatives mandate domestic data centers with compliant storage abstraction layers.
- Container-native storage convergence:Kubernetes persistent volume orchestration is merging with virtualization control planes, collapsing separate infrastructure procurement decisions.
Industry Challenges
- Storage administrator skill scarcity:Expertise in software-defined architectures and multi-cloud orchestration outpaces workforce development pipelines.
- Retrofit complexity with mainframe environments:IBM z/OS storage subsystem integration demands specialized consulting engagement, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage Virtualization Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Solution Type: Backup Solutions, Disaster Recovery, Data Migration, Storage Management End User: Healthcare Providers, Financial Institutions, Educational Institutions, IT Services Technology: Block Storage, File Storage, Object Storage, Hyper-Converged Infrastructure |
| Companies Covered | Microsoft, Infinidat, VMware (Broadcom), Cloudian, Scality, Nutanix, Cohesity, Qumulo, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage Virtualization Market Evolving Landscape
Computational storage integration and policy-driven data placement automation are compressing the boundary between virtualization software and hardware acceleration, reshaping how vendors architect control plane efficiency.
Computational storage drives with embedded processing capabilities are unifying data reduction, encryption, and analytics functions at the device level. Hyperscale operators in the United States are deploying these units to minimize host CPU overhead during intensive AI training cycles. This convergence is unifying previously separate hardware refresh decisions into single procurement events centered on data processing density rather than raw capacity metrics.
EU AI Act algorithmic audit requirements are mandating immutable data lineage and automated compliance tagging within virtualized storage pools. Pharmaceutical and financial services firms operating across Frankfurt, Paris, and Amsterdam must now engineer geographically partitioned architectures with real-time policy enforcement. German automotive manufacturers are responding by embedding storage virtualization controls directly into manufacturing execution systems to satisfy product liability traceability mandates.
Enterprise buyers are consolidating vendor relationships through single-source hyper-converged contracts that collapse separate storage, compute, and networking procurement processes. Mid-market manufacturing firms in the United States Midwest are abandoning best-of-breed component strategies in favor of unified support models with predictable lifecycle costs. This concentration is most visible in healthcare provider networks where IT staff limitations drive preference for fully integrated appliance stacks over customizable software-defined alternatives.
Storage Virtualization Market Segmentation
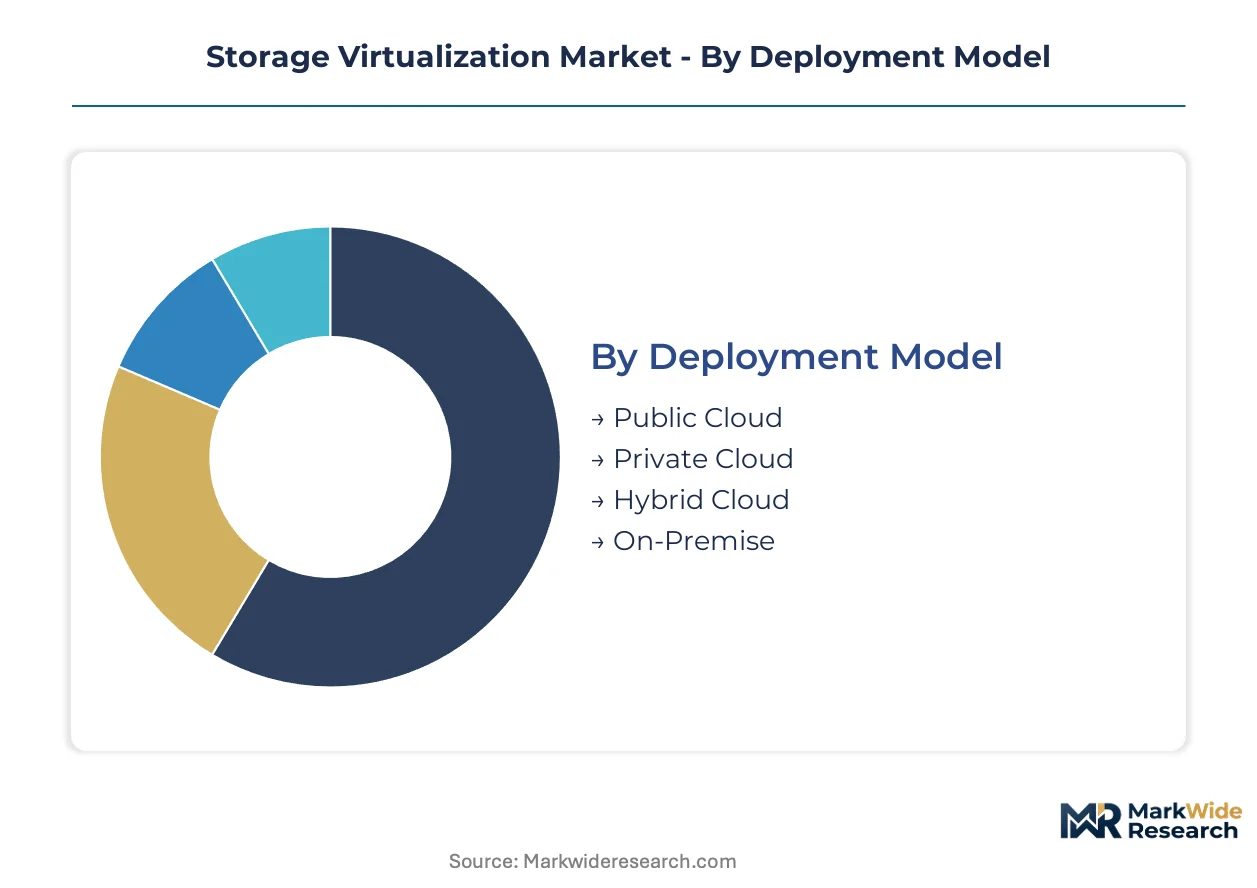
Storage virtualization procurement patterns diverge sharply across deployment models, solution architectures, and compliance-sensitive end users. Understanding these fault lines illuminates where vendors must engineer differentiated control planes versus standardized commodity offerings.
Deployment Model:
Capital intensity varies dramatically across deployment architectures, with on-premise and hybrid configurations demanding the heaviest upfront infrastructure investment while cloud models shift expenditure toward recurring operational commitments.
- Public Cloud:Third-party managed abstraction layers eliminate physical hardware procurement entirely. Financial services firms in Singapore and Australia leverage this model for development environments while retaining sensitive transaction data in sovereign-controlled facilities.
- Private Cloud:Dedicated virtualized infrastructure hosted in enterprise-owned or colocation facilities. German automotive manufacturers deploy these architectures to satisfy product liability traceability mandates while maintaining sub-millisecond latency for industrial control systems.
- Hybrid Cloud:Unified management planes spanning on-premise capacity and burst-ready public infrastructure. United States healthcare providers favor this model to automate HIPAA compliance tagging across distributed patient record repositories while scaling analytics workloads to AWS or Azure.
- On-Premise:Fully captive storage virtualization stacks within enterprise data centers. Saudi Arabian government entities mandate this architecture under national cloud initiatives requiring domestic data residency with no cross-border replication paths.
Hybrid cloud absorbs the bulk of installed capacity; object-optimized public cloud deployments are expanding most quickly for AI training workloads.
Solution Type:
Margin structures align with operational criticality, where disaster recovery and storage management solutions command premium pricing due to their role in revenue protection and workforce productivity.
- Backup Solutions:Automated snapshot orchestration and deduplication across heterogeneous storage arrays. Japanese manufacturing conglomerates integrate these capabilities with manufacturing execution systems to preserve industrial IoT telemetry streams.
- Disaster Recovery:Synchronous and asynchronous replication with automated failover orchestration. Financial institutions in the United States deploy these solutions to satisfy SEC business continuity mandates with sub-minute recovery point objectives.
- Data Migration:Non-disruptive workload portability across storage generations and geographic locations. European pharmaceutical firms leverage these tools to execute GDPR-compliant cross-border transfers with automated residency validation.
- Storage Management:Policy-driven tiering, thin provisioning, and capacity forecasting across pooled resources. Mid-market IT services providers in India standardize on these platforms to deliver multi-tenant infrastructure with predictable per-gigabyte economics.
Storage management solutions dominate recurring revenue streams; disaster recovery offerings show the steepest expansion trajectory as regulatory pressure intensifies.
End User:
Procurement sophistication separates regulated industries with dedicated compliance officers from sectors where storage decisions remain subordinate to broader IT infrastructure refresh cycles.
- Healthcare Providers:Virtualized infrastructure for electronic health records, medical imaging archives, and genomic data repositories. United States hospital networks prioritize automated audit trails to satisfy HIPAA security rule requirements.
- Financial Institutions:High-availability block storage for trading platforms, risk analytics, and regulatory reporting. Frankfurt-based investment banks engineer geographically partitioned pools to satisfy ECB data localization expectations.
- Educational Institutions:Cost-optimized capacity for research datasets, learning management systems, and administrative records. Australian universities consolidate vendor relationships through unified hyper-converged contracts with predictable lifecycle costs.
- IT Services:Multi-tenant platforms delivering storage-as-a-service to downstream enterprise clients. Indian outsourcing majors deploy container-native virtualization to collapse separate infrastructure procurement decisions for Kubernetes workloads.
Financial institutions absorb the bulk of high-margin block storage deployments; healthcare providers are gaining share fastest as HIPAA enforcement tightens.
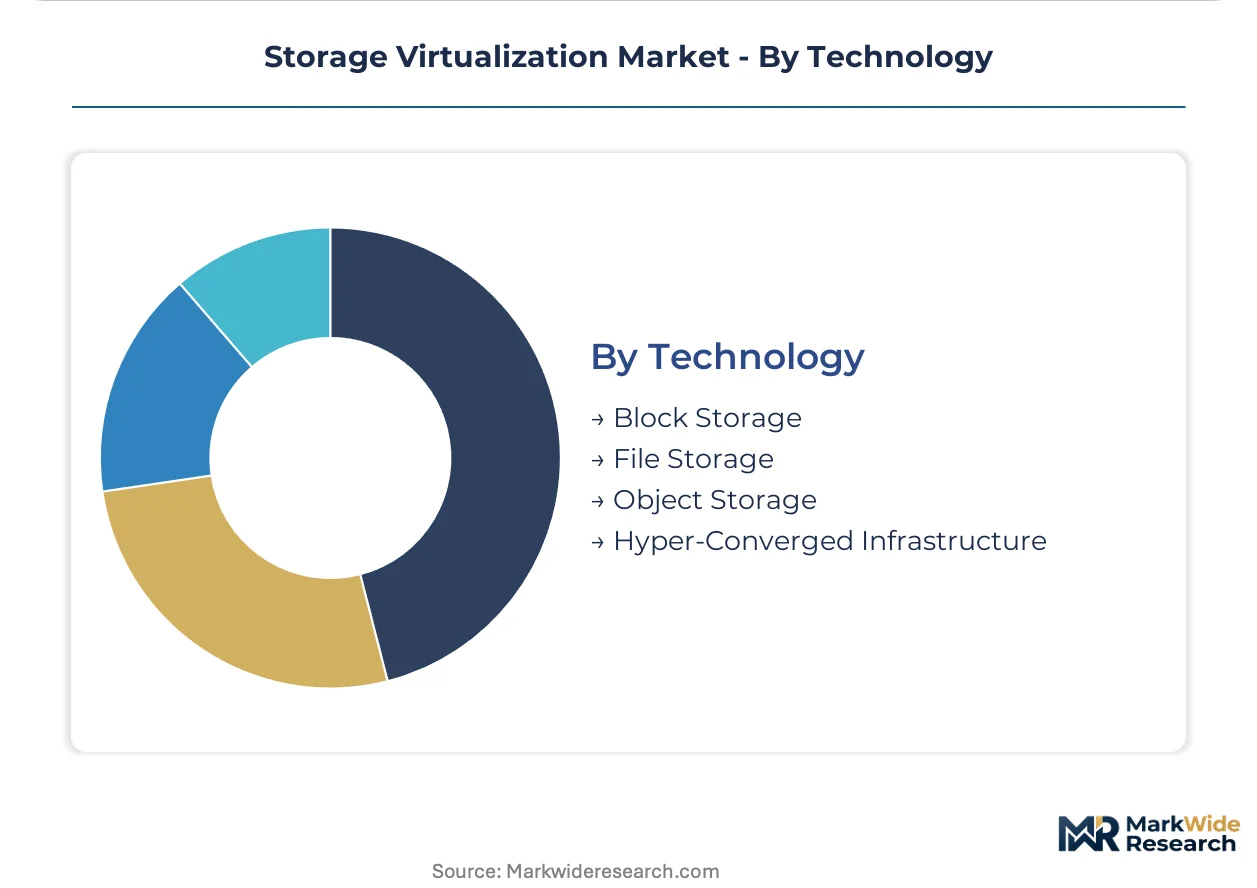
Technology:
Architectural maturity determines integration complexity, with block storage leveraging decades of Fibre Channel investment while object storage requires greenfield application refactoring.
- Block Storage:Raw volume abstraction with SCSI command mapping for databases and transactional workloads. Legacy investments in IBM z/OS subsystems extend refresh timelines at United States insurance carriers.
- File Storage:POSIX-compliant namespace services for user home directories and collaborative content repositories. European media production houses in Amsterdam and Copenhagen favor these architectures for editorial workflow integration.
- Object Storage:Flat namespace architecture with RESTful API access for unstructured data at petabyte scale. Hyperscale operators in Northern Virginia deploy these systems to absorb AI training pipeline volumes overwhelming traditional file systems.
- Hyper-Converged Infrastructure:Collapsed compute-storage-networking stacks with unified lifecycle management. Midwestern United States manufacturers abandon best-of-breed strategies for single-vendor support models addressing staff limitations.
Block storage retains the largest installed base; object storage climbs the fastest as machine learning workloads proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Storage virtualization infrastructure concentrates production capacity in United States hyperscale clusters while consumption spreads across regulated industries in Germany, Japan, and Saudi Arabia seeking data sovereignty compliance.
United States
Northern Virginia and Dallas-Fort Worth hyperscale construction drives software-defined storage pooling across heterogeneous hardware generations. FCC resilience guidelines and HIPAA security rules shape healthcare provider architecture decisions. Financial institutions in New York and Chicago deploy high-availability block virtualization for trading platforms and risk analytics.
Germany
Automotive manufacturers in Stuttgart and Munich embed storage virtualization controls into manufacturing execution systems for product liability traceability. EU AI Act algorithmic audit requirements mandate immutable data lineage across Frankfurt and Düsseldorf data centers. German industrial IoT streams require localized edge computing nodes to avoid cloud egress penalties.
Japan
Tokyo-based manufacturing conglomerates integrate automated snapshot orchestration with production systems to preserve industrial telemetry. METI industrial data governance frameworks pressure domestic virtualization deployment over foreign cloud alternatives. Osaka and Nagoya automotive suppliers engineer sub-millisecond latency architectures for robotic control systems.
Saudi Arabia
National cloud initiatives under Vision 2030 mandate fully captive on-premise stacks with no cross-border replication paths. Government entities in Riyadh and Jeddah require domestic data residency certification for all storage abstraction layers. Domestic hyperscale investments accelerate to absorb AI training workloads from regional financial services.
India
Bengaluru and Hyderabad IT services majors deploy container-native virtualization for multi-tenant Kubernetes persistent volume orchestration. RBI data localization expectations for financial transaction records drive private cloud storage pooling investments. Mid-market providers standardize on policy-driven tiering platforms with predictable per-gigabyte economics.
Storage Virtualization Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. VMware leverages hypervisor dominance to anchor integrated compute-storage offerings while IBM sustains mainframe-era credibility in regulated block storage workloads. Nutanix and Cohesity represent the hyper-converged collapse of separate procurement decisions into single-vendor contracts. Strategic moves concentrate on M&A for container-native capabilities and geographic expansion into sovereign cloud mandates.
Within the diversified technology tier, Microsoft and IBM occupy positions spanning enterprise software through infrastructure hardware. VMware (Broadcom) exemplifies the virtualization-centric specialist archetype with hypervisor-anchored control planes. Among storage-focused innovators, Infinidat, Cloudian, and Scality represent alternative architectural approaches to software-defined capacity pooling.
| Leading Market Players |
|---|
| Microsoft |
| Infinidat |
| VMware (Broadcom) |
| Cloudian |
| Scality |
| Nutanix |
| Cohesity |
| Qumulo |
| IBM |
| Others |
Value Network & Pricing Analysis
Storage administrator scarcity in Bengaluru and Hyderabad widens pricing-tier spreads between premium managed services and economy self-service tiers, compressing mid-market margins as labor-cost differentials outweigh hardware savings.
Pricing Analysis
Margin tightening in mid-market tiers reflects NAND flash supply concentration in South Korea and Taiwan. Three-tier pricing structure across premium, standard, and economy levels separates fully managed sovereign cloud deployments from self-optimized hyperscale configurations. Price differentiation hinges on compliance certification level and geographic data residency guarantees. Healthcare providers in the United States exhibit highest price sensitivity due to constrained IT budgets, while Saudi government entities absorb premium tiers under national cloud mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand in Northern Virginia and Dallas-Fort Worth, while value-added distributors serve mid-market manufacturing firms in Germany and Japan. NAND fabrication capacity concentrates in South Korea, Taiwan, and China, with controller silicon sourcing from United States and Israeli design houses. Supply chain risk centers on single-source vulnerability for advanced node flash memory. Distribution runs through certified systems integrators for regulated healthcare and financial workloads requiring HIPAA and SEC compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Storage virtualization is consolidating around vendors with sovereign cloud credentials as EU AI Act and HIPAA enforcement eliminate thinly capitalized competitors lacking compliance engineering depth.
For Market Incumbents: To counter container-native storage convergence threatening hypervisor-anchored control planes, VMware and IBM must deepen Kubernetes persistent volume integration while securing ECB data localization certifications for Frankfurt and Paris financial hubs. Capacity addition in Riyadh and Jeddah captures Saudi Vision 2030 national cloud spending. For New Entrants and Emerging Players: Launch via edge computing storage nodes targeting German automotive manufacturers in Stuttgart and Munich seeking localized industrial IoT processing without cloud egress penalties. White-space opportunity sits with mid-market United States Midwest manufacturers abandoning best-of-breed strategies for unified hyper-converged support models. For Investors and Strategic Acquirers: Re-rating potential sits with container-native storage specialists given Kubernetes orchestration merging with virtualization control planes. Long-term viability favors vendors with sovereign cloud deployments across Saudi Arabia, UAE, and India. Signal to watch is RBI data localization enforcement accelerating private cloud storage pooling investments among Bengaluru IT services majors.| Strategic Initiative | Industry Significance |
|---|---|
| Container-Native Storage Convergence | Kubernetes persistent volume orchestration collapses separate infrastructure procurement decisions for hyperscale operators. |
| Sovereign Cloud Certification | EU AI Act and Saudi Vision 2030 mandates require domestic data residency with automated compliance tagging. |
| Edge Computing Node Deployment | German automotive manufacturers embed virtualization controls into manufacturing execution systems for liability traceability. |
| Computational Storage Integration | Embedded processing capabilities at the device level minimize host CPU overhead during intensive AI training cycles. |
| Hyper-Converged Infrastructure Packaging | Mid-market United States healthcare providers consolidate vendor relationships through single-source contracts addressing IT staff limitations. |
Research Methodology
Document review covered hyperscaler capex disclosures, SEC 10-K infrastructure spending filings, and regulatory guidance from HIPAA, EU AI Act, and RBI, complemented by interviews with CTOs at financial institutions, IT procurement officers at German automotive manufacturers, platform engineers at Indian IT services majors, and channel partners serving United States healthcare networks. Secondary validation drew from hospital procurement databases, GPO contracts, and customs records for storage hardware imports. Bottom-up and top-down triangulation reconciled vendor shipment data with enterprise spending surveys.
Installed base and revenue outputs were derived through segmentation modeling across deployment models, solution architectures, technology types, and regional regulatory clusters. CAGRs were computed from annual growth rate interpolation across the projection horizon. Forecast inputs incorporated NAND flash supply forecasts, hyperscale data center construction pipelines, and compliance mandate implementation timelines.
Flash memory supply disruption, sovereign cloud policy reversals, and workforce scarcity in software-defined architectures are the dominant revision risks. Forecasts reflect documented assumptions regarding hyperscale investment continuity and regulatory enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Middle East and Africa Data Storage Market
Data Storage
Recordable Optical Disc Market
Data Storage
Global Digital Storage Devices Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Enterprise Flash Storage Market
Data Storage
NOR Flash Market
Data Storage
Powered Storage Devices Market
Data Storage
Flash Memory Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Global Portable Data Storage Market
Data Storage
Optical Disk Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Storage Area Network Market
Data Storage
OTG Pen Drive Market
Data Storage
Taiwan Data Center Storage Market